
Market Overview:
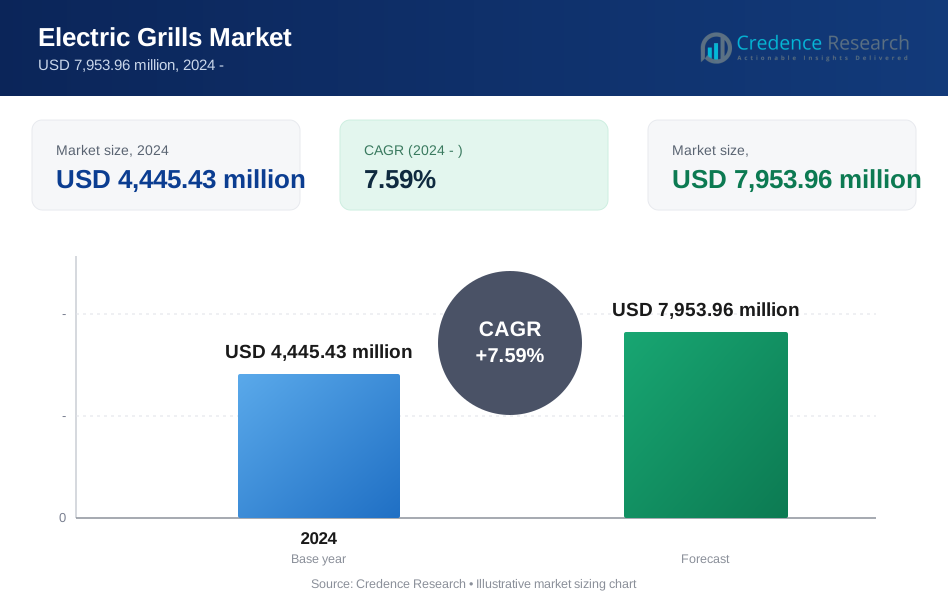
The Electric Grill market size was valued at USD 3,560.00 million in 2018 and reached USD 4,445.43 million in 2024. It is anticipated to reach USD 7,953.96 million by 2032, growing at a CAGR of 7.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Grill Market Size 2024 | USD 4,445.43 million |
| Electric Grill Market, CAGR | 7.59% |
| Electric Grill Market Size 2032 | USD 7,953.96 million |
The electric grill market is led by key players such as Weber, The Middleby Corporation, Char-Broil LLC, Taylor Commercial Foodservice, LLC, ROLLER GRILL, Zojirushi America Corporation, Holland Grill, FIRE MAGIC, Glen Dimplex Americas, and De’ Longhi Appliances. These companies compete through product innovation, smart features, and global distribution strategies. North America emerged as the leading region in 2024, capturing 34.1% of the global market share, driven by high consumer spending, a preference for indoor grilling, and early adoption of advanced cooking technologies. Asia Pacific follows closely, supported by rising urbanization and growing demand for convenient home appliances.
Market Insights
- The Electric Grill market was valued at USD 3,560.00 million in 2018, reached USD 4,445.43 million in 2024, and is expected to grow to USD 7,953.96 million by 2032 at a CAGR of 7.59% during the forecast period.
- Market growth is driven by rising demand for convenient, smoke-free indoor cooking appliances, increasing health-consciousness, and urban lifestyle changes that limit the use of traditional grills.
- A key trend includes the surge in smart, energy-efficient electric grills with digital features and app connectivity; portable and compact models are also gaining popularity among urban consumers.
- The market is moderately competitive with players like Weber, Char-Broil LLC, and De’ Longhi focusing on innovation and global distribution; however, high competition and limited flavor compared to charcoal grills act as restraints.
- North America led the market with a 34.1% share, followed by Asia Pacific at 28.6%; by product, electric griddles dominated, owing to their versatility and ease of use.
Market Segmentation Analysis:
By Product
In the Electric Grill market, electric griddles dominate the product segment, accounting for the largest market share in 2024. Their popularity stems from their versatility, ease of use, and suitability for preparing a wide range of foods, making them a preferred choice for households and small food businesses. Electric griddles also offer faster cooking times and temperature control, which appeals to consumers seeking convenience and energy efficiency. Additionally, growing awareness of indoor grilling and the rise in health-conscious eating habits are driving demand for electric griddles across both developed and emerging markets.
- For instance, Zojirushi America’s EA-DCC10 electric griddle features a ceramic cooking surface with a temperature range of 176°F to 425°F and a cooking area of 19" x 12.5", making it a popular model among consumers seeking precise control and easy maintenance.
By Distribution Channel:
The offline distribution channel holds the dominant market share in 2024, owing to the strong presence of retail stores, specialty kitchen appliance outlets, and department stores. Consumers still prefer in-store purchases for high-involvement products like electric grills due to the ability to physically inspect the product, seek expert advice, and benefit from promotional deals. However, the online segment is rapidly gaining traction, driven by increasing digital penetration, convenience of home delivery, and broader product variety. Retailers are also adopting omnichannel strategies to capitalize on both online and offline opportunities.
- For instance, Weber expanded its direct-to-consumer strategy by launching its proprietary e-commerce platform in 40 countries, while maintaining over 7,000 physical retail partner locations globally.
By End-use:
The residential segment leads the end-use category in the electric grill market, contributing the highest revenue share in 2024. The rising trend of home cooking, supported by increased awareness around healthy lifestyles and reduced oil consumption, has driven demand for electric grills in households. Furthermore, growing urbanization, smaller living spaces, and bans on open-flame grilling in residential buildings have made electric grills an attractive alternative. The commercial segment is also expanding, especially within restaurants and quick-service outlets, as electric grills enable efficient, smoke-free cooking in indoor settings.
Market Overview
Rising Demand for Indoor Cooking Appliances
The increasing adoption of electric grills is largely driven by growing consumer preference for indoor cooking solutions, especially in urban settings. Traditional grills, which rely on open flames or charcoal, are often restricted in apartments and enclosed spaces. Electric grills offer a safer, smoke-free, and compact alternative, making them ideal for modern homes. Additionally, evolving lifestyle patterns and a shift toward healthy home-cooked meals support the popularity.
- For instance, De’Longhi’s MultiGrill CGH1030D is specifically designed for indoor use, offering 6 cooking functions and 2 independent electronic temperature controls, with a maximum heat output of 450°F across a 14.5" x 9" surface.
Growth in Smart Kitchen Appliances
The integration of smart features in electric grills, such as digital temperature controls, programmable timers, and app connectivity, is propelling market growth. Consumers are increasingly inclined toward appliances that enhance convenience and cooking precision. Manufacturers are focusing on innovation to offer smart, energy-efficient, and user-friendly products. The rising penetration of IoT and smart home ecosystems globally has amplified this demand, especially in technologically advanced regions such as North America and Europe, thereby contributing to the widespread adoption of advanced electric grill models.
- For instance, Char-Broil’s SmartChef® TRU-Infrared Electric Grill connects via Wi-Fi and mobile apps, enabling remote control and temperature monitoring with ±5°F accuracy, providing users with a high degree of precision and control.
Expanding Foodservice Sector and Outdoor Catering
The growth of the foodservice industry, including fast-casual restaurants, cafes, and catering services, has bolstered demand for electric grills in commercial applications. These establishments favor electric grills for their quick heat-up times, low maintenance, and indoor compatibility. The rising trend of live cooking stations and food trucks also contributes to this growth. Furthermore, electric grills are increasingly used in outdoor catering and events where open-flame grilling is either restricted or impractical, making them a versatile tool for professional use.
Key Trends & Opportunities
Surge in Eco-friendly and Energy-efficient Appliances
With growing environmental awareness, consumers are gravitating toward energy-efficient and eco-friendly kitchen appliances. Electric grills that use less power, emit lower emissions, and eliminate the need for charcoal or gas are gaining attention. This shift aligns with government policies promoting sustainable energy consumption and reductions in household carbon footprints. Manufacturers are responding with greener materials and energy-saving technologies, offering significant growth opportunities for brands that focus on sustainability as a core product feature.
- For instance, Glen Dimplex introduced the Morphy Richards electric grill line with an Eco Mode that consumes 28% less electricity than standard models, confirmed through in-lab efficiency testing under BS EN 60335 standards.
Rising Popularity of Portable and Compact Grills
Portable and compact electric grills are witnessing increased demand, especially among younger consumers and renters who require space-efficient cooking solutions. These models are favored for their ease of use, low maintenance, and mobility, making them ideal for balconies, patios, and travel use. The growth of outdoor recreational activities, including camping and tailgating, is also opening up new opportunities for compact electric grills. Brands focusing on lightweight, foldable, and user-friendly designs are well-positioned to capture this emerging segment.
- For instance, George Foreman’s GFO240S Indoor/Outdoor Electric Grill weighs 17.2 pounds, supports up to 15 servings, and features a removable stand, making it one of the most popular compact models sold in over 60,000 units per year through both Walmart and Amazon channels.
Key Challenges
Limited Flavor Profile Compared to Traditional Grills
One of the major challenges in the electric grill market is the perceived compromise on taste and aroma compared to traditional charcoal or gas grills. Many grilling enthusiasts value the smoky flavor imparted by wood or charcoal, which electric grills inherently lack. This limitation poses a barrier to adoption among traditional grill users and can hinder market penetration in regions where outdoor grilling is culturally significant. Bridging this sensory gap remains a key hurdle for manufacturers.
High Competition and Price Sensitivity
The market faces intense competition with a wide range of brands offering electric grills at varying price points. As a result, consumers often exhibit price sensitivity, particularly in emerging economies. Smaller players face challenges in differentiating their products and maintaining profitability. Moreover, frequent technological upgrades and the availability of low-cost alternatives further pressure manufacturers to innovate while keeping costs competitive, which can strain margins and hinder scalability.
Infrastructure Constraints in Developing Regions
The adoption of electric grills in many developing countries is constrained by inadequate access to reliable electricity and limited awareness of electric cooking technologies. In regions with frequent power outages or voltage fluctuations, electric appliances are less preferred. Moreover, traditional cooking practices and low purchasing power can slow down market penetration. Addressing these challenges requires targeted marketing, infrastructure improvements, and affordable product variants tailored to regional needs.
Regional Analysis
North America:
North America dominated the global electric grill market in 2024, holding the largest regional share of approximately 34.1%, with market size rising from USD 1,228.20 million in 2018 to USD 1,514.09 million in 2024. The region is projected to reach USD 2,705.16 million by 2032, growing at a CAGR of 7.6%. Growth is driven by high consumer spending on advanced kitchen appliances, rising popularity of indoor grilling, and increasing demand for convenient and healthy cooking options. The strong presence of key manufacturers and early adoption of smart and energy-efficient appliances further strengthen the region’s market leadership.
Europe:
Europe accounted for 23.3% of the global electric grill market in 2024, with its market size increasing from USD 865.79 million in 2018 to USD 1,035.66 million. It is forecasted to reach USD 1,741.54 million by 2032, registering a CAGR of 6.8%. The European market benefits from stringent energy regulations, a growing focus on sustainable appliances, and a well-established consumer base favoring compact and eco-friendly cooking solutions. Countries like Germany, the UK, and France contribute significantly to regional growth through higher disposable incomes and demand for smart home integration in kitchen appliances.
Asia Pacific:
Asia Pacific is the fastest-growing region in the electric grill market, holding around 28.6% market share in 2024. The market expanded from USD 978.29 million in 2018 to USD 1,269.82 million in 2024 and is projected to reach USD 2,482.44 million by 2032, at a CAGR of 8.8%. Growth is driven by rising urbanization, expanding middle-class population, and increasing interest in modern cooking appliances across China, India, and Southeast Asia. In addition, increasing internet penetration and e-commerce platforms are helping manufacturers reach a wider customer base, making the region a lucrative market for electric grill makers.
Latin America:
Latin America accounted for a modest 6.5% of the global electric grill market in 2024, with the market growing from USD 234.25 million in 2018 to USD 289.80 million. It is expected to reach USD 482.57 million by 2032, expanding at a CAGR of 6.7%. Demand is supported by increasing urban population, greater interest in home cooking, and growing exposure to Western culinary trends. Countries such as Brazil, Mexico, and Argentina are key contributors. Despite economic challenges, rising awareness about electric cooking devices and increasing retail penetration are fostering gradual but consistent market expansion.
Middle East:
The Middle East held a 4.6% share of the global electric grill market in 2024, with its size rising from USD 173.37 million in 2018 to USD 205.79 million. The market is forecasted to reach USD 340.47 million by 2032, growing at a CAGR of 6.6%. The growth is driven by expanding foodservice sectors in urban hubs like the UAE and Saudi Arabia and a rising preference for smoke-free cooking indoors. Increasing adoption of modern kitchen appliances among affluent consumers and the hospitality sector’s investment in efficient cooking technologies also support regional market development.
Africa:
Africa accounted for the smallest share of the global electric grill market in 2024, at around 2.9%. The market grew from USD 80.10 million in 2018 to USD 130.27 million and is expected to reach USD 201.79 million by 2032, at a CAGR of 5.2%. Limited infrastructure and low consumer purchasing power remain key barriers, although increasing electrification and urban development are gradually improving market conditions. South Africa and Nigeria are leading contributors due to rising awareness of modern cooking appliances. Opportunities exist for low-cost, energy-efficient electric grills tailored to local economic and infrastructure.
Market Segmentations:
By Product
- Electric Smokers
- Electric Griddles
By Distribution Channel
- Online
- Offline
By End-use
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the electric grill market is characterized by the presence of several prominent players competing on product innovation, pricing strategies, and distribution reach. Key companies such as Weber, The Middleby Corporation, Char-Broil LLC, Taylor Commercial Foodservice, LLC, and ROLLER GRILL focus on expanding their product portfolios with advanced features like digital controls, smart connectivity, and energy-efficient designs to gain a competitive edge. Manufacturers also prioritize durable materials, compact designs, and user-friendly features to cater to evolving consumer preferences across residential and commercial segments. Strategic collaborations, acquisitions, and expansion into emerging markets further define competitive dynamics. Companies such as Zojirushi America Corporation, De’ Longhi Appliances, and Glen Dimplex Americas strengthen their global footprint through retail partnerships and e-commerce platforms. Meanwhile, niche players like Holland Grill and FIRE MAGIC target premium segments with specialized offerings. Overall, the market reflects moderate concentration, with innovation, quality, and brand positioning serving as key differentiators among competitors.
Key Player Analysis
- Weber
- The Middleby Corporation
- Char-Broil LLC
- Taylor Commercial Foodservice, LLC
- ROLLER GRILL
- Zojirushi America Corporation
- Holland Grill
- FIRE MAGIC
- Glen Dimplex Americas
- De’ Longhi Appliances
Recent Developments
- In March 2025, SMEG S.p.A., an Italy-based manufacturer, announced the launch of a built-in electric barbeque grills, cooking ranges, new fridges, and also a laundry collection. The company is planning to enhance its large appliance collection in the U.S. market.
- In June 2024, Kenyon announced the launch of The Signature Grill. It is its newest grill which offers personalized grilling to match one’s unique signature style. It is a built-in grill for both outdoor and indoor use.
- In February 2024, Current Backyard launched Current Model G Electric Griddle and Current Model G Dual-Zone Electric Grill. It’s a solution to consumers looking for electric grilling experience outdoors with smart home connectivity.
- In March 2024, Char-Broil, a U.S. -based company, announced the launch of its new barbeque grills, which are available in both electric and gas models. This product is available on both online and offline platforms.
- In February 2024, Current Backyard LLC, a U.S.-based company, announced the launch of the Current Model G Electric Griddle and Current Model G Dual-Zone Electric Grill. The new griddles and grill will help consumers improve the outdoor electric grilling experience.
Market Concentration & Characteristics
The Electric Grill Market exhibits a moderate level of market concentration, with a mix of global and regional players competing across various price points and product categories. It is characterized by a strong focus on product innovation, energy efficiency, and user convenience. Companies prioritize developing smart features such as temperature control, programmable settings, and compact designs to cater to evolving consumer preferences. The market structure supports both premium and value-based offerings, allowing smaller brands to compete through niche positioning and cost-effective models. It responds quickly to trends in home cooking, sustainability, and urban living, which influence product development and distribution strategies. Retail networks, both offline and online, play a key role in shaping consumer access and brand visibility. Leading brands maintain competitive advantages through global supply chains, brand loyalty, and technological advancements, while emerging players focus on affordable and space-saving solutions. It remains responsive to seasonal demand spikes, especially in North America and Europe, and shows growing traction in Asia Pacific due to rising middle-class income and urbanization.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The electric grill market will continue to expand with rising demand for smoke-free, indoor cooking solutions in urban areas.
- Smart electric grills with app control and precision temperature settings will gain more consumer traction.
- Asia Pacific will emerge as the fastest-growing region due to increasing disposable income and urbanization.
- Manufacturers will focus on compact, portable designs to appeal to consumers with limited kitchen space.
- Online retail channels will see higher sales volumes driven by digital convenience and wider product availability.
- Energy-efficient and eco-friendly models will become more prominent in response to sustainability preferences.
- Residential users will remain the dominant end-users, supported by growing interest in home cooking and wellness.
- Commercial demand will rise in restaurants and catering services seeking consistent and efficient cooking solutions.
- Product differentiation through design, durability, and smart features will drive brand competition.
- Companies will invest in emerging markets with tailored pricing and localized marketing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Grill Market?
What factors are driving the growth of the Electric Grill Market?
What are some challenges faced by the Electric Grill Market?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Grills Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Grills Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 4,445.43 million → forecast year: USD 7,953.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Grills Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Grills Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Grills Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Grills Market Drivers
- 3.3 Electric Grills Market Restraints & Challenges
- 3.4 Electric Grills Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Grills Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Grills Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Grills category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Grills Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electric Grills Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electric Grills market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Grills Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Grills Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electric Grills Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Grills (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electric Grills Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Grills Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electric Grills Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Grills Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Grills Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Grills Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Grills Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Grills Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Grills Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
