
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China Meat Processing Equipment Market Size 2023 | USD 1,425.20 million |
| China Meat Processing Equipment Market, CAGR | 7.14% |
| China Meat Processing Equipment Market Size 2032 | USD 2,653.85 million |
Market Overview:
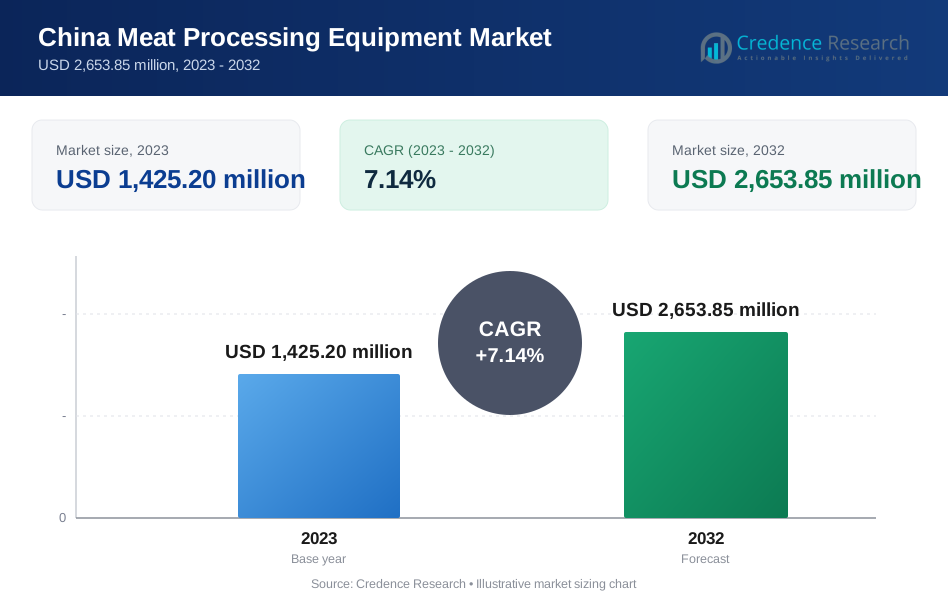
China Meat Processing Equipment Market size was valued at USD 1,425.20 million in 2023 and is anticipated to reach USD 2,653.85 million by 2032, at a CAGR of 7.14% during the forecast period (2023-2032).
Several factors contribute to the strong growth of the China Meat Processing Equipment Market. Firstly, the rising demand for processed meat due to shifting consumer preferences toward ready-to-cook and packaged food products is a significant driver. Secondly, technological advancements in meat processing equipment, such as automation, AI integration, and precision cutting technologies, are improving efficiency and product quality. Additionally, stringent food safety regulations and the enforcement of hygiene standards are compelling meat processors to adopt modern equipment to ensure compliance and maintain product quality. The expansion of e-commerce and retail channels has also facilitated increased sales of processed meat, further driving demand for advanced processing equipment.
The China Meat Processing Equipment Market is experiencing significant growth across key regions, particularly in coastal provinces such as Guangdong, Jiangsu, and Zhejiang, where urbanization and disposable incomes are higher. These regions are home to several large-scale meat processing facilities and food manufacturing hubs. In northern and central China, including Beijing and Henan, the industry benefits from strong government policies promoting food safety and industrial automation. Meanwhile, western provinces such as Sichuan and Chongqing are witnessing growing demand, primarily driven by increasing meat consumption and the expansion of local food production industries. Overall, regional differences in economic development, consumption patterns, and industrial infrastructure influence market dynamics, making tiered expansion strategies essential for industry players.
Market Insights:
- The China Meat Processing Equipment Market was valued at USD 1,425.20 million in 2023 and is expected to reach USD 2,653.85 million by 2032, growing at a CAGR of 7.14% during the forecast period.
- Rising demand for processed meat products, driven by urbanization, changing dietary habits, and increased disposable incomes, is fueling market growth and adoption of advanced processing technologies.
- Technological advancements, including automation, AI integration, and precision cutting equipment, are improving processing efficiency, reducing costs, and ensuring product consistency.
- Strict food safety regulations set by the National Food Safety Standards (GB) and General Administration of Customs of China (GACC) are compelling manufacturers to invest in modern, compliant processing equipment.
- The e-commerce boom and expansion of retail channels are increasing sales of processed meat, driving demand for high-tech meat processing, packaging, and cold-chain logistics solutions.
- High initial investment and maintenance costs pose a challenge for small and medium-sized meat processors, limiting their access to cutting-edge equipment and automation solutions.
- Regional growth disparities exist, with Guangdong, Jiangsu, and Zhejiang leading due to higher urbanization, while Henan, Sichuan, and Chongqing are witnessing rising demand fueled by local meat production expansion.
Market Drivers:
Rising Demand for Processed Meat Products
The increasing demand for processed meat products is a significant factor propelling the growth of the China Meat Processing Equipment Market. As urbanization accelerates and lifestyles become more fast-paced, consumers are shifting towards convenience foods, including packaged and ready-to-eat meat products. This change in consumption patterns has heightened the need for efficient meat processing solutions to meet rising demand while ensuring quality and safety. For instance, Hebei Xiaojin Machinery Manufacturing Inc., established in 1986, has over 30 years of experience in the food processing machinery industry and is a leading player in China. .Moreover, the expanding middle-class population with higher disposable incomes is driving premium meat product consumption, further increasing the adoption of advanced processing equipment among manufacturers.
Technological Advancements in Meat Processing Equipment
Continuous innovations in meat processing technology are transforming the industry by enhancing automation, precision, and efficiency. The integration of artificial intelligence (AI), robotics, and IoT-enabled monitoring systems is improving the production process, reducing operational costs, and minimizing human error. For example, robotic butchering systems utilize AI and machine learning to accurately identify and separate different cuts of meat, reducing waste and ensuring quality standards. Equipment such as automated slicers, deboning machines, and high-speed meat grinders are becoming more prevalent, allowing manufacturers to enhance production capacity while maintaining consistency in product quality. Additionally, energy-efficient and sustainable processing technologies are gaining traction, aligning with China's increasing focus on environmental sustainability and resource conservation in the food industry.
Stringent Food Safety Regulations and Hygiene Standards
The Chinese government has been enforcing strict food safety regulations to ensure high-quality meat processing standards. These regulations, including those set by the National Food Safety Standards (GB) and the General Administration of Customs of China (GACC), mandate adherence to stringent hygiene protocols and advanced processing methods. For example, the National Food Safety Standard for "Sanitary Practices for The Production of Cooked Meat Products" (GB 19303-2023) implemented on September 6, 2024, replaces GB 19303-2003 and includes modified requirements for site selection, environmental conditions, facilities, equipment, food storage, transportation, and processing procedures. This regulatory landscape has encouraged meat processing companies to invest in state-of-the-art equipment that complies with international food safety norms. Additionally, consumer awareness regarding foodborne diseases and contamination risks has further pressured manufacturers to adopt automated, contactless processing solutions, reducing human handling and enhancing food safety across the supply chain.
Expansion of E-Commerce and Retail Distribution Channels
The rapid growth of e-commerce and modern retail channels has significantly influenced the demand for processed meat products, thereby boosting the need for advanced meat processing equipment. Online grocery platforms and supermarket chains are expanding their product offerings, leading to a surge in demand for efficient packaging, preservation, and cold-chain logistics technologies. For instance, major e-commerce platforms like Alibaba's Tmall and JD.com have become prominent players in the meat industry, offering a wide range of products from both domestic and international suppliers. The rise of direct-to-consumer meat delivery services has further accelerated the adoption of automated meat processing systems to meet high-volume requirements while ensuring freshness, extended shelf life, and compliance with safety standards. As the e-commerce sector continues to expand, meat processors are increasingly investing in high-tech equipment to enhance supply chain efficiency and cater to evolving consumer preferences.
Market Trends:
Growing Adoption of Automation and Smart Technologies
The China Meat Processing Equipment Market is witnessing a significant shift towards automation and smart processing technologies to enhance efficiency, consistency, and product quality. Advanced robotic butchering, AI-powered sorting systems, and IoT-enabled monitoring solutions are becoming integral to modern meat processing facilities. These technologies help manufacturers streamline operations, reduce labor dependency, and maintain hygiene standards by minimizing human intervention. For instance, advanced robotic systems are being integrated into meat processing lines to perform tasks such as cutting and deboning with high precision, thereby reducing labor costs and improving consistency. Additionally, automated processing solutions contribute to higher yields and lower waste, making them a preferred choice for large-scale meat processing plants looking to optimize production costs while meeting increasing consumer demand.
Surging Demand for Plant-Based and Alternative Meat Processing Equipment
The rising popularity of plant-based and alternative protein products is influencing equipment innovation in China’s meat processing sector. As consumers shift towards health-conscious and sustainable dietary choices, manufacturers are expanding their product portfolios to include plant-based meat substitutes and lab-grown meat. This shift is driving investments in specialized equipment, such as extruders for plant-based protein processing, high-pressure processing (HPP) systems for texture enhancement, and advanced blending technologies. For instance, OctoFrost specializes in Individual Quick Freezing (IQF) technology, which ensures moisture retention and prevents dehydration in frozen plant-based meat products, maintaining their texture and nutritional quality. As the alternative protein market gains traction, meat processing companies are adapting their facilities to accommodate new product categories while maintaining compliance with food safety and quality standards.
Emphasis on Energy Efficiency and Sustainable Processing
Sustainability is becoming a crucial factor in the development of China’s meat processing industry, with an increasing focus on energy-efficient and eco-friendly processing technologies. Meat processors are investing in water-saving slaughtering systems, waste heat recovery mechanisms, and energy-efficient refrigeration solutions to reduce environmental impact. For instance, KUKA AG’s automation solutions are designed to minimize energy consumption and carbon footprint, while meat processors are also turning to biodegradable and recyclable packaging materials. Additionally, the adoption of biodegradable and recyclable packaging materials is gaining momentum, aligning with China’s national goals for carbon neutrality and reduced plastic waste. Manufacturers are also exploring alternative energy sources, such as solar-powered processing plants, to lower operational costs and minimize their carbon footprint in response to regulatory pressures and consumer expectations for sustainable food production.
Rising Integration of Cold Chain Logistics in Meat Processing
The expansion of cold chain logistics is playing a pivotal role in supporting the growth of China’s meat processing industry, ensuring that processed meat products maintain freshness and quality throughout distribution. With the increasing demand for frozen and chilled meat products, advanced refrigeration and storage solutions are becoming essential. Innovations such as vacuum-sealed packaging, temperature-controlled transportation, and real-time monitoring of storage conditions are enhancing supply chain efficiency. For instance, OctoFrost’s IQF freezing technology plays a key role in ensuring optimal product integrity, particularly for frozen meat and plant-based products, by locking in freshness and preventing dehydration. Additionally, government initiatives promoting investments in cold storage infrastructure are further strengthening the market, enabling meat processors to expand their reach across both domestic and international markets while meeting stringent safety and quality standards.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs
One of the primary restraints in the China Meat Processing Equipment Market is the high initial investment required for purchasing and installing advanced processing machinery.** Small and medium-sized meat processing enterprises often struggle with the financial burden of acquiring state-of-the-art equipment, as these systems involve significant capital expenditure. Additionally, ongoing maintenance costs, operational expenses, and the need for skilled labor to operate and maintain automated systems further add to the financial strain. While large-scale meat processors are able to invest in cutting-edge technologies, smaller players face challenges in keeping up with industry advancements, limiting their ability to compete effectively in the market.
Regulatory Compliance and Supply Chain Disruptions
Stringent food safety regulations, hygiene standards, and environmental policies pose challenges for meat processing companies operating in China. Compliance with evolving regulations, such as those mandated by the General Administration of Customs of China (GACC) and the National Food Safety Standards (GB), requires constant upgrades to processing equipment, training personnel, and adopting advanced monitoring technologies. Additionally, disruptions in the supply chain, including raw material shortages, fluctuations in meat prices, and logistics inefficiencies, impact production stability. The COVID-19 pandemic further highlighted the vulnerability of global supply chains, leading to increased scrutiny over imported meat products and delays in equipment procurement. Overcoming these regulatory and logistical challenges requires strategic planning and investment in localized supply chains and regulatory expertise to ensure seamless operations in the evolving market landscape.
Market Opportunities:
The China Meat Processing Equipment Market presents significant opportunities with the ongoing expansion of meat processing facilities and investments in technological advancements. As consumer demand for high-quality, processed meat products rises, manufacturers are increasingly adopting automated, high-speed processing equipment to enhance productivity and efficiency. Government initiatives promoting modernization of the food processing sector and investments in smart manufacturing further create avenues for advanced machinery adoption, including AI-driven cutting, deboning, and packaging systems. Additionally, the growing presence of international meat processing equipment manufacturers in China is fostering innovation, offering local players access to cutting-edge technology and customized solutions tailored to the domestic market’s specific needs.
The increasing demand for alternative protein sources, including plant-based and cultured meat, is driving the need for specialized processing equipment. As China emerges as a key player in the global plant-based meat industry, manufacturers have the opportunity to expand their processing capabilities to cater to this fast-growing segment. Additionally, the rising demand for high-quality Chinese meat products in international markets presents an opportunity for local meat processors to upgrade their facilities and meet export-quality standards. Investments in advanced food safety technologies, cold chain logistics, and sustainable processing solutions will further strengthen China’s position in the global meat processing industry, creating long-term growth prospects for equipment manufacturers.
Market Segmentation Analysis:
The China Meat Processing Equipment Market is segmented based on type, meat type, and product, each playing a crucial role in the industry's growth and technological advancements.
By Type, the market includes slicing, bending, dicing, grinding, and massaging & marinating equipment. Slicing and dicing machinery dominate the segment due to the rising demand for precision-cut meat products in retail and foodservice industries. Grinding equipment is also experiencing steady growth as the consumption of processed and ground meat products increases. The massaging and marinating segment is expanding with the growing popularity of seasoned and ready-to-cook meat products.
By Meat Type, the market is categorized into beef, mutton, pork, and others. Pork holds the largest market share, driven by its high consumption in China’s culinary culture. The beef segment is growing steadily due to increasing consumer demand for premium and imported beef products. Mutton and other meat types are also gaining traction, particularly in western China, where lamb-based dishes are more prevalent.
By Product, the market includes fresh processed meat, raw cooked meat, precooked meat, raw fermented sausage, and cured meat. Fresh processed meat remains the dominant segment, reflecting consumer preference for minimally processed but convenient options. Raw cooked and precooked meat are experiencing rapid growth due to the rise of fast-food chains and home-cooking convenience trends. Raw fermented sausages and cured meats continue to see demand, particularly in traditional and regional meat product markets.
Segmentation:
By Type
- Slicing
- Bending
- Dicing
- Grinding
- Massaging & Marinating
By Meat Type
- Beef
- Mutton
- Pork
- Others
By Product
- Fresh processed meat
- Raw cooked meat
- Precooked meat
- Raw fermented sausage
- Cured meat
Regional Analysis:
Eastern China: The Leading Hub for Meat Processing
Eastern China holds the largest market share, accounting for approximately 35% of the China Meat Processing Equipment Market. This dominance is primarily due to the presence of major industrial cities such as Shanghai, Jiangsu, and Zhejiang, where large-scale meat processing facilities and advanced food manufacturing industries are concentrated. These regions benefit from well-developed infrastructure, a strong supply chain network, and high consumer demand for processed meat products. The expansion of retail chains, fast-food outlets, and e-commerce grocery platforms in these provinces further drives the need for modern meat processing equipment. Additionally, stringent food safety regulations in these economically advanced areas have led to higher investments in automation, AI-integrated processing systems, and sustainable meat production technologies.
Northern and Central China: Rapid Industrialization and Government Support
Northern and Central China collectively account for around 30% of the market share, driven by provinces such as Beijing, Henan, and Shandong. These regions are witnessing rapid industrialization and strong government initiatives supporting food safety and modern meat processing techniques. Henan, known for its large-scale meat production facilities, is a key player in China’s meat processing industry, housing several leading meat manufacturers. Meanwhile, Beijing’s strict regulatory oversight and consumer demand for high-quality processed meat products are pushing companies to adopt advanced processing technologies. Furthermore, Central China’s growing population and rising disposable incomes are leading to an increase in meat consumption, necessitating further investment in efficient meat processing equipment.
Southern China: Growing Demand for Premium and Processed Meat Products
Southern China holds approximately 20% of the market share, driven by its strong food industry and consumer preference for premium, processed meat products. Guangdong, in particular, has emerged as a leading region for imported meat processing and high-end meat products, catering to affluent consumers. The rise of modern retail formats, including supermarkets and specialty meat stores, has further boosted the demand for automated processing and packaging solutions. Additionally, the expansion of quick-service restaurants (QSRs) and the increasing popularity of Western-style processed meat products are key growth drivers in the region. Southern China’s well-established logistics and cold chain infrastructure also supports efficient meat processing and distribution, making it a crucial market for advanced processing equipment.
Western China: Emerging Market with Growth Potential
Western China, including provinces such as Sichuan and Chongqing, holds around 15% of the market share, but it is the fastest-growing region. Increasing urbanization and rising consumer awareness about processed and frozen meat products are driving demand for modern meat processing facilities. The government’s focus on rural industrial development is also encouraging investment in food processing infrastructure and meat production technologies. Although currently lagging behind other regions in terms of technological adoption, Western China’s expanding middle-class population and improving supply chain networks present a significant growth opportunity for meat processing equipment manufacturers in the coming years.
Key Player Analysis:
- Mepaco
- Minerva Omega Group s.r.l
- Tomra Systems ASA
- JBT
- Nemco Food Equipment, LTD
- RAM Beef Equipment
- The Middleby Corporation
- Marel
- Equipamientos cárnicos
- S.L. (MAINCA)
- Bettcher Industries, Inc
- Fortifi Food Processing Solutions
- Company 13
- Company 14
Competitive Analysis:
The China Meat Processing Equipment Market is characterized by intense competition among both domestic and international manufacturers striving to capture significant market share. Leading global companies, such as Marel, GEA Group AG, and JBT Corporation, have established a strong presence in China, offering advanced processing solutions that cater to the evolving demands of large-scale meat processors. These multinational corporations leverage their technological expertise and comprehensive service networks to maintain a competitive edge in the market. In parallel, numerous domestic enterprises have emerged as formidable competitors by providing cost-effective and customized equipment tailored to local market needs. Companies like Newamstar and Triowin have gained traction by focusing on innovation and understanding regional consumer preferences. The competitive landscape is further intensified by the rapid adoption of automation and smart technologies, compelling manufacturers to continuously upgrade their offerings. For instance, Newamstar has implemented advanced automation and robotics in their meat processing equipment to enhance efficiency and reduce labor costs. This dynamic environment fosters ongoing innovation and strategic partnerships, shaping the future trajectory of the meat processing equipment industry in China.
Recent Developments:
- In August 2024, Mepaco (part of Apache Stainless) launched the ETD3000 Electric Tote Dumper, designed for food and operational safety and production efficiency. The electric dumper eliminates the maintenance and inefficiencies associated with hydraulics16. Also, Mepaco has opened a food processing research and test facility called the Validation Lab to support the food processing industry.
- In April 2024, Nemco announced an extensive expansion to its Ohio manufacturing facility.
- In November 2024, Middleby acquired Gorreri Food Processing Technology a manufacturer of baked goods equipment
Market Concentration & Characteristics:
The China Meat Processing Equipment Market is moderately concentrated, with a mix of established multinational corporations and competitive domestic players driving industry growth. Leading global companies, including Marel, GEA Group AG, and JBT Corporation, hold a significant market share due to their technological expertise and advanced automation solutions. At the same time, domestic manufacturers such as Newamstar and Triowin are expanding their presence by offering cost-effective and customized equipment tailored to local industry needs. The market is characterized by rapid technological advancements, increasing automation, and stringent regulatory compliance requirements. Product innovation, energy efficiency, and food safety are key differentiators in this competitive landscape. Additionally, the industry's growth is supported by rising demand for processed meat, expansion of retail channels, and investments in smart manufacturing technologies. As companies strive for operational efficiency and regulatory compliance, the market continues to evolve towards greater digitalization and intelligent processing solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Meat Type and By Product. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of AI, robotics, and IoT in meat processing equipment will enhance efficiency, precision, and compliance with food safety standards.
- Rising demand for plant-based and lab-grown meat will drive innovation in specialized processing equipment to accommodate new product categories.
- Stricter food safety and hygiene regulations will push manufacturers to invest in advanced sanitation, traceability, and compliance-focused processing technologies.
- Improvements in temperature-controlled storage and transportation will enhance the quality and safety of processed meat products.
- Rising urbanization and disposable incomes will increase consumption of processed meat, fueling the demand for efficient, high-speed processing equipment.
- Investments in quality assurance and international food safety certifications will strengthen China’s position as a key exporter of processed meat products.
- Adoption of energy-efficient and eco-friendly technologies will become essential as environmental regulations tighten.
- Smart processing plants integrating data analytics and real-time monitoring will optimize production efficiency and minimize operational costs.
- Mergers and acquisitions among domestic and international players will lead to increased competition and technological collaboration.
- Growth in online grocery platforms and direct-to-consumer meat sales will drive demand for automated packaging and extended shelf-life solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the China Meat Processing Equipment Market?
What factors are driving the growth of the China Meat Processing Equipment Market?
What are some challenges faced by the China Meat Processing Equipment Market?
Who are the major players in the China Meat Processing Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China Meat Processing Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China Meat Processing Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,425.20 million → 2032: USD 2,653.85 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China Meat Processing Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China Meat Processing Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China Meat Processing Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China Meat Processing Equipment Market Drivers
- 3.3 China Meat Processing Equipment Market Restraints & Challenges
- 3.4 China Meat Processing Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China Meat Processing Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China Meat Processing Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China Meat Processing Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China Meat Processing Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China Meat Processing Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China Meat Processing Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China Meat Processing Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China Meat Processing Equipment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China Meat Processing Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China Meat Processing Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China Meat Processing Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China Meat Processing Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China Meat Processing Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China Meat Processing Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China Meat Processing Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China Meat Processing Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China Meat Processing Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China Meat Processing Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China Meat Processing Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
