
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| China Women Apparel Market Size 2023 | USD 121,459.07 Million |
| China Women Apparel Market, CAGR | 5.11% |
| China Women Apparel Market Size 2032 | USD 190,285.93 Million |
Market Overview
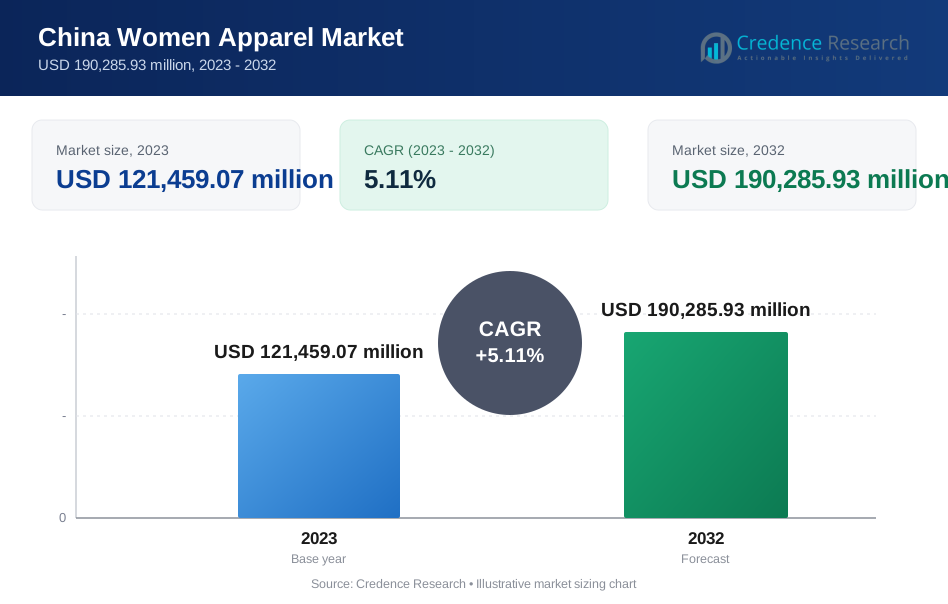
The China Women Apparel Market is projected to grow from USD 121,459.07 million in 2023 to an estimated USD 190,285.93 million by 2032, with a compound annual growth rate (CAGR) of 5.11% from 2024 to 2032. This growth is driven by increasing disposable income, a rising middle class, and growing demand for fashionable, high-quality clothing.
The market is largely driven by factors such as urbanization, changing lifestyles, and the growing influence of social media on fashion trends. Additionally, the increasing preference for online shopping and the rising adoption of sustainable and eco-friendly fashion are significant trends that are expected to shape the market. Brands are focusing on innovation, offering personalized shopping experiences and embracing digital transformation to meet consumer demand for convenience and exclusivity.
Geographically, the market is dominated by major urban centers, with first- and second-tier cities such as Beijing, Shanghai, and Guangzhou leading the demand for women’s apparel. These cities experience a higher concentration of fashion-conscious consumers and purchasing power. Key players in the market include domestic and international brands such as Anta, Li Ning, Zara, and H&M, which have strategically positioned themselves to capture the growing demand for women's fashion across China.
Market Insights
- The China Women Apparel Market is expected to grow from USD 121,459.07 million in 2023 to USD 190,285.93 million by 2032, with a CAGR of 5.11% from 2024 to 2032.
- Increasing disposable income and a growing middle class are driving demand for both affordable and premium apparel in China.
- Urbanization is significantly impacting the apparel market, with major cities like Beijing, Shanghai, and Guangzhou seeing heightened demand for fashionable clothing.
- The growing influence of social media on fashion trends and the rise of e-commerce platforms are shaping consumer purchasing behavior.
- There is a rising consumer preference for eco-friendly and sustainable fashion, pushing brands to adopt more responsible production practices.
- Key players such as Anta, Li Ning, Zara, and H&M are strategically positioned to cater to the expanding consumer base in both domestic and international markets.
- First- and second-tier cities dominate the market, but emerging regions such as second- and third-tier cities are expected to experience significant growth in the coming years.
Market Drivers
Increasing Disposable Income and Rising Middle Class
One of the primary drivers of the China Women Apparel Market is the growing disposable income of Chinese consumers. Over the past few years, China has experienced significant economic growth, leading to an increase in income levels, especially in urban areas. This rise in disposable income enables consumers to spend more on discretionary products, including clothing. The expansion of the middle class, which is becoming more financially stable and fashion-conscious, further drives demand for women’s apparel. The ability to purchase high-quality, branded, and fashionable clothing has led to a shift in consumer purchasing behavior, with women increasingly seeking a wide range of clothing options to suit their lifestyle and preferences. This trend is expected to continue as China’s middle-class population grows, contributing to the overall expansion of the women’s apparel market.For instance, China's average disposable income increased significantly over the past year, reflecting a broader economic trend where urban incomes have risen substantially. This growth in disposable income has enabled consumers to spend more on discretionary products like clothing, contributing to the expansion of the women's apparel market.
Urbanization and Changing Lifestyles
Urbanization is another significant driver fueling the demand for women’s apparel in China. As more people move from rural areas to urban centers in search of better job opportunities and improved living standards, the demand for fashionable clothing increases. This shift has led to the growth of large metropolitan cities, such as Beijing, Shanghai, and Guangzhou, which have become hubs of fashion and retail. As urban populations become more diverse and exposed to global fashion trends, there is a growing desire for stylish and trendy clothing. Additionally, changing lifestyles, including a shift toward a more fast-paced, dynamic way of living, also play a role. Women in urban areas are more inclined to purchase apparel that is versatile, comfortable, and suitable for their busy routines. The influence of modern lifestyle changes, such as increased participation of women in the workforce and the rise of dual-income households, has resulted in an increased focus on fashion-forward, functional, and stylish apparel.For example, cities like Beijing and Shanghai have become major fashion hubs due to urbanization, with a growing demand for fashionable clothing as urban lifestyles become more fast-paced and diverse. The shift toward dual-income households and increased participation of women in the workforce has further fueled the demand for versatile and stylish apparel.
Influence of Social Media and Digitalization
The influence of social media and the digital landscape has been a key driver in the growth of the China Women Apparel Market. Platforms like WeChat, Weibo, Douyin (Chinese TikTok), and Instagram have become major tools for fashion brands to engage with consumers, promote their products, and influence purchasing behavior. Chinese consumers are highly active on social media, and the ability to follow fashion trends, interact with influencers, and receive personalized recommendations has had a significant impact on the way apparel is marketed and consumed. The growing use of e-commerce platforms has also facilitated the shift toward online shopping, offering consumers convenience and easy access to a vast array of products. Online shopping platforms, including Taobao, JD.com, and Tmall, have become essential for reaching a broader audience and providing a personalized shopping experience. The convergence of fashion and technology allows consumers to discover, review, and purchase the latest trends with just a few clicks, further driving demand for apparel.For instance, platforms like Douyin and Xiaohongshu have become crucial for fashion brands in China, allowing them to engage with consumers and influence purchasing decisions through interactive content and influencer collaborations. The widespread use of e-commerce platforms like Taobao and JD.com has also transformed the way consumers shop for apparel, offering convenience and access to a wide range of products.
Rising Demand for Sustainable and Eco-Friendly Fashion
As sustainability becomes a global concern, the demand for eco-friendly and sustainable fashion is rapidly growing in China. Consumers are increasingly aware of the environmental impact of the fashion industry and are showing a preference for brands that focus on sustainable sourcing, ethical production practices, and environmentally friendly materials. This shift in consumer values is driving brands to adopt more sustainable practices, such as using organic fabrics, reducing waste, and utilizing environmentally friendly production techniques. Chinese women, particularly younger generations, are more inclined to support brands that align with their values regarding sustainability and environmental responsibility. In response to this growing demand, several domestic and international apparel brands are introducing sustainable fashion lines and promoting transparency in their supply chains. As a result, the rise in consumer demand for eco-friendly fashion is reshaping the women’s apparel market in China and driving growth in this segment.For example, brands like Icicle and Klee Klee are leading the way in sustainable fashion in China by using eco-friendly materials and promoting transparent supply chains. This shift toward sustainability is driven by younger consumers who are increasingly environmentally conscious and willing to support brands that align with their values regarding sustainability and environmental responsibility.
Market Trends
Shift Toward Online Shopping and E-commerce Integration
One of the most prominent trends in the China Women Apparel Market is the rapid shift toward online shopping and the increasing reliance on e-commerce platforms. With the rise of internet penetration and smartphone usage across China, consumers are becoming more comfortable purchasing apparel online. E-commerce platforms such as Taobao, Tmall, JD.com, and Pinduoduo have emerged as key players in this retail transformation, enabling consumers to shop conveniently from their homes. Online shopping offers several advantages, including a wider variety of products, the ability to compare prices, and access to exclusive online discounts. Social commerce, where products are marketed and sold via social media platforms like WeChat, Douyin (TikTok), and Weibo, has further accelerated this trend. The integration of live-streaming with e-commerce, a popular feature in China, allows consumers to view real-time product demonstrations, interact with influencers, and purchase items directly through live broadcasts. This seamless combination of social interaction, entertainment, and shopping has drastically transformed how apparel is sold, making it a crucial trend in the market. The convenience of online shopping, along with the ability to browse an expansive range of styles and the ease of product discovery, continues to draw more women to make apparel purchases through digital channels.
Sustainability and Ethical Fashion
In response to growing global concerns over environmental sustainability, the demand for eco-friendly and ethically produced apparel is rising in China. Chinese consumers, particularly among the younger demographic, are becoming increasingly conscious of the environmental impact of their purchasing decisions. This awareness has led to a shift toward sustainable fashion, where consumers are choosing clothing made from organic, recycled, or upcycled materials. Fashion brands are responding to this demand by adopting environmentally friendly manufacturing processes, such as using water-saving techniques, reducing carbon emissions, and minimizing waste. Additionally, transparency in supply chains is becoming more important, with brands being held accountable for the environmental and social impacts of their operations. Ethical fashion, which includes fair labor practices and ensuring that workers are paid a living wage, is also gaining traction among Chinese consumers. This movement is not just about adopting eco-friendly materials but also about shifting to slow fashion, which emphasizes quality over quantity and aims to reduce the fast fashion cycle. Several international and local brands are already focusing on sustainability, with Chinese consumers showing an increasing preference for those that incorporate sustainable practices in their business models. The rise of sustainable fashion is a critical trend that is expected to grow in the coming years as environmental awareness continues to influence consumer choices.
Influence of Western and Global Fashion Trends
The China Women Apparel Market is heavily influenced by Western and global fashion trends, as Chinese consumers increasingly look to international brands and designers for inspiration. This trend has been accelerated by the rise of social media platforms, where global fashion trends are quickly disseminated and adopted by Chinese consumers. International fashion houses like Zara, H&M, Uniqlo, and luxury brands such as Gucci, Prada, and Louis Vuitton have become highly popular in China. Their ability to provide the latest international fashion styles has made them key players in shaping the apparel market. Furthermore, the growing affluence of Chinese consumers, particularly among the younger generation, has resulted in a desire for global luxury and premium brands. Consumers in China are no longer confined to domestic fashion trends but are instead looking at global fashion capitals such as New York, Paris, and Milan for inspiration. This cross-cultural influence is evident in the rise of fashion collaborations, where Chinese designers are partnering with international brands to create exclusive collections that blend Western and Chinese aesthetics. Additionally, Western cultural trends, such as streetwear, athleisure, and minimalism, have gained substantial popularity in China. As consumers in China continue to seek the latest global trends, international and domestic apparel brands are adapting their strategies to cater to this fashion-forward market.
Personalization and Customization of Apparel
Personalization and customization are increasingly becoming significant trends in the China Women Apparel Market. Chinese consumers, especially younger generations, are seeking clothing that allows them to express their individuality. This has led to the rise of personalized fashion, where consumers can tailor their apparel to their specific preferences. Customization can range from selecting different colors, fabrics, and patterns to creating one-of-a-kind pieces that are made to order. Many brands now offer "design-your-own" options, where consumers can choose from a variety of styles, prints, and materials to create unique garments. This trend is fueled by the increasing demand for exclusivity and a desire to stand out from the crowd. In addition, the use of advanced technology, such as 3D printing, has enabled brands to offer bespoke products at more affordable prices. Personalization is also being incorporated into the shopping experience, with many online platforms offering personalized recommendations based on a consumer’s browsing history and preferences. The growing trend of customization is not only changing the way consumers shop but also influencing the apparel market to move toward more unique, tailored clothing options. As technology continues to evolve, the potential for customization and personalization in the women’s apparel sector in China is likely to expand further, catering to the increasing demand for individuality.
Market Challenges
Intense Competition and Price Sensitivity
One of the primary challenges facing the China Women Apparel Market is the intense competition among both domestic and international brands. The market is saturated with a wide variety of clothing options across multiple price points, from budget-friendly fast fashion to premium and luxury apparel. This intense competition creates a pricing pressure that forces many brands to constantly adjust their pricing strategies in order to maintain market share. Price sensitivity among Chinese consumers, especially in lower-tier cities, further intensifies this challenge. Consumers are often looking for high-quality products at competitive prices, making it difficult for brands to balance cost-efficiency and product quality. Fast fashion giants like Zara, H&M, and local players such as Uniqlo dominate the market with their frequent product launches and affordable pricing. Moreover, e-commerce platforms have further complicated the competitive landscape by providing an easy platform for new entrants to disrupt the market with lower-priced products. As a result, established brands must continually innovate and differentiate themselves through quality, design, and customer experience, which demands significant investment in branding and marketing efforts.
Supply Chain Disruptions and Sustainability Pressures
Another significant challenge for the China Women Apparel Market is the vulnerability of the supply chain to disruptions. Global supply chain issues, exacerbated by the COVID-19 pandemic, have highlighted the fragility of production and distribution networks. Apparel brands often rely on a complex network of manufacturers, suppliers, and logistics providers, and disruptions in any part of this chain can lead to delays, increased costs, and inventory shortages. Furthermore, the increasing pressure on brands to adopt sustainable practices adds an additional layer of complexity. While consumers are becoming more concerned about the environmental impact of their purchases, the implementation of sustainable production methods and materials often comes at a higher cost. Brands are under pressure to reduce their carbon footprints and ensure ethical sourcing, all while maintaining profitability and meeting fast fashion demands. Balancing sustainability with supply chain efficiency remains a major challenge for many players in the Chinese women’s apparel market.
Market Opportunities
Expansion of Online and Omnichannel Retailing
The continued growth of e-commerce presents a significant opportunity for brands in the China Women Apparel Market. With the increasing adoption of digital platforms for shopping, there is a substantial opportunity to capitalize on online retailing. The popularity of online platforms like Taobao, Tmall, and JD.com, as well as social media-driven shopping experiences, allows brands to reach a broader consumer base. Omnichannel strategies that integrate online and offline shopping experiences are also gaining traction, as consumers seek flexibility and convenience in their shopping habits. By offering seamless transitions between physical stores and digital platforms, brands can enhance customer engagement, improve sales conversion rates, and capture the growing number of tech-savvy shoppers. The rise of live-streaming commerce and influencer-driven marketing also presents an opportunity to build brand awareness and directly engage with consumers, especially among younger demographics. Brands that strategically invest in digital marketing and e-commerce technologies can gain a competitive edge in the expanding online retail landscape.
Rising Demand for Sustainable and Premium Fashion
The increasing focus on sustainability and ethical production practices provides a strong market opportunity for brands in the China Women Apparel Market. As Chinese consumers become more environmentally conscious, there is a growing demand for sustainable, eco-friendly, and ethically produced clothing. This shift is particularly prominent among younger, urban consumers who prioritize eco-conscious choices in their purchasing decisions. Brands that adopt green practices, such as using organic materials, reducing waste, and ensuring fair labor conditions, can differentiate themselves in a crowded market. Additionally, the growing affluence of the middle class has led to a rise in demand for premium and luxury apparel. Brands that offer high-quality, durable, and unique products catering to these evolving preferences can tap into the expanding market for sustainable and premium fashion.
Market Segmentation Analysis
By Type
The China Women Apparel Market is segmented into casual wear, formal wear, sportswear, nightwear, and innerwear. Casual wear holds the largest share, accounting for around 50% of the market, driven by increasing consumer preference for comfortable, everyday clothing. Formal wear maintains steady demand, particularly in corporate and professional settings, where tailored clothing and business attire remain essential. Sportswear is experiencing significant growth, supported by the rise of athleisure trends and an increasing focus on fitness and wellness. Nightwear is gaining traction due to growing demand for comfort-oriented sleepwear, particularly in urban areas. Innerwear continues to see strong sales, with innovations in fabric technology and the growing influence of fashion-forward lingerie driving consumer interest.
By Application
The market is segmented into mass, premium, and luxury categories. The mass segment dominates, fueled by widespread consumer demand for affordable and stylish clothing. The premium segment is growing steadily as middle-class consumers seek higher-quality apparel with better materials and design. The luxury segment, while niche, is expanding as affluent Chinese consumers increasingly invest in high-end fashion brands. The rising influence of international luxury brands and growing disposable income among younger consumers contribute to the segment’s growth.
Segments
Based on Type
- Casual Wear
- Formal Wear
- Sportswear
- Night Wear
- Inner Wear
Based on Application
- Mass
- Premium
- Luxury
Based on Age group
- 5-16 years
- 16-45 years
- 45-70 years
- 70 and above
Based on Distribution Channel
- Offline
- Online
Based on Region
- Beijing
- Shanghai
- Guangzhou
- Shenzhen
Regional Analysis
East China (40%)
East China is the leading region in the women’s apparel market, contributing approximately 40% of the overall market share. This region includes major cities like Shanghai, Hangzhou, and Nanjing, which are recognized as fashion hubs of China. Shanghai, in particular, is home to a large population of affluent consumers with a high demand for both domestic and international fashion brands. The region's robust economic development, high urbanization rates, and exposure to global trends have led to a significant increase in the demand for trendy and premium apparel. Moreover, East China is highly developed in terms of retail infrastructure, with numerous shopping malls, department stores, and e-commerce platforms offering convenient shopping experiences for women.
South China (30%)
South China, with a market share of around 30%, includes major cities like Guangzhou, Shenzhen, and Hong Kong. This region is known for its fashion-forward consumer base, particularly in cities such as Guangzhou, which is a key player in the textile and garment industry. The growing middle class in South China, coupled with the rising influence of online shopping, has contributed to the region’s rapid growth in the apparel sector. In addition, the proximity to international markets like Hong Kong and the extensive retail networks across South China play a crucial role in shaping fashion consumption trends, with many international brands catering to this region’s discerning consumers.
Key players
- Giorgio Armani S.p.A
- Manolo Blahnik
- Dior
- Louis Vuitton
- Burberry
- Dolce & Gabbana S.R.L
- Prada
- Guccio Gucci S.p.A
- Chanel
- Gianni Versace S.r.l
- Hongyu Apparel
- Shingrand Hats
Competitive Analysis
The China Women Apparel Market is highly competitive, with both international luxury brands and domestic players vying for market share. Luxury brands such as Giorgio Armani, Dior, Louis Vuitton, and Gucci maintain a strong presence, driven by their established reputation and affluent consumer base. These brands cater to high-income consumers seeking premium and exclusive fashion items. Domestic players like Hongyu Apparel and Shingrand Hats have carved a niche in the market by offering tailored, locally-inspired apparel while capitalizing on regional preferences. Additionally, emerging fashion brands are increasingly focusing on e-commerce and social media strategies to target the younger, tech-savvy demographic. Competitive strategies include brand positioning through sustainability, exclusive collections, and leveraging online platforms. The market's dynamic nature requires brands to continuously innovate in design, product offerings, and customer experience to stay ahead of competitors and cater to evolving consumer demands.
Recent Developments
In June 2024, Giorgio Armani celebrated more than a decade in China with a "One Night Only in Beijing" event, highlighting the brand's commitment to the Chinese market.Market Concentration and Characteristics
The China Women Apparel Market is characterized by a high level of competition and a mix of both domestic and international players. Market concentration is moderate, with a few large companies such as Zara, H&M, Uniqlo, and local brands like Anta and Li Ning dominating a significant portion of the market. These players have established a strong retail presence through both offline stores and e-commerce platforms. However, the market also includes a large number of smaller, emerging brands that cater to niche segments, such as sustainable fashion or premium apparel. Consumer preferences are increasingly driven by trends in fast fashion, with a growing demand for both stylish, affordable options and high-quality, sustainable products. The market is also marked by the growing importance of online shopping, digital marketing, and social commerce, as more consumers turn to e-commerce platforms for convenience and variety. This competitive and dynamic environment makes the China Women Apparel Market both highly fragmented and rapidly evolving.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Age group, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The shift towards online shopping will continue to accelerate, driven by convenience, digital platforms, and the increasing use of mobile commerce. E-commerce giants like Tmall and JD.com will play a crucial role in expanding market access.
- As environmental concerns grow, the demand for sustainable and ethically produced apparel will increase, prompting brands to adopt greener production methods. Consumers will increasingly prioritize eco-friendly and sustainable options.
- The expansion of retail networks in second- and third-tier cities will open new opportunities as urbanization and disposable incomes rise. These regions are expected to see significant growth in fashion consumption.
- Social media platforms and live-streaming commerce will continue to shape consumer behavior, particularly among younger demographics. Influencer marketing will remain a powerful tool for brand promotion.
- Consumers will seek more personalized and customized clothing, with brands offering unique designs and tailored options. Technology advancements in 3D printing and virtual try-ons will further enhance this trend.
- As disposable incomes rise, there will be a greater demand for premium and luxury apparel, particularly among younger, affluent consumers. International and local luxury brands will continue to expand their presence.
- Athleisure will continue to thrive as Chinese consumers increasingly prioritize fitness and wellness. Sportswear, particularly casual and stylish athletic wear, will dominate both everyday fashion and fitness routines.
- Augmented reality (AR) and virtual reality (VR) will revolutionize the shopping experience, offering customers virtual fitting rooms and interactive product displays. These technologies will enhance customer engagement and sales conversion.
- The integration of online and offline shopping experiences will grow, offering consumers seamless transitions between physical stores and e-commerce platforms. Omnichannel retail strategies will become essential for brands to meet evolving consumer expectations.
- Post-pandemic, the demand for comfortable, functional, and health-focused clothing will rise. Brands will invest in innovative fabrics and designs that prioritize comfort without compromising style.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Income and Expanding Middle Class
China's rapid economic growth has led to higher disposable incomes, especially in urban areas, enabling more women to purchase both affordable and premium apparel. The expanding middle class is increasingly fashion-conscious, fueling demand for a wider variety of clothing styles and brands.
Urbanization and Lifestyle Changes
The migration of populations to urban centers like Beijing, Shanghai, and Guangzhou has created concentrated markets of fashion-forward consumers. Urban lifestyles, dual-income households, and increased workforce participation among women are driving demand for versatile, stylish, and functional apparel.
Digitalization, E-commerce, and Social Media Influence
The proliferation of e-commerce platforms and social media channels such as WeChat, Douyin, and Tmall has transformed how women discover, evaluate, and purchase apparel. Brands leverage digital marketing, influencer collaborations, and live-streaming to engage consumers and boost online sales.
Growing Preference for Sustainable and Eco-Friendly Fashion
Environmental awareness is rising among Chinese consumers, particularly younger generations, leading to increased demand for sustainable, ethically produced clothing. Brands adopting eco-friendly materials and transparent supply chains are gaining market share as consumers prioritize responsible fashion choices.
Influence of Global Fashion Trends and International Brands
Exposure to Western and global fashion trends through social media and international travel has heightened Chinese consumers' appetite for the latest styles. International brands and luxury labels are expanding their presence, catering to the demand for premium and globally inspired apparel.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the China Women Apparel Market in 2023 and 2032?
What factors are driving the growth of the China Women Apparel Market?
How is online shopping influencing the China Women Apparel Market?
What role does sustainability play in the China Women Apparel Market?
Which regions dominate the China Women Apparel Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Casual Wear
- 1.2.2 Formal Wear
- 1.2.3 Sportswear
- 1.2.4 Night Wear
- 1.2.5 Inner Wear
- 1.3 By Age Group
- 1.3.1 5-16 years
- 1.3.2 16-45 years
- 1.3.3 45-70 years
- 1.3.4 70 and above
- 1.4 By Application
- 1.4.1 Mass
- 1.4.2 Premium
- 1.4.3 Luxury
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 121,459.07 million → 2032: USD 190,285.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Women Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Women Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Women Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Women Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Women Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Women Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Women Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Women Apparel Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 121,459.07 million → 2032: USD 190,285.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Women Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Casual Wear
- 12.3.7.2 Formal Wear
- 12.3.7.3 Sportswear
- 12.3.7.4 Night Wear
- 12.3.7.5 Inner Wear
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 5-16 years
- 12.4.7.2 16-45 years
- 12.4.7.3 45-70 years
- 12.4.7.4 70 and above
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mass
- 12.5.7.2 Premium
- 12.5.7.3 Luxury
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 China Women Apparel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 China Women Apparel Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 China Women Apparel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 China Women Apparel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Anta
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Li Ning
- 18.4 Zara
- 18.5 H&M
- 18.6 Uniqlo
- 18.7 Giorgio Armani
- 18.8 Dior
- 18.9 Louis Vuitton
- 18.10 Hongyu Apparel
- 18.11 Shingrand Hats
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

