
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| China Single-Use Bio-Processing Systems Market Size 2024 | USD 2,145.03 million |
| China Single-Use Bio-Processing Systems Market, CGR | 18.36% |
| China Single-Use Bio-Processing Systems Market Size 2032 | USD 8,263.99 million |
Market Overview
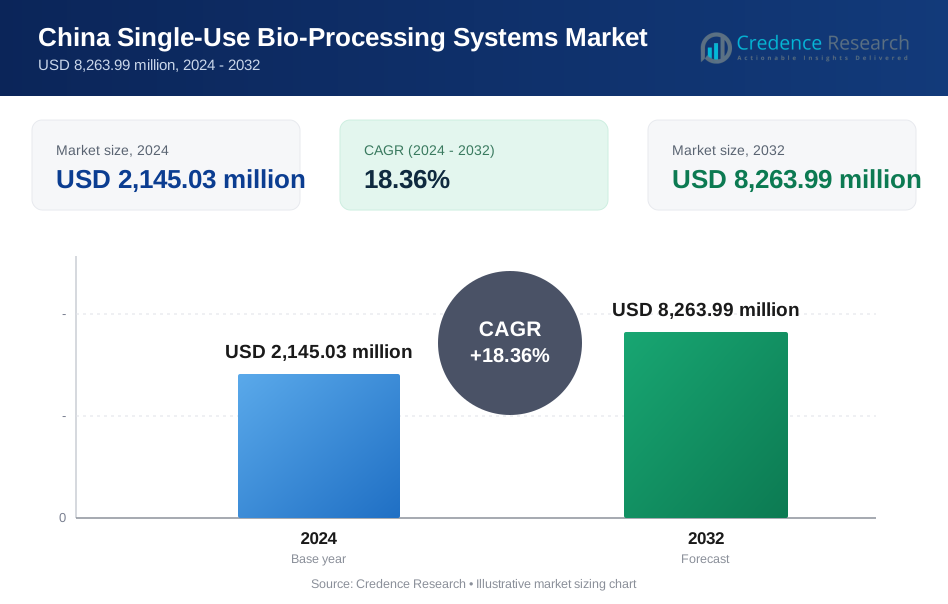
China Single-Use Bio-Processing Systems market size was valued at USD 2,145.03 million in 2024 and is anticipated to reach USD 8,263.99 million by 2032, at a CAGR of 18.36% during the forecast period (2024-2032).
The China Single-Use Bio-Processing Systems market is driven by the rapid expansion of the biopharmaceutical industry, increasing demand for cost-effective and flexible manufacturing solutions, and the need to minimize contamination risks in biologics production. The shift toward personalized medicine and the growing pipeline of biologics and biosimilars further accelerate the adoption of single-use technologies. Additionally, favorable government policies supporting biomanufacturing innovation and rising investments from both domestic and international players are fostering market growth. Trends such as the integration of automation and digital monitoring in bio-processing systems, along with advancements in material science to enhance product performance and sustainability, are shaping the future of the industry. The increasing focus on reducing operational complexity, improving scalability, and ensuring regulatory compliance also contributes to the growing preference for single-use systems across research and commercial-scale production. These factors collectively position China as a significant player in the global single-use bio-processing landscape.
The geographical landscape of the China Single-Use Bio-Processing Systems market is characterized by strong growth across major cities such as Beijing, Shanghai, Guangzhou, and Shenzhen, where biopharmaceutical innovation and manufacturing infrastructure are rapidly evolving. These urban hubs serve as focal points for research, development, and large-scale production activities due to favorable government policies, technological advancements, and access to skilled talent. The market is highly competitive, with prominent players including Wuxi AppTec, Cytiva, Thermo Fisher Scientific Asia, Merck Life Science, and Danaher Asia-Pacific driving innovation and product development. These companies are actively investing in R&D, expanding production capabilities, and forming strategic alliances to address increasing demand for cost-effective and scalable solutions. Additionally, regional firms like Shanghai Bailun Biotechnology and institutions such as Tsinghua University Suzhou Institute for Biomedicine contribute to localized advancements, further solidifying China's position as a key player in the global single-use bio-processing landscape.
Market Insights
- The China Single-Use Bio-Processing Systems market was valued at USD 2,145.03 million in 2024 and is projected to reach USD 8,263.99 million by 2032, growing at a CAGR of 18.36% from 2024 to 2032.
- The global single-use bio-processing systems market was valued at USD 17,326.05 million in 2024 and is projected to reach USD 57,663.39 million by 2032, growing at a CAGR of 16.22% from 2024 to 2032.
- Growing adoption of disposable technologies in biopharmaceutical manufacturing is driving market expansion, as single-use systems offer cost-effective, scalable, and contamination-free solutions.
- The increasing demand for personalized medicine and biologics, particularly monoclonal antibodies, is pushing for more efficient bioprocessing solutions.
- Trends such as the integration of automation and real-time monitoring in single-use systems are enhancing operational efficiency and product quality.
- Market restraints include concerns about leachables and extractables, which can affect the purity and safety of biologic products.
- Regional hubs like Beijing, Shanghai, Guangzhou, and Shenzhen are key drivers of market growth due to robust research, manufacturing, and regulatory support.
- Key players in the market include Wuxi AppTec, Thermo Fisher Scientific, Cytiva, and Merck Life Science, focusing on product innovation and market expansion.
Report Scope
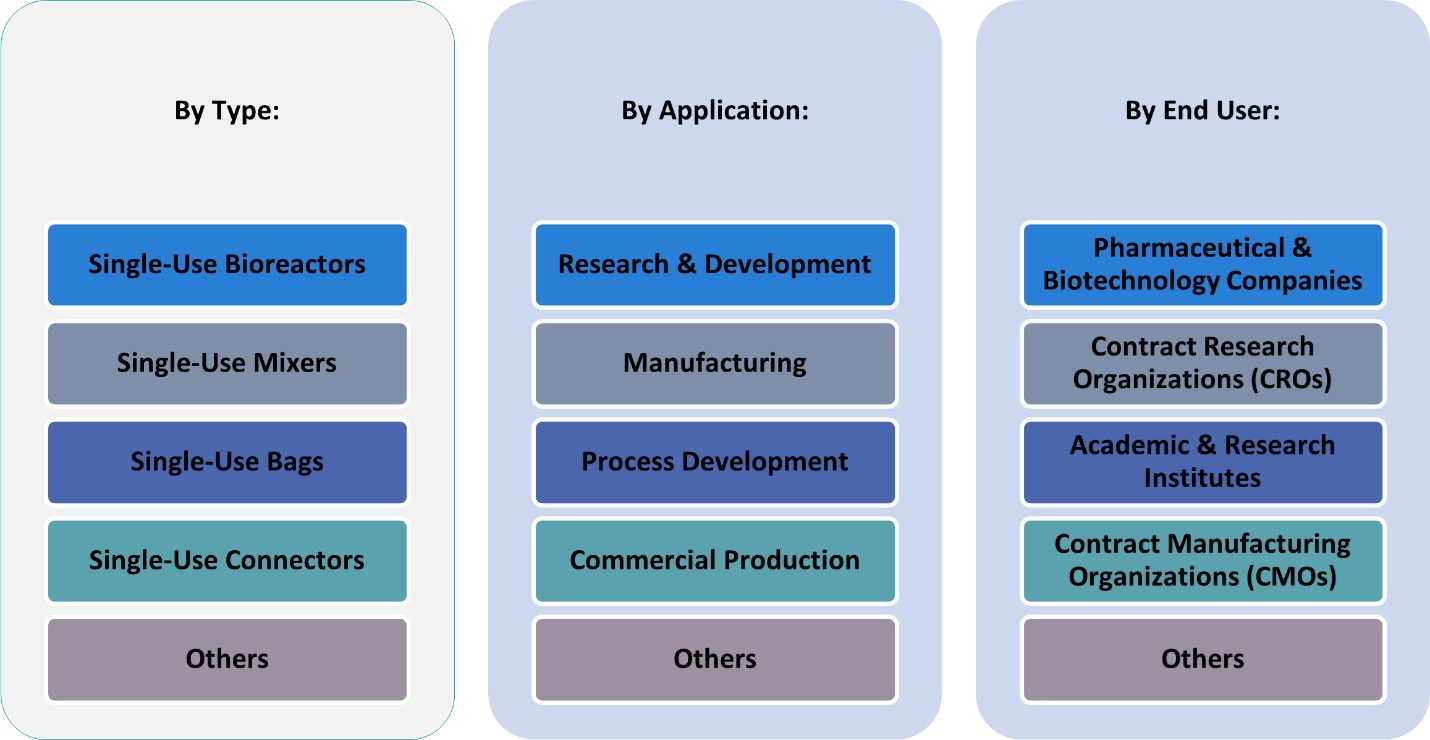
This report segments the China Single-Use Bio-Processing Systems Market as follows:
Market Drivers
Rapid Growth of the Biopharmaceutical Industry
China's expanding biopharmaceutical sector is a primary driver for the adoption of single-use bio-processing systems. Government initiatives aimed at strengthening the pharmaceutical industry have led to increased investments in biologics manufacturing. For instance, policies under the "Made in China 2025" strategy have encouraged local production of monoclonal antibodies and cell and gene therapies, reducing reliance on imports. This growth necessitates scalable, cost-efficient, and contamination-free processing solutions, making single-use systems an ideal choice. Moreover, the domestic biopharma landscape is shifting from traditional drug manufacturing to advanced therapies, including monoclonal antibodies and cell and gene therapies, which align well with the benefits offered by disposable technologies. As Chinese pharmaceutical companies aim to meet both domestic and international regulatory standards, the demand for high-quality, GMP-compliant single-use systems continues to rise.
Cost Efficiency and Operational Flexibility
One of the key advantages of single-use bio-processing systems is their ability to significantly reduce capital expenditure and operating costs. Government-backed funding programs have encouraged biotech firms to adopt cost-effective production methods. For instance, national research agencies have introduced grants to support the transition from traditional stainless-steel bioreactors to single-use technologies. In contrast, single-use technologies eliminate the need for cleaning and sterilization, thereby reducing labor costs, minimizing cross-contamination risks, and shortening batch changeover times. This is particularly valuable for contract development and manufacturing organizations (CDMOs) and smaller biotech firms that prioritize speed and agility. The reduced infrastructure requirements also allow companies to build modular, flexible facilities, which are essential for responding quickly to market demands and innovation cycles.
Supportive Regulatory Environment and Government Initiatives
The Chinese government has implemented a range of policies to stimulate innovation and self-sufficiency in the life sciences sector, which positively impacts the adoption of single-use systems. Initiatives such as “Made in China 2025” and increased funding for high-tech biopharmaceutical projects have encouraged both local and global players to invest in bioprocessing infrastructure within China. Regulatory reforms aimed at accelerating drug approvals and encouraging clinical trials have further spurred demand for efficient and compliant manufacturing systems. Additionally, as China aims to strengthen its global competitiveness in biologics manufacturing, regulatory authorities are emphasizing quality standards that align with international norms, indirectly promoting the use of validated, standardized single-use technologies.
Technological Advancements and Innovation Adoption
Ongoing innovations in materials, sensor integration, and automation have greatly enhanced the functionality and appeal of single-use bio-processing systems. Modern disposable systems now incorporate real-time monitoring, advanced control mechanisms, and data analytics capabilities, enabling smarter and more efficient manufacturing. These advancements improve product consistency and process reproducibility, which are critical for regulatory compliance and large-scale production. Furthermore, rising awareness of environmental sustainability has driven manufacturers to develop eco-friendly, recyclable single-use components. As China's biotechnology firms increasingly adopt Industry 4.0 practices, the integration of intelligent single-use systems becomes a strategic enabler of competitive differentiation and operational excellence across research, clinical, and commercial manufacturing stages.
Market Trends
Accelerated Adoption Across Clinical and Commercial Manufacturing
China is witnessing a significant trend toward the accelerated adoption of single-use bio-processing systems across both clinical trial production and large-scale commercial manufacturing. As biotech companies strive to bring biologics to market more quickly, single-use systems offer a compelling solution by reducing setup times and improving manufacturing agility. The flexibility of these systems allows manufacturers to easily scale production from pilot to commercial levels without extensive infrastructure changes. This scalability is particularly relevant in the Chinese context, where a surge in start-ups and innovation-driven enterprises are fueling the need for modular and responsive production capabilities.
Expansion of Local Manufacturing Capabilities
Another notable trend is the rise in local manufacturing and domestic production of single-use systems and components. For instance, Merck has invested approximately €100 million to expand its single-use manufacturing center in Wuxi, China, strengthening local production capabilities. While global suppliers continue to play a major role in the Chinese market, local companies are increasingly entering the value chain by producing bags, connectors, and tubing tailored to regional standards and pricing structures. This trend helps reduce reliance on imports, lowers lead times, and enhances supply chain resilience. Furthermore, collaborations between domestic players and multinational corporations are fostering knowledge exchange and driving the localization of advanced technologies. As a result, China is becoming not only a major consumer but also an emerging producer of single-use bio-processing technologies.
Sustainability and Regulatory Compliance Focus
Environmental sustainability is becoming a growing concern in the single-use bio-processing sector. With increasing scrutiny on waste management and lifecycle impacts, manufacturers are investing in the development of recyclable or biodegradable materials to align with China’s green manufacturing policies. For instance, environmental agencies in China have introduced policies supporting the use of recyclable materials in single-use systems. Additionally, regulatory compliance remains a key trend, as companies prioritize systems that meet stringent international standards such as cGMP, FDA, and EMA guidelines. This dual focus on sustainability and compliance is prompting innovation in product design and materials, while also encouraging firms to adopt best practices in quality assurance and risk mitigation, ensuring long-term market viability.
Integration of Automation and Smart Manufacturing
The integration of automation and smart technologies into single-use systems is reshaping China's bio-processing landscape. Manufacturers are increasingly deploying systems with built-in sensors, data analytics, and remote monitoring capabilities to improve process control, reduce human error, and optimize operational efficiency. This trend aligns with China's broader push toward digital transformation and smart manufacturing under initiatives like “China Manufacturing 2025.” As a result, biopharma firms are adopting automated single-use platforms that support continuous processing and real-time quality assurance, paving the way for more consistent and compliant production processes.
Market Challenges Analysis
Regulatory Uncertainty and Standardization Gaps
Despite growing adoption, regulatory uncertainty and the lack of standardized guidelines for single-use bio-processing systems in China present significant challenges. For instance, the National Medical Products Administration (NMPA) has been working to align China’s regulatory framework with International Council for Harmonisation (ICH) guidelines. While the government is promoting the biopharmaceutical industry, regulatory bodies have yet to fully establish comprehensive, harmonized standards specifically tailored to single-use technologies. This creates ambiguity for manufacturers and end-users regarding validation, quality control, and compliance expectations. Additionally, inconsistencies between domestic and international regulatory frameworks can hinder the approval and export of biologics manufactured using single-use systems. Companies are often forced to overcompensate with redundant testing and documentation to satisfy various authorities, thereby increasing time-to-market and operational costs.
Supply Chain Constraints and Technical Limitations
China faces supply chain limitations that affect the availability and scalability of single-use components such as bioreactor bags, filters, and connectors, many of which are still sourced from international suppliers. This dependence exposes manufacturers to risks such as import delays, price volatility, and geopolitical tensions. While local production is growing, domestic capabilities are not yet sufficient to meet high-performance standards across all product categories. Furthermore, technical limitations such as concerns over leachables and extractables, material compatibility, and single-use equipment durability continue to challenge widespread implementation, especially in high-volume or long-duration processes. These factors can hinder confidence among manufacturers and slow down adoption, particularly for complex biologic products that demand stringent and consistent process conditions.
Market Opportunities
The China Single-Use Bio-Processing Systems market presents substantial opportunities, driven by the country’s rapidly advancing biopharmaceutical sector and the increasing shift toward biologics and personalized medicine. As more Chinese biotech and pharmaceutical companies expand their biologics pipelines, demand for flexible, efficient, and contamination-resistant manufacturing solutions is accelerating. Single-use systems offer a scalable and cost-effective alternative to traditional stainless-steel setups, making them especially attractive for start-ups and contract development and manufacturing organizations (CDMOs) seeking to reduce capital expenditures and streamline production timelines. Additionally, the growing focus on decentralized manufacturing models and modular facility design aligns with the versatility of single-use technologies, offering new avenues for implementation across preclinical, clinical, and commercial stages of drug development.
Foreign and domestic suppliers have significant opportunities to invest in localized production, customization, and technical services to support China's evolving regulatory and manufacturing environment. As regulatory frameworks mature and begin to align more closely with international standards, there will be increased potential for companies to offer certified, GMP-compliant single-use systems tailored for Chinese market needs. Moreover, the integration of automation, real-time monitoring, and advanced analytics into single-use platforms presents a valuable opportunity to enhance process control and product quality. Environmental sustainability is also gaining importance, encouraging innovation in recyclable materials and waste reduction strategies. With supportive government policies, growing investment in biomanufacturing infrastructure, and increased collaboration between academic, clinical, and industrial sectors, China is poised to become not only a leading consumer but also a global innovator in single-use bio-processing technologies.
Market Segmentation Analysis:
By Type:
The Chinese market for single-use bio-processing systems is segmented into single-use bioreactors, single-use mixers, single-use bags, single-use connectors, and other components. Among these, single-use bioreactors hold the largest market share, driven by their widespread use in upstream processing for biologics production. Their ability to reduce contamination risks and simplify process validation makes them highly attractive for both research and commercial applications. Single-use bags, used for media storage, transport, and cell culture, are also witnessing strong demand due to their versatility and cost-efficiency. Single-use mixers are increasingly adopted in formulation and buffer preparation processes, particularly in modular facilities. Connectors and tubing systems play a critical role in maintaining closed system operations, ensuring sterility, and enabling flexible process integration. The "Others" category, which includes filters, sensors, and tubing assemblies, is also growing steadily as companies seek complete disposable solutions. Overall, advancements in materials, increased local production, and demand for contamination control continue to drive growth across all product segments.
By Application:
Based on application, the market is categorized into research & development, manufacturing, process development, commercial production, and others. Research & development accounts for a substantial portion of adoption, particularly within academic institutions, start-ups, and clinical research organizations, where flexibility and cost-effectiveness are paramount. Process development is another rapidly growing segment, as companies increasingly use single-use systems to accelerate scale-up and optimize biologic formulations. However, commercial production is poised for the most significant expansion, driven by increased approval of biologics and biosimilars in China and the need for scalable GMP-compliant manufacturing solutions. Manufacturing applications benefit from reduced downtime and lower operational costs, especially in multi-product facilities. The "Others" segment includes quality testing and pilot-scale operations, which are also adopting disposable systems to streamline operations. The shift toward integrated, end-to-end single-use platforms reflects a broader trend in the Chinese life sciences industry toward efficiency, agility, and global regulatory alignment.
Segments:
Based on Type:
- Single-Use Bioreactors
- Single-Use Mixers
- Single-Use Bags
- Single-Use Connectors
- Others
Based on Application:
- Research & Development
- Manufacturing
- Process Development
- Commercial Production
- Others
Based on End- User:
- Pharmaceutical & Biotechnology Companies
- Contract Research Organizations (CROs)
- Academic & Research Institutes
- Contract Manufacturing Organizations (CMOs)
- Others
Based on the Geography:
- Beijing
- Shanghai
- Guangzhou
- Shenzhen
Regional Analysis
Beijing
Beijing holds the largest market share of approximately 32% in China’s single-use bio-processing systems market. As the country’s political and academic hub, Beijing is home to numerous national research institutes, top-tier universities, and leading biopharmaceutical companies. The region has benefitted from strong government backing and robust public-private investment in life sciences infrastructure. Single-use systems are widely implemented in Beijing's state-sponsored biologics research and clinical trial centers, especially for monoclonal antibody development, vaccine research, and personalized medicine. The growing number of biotechnology incubators and collaborations with global pharmaceutical firms further boosts demand for flexible, scalable processing systems in the region. With its highly skilled workforce and close ties to regulatory agencies, Beijing continues to set the standard for innovation and quality in bio-processing practices across China.
Shanghai
Shanghai commands an estimated market share of 28%, ranking as the second-largest regional market. As a major commercial and financial center, Shanghai has attracted substantial foreign direct investment and multinational pharmaceutical companies. The city hosts several biopharma parks and free trade zones that encourage high-tech manufacturing, including contract development and manufacturing organizations (CDMOs) and clinical research organizations (CROs). Single-use systems are widely adopted in Shanghai’s rapidly growing commercial production and process development sectors due to their time and cost efficiencies. Furthermore, the city’s focus on international regulatory compliance and quality control drives demand for high-performance, validated disposable technologies. The presence of international suppliers and advanced logistics infrastructure makes Shanghai a vital hub for both domestic distribution and export-oriented bio-manufacturing activities.
Guangzhou
Guangzhou represents around 20% of the market share, driven by its strong pharmaceutical manufacturing base and supportive provincial policies. The city has been actively developing its biotech sector under the Guangdong-Hong Kong-Macao Greater Bay Area initiative, attracting both domestic start-ups and global partnerships. Single-use systems are increasingly adopted in Guangzhou’s mid-sized biopharmaceutical firms, particularly in vaccine and biosimilar production. The region also emphasizes process development and pilot-scale manufacturing, where single-use systems offer a competitive edge by minimizing contamination risk and accelerating turnaround times. With rising investment in R&D parks and government-backed innovation hubs, Guangzhou continues to gain ground as a key contributor to China’s overall bio-processing ecosystem.
Shenzhen
Shenzhen accounts for approximately 15% of the national market share, emerging as a fast-growing player in China’s life sciences landscape. Known for its innovation-driven economy and high-tech manufacturing capabilities, Shenzhen has seen a surge in biotech start-ups, particularly those focused on cell and gene therapies. The city’s agile manufacturing environment favors single-use technologies due to their modular design, fast deployment, and suitability for small-batch, high-value production. Additionally, Shenzhen’s integration of digital health and smart factory concepts supports the adoption of automated, sensor-enabled single-use systems. While still developing compared to Beijing and Shanghai, Shenzhen’s rapid growth and forward-looking industrial policies position it as a promising market for future expansion.
Key Player Analysis
- Wuxi AppTec
- Shanghai Bailun Biotechnology Co., Ltd.
- Tsinghua University Suzhou Institute for Biomedicine
- FUJIFILM Irvine Scientific
- Cytiva
- Hitachi Chemical Co., Ltd.
- Mitsubishi Gas Chemical Company, Inc.
- Merck Life Science
- Thermo Fisher Scientific Asia
- Danaher Asia-Pacific
Competitive Analysis
The competitive landscape of the China Single-Use Bio-Processing Systems market is dominated by several key players that lead in innovation, market share, and global reach. Wuxi AppTec, Cytiva, Thermo Fisher Scientific, Merck Life Science, and Danaher Asia-Pacific are the primary companies shaping the market through extensive product portfolios and strategic expansions. These players have a strong presence in China, supported by their local manufacturing capabilities, R&D investments, and partnerships with biopharma companies. Companies in this space are focusing on developing advanced, cost-effective solutions to meet the increasing demand for biopharmaceutical manufacturing, particularly in the production of biologics, vaccines, and monoclonal antibodies. Key factors driving competition include product differentiation, such as offering customizable, scalable, and contamination-free systems, along with the integration of automation, real-time monitoring, and digital solutions to enhance process efficiency. Competitive players are also expanding their manufacturing capabilities and forming strategic alliances with regional players and global biopharmaceutical companies to improve service delivery and market penetration. While established players maintain a stronghold in the market, new entrants are also emerging, focusing on niche markets and specific bioprocessing needs. As the market matures, companies are leveraging research and development to introduce new products that comply with stringent regulatory standards and meet evolving customer requirements, ensuring their growth and sustainability in the competitive environment.
Recent Developments
- In April 2025, Thermo Fisher Scientific launched the 5L DynaDrive Single-Use Bioreactor, a bench-scale system designed for seamless scalability from 1 to 5,000 liters. This new bioreactor offers a 27% productivity increase over glass bioreactors, enhanced sustainability with biobased films, and consistent performance across different scales, supporting both large and small biopharma manufacturers. The DynaDrive S.U.B. supports robust production across scales and has the flexibility to accommodate a variety of cell lines and processing modalities.
- In April 2025, Sartorius Stedim Biotech entered a strategic partnership with Tulip Interfaces to drive digital transformation in single-use bioprocessing. The collaboration introduced Biobrain® Operate powered by Tulip, a suite of digital manufacturing applications that integrate with Sartorius equipment to reduce process variability, digitize operations, and ensure regulatory compliance. This partnership aims to advance paperless manufacturing and optimize resource efficiency in bioprocessing.
- In March 2025, Corning introduced new technologies to support advanced therapy applications, including the Ascent™ Fixed Bed Reactor (FBR) and expanded cell expansion platforms like HYPERStack®, HYPERFlask®, and CellSTACK®. These platforms feature closed systems and automation to reduce contamination risk and enhance scalability for bioprocess applications.
- In April 2023, Merck KGaA launched the Ultimus® Single-Use Process Container Film, featuring ten times greater abrasion resistance than other films, improved durability, and leak resistance for single-use assemblies. The technology is now available in Mobius® 3D process containers, enhancing operational efficiency and cell growth performance.
Market Concentration & Characteristics
The market for Single-Use Bio-Processing Systems in China exhibits a moderate to high level of concentration, with several large players dominating the space. These companies often benefit from economies of scale, significant research and development (R&D) investments, and extensive product portfolios that include a wide range of bioprocessing solutions. Market characteristics include rapid innovation, with a focus on improving the efficiency, scalability, and cost-effectiveness of disposable systems. The demand for single-use technologies is driven by the increasing need for flexible, contamination-free, and faster biomanufacturing processes, especially in the production of biologics, vaccines, and monoclonal antibodies. As a result, established players continue to expand their product offerings and strengthen their market presence through strategic partnerships, acquisitions, and localized manufacturing. Smaller players also contribute to the market by addressing niche requirements, such as specialized systems for research or early-stage production, further diversifying the competitive landscape. The market’s concentration is expected to grow as companies continue to consolidate resources and technology to stay ahead in the rapidly evolving sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The China Single-Use Bio-Processing Systems market is expected to continue growing rapidly due to increasing demand for biologics and vaccines.
- Advancements in single-use technology, including automation and digital integration, will drive future market development.
- Rising biopharmaceutical production demands will encourage companies to adopt more flexible and cost-effective bioprocessing solutions.
- The trend of adopting disposable technologies will increase as companies seek faster, more efficient manufacturing processes.
- Regulatory improvements and stricter quality standards will push companies to develop systems that comply with international guidelines.
- Collaboration between global and local players will foster innovation, driving the development of new and more specialized products.
- The growing focus on personalized medicine will create new opportunities for single-use systems, particularly in smaller-scale production.
- Biomanufacturing plants in China will continue to expand, creating higher demand for scalable, contamination-free production solutions.
- Research and development investments will be crucial for companies to stay competitive, especially in the face of rising technological demands.
- With China's expanding position in the global biopharmaceutical market, the demand for single-use systems will rise significantly over the next decade.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the China Single-Use Bio-Processing Systems market?
What factors are driving the growth of the China Single-Use Bio-Processing Systems market?
.What are some challenges faced by the China Single-Use Bio-Processing Systems market?
Who are the major players in the China Single-Use Bio-Processing Systems market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China Single-Use Bio-Processing Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China Single-Use Bio-Processing Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,145.03 million → 2032: USD 8,263.99 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China Single-Use Bio-Processing Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China Single-Use Bio-Processing Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China Single-Use Bio-Processing Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China Single-Use Bio-Processing Systems Market Drivers
- 3.3 China Single-Use Bio-Processing Systems Market Restraints & Challenges
- 3.4 China Single-Use Bio-Processing Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China Single-Use Bio-Processing Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China Single-Use Bio-Processing Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China Single-Use Bio-Processing Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China Single-Use Bio-Processing Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China Single-Use Bio-Processing Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China Single-Use Bio-Processing Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China Single-Use Bio-Processing Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China Single-Use Bio-Processing Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China Single-Use Bio-Processing Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China Single-Use Bio-Processing Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China Single-Use Bio-Processing Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China Single-Use Bio-Processing Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China Single-Use Bio-Processing Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China Single-Use Bio-Processing Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China Single-Use Bio-Processing Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China Single-Use Bio-Processing Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China Single-Use Bio-Processing Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China Single-Use Bio-Processing Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China Single-Use Bio-Processing Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
