
Market Overview
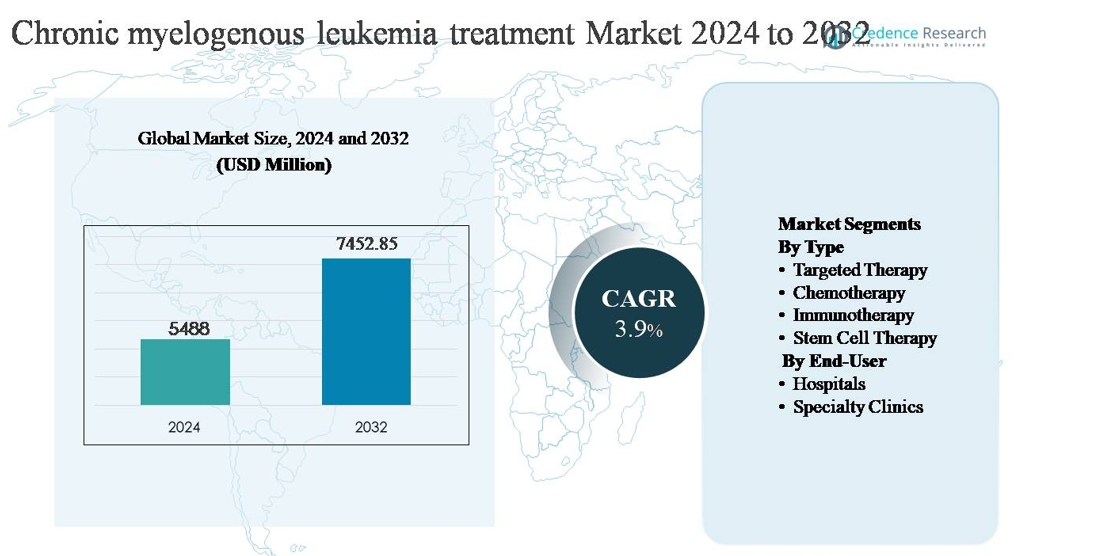
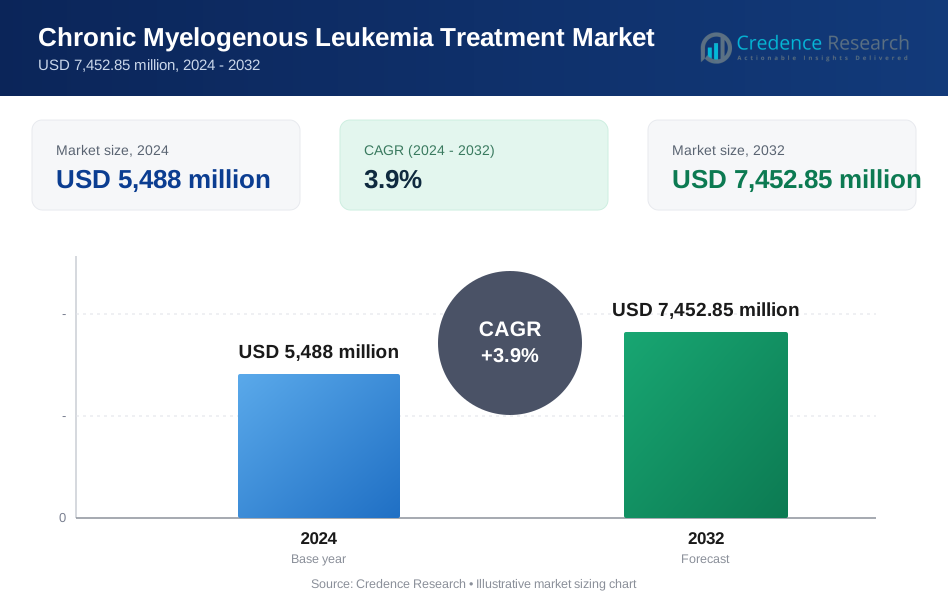
The chronic myelogenous leukemia (CML) treatment market was valued at USD 5,488 million in 2024 and is anticipated to reach USD 7,452.85 million by 2032, expanding at a compound annual growth rate (CAGR) of 3.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
|
|
USD 5,488 million |
| Chronic Myelogenous Leukemia Treatment Market, CAGR | 3.9% |
| Chronic Myelogenous Leukemia Treatment Market Size 2032 | USD 7,452.85 million |
The chronic myelogenous leukemia (CML) treatment market is led by a concentrated group of global pharmaceutical companies with strong expertise in targeted oncology therapies, including Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Otsuka Holdings Co., Ltd., Incyte, Biopath Holdings Inc., and Stragen Pharma SA. These players compete through differentiated tyrosine kinase inhibitor portfolios, lifecycle management strategies, and global commercialization capabilities. North America is the leading region, accounting for approximately 42% of the global market, supported by early diagnosis, advanced molecular monitoring, and high treatment adherence. Europe follows as a major contributor, while Asia-Pacific continues to gain importance due to expanding access to affordable therapies and improving oncology infrastructure.
Market Insights
- The chronic myelogenous leukemia (CML) treatment market was valued at USD 5,488 million in 2024 and is projected to reach USD 7,452.85 million by 2032, expanding at a CAGR of 3.9% during the forecast period, supported by long-term therapy demand and sustained patient treatment cycles.
- Market growth is driven by the widespread adoption of targeted therapies, which represent the dominant segment with over 75% share, due to their role as first-line treatment, high efficacy in achieving molecular remission, and requirement for prolonged or lifelong use.
- Key market trends include increasing focus on treatment-free remission strategies, next-generation tyrosine kinase inhibitors for resistant cases, and rising use of generics, which improve affordability while intensifying competitive dynamics.
- The competitive landscape is characterized by established pharmaceutical players focusing on portfolio optimization, lifecycle extensions, and global distribution, while generic manufacturers exert pricing pressure and expand access in emerging markets.
- Regionally, North America leads with around 42% market share, followed by Europe at ~30%, Asia-Pacific at ~18%, with Latin America and the Middle East & Africa together accounting for the remaining share, driven by improving diagnostics and therapy access.
Market Segmentation Analysis:
By Type:
The chronic myelogenous leukemia (CML) treatment market is dominated by targeted therapy, which holds the largest market share due to its position as the global standard of care across all disease phases. Tyrosine kinase inhibitors (TKIs) effectively suppress BCR-ABL activity, enabling durable molecular remission and long-term disease control. High prescription volumes, lifelong treatment duration, and strong clinical guideline endorsement continue to drive demand. Chemotherapy remains limited to advanced or blast-phase cases, while immunotherapy is emerging through clinical development. Stem cell therapy, despite curative potential, remains restricted due to procedural risk and eligibility constraints.
- For instance, Bristol Myers Squibb’s dasatinib (Sprycel®) is prescribed at 100 mg once daily for chronic-phase CML and demonstrates activity against over 30 documented BCR-ABL1 kinase domain mutations, supporting its use after first-line failure.
By End-User:
Hospitals represent the dominant end-user segment in the CML treatment market, accounting for the highest share owing to their advanced oncology infrastructure and integrated hematology services. Hospitals lead in diagnosis, molecular monitoring, treatment initiation, and management of complex or resistant cases, including stem cell transplantation. Their access to specialized clinicians and inpatient capabilities supports sustained utilization. Specialty clinics are increasingly important in long-term outpatient management, particularly for stable patients receiving oral targeted therapies, driven by convenience, continuity of care, and reduced hospitalization needs.
- For instance, MD Anderson Cancer Center operates a dedicated Leukemia Department that performs quantitative BCR-ABL1 monitoring using real-time PCR (RQ-PCR) assays. These assays are highly sensitive and capable of detecting transcript levels below the 0.0032% mark (MR4.5) on the International Scale, with the lab's stated limit of quantification being 002% IS (MR4.7).
Key Growth Driver
Sustained Reliance on Targeted Therapies as Standard of Care
The chronic myelogenous leukemia (CML) treatment market continues to be driven by the long-term reliance on tyrosine kinase inhibitors (TKIs) as the established first-line therapy. These agents have significantly improved survival outcomes by enabling durable molecular remission and transforming CML into a manageable chronic condition for most patients. Lifelong treatment requirements for many patients result in consistent therapy demand, reinforcing revenue stability. The availability of multiple generations of TKIs supports sequential treatment strategies in cases of resistance or intolerance, further extending treatment duration. In addition, expanding access to generic TKIs in several regions has increased patient reach, supporting broader diagnosis-to-treatment conversion and sustaining overall market expansion.
- For instance, Novartis’ imatinib mesylate (Gleevec®) is prescribed at a standard starting dose of 400 mg once daily for newly diagnosed chronic-phase CML, with long-term follow-up data extending beyond two decades since its initial regulatory approval in 2001, demonstrating persistent molecular control under continuous dosing.
Rising Diagnosis Rates and Improved Molecular Monitoring
Growth in the CML treatment market is also supported by rising diagnosis rates enabled by improved access to cytogenetic and molecular diagnostic tools. Advances in real-time quantitative PCR testing allow for early detection and precise monitoring of BCR-ABL transcript levels, encouraging timely treatment initiation and therapy optimization. Increased physician awareness and standardized monitoring protocols have strengthened adherence to long-term treatment plans, reducing disease progression rates. As healthcare systems invest in diagnostic infrastructure, particularly in emerging economies, a larger patient pool is entering structured treatment pathways, directly contributing to increased therapy uptake and sustained market growth.
- For instance, Roche’s LightCycler® 480 System II supports RT-qPCR workflows with reaction volumes as low as 5 µL and cycling times under 40 minutes, allowing high-throughput BCR-ABL1 transcript analysis in clinical laboratories.
Expanding Treatment Access Across Emerging Healthcare Markets
The gradual expansion of oncology care infrastructure across emerging markets represents a significant growth driver for CML treatment. Governments and private healthcare providers are improving access to essential cancer therapies through reimbursement programs, public-private partnerships, and inclusion of TKIs in national treatment formularies. Improved affordability through generics and patient assistance programs has reduced treatment gaps, enabling earlier intervention and continuous therapy. As access improves, treatment adherence and survival outcomes rise, reinforcing demand for long-term pharmacological management and supporting steady market expansion across developing regions.
Key Trend & Opportunity:
Shift Toward Treatment-Free Remission Strategies
An important trend shaping the CML treatment landscape is the growing clinical focus on treatment-free remission (TFR). Advances in molecular monitoring have enabled select patients with sustained deep molecular responses to safely discontinue TKIs under strict supervision. This shift is driving innovation in patient stratification, response monitoring, and relapse management protocols. While TFR may reduce long-term drug exposure for eligible patients, it creates opportunities for premium diagnostics, specialized follow-up services, and next-generation therapies designed to deepen molecular responses. Pharmaceutical developers are increasingly positioning newer TKIs to support durable remission outcomes aligned with TFR objectives.
- For instance, Otsuka Pharmaceutical Co., Ltd. developed and obtained approval for the "Major BCR-ABL mRNA Measurement Kit" in Japan, which is used as an aid to diagnose and monitor the effectiveness of treatment for chronic myeloid leukemia (CML), and which is covered by national health insurance as of April 1, 2015.
Development of Next-Generation and Combination Therapies
Ongoing research into next-generation TKIs and combination treatment approaches presents a major opportunity within the CML treatment market. Novel agents are being developed to address resistance mutations and improve tolerability profiles, particularly for patients with long-term treatment exposure. Combination strategies integrating targeted therapy with immune-modulating agents are also under investigation to enhance response depth. These developments support product differentiation and lifecycle management strategies, enabling manufacturers to strengthen their competitive positioning while addressing unmet clinical needs in resistant or refractory patient populations.
- For instance, Takeda Pharmaceutical Company Limited advanced ponatinib life-cycle optimization strategies through dose-modification protocols validated in clinical programs where ponatinib was initiated at 45 mg once daily with protocol-defined reductions to 15 mg once daily following achievement of molecular milestones, supported by serial BCR-ABL1 transcript monitoring at 3-month intervals using centralized laboratories calibrated to international reference standards.
Key Challenge
Long-Term Treatment Adherence and Safety Concerns
Despite therapeutic advances, long-term treatment adherence remains a significant challenge in CML management. Lifelong or extended therapy increases the risk of cumulative adverse effects, including cardiovascular and metabolic complications, which can impact patient compliance. Managing chronic toxicity requires ongoing monitoring and potential therapy switching, increasing clinical complexity. Non-adherence can lead to suboptimal molecular responses and disease progression, undermining treatment effectiveness. These challenges place pressure on healthcare providers to balance efficacy with tolerability, while pharmaceutical companies must continue improving safety profiles to sustain long-term patient engagement.
Pricing Pressures and Generic Competition
The increasing penetration of generic TKIs presents a structural challenge for branded therapies within the CML treatment market. While generics improve patient access, they intensify pricing pressure and limit revenue growth for originator products. Payers are prioritizing cost containment, particularly for long-term therapies, which can restrict uptake of newer, higher-priced agents unless clear clinical advantages are demonstrated. Manufacturers must navigate competitive pricing environments while investing in innovation, creating a challenging balance between affordability, differentiation, and sustainable profitability in a market characterized by extended treatment durations.
Regional Analysis
North America:
North America holds the largest share of the chronic myelogenous leukemia (CML) treatment market, accounting for approximately 42% of global revenue. The region benefits from early disease diagnosis, widespread access to molecular testing, and strong adoption of targeted therapies as first-line treatment. High treatment adherence, established reimbursement frameworks, and the presence of leading pharmaceutical innovators support sustained therapy utilization. The United States dominates regional demand due to advanced oncology infrastructure and long-term patient management protocols, while Canada contributes through universal healthcare coverage and standardized clinical guidelines supporting continuous CML treatment.
Europe:
Europe represents around 30% of the global CML treatment market, supported by strong public healthcare systems and broad access to tyrosine kinase inhibitors across major countries. Western Europe leads regional consumption due to well-established hematology networks, routine molecular monitoring, and favorable reimbursement policies. Countries such as Germany, the United Kingdom, and France maintain high treatment continuity rates through national cancer programs. Eastern Europe shows gradual growth as access to diagnostics and generics improves. The region also benefits from strong clinical research activity and structured long-term disease management frameworks.
Asia-Pacific:
Asia-Pacific accounts for approximately 18% of the global CML treatment market and represents the fastest-expanding regional opportunity. Growth is driven by rising disease awareness, improving diagnostic penetration, and expanding access to affordable generic targeted therapies. Countries such as China, India, Japan, and South Korea are strengthening oncology infrastructure and increasing inclusion of CML treatments in public reimbursement programs. Large patient populations and improving healthcare investment continue to expand the treated patient base. While access disparities remain across rural areas, urban centers are increasingly adopting guideline-based CML management.
Latin America:
Latin America holds around 6% of the global CML treatment market, supported by gradual improvements in cancer care access and expanding use of targeted therapies. Brazil and Mexico dominate regional demand due to higher healthcare spending and growing availability of reimbursed oncology drugs. Public healthcare systems increasingly incorporate generic TKIs to improve affordability, while private healthcare providers support advanced diagnostics and monitoring. Despite progress, uneven access and delayed diagnosis in certain countries limit full market potential. Continued healthcare reforms and investment in oncology services are expected to support steady regional growth.
Middle East & Africa:
The Middle East & Africa region accounts for approximately 4% of the global CML treatment market, reflecting limited but gradually improving access to advanced leukemia therapies. Gulf Cooperation Council countries lead regional demand due to higher healthcare expenditure, access to branded therapies, and specialized oncology centers. In contrast, much of Africa faces challenges related to late diagnosis, limited molecular testing, and constrained treatment availability. International aid programs, expanding generic penetration, and gradual healthcare infrastructure development are improving access, supporting incremental growth across select Middle Eastern and African markets.
Market Segmentations:
By Type
- Targeted Therapy
- Chemotherapy
- Immunotherapy
- Stem Cell Therapy
By End-User
- Hospitals
- Specialty Clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the chronic myelogenous leukemia (CML) treatment market is characterized by the presence of established pharmaceutical companies with strong oncology portfolios and extensive experience in targeted therapies. Market competition centers on the development, commercialization, and lifecycle management of tyrosine kinase inhibitors, with companies focusing on efficacy, safety profiles, and resistance management. Leading players leverage robust clinical data, long-term patient outcomes, and global distribution networks to maintain market positions. Generic manufacturers intensify competition by expanding access and exerting pricing pressure, particularly in emerging markets. Strategic priorities include label expansions, next-generation molecule development, and partnerships to support advanced diagnostics and monitoring. Companies also invest in real-world evidence generation and patient support programs to strengthen treatment adherence and brand differentiation in a market defined by chronic disease management and prolonged therapy durations.
Key Player Analysis
- Novartis AG
- Pfizer Inc.
- Bristol-Myers Squibb Company
- Takeda Pharmaceutical Company Limited
- Teva Pharmaceutical Industries Ltd.
- Otsuka Holdings Co., Ltd.
- Incyte
- Biopath Holdings Inc.
- Stragen Pharma SA
Recent Developments
- In April 2024,Takeda highlighted updated clinical practice data in April 2024 supporting its response-based dosing strategy for ponatinib, originally validated in the OPTIC trial. Treatment initiation at 45 mg once daily, followed by protocol-defined reduction to 15 mg once daily upon achievement of BCR-ABL1 transcript levels ≤1%, was reaffirmed as an effective approach for patients with resistant CML, including those harboring the T315I mutation. Molecular response assessments were based on serial quantitative PCR testing aligned with international reference laboratories, ensuring early detection of molecular relapse and sustained disease control.
- In February 2024, Bristol-Myers Squibb referenced extended follow-up analyses from long-running dasatinib clinical cohorts, including patients receiving 100 mg once daily dosing in chronic-phase CML. These analyses reaffirmed durable molecular response maintenance over extended treatment durations, with molecular monitoring conducted via centralized PCR assays calibrated to International Scale standards. While dasatinib has transitioned to a mature lifecycle phase, BMS continues to support long-term safety and response durability documentation in both adult and pediatric populations.
Report Coverage
The research report offers an in-depth analysis based on Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Targeted therapies will continue to anchor chronic myelogenous leukemia treatment due to their proven long-term efficacy and established clinical acceptance.
- Next-generation tyrosine kinase inhibitors will gain wider adoption to address resistance and intolerance in long-term treated patients.
- Treatment-free remission strategies will increasingly influence clinical decision-making for patients achieving deep and sustained molecular responses.
- Molecular diagnostics and real-time monitoring will play a more central role in therapy optimization and relapse prevention.
- Generic penetration will expand further, improving treatment accessibility while increasing price competition across markets.
- Combination therapy research will accelerate to enhance response durability and minimize disease progression risks.
- Specialty clinics will grow in importance for long-term outpatient management of stable patients.
- Emerging markets will experience higher treatment uptake as healthcare infrastructure and reimbursement frameworks improve.
- Patient adherence and long-term safety management will remain critical focus areas for healthcare providers.
- Innovation in personalized treatment approaches will shape future clinical guidelines and care pathways.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chronic myelogenous leukemia treatment, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chronic myelogenous leukemia treatment market projected to grow between 2024 and 2032?
What are some key challenges in the CML treatment market?
What does the future outlook seem like for CML treatments?
Who are the leading companies in the Chronic myelogenous leukemia treatment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chronic Myelogenous Leukemia Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chronic Myelogenous Leukemia Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,488 million → 2032: USD 7,452.85 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chronic Myelogenous Leukemia Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chronic Myelogenous Leukemia Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chronic Myelogenous Leukemia Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chronic Myelogenous Leukemia Treatment Market Drivers
- 3.3 Chronic Myelogenous Leukemia Treatment Market Restraints & Challenges
- 3.4 Chronic Myelogenous Leukemia Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chronic Myelogenous Leukemia Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chronic Myelogenous Leukemia Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chronic Myelogenous Leukemia Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chronic Myelogenous Leukemia Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chronic Myelogenous Leukemia Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chronic Myelogenous Leukemia Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chronic Myelogenous Leukemia Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chronic Myelogenous Leukemia Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chronic Myelogenous Leukemia Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chronic Myelogenous Leukemia Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chronic Myelogenous Leukemia Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chronic Myelogenous Leukemia Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chronic Myelogenous Leukemia Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chronic Myelogenous Leukemia Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chronic Myelogenous Leukemia Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chronic Myelogenous Leukemia Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chronic Myelogenous Leukemia Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chronic Myelogenous Leukemia Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chronic Myelogenous Leukemia Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
