
Volume, not price, is carrying collector car growth
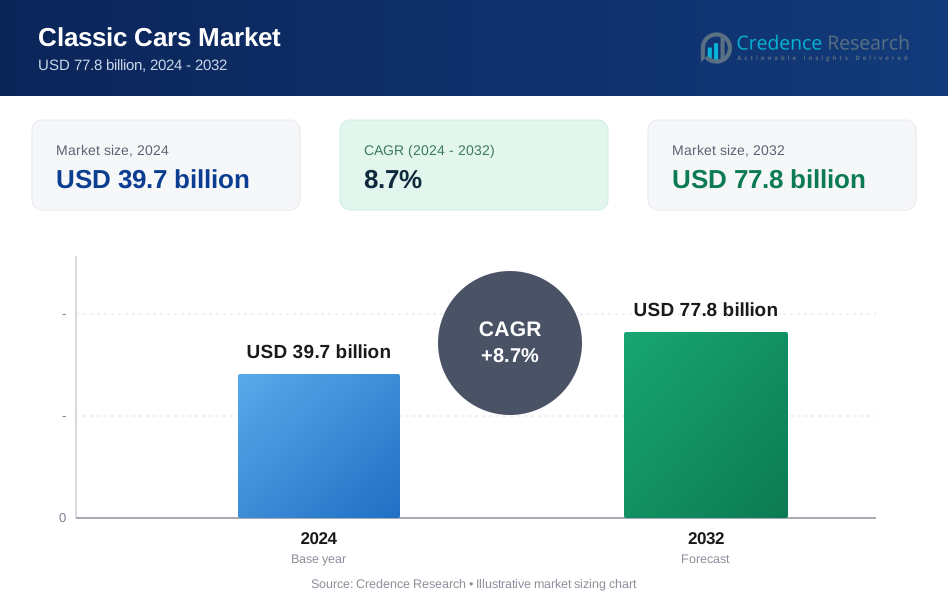
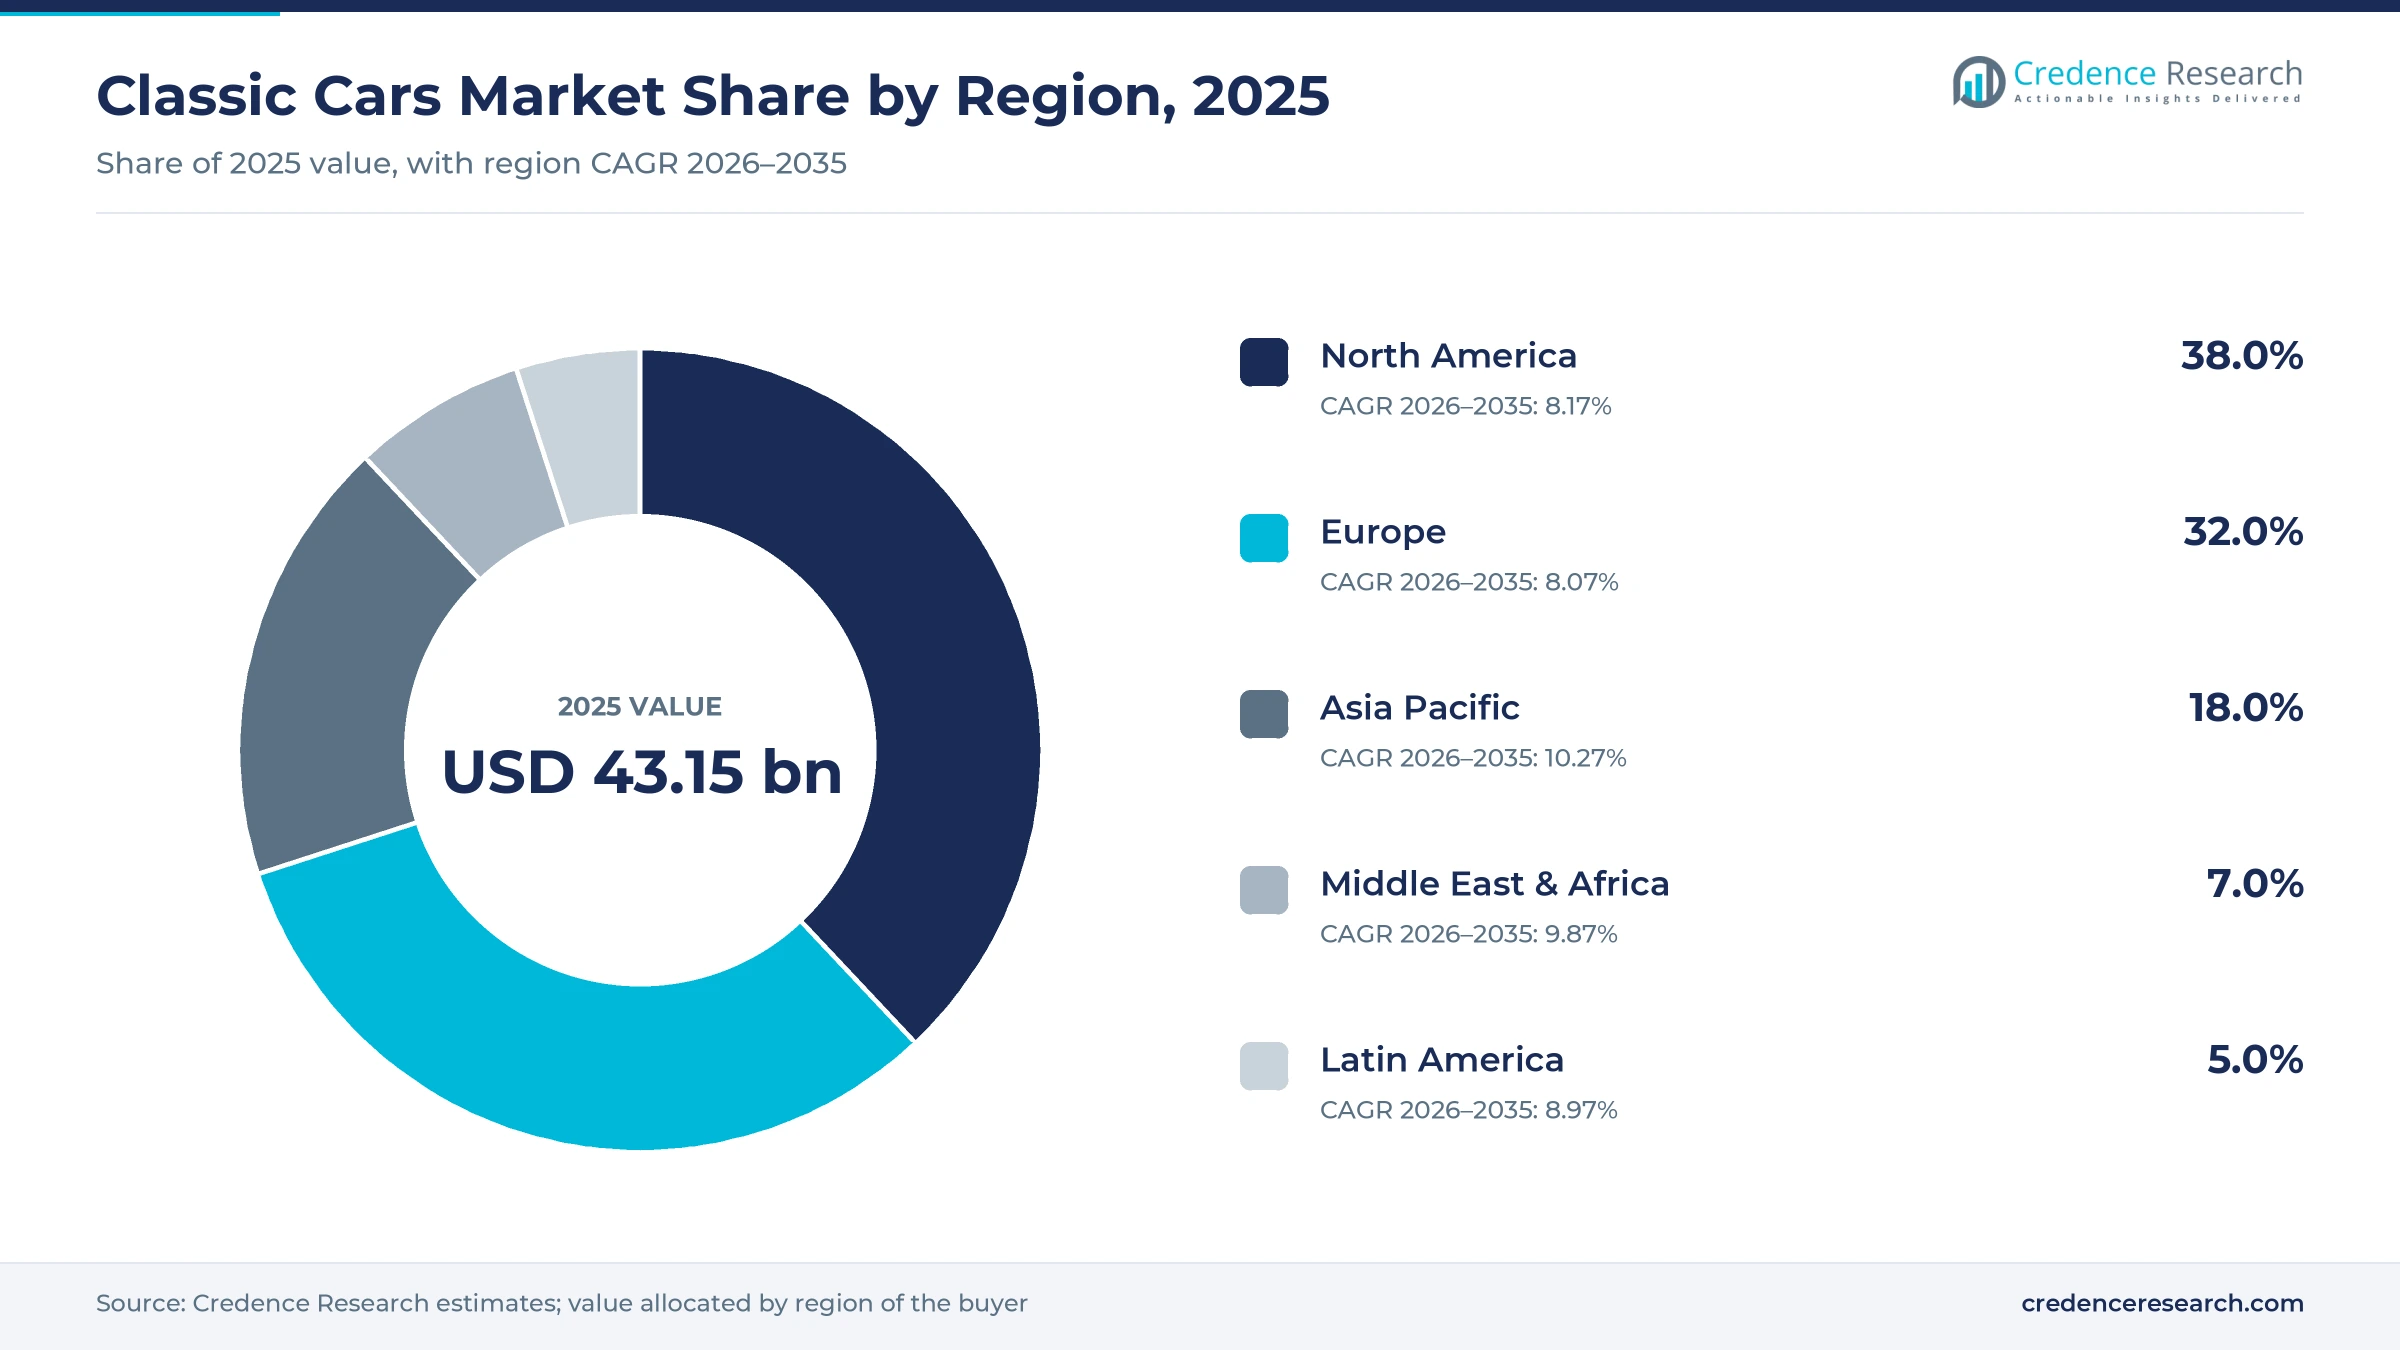
The global classic cars market was valued at USD 43.15 billion in 2025 and is projected to increase from USD 46.91 billion in 2026 to USD 99.38 billion by 2035, registering a CAGR of 8.70% during 2026–2035. Demand comes from collectors, enthusiasts and investors who buy through auctions, online platforms, specialist dealers and private sales. North America held the largest regional share, 38.0% in 2025, because Monterey Car Week, a deep insurance base and a large online bidder pool sit there. Asia Pacific is the fastest-growing region at 10.27% a year, as Japanese factory parts programs and an easier Indian import rule take effect. The most important commercial change is the rise of internet selling, because online auctions crossed $2 billion in 2025 and now run alongside live sales that still dominate the highest prices. Prices themselves were uneven in 2025, so growth rests more on the number of cars changing hands than on rising values.
What does the classic cars market count, and how do vintage cars fit in?
The market counts the value of collectible older and modern-classic vehicles sold each year through live auctions, online auctions, dealers and private treaty, across sports cars, coupes, convertibles, sedans, SUVs and trucks. Vintage cars, usually described as cars built between 1919 and 1930, form a small and specialized part of this total. Buyers typically check condition, originality and documentation before they bid, because these factors set the price of an individual car far more than its age does.
New vehicles, ordinary used vehicles without collector demand, replica kits and memorabilia sit outside the estimate, even when an auction house sells them on the same day. The surrounding value chain includes restorers, parts suppliers, insurers, lenders, transport firms and event organizers, whose income depends on the cars but is not counted as sales value here.
Classic Cars Market Insights
- The market moves from USD 43.15 billion in 2025 to USD 99.38 billion by 2035 at an 8.70% CAGR, with volume and broader participation doing more of the work than price gains.
- North America held 38.0% of 2025 value, supported by Monterey Car Week, specialist insurers and a large base of online bidders and registered collectors.
- Post-War cars led with 40.0% of 2025 value, while Modern Classic models grow fastest at 9.98% a year as attention moves to newer cars.
- Online auctions crossed $2 billion in 2025 and lifted sell-through to 68%, according to CLASSIC.COM, showing that internet selling has become a mature sales channel for collectors.
- Broad Arrow reported private sales of more than $281 million in 2025, above its auction total for the first time, which points to growing competition for discreet consignments.
Good-condition, sports and post-war cars anchor value
Good-condition cars hold the most value because most collector cars sit in that grade
Based on condition, the market is categorized into concours, excellent, good, fair and poor cars. Good led with 40.0% of 2025 value because Hagerty's Price Guide team, drawing on insurance data and in-person ratings, reported in April 2024 that the vast majority of collector cars sit in its #3 condition grade. Excellent grows fastest at 9.42% a year as most fully restored cars land in that grade, and reissued parts widen the pool, with Nissan's Nismo Heritage program adding 37 Skyline GT-R parts from June 1, 2026. Concours examples remain rare and are seldom seen away from major shows.
Sports cars lead on price while SUVs gain from a decade of rising values
Based on type, the market is categorized into sports car, sedan, coupe, convertible, SUV and truck models. Sports Car led with 36.0% of 2025 value because the highest-priced trading concentrates there, and Hagerty reported that modern supercars accounted for more than half of all sales at the August 2026 Monterey auctions. SUV grows fastest at 10.16% a year as Hagerty's index of 19 collectible trucks and SUVs nearly tripled from $14,699 in 2010 to $43,611 by June 2024. Hagerty data cited by Motorious in December 2025 shows the gains are selective, since the early Mercedes-Benz G-Class rose while the Jeep Grand Wagoneer softened.
Post-war cars still lead, but modern classics are drawing the next wave of buyers
Based on era, the market is categorized into pre-war, post-war, muscle car and modern classic vehicles. Post-War led with 40.0% of 2025 value because 1960s cars alone brought $147.7 million from 182 sales at Monterey in 2026, according to CLASSIC.COM, while pre-war cars brought $102.6 million from 143 sales. Modern Classic grows fastest at 9.98% a year as Bring a Trailer's most-listed model years in 2025 were 2006, 2004, 2008, 2005 and 2007, and Knight Frank's Luxury Investment Index notes that cars from the late 1980s to early 2000s often outperform traditional classics.
Manual gearboxes command the premium as automated cars widen entry
Based on drive train, the market is categorized into manual, automatic and semi-automatic cars. Manual led with 62.0% of 2025 value because buyers pay heavily for a clutch pedal, and the Hagerty Price Guide showed in September 2022 a 125% premium for a manual 2002–06 Ferrari 575M and 50% for a manual Lamborghini Gallardo. Semi-Automatic grows fastest at 10.07% a year as automated-gearbox supercars enter collections, although Hagerty's guide still deducted 20% for an automated Audi R8, which keeps entry prices for these cars lower and broadens the buyer pool.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Condition | Good | 40.0% | Excellent | 9.42% |
| By Type | Sports Car | 36.0% | SUV | 10.16% |
| By Era | Post-War | 40.0% | Modern Classic | 9.98% |
| By Drive Train | Manual | 62.0% | Semi-Automatic | 10.07% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Online reach and new buyers keep collector cars trading
Online auctions widen access and lift sold volume
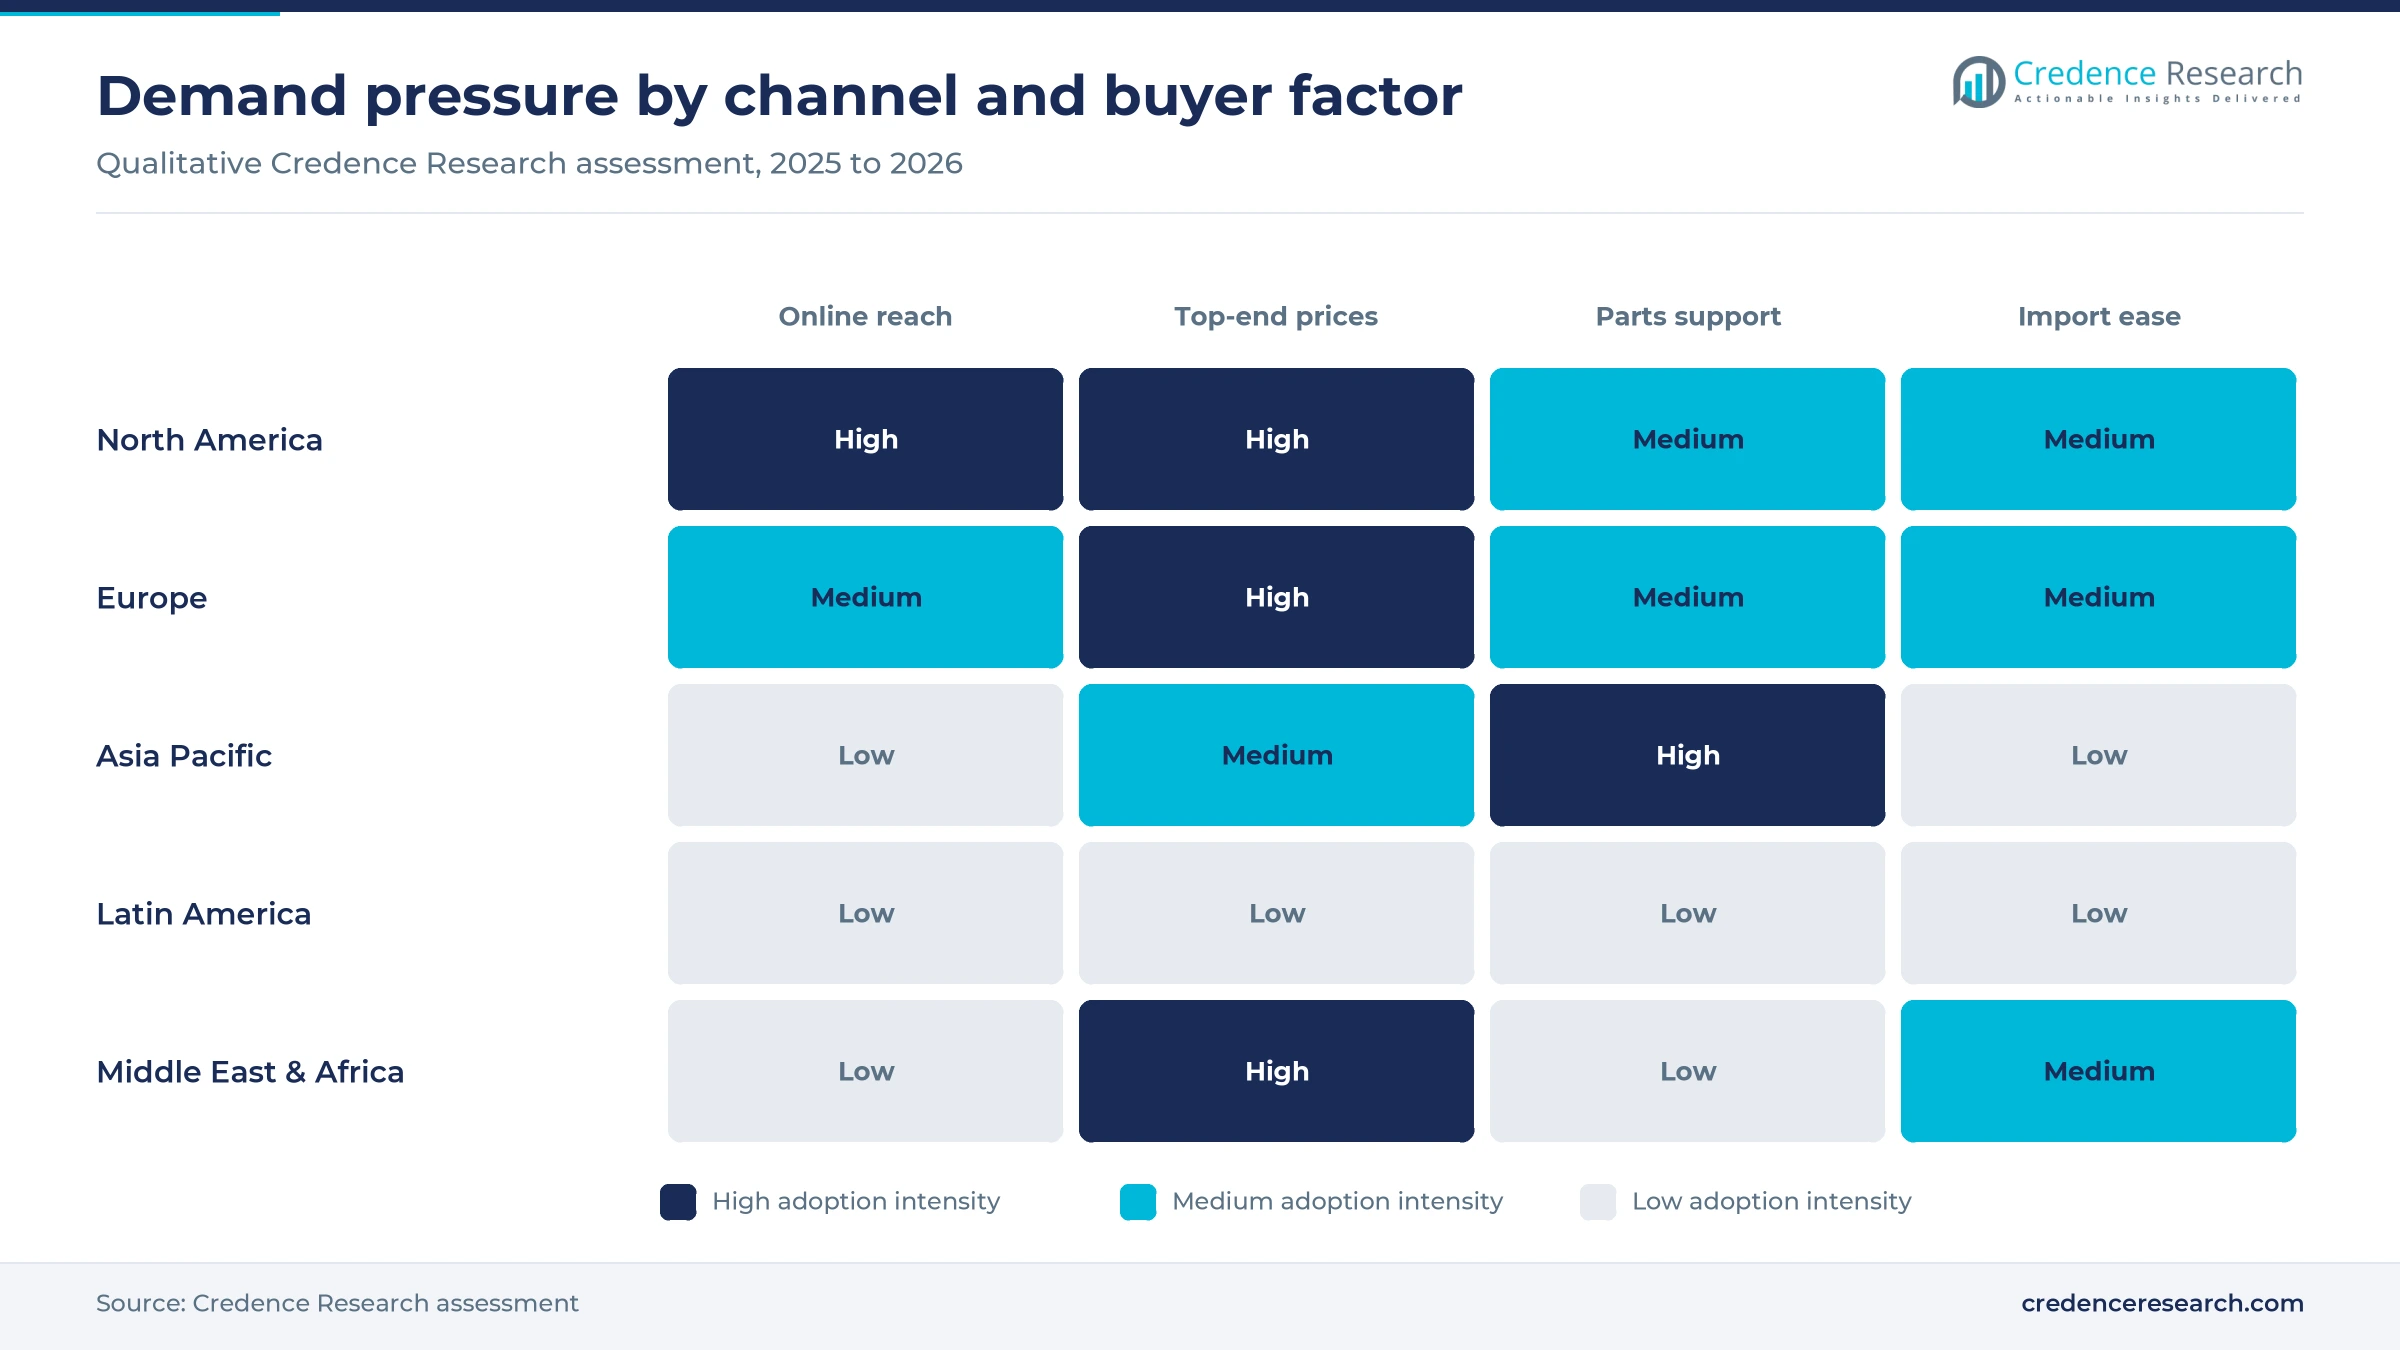
Online bidding has become the main growth channel, which puts collector cars in front of buyers far from the traditional auction weekends. CLASSIC.COM reported in January 2026 that online auctions crossed $2 billion in 2025 and that their sell-through climbed to 68% from 62% a year earlier, without a meaningful rise in listings. Bring a Trailer alone reported more than $1.7 billion in 2025 sales from a record 49,486 listings at an 81% sell-through rate, according to The Shop magazine. The same platform's registered users rose 11% to 1.65 million, which widens the bidder pool behind each listing. This reach helps North America remain the largest regional market for collector sales.
New buyers replace the generation that built the hobby
As long-held collections change hands, new buyers are entering, and this keeps cars trading rather than sitting in storage. RM Sotheby's said in December 2025 that 47% of its buyers and 46% of its bidders were participating for the first time, across 54 buyer countries. Hagerty data cited by Aviva Canada in August 2024 showed Gen X at about 35% of collector buyers in 2023, ahead of boomers at about 32%, with millennials and Gen Z just under 30%. Hagerty quotes reported by Collectors Car World then showed boomers back at 35% by February 2026, so wealthy older buyers remain active. According to SlashGear's November 2025 report on Hagerty data, Gen Z buyers choose cars about 24 years older than themselves.
Specialist insurance and lending lower the barrier to ownership
Specialist insurance and lending reduce the cost and risk of owning an older vehicle, which supports both first purchases and larger collections. Hagerty reported 2,819,179 insured vehicles at Dec. 31, 2025, up 9.4% from a year earlier, along with 371,203 units of new insurance business, a company record. Its State Farm program reached 27 states during 2025, which extends collector cover through another large insurer. Lending is growing too, because Broad Arrow Capital arranged about $85 million of new loans across the U.S., U.K. and Europe in 2025, and Motorious tied that activity to demand from younger clients. Together these services make a six-figure purchase easier to finance and protect.
Record top-end results encourage owners to consign
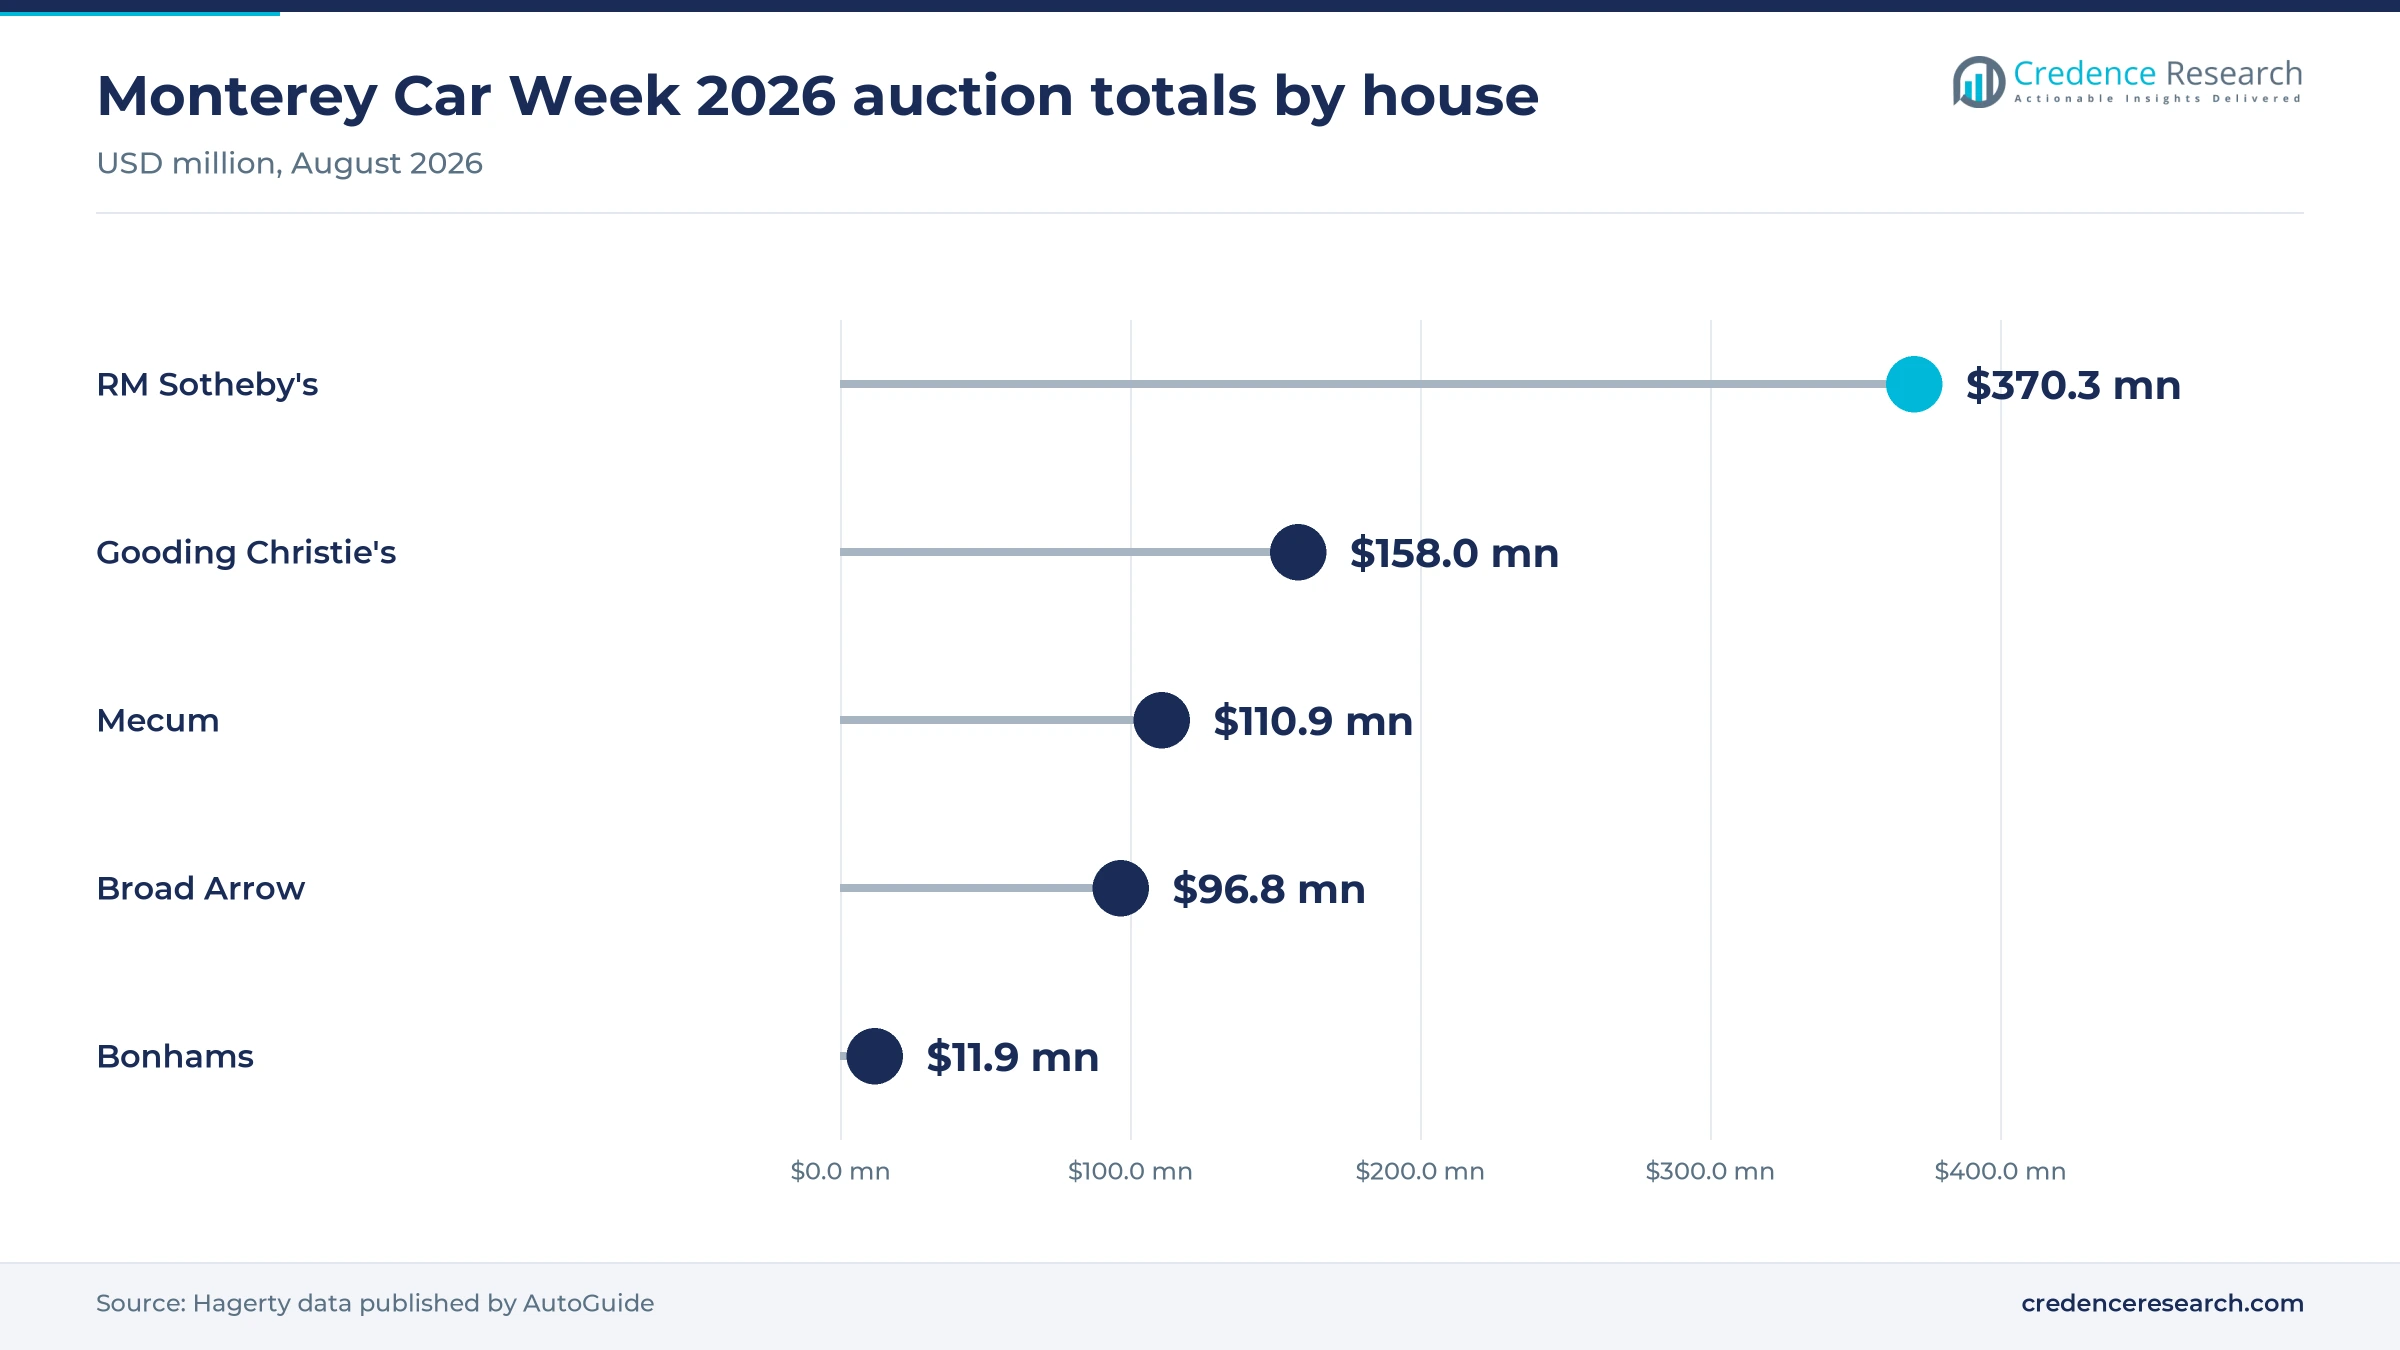
Strong results at the top of the market give owners confidence to consign and draw fresh capital into the category. Hagerty data published by AutoGuide put Monterey Car Week 2026 at $747.9 million, against $432.8 million in 2025, on 844 cars sold at a 75% sell-through rate. That total includes a $40 million charity Ferrari, so the underlying gain is smaller, but a 1964 Shelby Cobra Daytona Coupe still brought $42.9 million at Gooding Christie's. RM Sotheby's crossed $1 billion in 2025 sales and sold a 1954 Mercedes-Benz W 196 R Stromlinienwagen for $53.1 million in Stuttgart. These results also set visible price references for owners of less costly cars.
Younger eras and private deals reshape collector demand
Shift toward cars from the 1980s to the 2000s
Collector car market trends point to newer cars, and this changes which models carry premiums. Bring a Trailer's five most-listed model years in 2025 all fell between 2004 and 2008, according to The Shop magazine. Hagerty's 2026 Bull Market List, reported by Jalopnik in December 2025, names the 1999–2005 Mazda MX-5 Miata, 2006–2010 BMW M5 and 1995–1998 Nissan Skyline GT-R among its 11 picks. Hagerty valuation data also shows the 1985–91 Honda CRX up 168% since 2020, according to Motorious. As a result, Modern Classic models grow at 9.98% a year in the Credence Research model, ahead of every older era. CLASSIC.COM also found that pre-war cars lost momentum in the $100,000 to $500,000 range during 2025.
Rise of private sales alongside the auction stage
Sellers of important cars increasingly choose private treaty, because it offers discretion and avoids the risk of a public no-sale. Broad Arrow reported more than $281 million from 190 private transactions in December 2025, above its $257 million auction total for the first time, with an average deal near $1.48 million. Hagerty later reported private sales up 271.1% for 2025 as its marketplace expanded into Europe. RM Sotheby's also described record internal results for private and sealed sales in the same year. This shift means published auction totals understate activity, particularly above $1 million, and it pushes auction houses to build advisory and lending services around each consignor.
Opportunity in factory parts and restoration programs
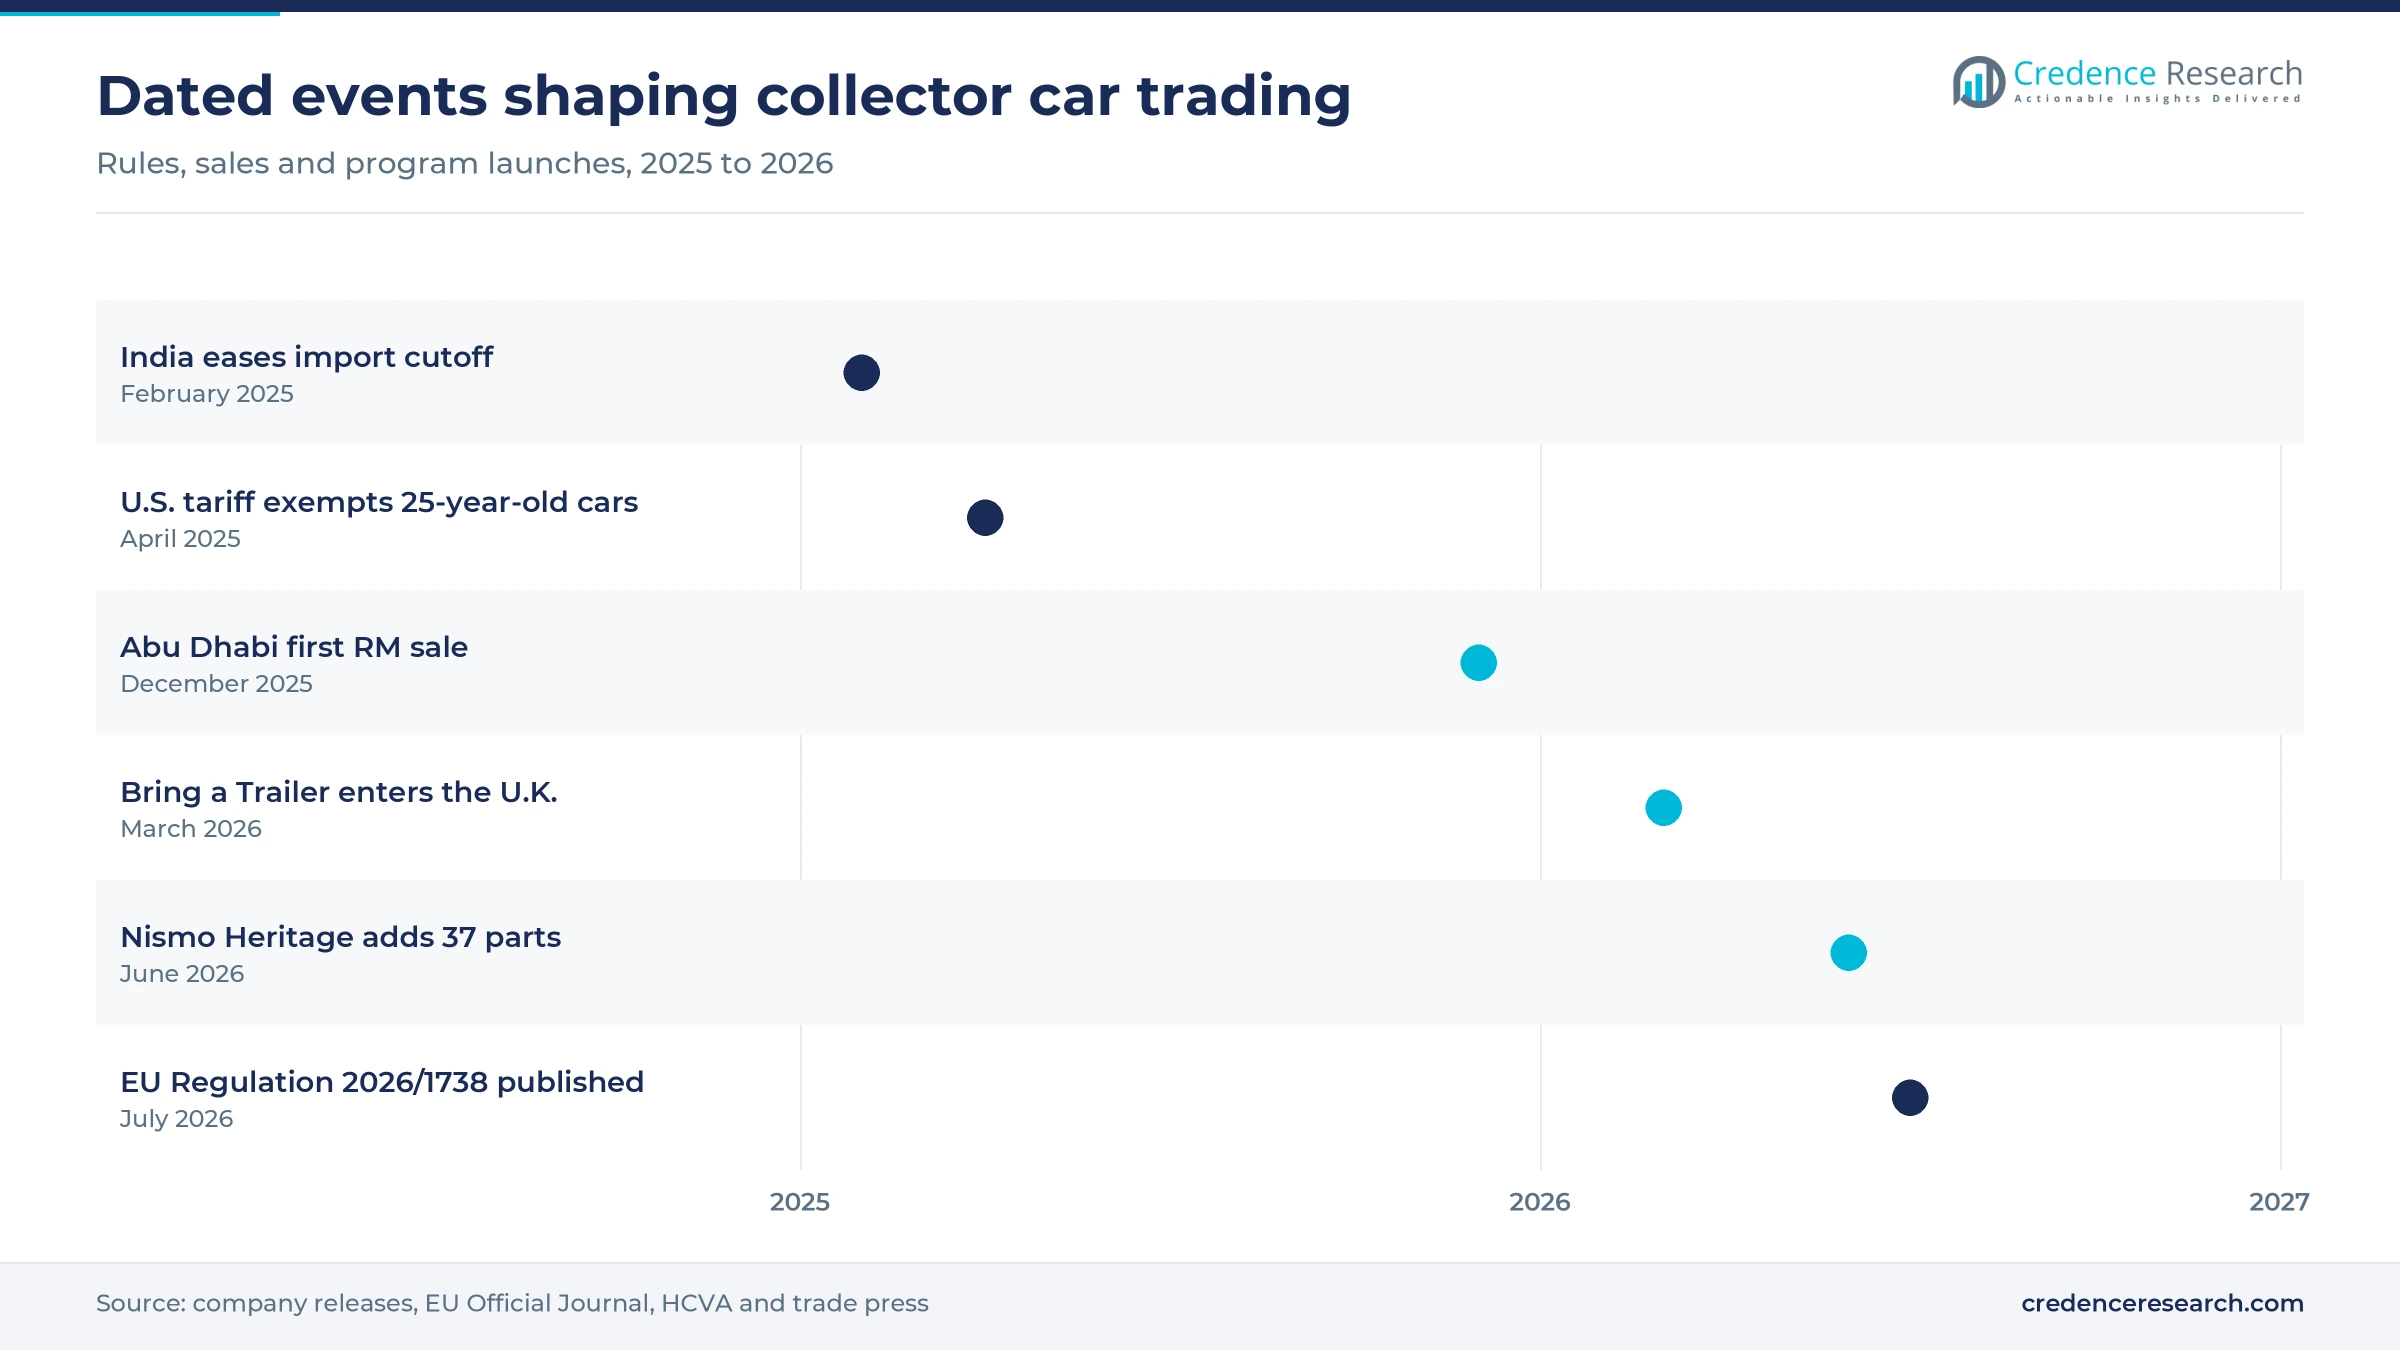
Factory heritage programs create an opening for suppliers and restorers, because parts availability decides how many cars stay usable. Nissan's Nismo Heritage program has reissued more than 300 parts since 2017 and opened orders for 37 more on June 1, 2026, including 3D-printed fuel pipe clips, according to Top Gear Philippines. Honda planned parts and restoration services for the first-generation NSX from spring 2026, according to ML Vehicle's report of a Bloomberg story. The FBHVC's 2025 survey shows the prize, with British owners spending an average of £4,567 a year on upkeep and use. Independent makers of aftermarket parts can serve models that factories do not yet cover.
Opportunity in newly accessible regions and buyer pools
New venues and looser import rules offer an opening for sellers willing to build local presence. Bring a Trailer announced its U.K. expansion on March 25, 2026, with Sports Purpose at Bicester Heritage as lead partner, according to The Shop magazine. RM Sotheby's held its first Abu Dhabi Collectors' Week sale on Dec. 5, 2025, and grossed $85.1 million from bidders in 45 countries. India moved its import cutoff in February 2025 from pre-1950 cars to cars aged 50 years or older, according to India Seatrade News. ItalPassion reported in January 2026 a possible import pilot for Guangdong from 2027, though that project remains unconfirmed. The Credence Research model reflects these openings through faster growth for Asia Pacific than for any other region.
Soft values, tariffs and aging owners test the market
Uneven values add risk to the investment case
Prices are not rising across the board, which weakens the case for buying purely as an investment. Knight Frank's Luxury Investment Index showed classic car values down 3.7% in 2025, according to Gulf News. Hagerty data cited by Motorious also put the 1948–52 Ford F-Series at $31,800 in excellent condition, below its 2019 level. Owners of mid-priced cars carry the most exposure, because storage and upkeep continue while values drift. Buyers respond by favoring documented cars and longer holding periods.
Tariffs and import costs form a barrier to moving cars
Trade costs have become less predictable for cross-border buyers and sellers. WCShipping reports that cars 25 years or older entering the U.S. from July 24, 2026 avoid the Section 232 auto tariff but pay 10% if built in the EU and 12.5% if built in the U.K. India's duties, GST and registration fees add roughly 250% of invoice value, according to India Seatrade News. Consignors and overseas bidders absorb these costs, which favors local selling such as the U.K. partner network that Bring a Trailer launched in 2026.
An aging owner base and thin skills pipeline
Ownership and workshop skills both depend on people who are getting older, which threatens long-term upkeep. The FBHVC's 2025 survey put the average British owner at 66 years old, and its 2,700 specialist businesses employ about 34,500 people. Only 45% of those businesses offer or plan apprenticeships, so succession is uneven. Restoration firm Clayton Classics has warned of a skills shortage in comments to GB News. Longer waiting times and higher labor bills can follow, so training programs are the main remedy.
Environmental rules can still reach cars and their suppliers
Regulation (EU) 2026/1738, adopted July 8, 2026, excludes vehicles of historical interest under Article 2(2)(e), according to FIVA and ADAC Klassik, yet related rules still pose a risk. FIVA's June 2026 update warned that a planned REACH restriction on chromium VI could affect chrome platers, with a committee vote possible in late 2027 or early 2028. Flanders plans to let each local authority decide on low emission zone exemptions, according to VRT NWS. Restorers and owners therefore face a patchwork of rules, and FIVA is urging stakeholders to submit data on the economic impact.
North America leads while the Gulf and Asia open up
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 16.40 | 38.0% | 8.17% |
| Europe | 13.81 | 32.0% | 8.07% |
| Asia Pacific | 7.77 | 18.0% | 10.27% |
| Middle East & Africa | 3.02 | 7.0% | 9.87% |
| Latin America | 2.16 | 5.0% | 8.97% |
North America leads on auctions, insurance and online bidding
North America held 38.0% of 2025 value and grows at 8.17% a year. The U.S. collector base is the deepest anywhere, with about 43 million collector vehicles valued near $1 trillion, according to Hagerty figures cited by Progressive. Monterey sets the annual price tone, and Hagerty's insured base provides a ready audience for its own marketplace. Mecum's 62% sell-through in Monterey in 2026 shows that this breadth does not guarantee every car finds a buyer at the volume end.
Europe combines heritage brands with new auction capacity
Europe held 32.0% of 2025 value and grows at 8.07% a year, supported by strong European collector demand and heritage events. Broad Arrow's three new European sales generated more than $93 million in 2025, according to Motorious, while RM Sotheby's sold a 1964 Ferrari 250 LM for $36.1 million in Paris. The U.K. alone counts 1,934,178 historic vehicles registered with the DVLA, and the FBHVC valued the sector at £7.3 billion a year in October 2025.
Asia Pacific grows fastest on Japanese supply and new access
Asia Pacific held 18.0% of 2025 value and is the fastest-growing region at 10.27% a year. Asia Pacific demand rests partly on Japan, which supplies both cars and factory support, with Nissan's Nismo Heritage program reissuing more than 300 parts since 2017 and Honda planning NSX support. India's 50-year rule allows cars built up to 1975, although resale restrictions from the DGFT limit dealer activity. Mainland China remains largely closed, so any Guangdong pilot would be a meaningful change.
Middle East & Africa gains a benchmark sale in Abu Dhabi
Middle East & Africa held 7.0% of 2025 value and grows at 9.87% a year, from a small but wealthy buyer base. RM Sotheby's Abu Dhabi sale became the most successful collector car auction held in the Middle East, led by a 1994 McLaren F1 at $25.3 million. That result gives the UAE collector scene a price reference, and its top lots favored modern supercars. Bidders from 45 countries took part, so the sale drew on international money as well as local collectors.
Latin America builds on registered collector status
Latin America held 5.0% of 2025 value and grows at 8.97% a year, which keeps it the smallest region by value. Brazil's black-plate status requires a car older than 30 years with at least 80% original features, under Contran Resolution 56, according to Canaltech. Second-generation Chevrolet Vectra models began to qualify in February 2026, so the eligible pool now reaches 1990s family cars. Chile and Mexico both answered FIVA's 2026 survey on historic vehicle rules, which shows organized club activity beyond Brazil.
Dated moves that changed collector car trading since 2025
| Development | Status and market relevance |
|---|---|
| In December 2025, RM Sotheby's held its first Abu Dhabi Collectors' Week sale and grossed $85.1 million. | Set a Middle East record and gave Gulf buyers a local price reference |
| In March 2026, Bring a Trailer announced its U.K. expansion with Sports Purpose as lead partner. | Live, adding local inspection, photography and listing support |
| In June 2026, Nissan's Nismo Heritage program opened orders for 37 more Skyline GT-R parts. | Orders open, with some 3D-printed clips in the range |
| In July 2026, the EU published Regulation (EU) 2026/1738 on vehicle design and end-of-life management. | Published, with vehicles of historical interest excluded from scope |
| In August 2026, Monterey Car Week auctions totaled a record $747.9 million, according to Hagerty. | Completed, including a charity Ferrari that lifted the total |
Data, reissued parts and online formats change ownership
- Sales databases give buyers years of price history, and CLASSIC.COM said in January 2026 that this has narrowed the information gap between buyers and sellers.
- Reissued and 3D-printed parts keep rare models usable, as shown by the printed fuel pipe clips in Nissan's June 2026 Nismo Heritage release.
- Timed online auctions use a seven-day format at Bring a Trailer, where the clock resets with each bid during the final two minutes.
- Valuation indexes turn condition grades into comparable prices, and the Hagerty Price Guide uses a six-step scale from concours down to parts cars.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Auction houses and platforms compete for scarce consignments
Competition centers on winning scarce consignments, because the supply of important cars limits every seller. RM Sotheby's holds the strongest position at the top, with nine of the ten biggest sales of 2025 running through it, according to CLASSIC.COM, and Gooding Christie's took the remaining spot. Broad Arrow, owned by Hagerty, expanded European sales and private treaty in 2025 and pairs them with lending. Mecum works at the volume end, while Bonhams runs smaller specialist sales. Bring a Trailer leads online and is now building a U.K. presence. Manufacturers such as Mercedes-Benz, Ferrari, Lamborghini and Chevrolet do not generally sell these cars, but their heritage models set demand, and Nissan and Honda now support older cars directly with parts programs. Hagerty adds insurance and price guides, which keep owners engaged between sales.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| RM Sotheby's | Auction house | Over $1 billion in 2025 sales; held nine of the ten top sales |
| Gooding Christie's | Auction house | Sold the 1964 Shelby Cobra Daytona Coupe at Monterey in 2026 |
| Broad Arrow Auctions | Auction house and lender | Hagerty unit with auctions, private sales and Broad Arrow Capital |
| Mecum Auctions | Auction house | High-volume sale with 521 lots at Monterey in 2026 |
| Bonhams | Auction house | Smaller specialist sale of 56 lots at Laguna Seca in 2026 |
| Bring a Trailer | Online auction platform | Record 49,486 listings in 2025; expanded to the U.K. in 2026 |
| Hagerty | Insurer and data provider | 2.8 million insured vehicles, Price Guide and Bull Market List |
| Nissan | Manufacturer | Nismo Heritage parts for R32, R33 and R34 Skyline GT-R |
| Honda | Manufacturer | Parts and restoration plan for the first-generation NSX |
| Mercedes-Benz | Heritage brand | W 196 R brought $53.1 million; early G-Class among top 2025 gainers |
Selective buying favors usable, well-documented cars
Credence Research's view is that the market is healthier than its price indexes suggest, but less uniform than its headline totals imply. Volume is setting records while average prices slip, so owners who bought on the assumption of steady appreciation may be disappointed. Classic cars can be a good investment for a selective buyer of documented, usable cars, yet carrying costs and thin liquidity reduce returns. The most useful signals for sellers are sell-through rates by price tier, because a single charity lot can distort a headline total by tens of millions of dollars.
How Credence Research estimated this market
The report uses 2025 as the base year and 2026–2035 as the forecast period. Market values come from the Credence Research model, which brings the earlier published estimate to 2025 with its own growth rate and tests it against public transaction, insurance and registration data. Segment and regional splits are Credence Research estimates built from the same public evidence. Sources are auction house releases, company results, valuation guides, trade press, club surveys and official EU documents opened during research. No interviews or primary surveys were conducted by Credence Research for this edition.
Broader participation should outlast uneven price cycles
Through 2035, the market should grow as newer cars qualify as collectible and as online selling reaches more countries. The value of USD 99.38 billion depends on continued buyer renewal, because Gen X and millennial demand must eventually replace boomer spending at the top of the market. Modern classics should take share from pre-war cars, although the rarest early cars will keep their appeal for museums and major collectors. Trade policy, parts availability and workshop skills are the main risks, and each is likely to matter more than short swings in asset prices.
Frequently Asked Questions
How big is the classic cars market?
Are classic cars a good investment?
What are the main classic car market trends?
How does the vintage car market relate to classic cars?
Which region leads the classic cars market?
How does restoration fit into the market?
Who are the main companies in this market?
Which segment is growing fastest by era?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Condition
- 1.2.1 Good
- 1.2.2 Excellent
- 1.2.3 Concours
- 1.2.4 Fair
- 1.2.5 Poor
- 1.3 By Type
- 1.3.1 Sports Car
- 1.3.2 Coupe
- 1.3.3 Convertible
- 1.3.4 Sedan
- 1.3.5 SUV
- 1.3.6 Truck
- 1.4 By Era
- 1.4.1 Post-War
- 1.4.2 Modern Classic
- 1.4.3 Muscle Car
- 1.4.4 Pre-War
- 1.5 By Drive Train
- 1.5.1 Manual
- 1.5.2 Automatic
- 1.5.3 Semi-Automatic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 43.15 billion → 2035: USD 99.38 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Classic Cars Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Classic Cars Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Classic Cars Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Classic Cars Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Classic Cars Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Classic Cars Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Classic Cars Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Classic Cars Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 43.15 billion → 2035: USD 99.38 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Classic Cars Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Condition - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Good
- 12.3.7.2 Excellent
- 12.3.7.3 Concours
- 12.3.7.4 Fair
- 12.3.7.5 Poor
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sports Car
- 12.4.7.2 Coupe
- 12.4.7.3 Convertible
- 12.4.7.4 Sedan
- 12.4.7.5 SUV
- 12.4.7.6 Truck
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Era - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Post-War
- 12.5.7.2 Modern Classic
- 12.5.7.3 Muscle Car
- 12.5.7.4 Pre-War
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Drive Train - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Manual
- 12.6.7.2 Automatic
- 12.6.7.3 Semi-Automatic
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Classic Cars Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Classic Cars Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Classic Cars Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 RM Sotheby's
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Gooding Christie's
- 17.4 Broad Arrow Auctions
- 17.5 Mecum Auctions
- 17.6 Bonhams
- 17.7 Bring a Trailer
- 17.8 Hagerty
- 17.9 Mercedes-Benz
- 17.10 Chevrolet
- 17.11 Lamborghini
- 17.12 Ferrari
- 17.13 Nissan
- 17.14 Honda
- 17.15 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

