
Market Overview
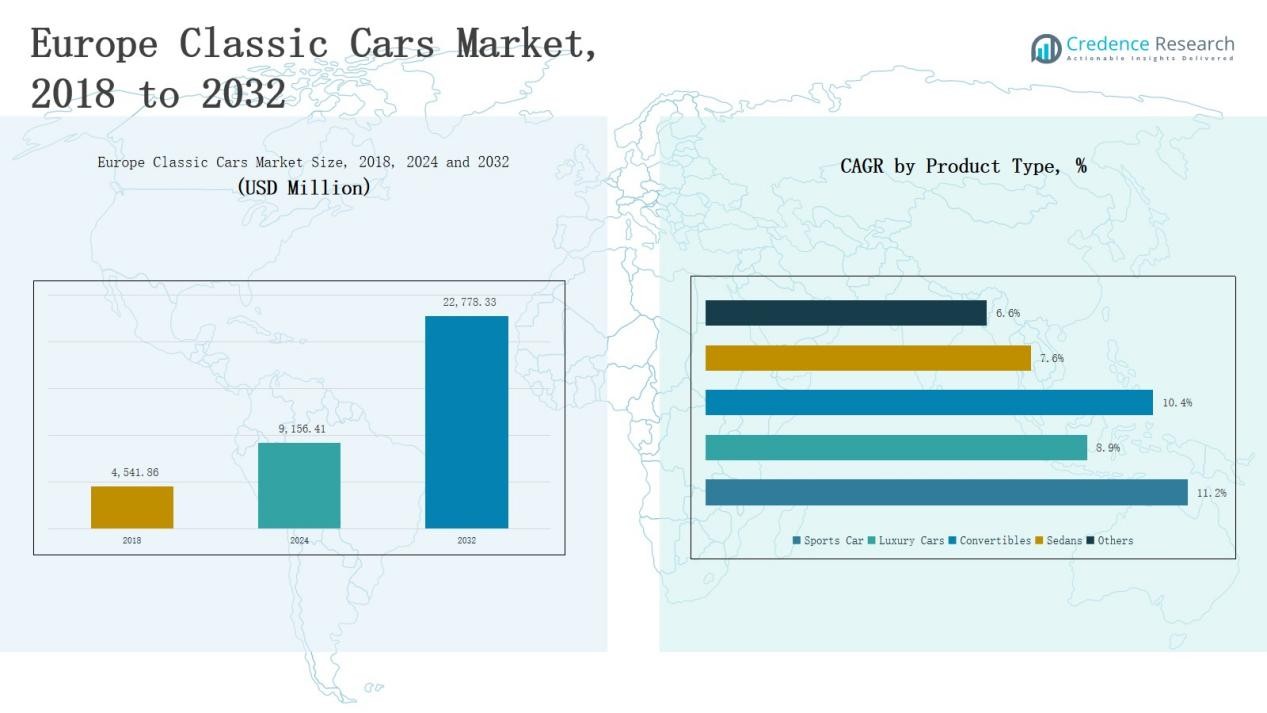
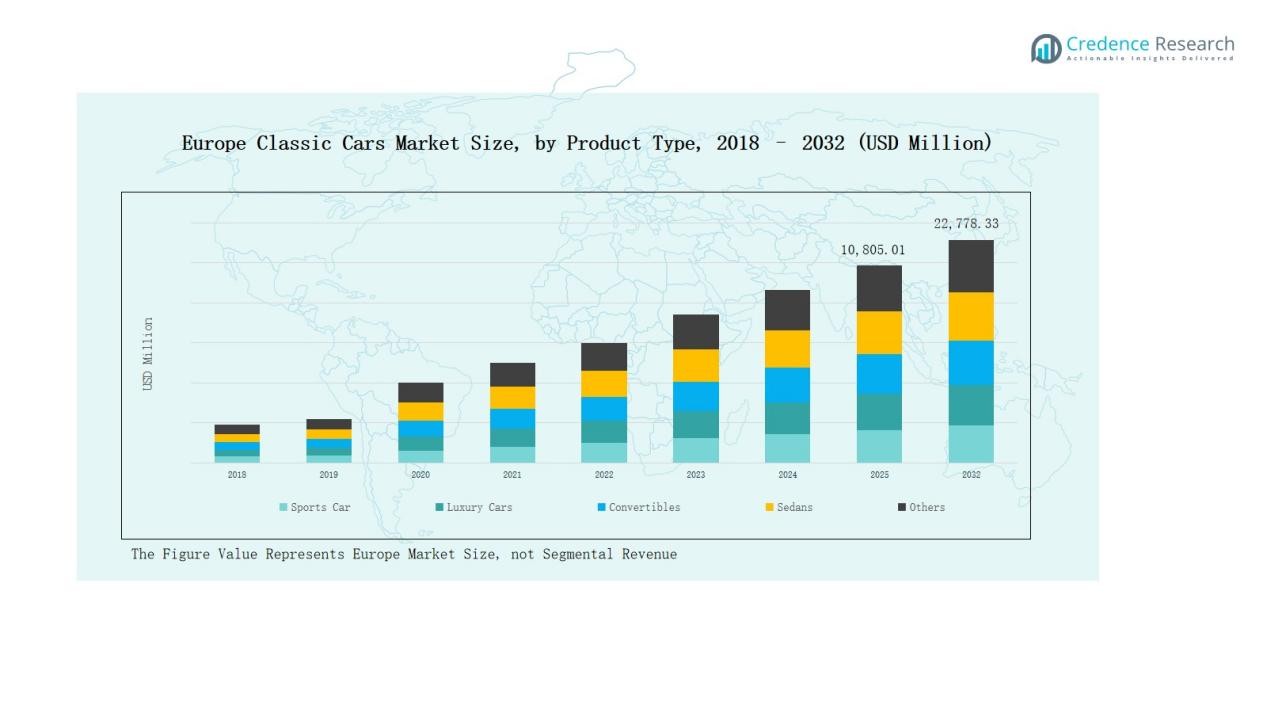
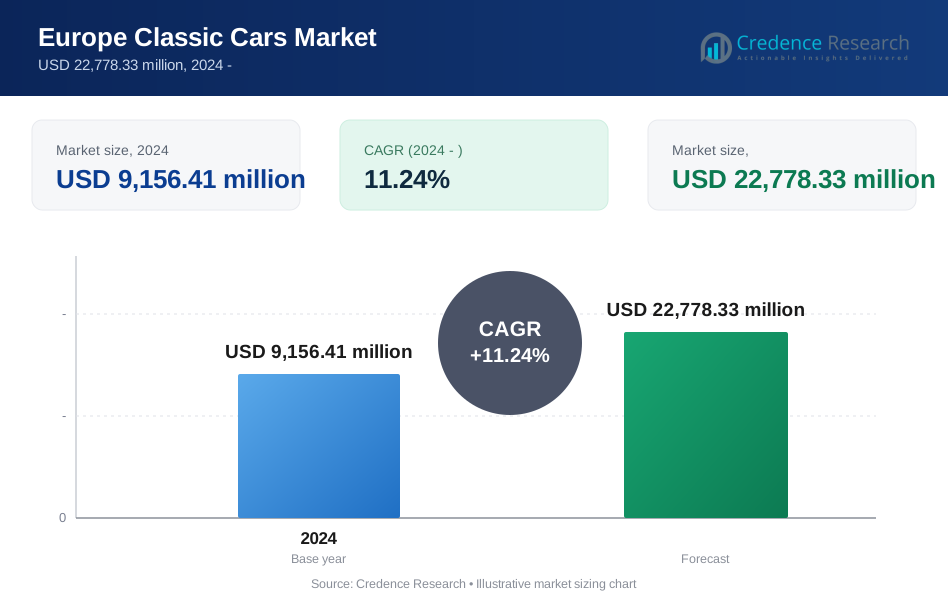
Europe Classic Cars Market size was valued at USD 4,541.86 million in 2018, grew to USD 9,156.41 million in 2024, and is anticipated to reach USD 22,778.33 million by 2032, expanding at a CAGR of 11.24% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Classic Cars Market Size 2024 | USD 9,156.41 Million |
| Europe Classic Cars Market, CAGR | 11.24% |
| Europe Classic Cars Market Size 2032 | USD 22,778.33 Million |
The Europe Classic Cars Market is led by prominent players such as Citroën DS, Chevrolet, Lamborghini, European Vintage Cars (EVC), Cadillac, Toyota, and Carrozzeria Touring Superleggera. These companies hold a strong presence through extensive heritage collections, premium restoration expertise, and active participation in high-value auctions across Europe. Their focus on craftsmanship, authenticity, and limited-edition offerings strengthens brand equity and customer loyalty. The United Kingdom emerged as the leading region in 2024 with a 27% market share, driven by robust collector demand, established auction networks, and rich automotive tradition.
Market Insights
- The Europe Classic Cars Market grew from USD 4,541.86 million in 2018 to USD 9,156.41 million in 2024 and is projected to reach USD 22,778.33 million by 2032, expanding at a CAGR of 11.24%.
- Leading companies include Citroën DS, Chevrolet, Lamborghini, European Vintage Cars (EVC), Cadillac, Toyota, and Carrozzeria Touring Superleggera, focusing on craftsmanship, authenticity, and heritage restoration.
- Sports Cars dominated the market in 2024 with a 36% share, driven by high collector demand, iconic designs, and limited production exclusivity.
- The High price range segment led with a 62% share, supported by strong investor interest in rare, high-value collectible vehicles.
- The United Kingdom emerged as the leading region with a 27% share in 2024, followed by Germany at 22% and France at 15%, reflecting strong collector culture and established auction networks across these nations.
Market Segment Insights
By Type
Sports Cars dominated the Europe Classic Cars Market in 2024 with a 36% share. Their strong demand stems from the region’s deep automotive heritage, collector enthusiasm, and high resale value. Brands such as Ferrari, Lamborghini, and Porsche drive interest with timeless engineering and iconic designs. The segment benefits from limited production runs and exclusivity, attracting wealthy collectors. Growing investments in car restoration and vintage rallies further strengthen demand for classic sports cars across major European countries.
- For instance, Ferrari showcased a meticulously restored 1962 Ferrari 250 GTO at the Concorso d’Eleganza Villa d’Este in Italy, which later fetched over USD 50 million at a private auction, underscoring continued appreciation for vintage sports models.
By Price Range
The High price range segment led the Europe Classic Cars Market in 2024, capturing a 62% share. This dominance reflects strong interest among affluent buyers and investors seeking rare models with proven appreciation value. Classic vehicles priced above USD 100,000 often offer authenticity, heritage, and craftsmanship. Auction houses and premium dealers drive visibility through exclusive sales. Rising demand for collectible assets as alternative investments continues to support growth in the high-value classic car category.
- For instance, at the 2024 Monterey Auction, several high-value classic cars sold well above USD 100,000, reflecting robust demand in exclusive auctions.
By Distribution Channel
Auction Houses accounted for the largest share of the Europe Classic Cars Market in 2024, holding 40% of total revenue. Their dominance is driven by credibility, transparency, and access to rare, high-value models. Reputed auction brands like Bonhams, RM Sotheby’s, and Barrett-Jackson attract global bidders. Digital auction platforms are also expanding participation from remote buyers. The segment’s growth is supported by increased online bidding adoption, high-profile events, and rising investor confidence in classic car assets.
Key Growth Drivers
Rising Collector and Investor Interest
The Europe Classic Cars Market is experiencing steady growth due to increasing interest from collectors and investors. Classic cars are viewed as tangible assets with strong appreciation potential, offering higher long-term returns than traditional investments. Wealthy buyers across the UK, Germany, and France are driving demand for rare and historically significant models. Auction records, exclusive events, and private collections highlight this shift toward classic vehicles as both lifestyle and financial investments, reinforcing steady market expansion.
- For instance, auction houses across Europe report a steady rise in sales volumes and prices for rare vintage models with documented histories, particularly those from brands like Ferrari and Porsche, attracting buyers seeking investment-grade vehicles
Expanding Classic Car Restoration and Maintenance Industry
The growing network of professional restoration facilities and vintage car workshops across Europe supports the market’s expansion. Skilled craftsmanship, availability of original parts, and technological improvements in restoration processes enhance the appeal of older models. Companies are focusing on authenticity and performance upgrades while preserving heritage value. This rise in specialized service providers has made ownership more sustainable and reliable, encouraging more enthusiasts and investors to acquire and maintain collectible vehicles for long-term appreciation.
- For instance, Porsche Classic in Germany is renowned for its authentic restoration services that focus on preserving the heritage and enhancing the performance of classic Porsche models, using original parts and precision craftsmanship.
Increasing Popularity of Classic Car Events and Auctions
High-profile auctions and classic car events across Europe, such as the Goodwood Revival and Retromobile Paris, drive both visibility and demand. These gatherings attract global buyers, media attention, and sponsorship, creating a thriving ecosystem for trade and networking. Auction houses continue to expand both physical and digital participation, making vintage car ownership accessible to a wider audience. This event-driven engagement strengthens the region’s reputation as a global hub for collectible and historic automobiles.
Key Trends & Opportunities
Growth of Digital Auction Platforms
Digital transformation has reshaped how collectors buy and sell vintage cars across Europe. Online platforms like Collecting Cars and Bring a Trailer have simplified transactions, offering verified listings and global reach. This digital shift increases transparency, attracts younger investors, and ensures real-time participation in high-value auctions. As buyers gain confidence in online valuations and secure payment systems, the adoption of digital marketplaces is expected to further accelerate growth in the classic car trading segment.
- For instance, Autobid.de, conducts up to 4,500 B2B auctions weekly, serving dealers across Europe with vehicles from leasing companies and fleet operators, ensuring a wide and reliable selection.
Rising Demand for Electrified Restorations
A growing trend in the Europe Classic Cars Market is the integration of electric powertrains into classic vehicles. Companies are offering electric conversions that retain the vehicle’s exterior charm while improving performance and sustainability. This appeals to environmentally conscious collectors and urban drivers facing emission restrictions. The shift blends nostalgia with innovation, expanding the market’s reach. Electric restomods are positioning classic vehicles as future-proof investments without sacrificing their historical appeal or aesthetic value.
- For instance, Electric Classic Cars, a U.K.-based company, has successfully converted over 100 classic vehicles, including models like the VW Beetle and Ferrari 308, into electric-powered cars that preserve their iconic look while enhancing drivability and sustainability.
Key Challenges
High Maintenance and Restoration Costs
Owning and maintaining a classic car in Europe often involves substantial expense. Original parts are scarce, and restoration requires skilled labor and authentic materials, which raise costs significantly. Insurance premiums for rare models are also high due to valuation risks. These financial challenges limit ownership to affluent buyers and investors. As maintenance costs continue to climb, the market may face slower adoption among younger enthusiasts with limited financial resources.
Regulatory Restrictions on Emissions and Road Use
Stricter European environmental regulations pose a challenge for vintage vehicles that rely on older, high-emission engines. Cities such as Paris and London have introduced low-emission zones restricting classic car movement. This impacts usage frequency and potential resale value. Although exemptions exist for historic models, uncertainty around future laws affects buyer confidence. The classic car community continues to advocate for balanced policies to protect automotive heritage while meeting sustainability goals.
Counterfeit Parts and Authenticity Concerns
The Europe Classic Cars Market faces challenges from counterfeit parts and inaccurate documentation, which affect buyer trust and asset valuation. Unscrupulous restorers may use imitation components or falsify vehicle history, reducing authenticity. This risk is particularly high in private transactions and cross-border sales. Reputable certification bodies and auction houses are implementing stricter verification procedures. However, ensuring complete transparency across the fragmented market remains difficult, posing ongoing risks to collectors and investors.
Regional Analysis
United Kingdom
The United Kingdom dominated the Europe Classic Cars Market in 2024 with a 27% share. It benefits from a rich automotive heritage and strong collector culture. The country hosts prestigious events like Goodwood Revival and London Classic Car Show, attracting global buyers. Prominent auction houses, restoration centers, and heritage clubs sustain market growth. High disposable income and tax incentives for classic vehicles further boost investment. It continues to lead in both vintage sports and luxury car segments across Europe.
Germany
Germany accounted for a 22% share of the Europe Classic Cars Market in 2024. Its long-standing manufacturing excellence and passion for engineering drive collector interest in brands like Mercedes-Benz, BMW, and Porsche. Restoration workshops and specialized dealerships across Stuttgart, Munich, and Hamburg enhance accessibility. The market benefits from strict preservation standards and strong automotive associations. It remains a major exporter of collectible models, attracting global investors seeking performance and authenticity in vintage vehicles.
France
France captured a 15% share of the Europe Classic Cars Market in 2024. It is home to iconic marques such as Citroën, Peugeot, and Renault, known for timeless design and craftsmanship. The Retromobile event in Paris remains a major driver of classic car demand and trade activity. Restoration and customization services are widely available, ensuring steady market development. It continues to attract both domestic collectors and international buyers interested in classic European aesthetics.
Italy
Italy represented a 14% share of the Europe Classic Cars Market in 2024. Its dominance in the sports and luxury car category stems from legendary brands such as Ferrari, Lamborghini, and Alfa Romeo. Italian craftsmanship, design heritage, and brand prestige attract high-net-worth individuals. Strong demand for restoration of vintage models reinforces its growth. The country’s scenic routes and cultural events create an ideal ecosystem for classic car exhibitions and tourism-linked ownership.
Spain
Spain held an 11% share of the Europe Classic Cars Market in 2024. Interest in collectible vehicles is growing among enthusiasts and investors. Rising tourism and vintage car rallies are driving sales across the country. Restoration shops and dealership networks are expanding to serve growing demand. It is becoming a regional hub for mid-priced collectible models and emerging investors. Favorable weather conditions also support year-round use and preservation of classic automobiles.
Russia and Rest of Europe
Russia and the Rest of Europe together accounted for an 11% share of the Europe Classic Cars Market in 2024. Interest in luxury and performance models is rising among affluent buyers in Eastern Europe. Cross-border sales and online auctions connect these regions to Western European suppliers. Limited restoration infrastructure remains a challenge, but growing import activity supports expansion. It continues to gain traction as collectors seek investment opportunities beyond traditional markets.
Market Segmentations:
By Type
- Sports Cars
- Luxury Cars
- Convertibles
- Sedans
- Others
By Price Range
- High
- Low & Medium
By Distribution Channel
- Auction Houses
- Classic Car Dealerships
- Online Platforms
- Car Shows & Events
- Others
By Region
- United Kingdom
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe Classic Cars Market features a moderately consolidated landscape with a mix of global automakers, restoration specialists, and auction houses. Leading players such as Citroën DS, Chevrolet, Lamborghini, European Vintage Cars (EVC), Cadillac, Toyota, and Carrozzeria Touring Superleggera dominate through strong brand heritage, limited-edition models, and exclusive restoration programs. These companies focus on preserving authenticity while offering modernized restoration and maintenance services. Auction houses play a major role in shaping pricing trends and buyer sentiment through high-value sales events. Strategic collaborations with restoration experts, collector clubs, and digital auction platforms have enhanced customer reach and trust. The competitive environment is defined by craftsmanship quality, vehicle originality, and after-sales service excellence. Continuous innovation in electrified restomods, expanded dealership networks, and digital trade participation are strengthening the market’s structure and helping established players maintain leadership across the premium and collectible automobile segments in Europe.
Key Players
- Citroën DS
- Chevrolet
- Lamborghini
- European Vintage Cars (EVC)
- Cadillac
- Toyota
- Carrozzeria Touring Superleggera
Recent Developments
- In July 2025, Fiera Milano and IEG acquired a 70% stake in EMAC, a company specializing in organizing classic car trade shows across Europe.
- In May 2025, Gooding Christie’s and Rétromobile (Comexposium) announced a multi-year partnership, making Gooding Christie’s the official auction partner for Rétromobile Paris and a new U.S. event.
- In 2024, Christie’s completed the acquisition of Gooding & Company, a leading classic-car auction house, to expand its footprint in the global collector car market.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Material Composition, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for rare and historically significant vehicles will continue to rise among collectors.
- Digital auction platforms will expand accessibility and attract younger investors.
- Electric conversions of vintage models will gain popularity across European markets.
- Restoration technology will improve efficiency and reduce costs for classic car maintenance.
- Cross-border trade of collectible vehicles will increase through online and hybrid auctions.
- Heritage-driven tourism and rally events will strengthen brand value and community engagement.
- Partnerships between manufacturers and restoration firms will enhance authenticity and quality.
- Government policies may evolve to support sustainable preservation of vintage vehicles.
- Rising disposable income and investment diversification will support long-term market growth.
- Enhanced verification and certification systems will improve buyer confidence and market transparency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Classic Cars Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Classic Cars Market projected to grow between 2025 and 2032?
Which Europe Classic Cars Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Classic Cars Market?
Who are the leading companies in the Europe Classic Cars Market?
Which region commanded the largest share of the Europe Classic Cars Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Classic Cars Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Classic Cars Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 9,156.41 million → forecast year: USD 22,778.33 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Classic Cars Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Classic Cars Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Classic Cars Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Classic Cars Market Drivers
- 3.3 Europe Classic Cars Market Restraints & Challenges
- 3.4 Europe Classic Cars Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Classic Cars Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Classic Cars Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Classic Cars category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Classic Cars Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Classic Cars Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Classic Cars market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Classic Cars Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Classic Cars Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Classic Cars Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Classic Cars (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Classic Cars Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Classic Cars Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Classic Cars Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Classic Cars Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Classic Cars Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Classic Cars Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Classic Cars Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Classic Cars Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Classic Cars Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
