
Auctions and online sales define U.S. collector demand
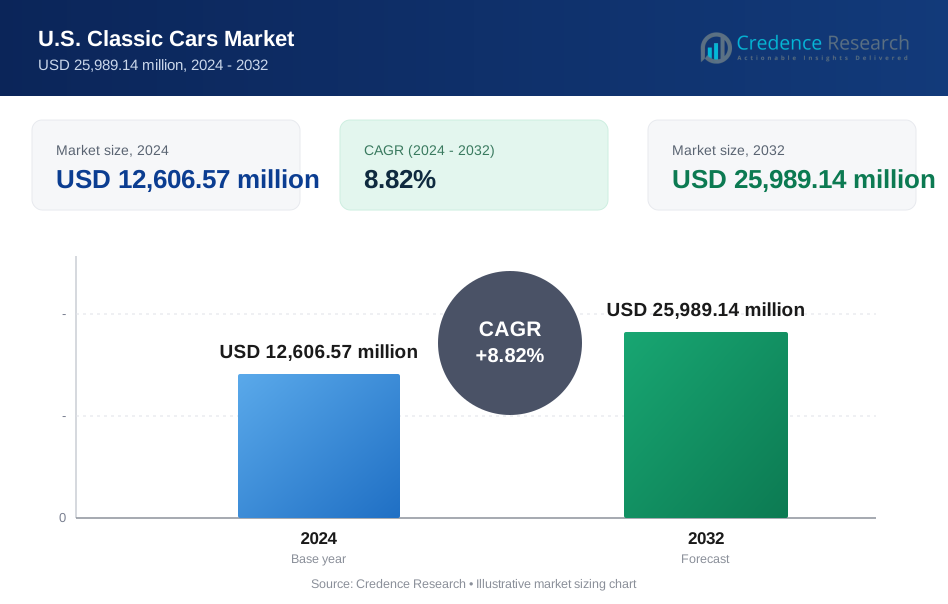
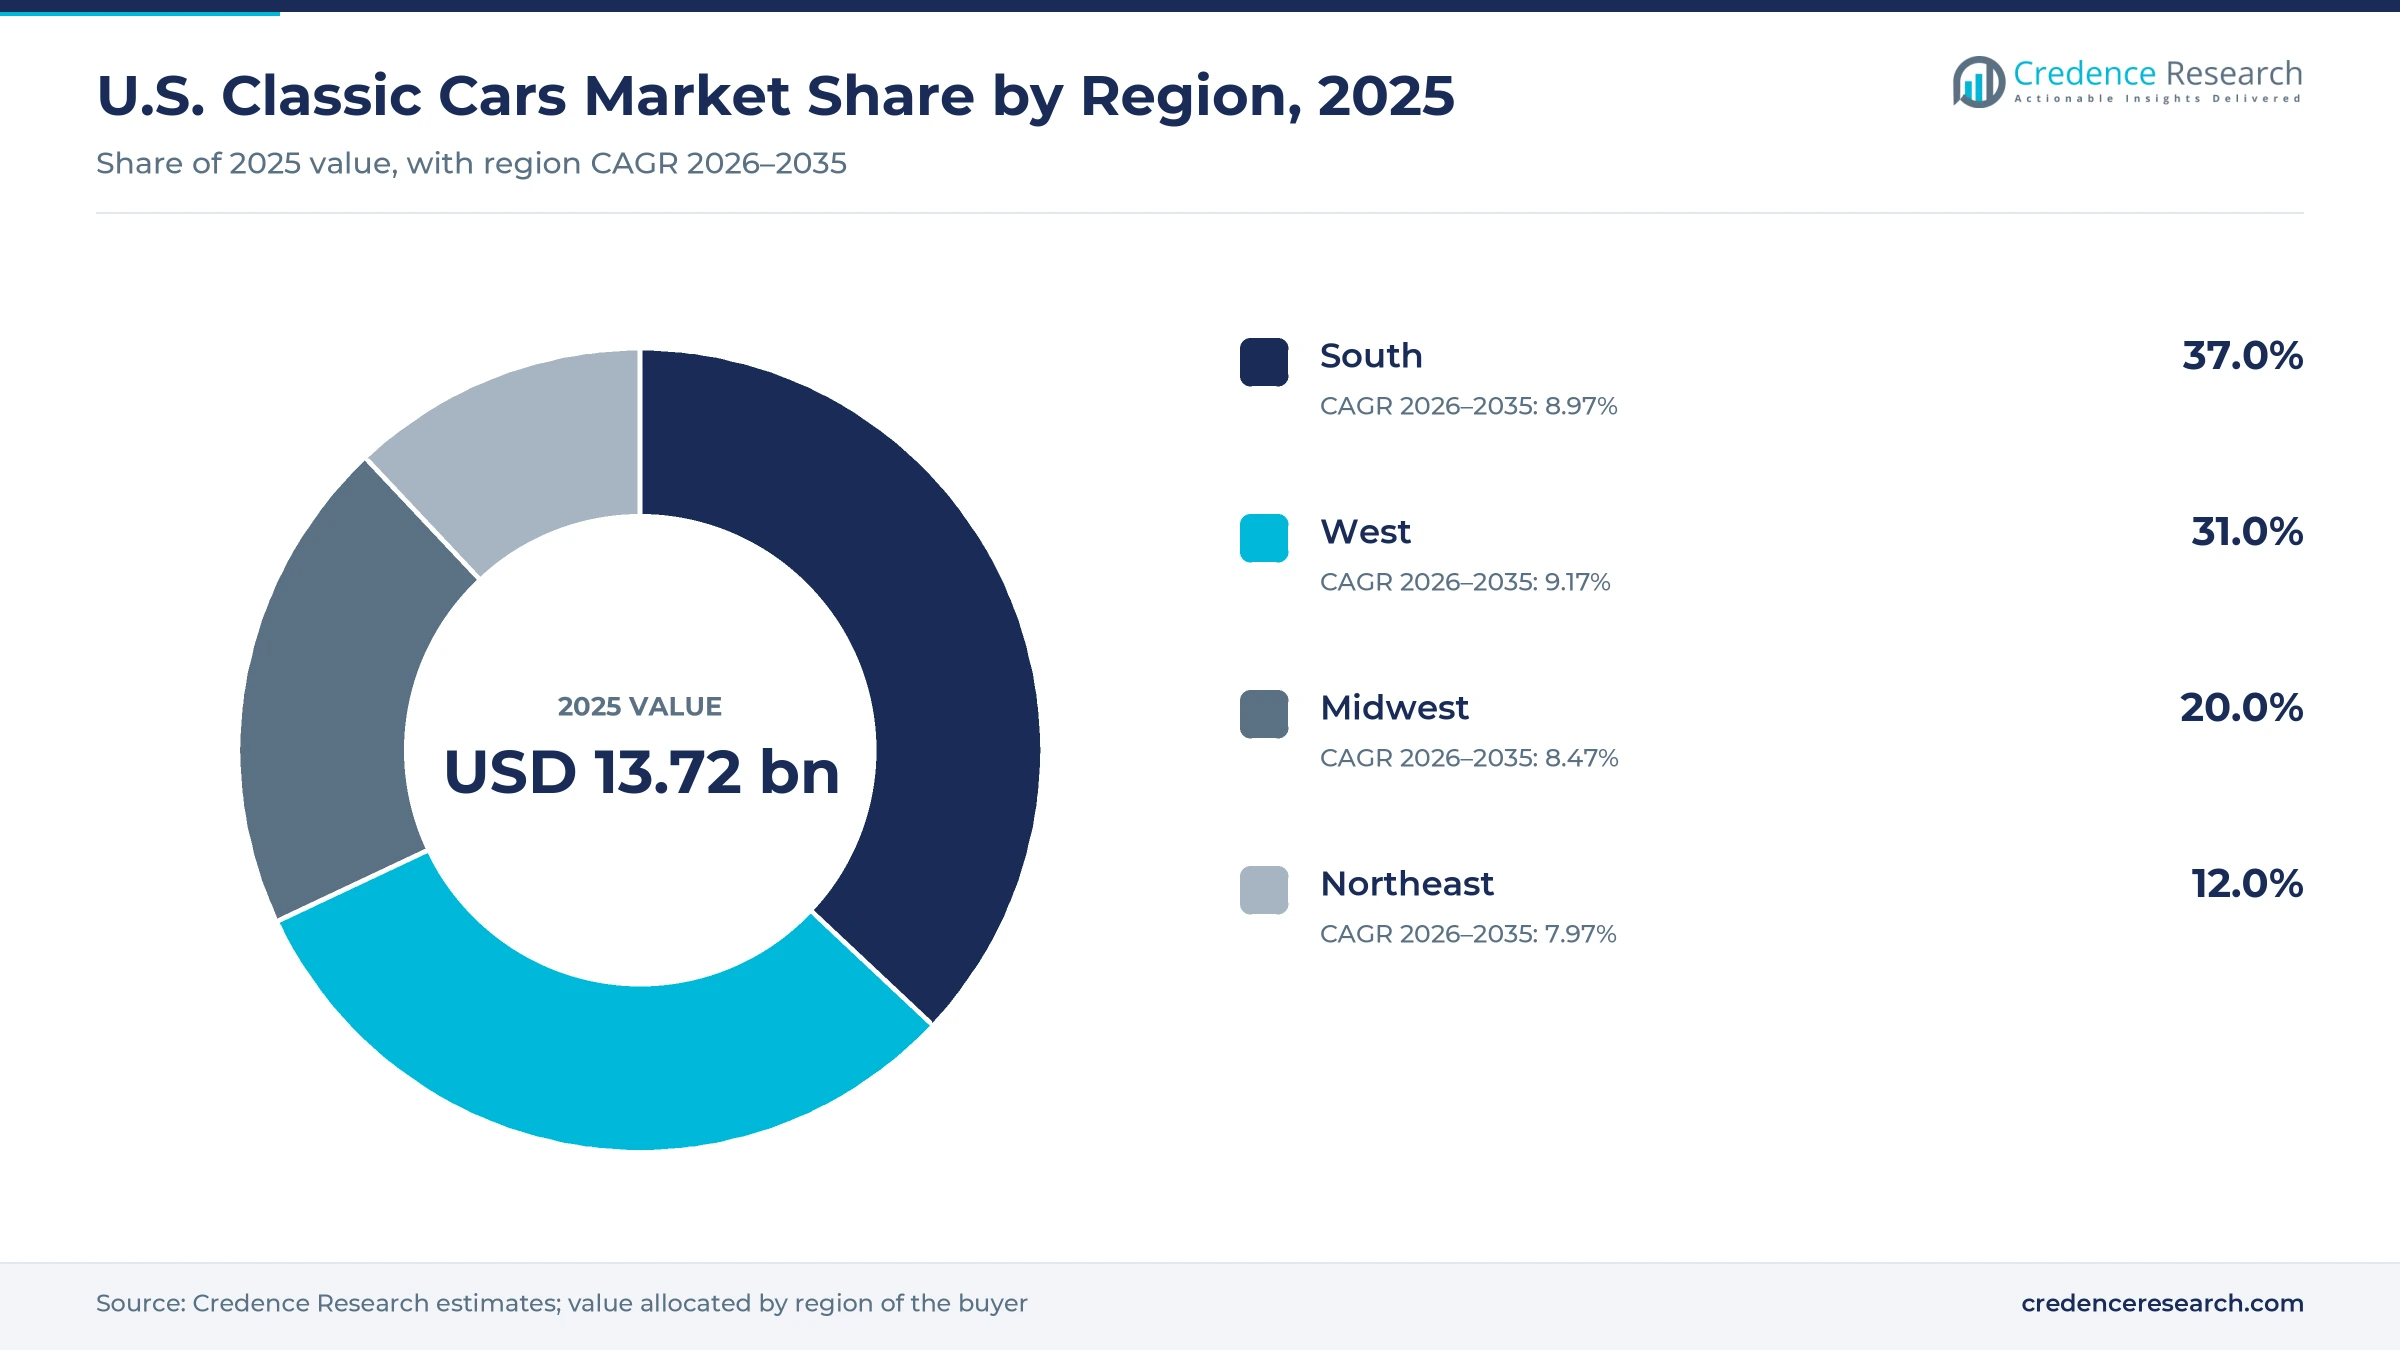
The U.S. classic cars market was valued at USD 13.72 billion in 2025 and is projected to increase from USD 14.93 billion in 2026 to USD 31.94 billion by 2035, registering a CAGR of 8.82% during 2026–2035. Demand comes from collectors, investors and restorers buying through auction houses, online platforms, dealerships and private sales. The South held the largest regional share, 37.0% in 2025, because Florida hosts the Kissimmee and Amelia sales and Texas adds a large registered fleet. The West is the fastest-growing region at 9.2% a year, as Monterey Car Week and Scottsdale keep drawing the highest-value consignments. Prices are moving in two directions, since seven-figure cars set records in 2026 while mainstream values slid. One commercial change stands out, because online auctions passed the $2 billion mark in 2025, according to Classic.com. A federal exemption for vehicles at least 25 years old also kept older imports outside the 25% auto tariff.
What does the U.S. classic cars market count, and who buys?
The market counts the value of classic, collector and modern collectible vehicles sold in the United States through auction houses, online platforms, dealerships, events and private transactions. Buyers range from first-time enthusiasts purchasing an affordable driver to private collectors bidding eight figures for a historic race car. Hagerty, the specialty insurer, estimates that the country holds about 43 million classic cars worth more than $1 trillion, so only a small part of that stock changes hands each year.
Insurance premiums, storage, parts, restoration labor and new vehicles sold for charity or as limited editions are excluded from the market value. However, those services shape demand, because restoration costs and insurance access decide how many owners keep, upgrade or sell a car. The value chain runs from original owners and estates through consignment specialists and auction houses to collectors, restorers and financing providers.
U.S. Classic Cars Market Insights
- The U.S. classic cars market is projected to grow from USD 13.72 billion in 2025 to USD 31.94 billion by 2035, at an 8.82% CAGR over 2026–2035.
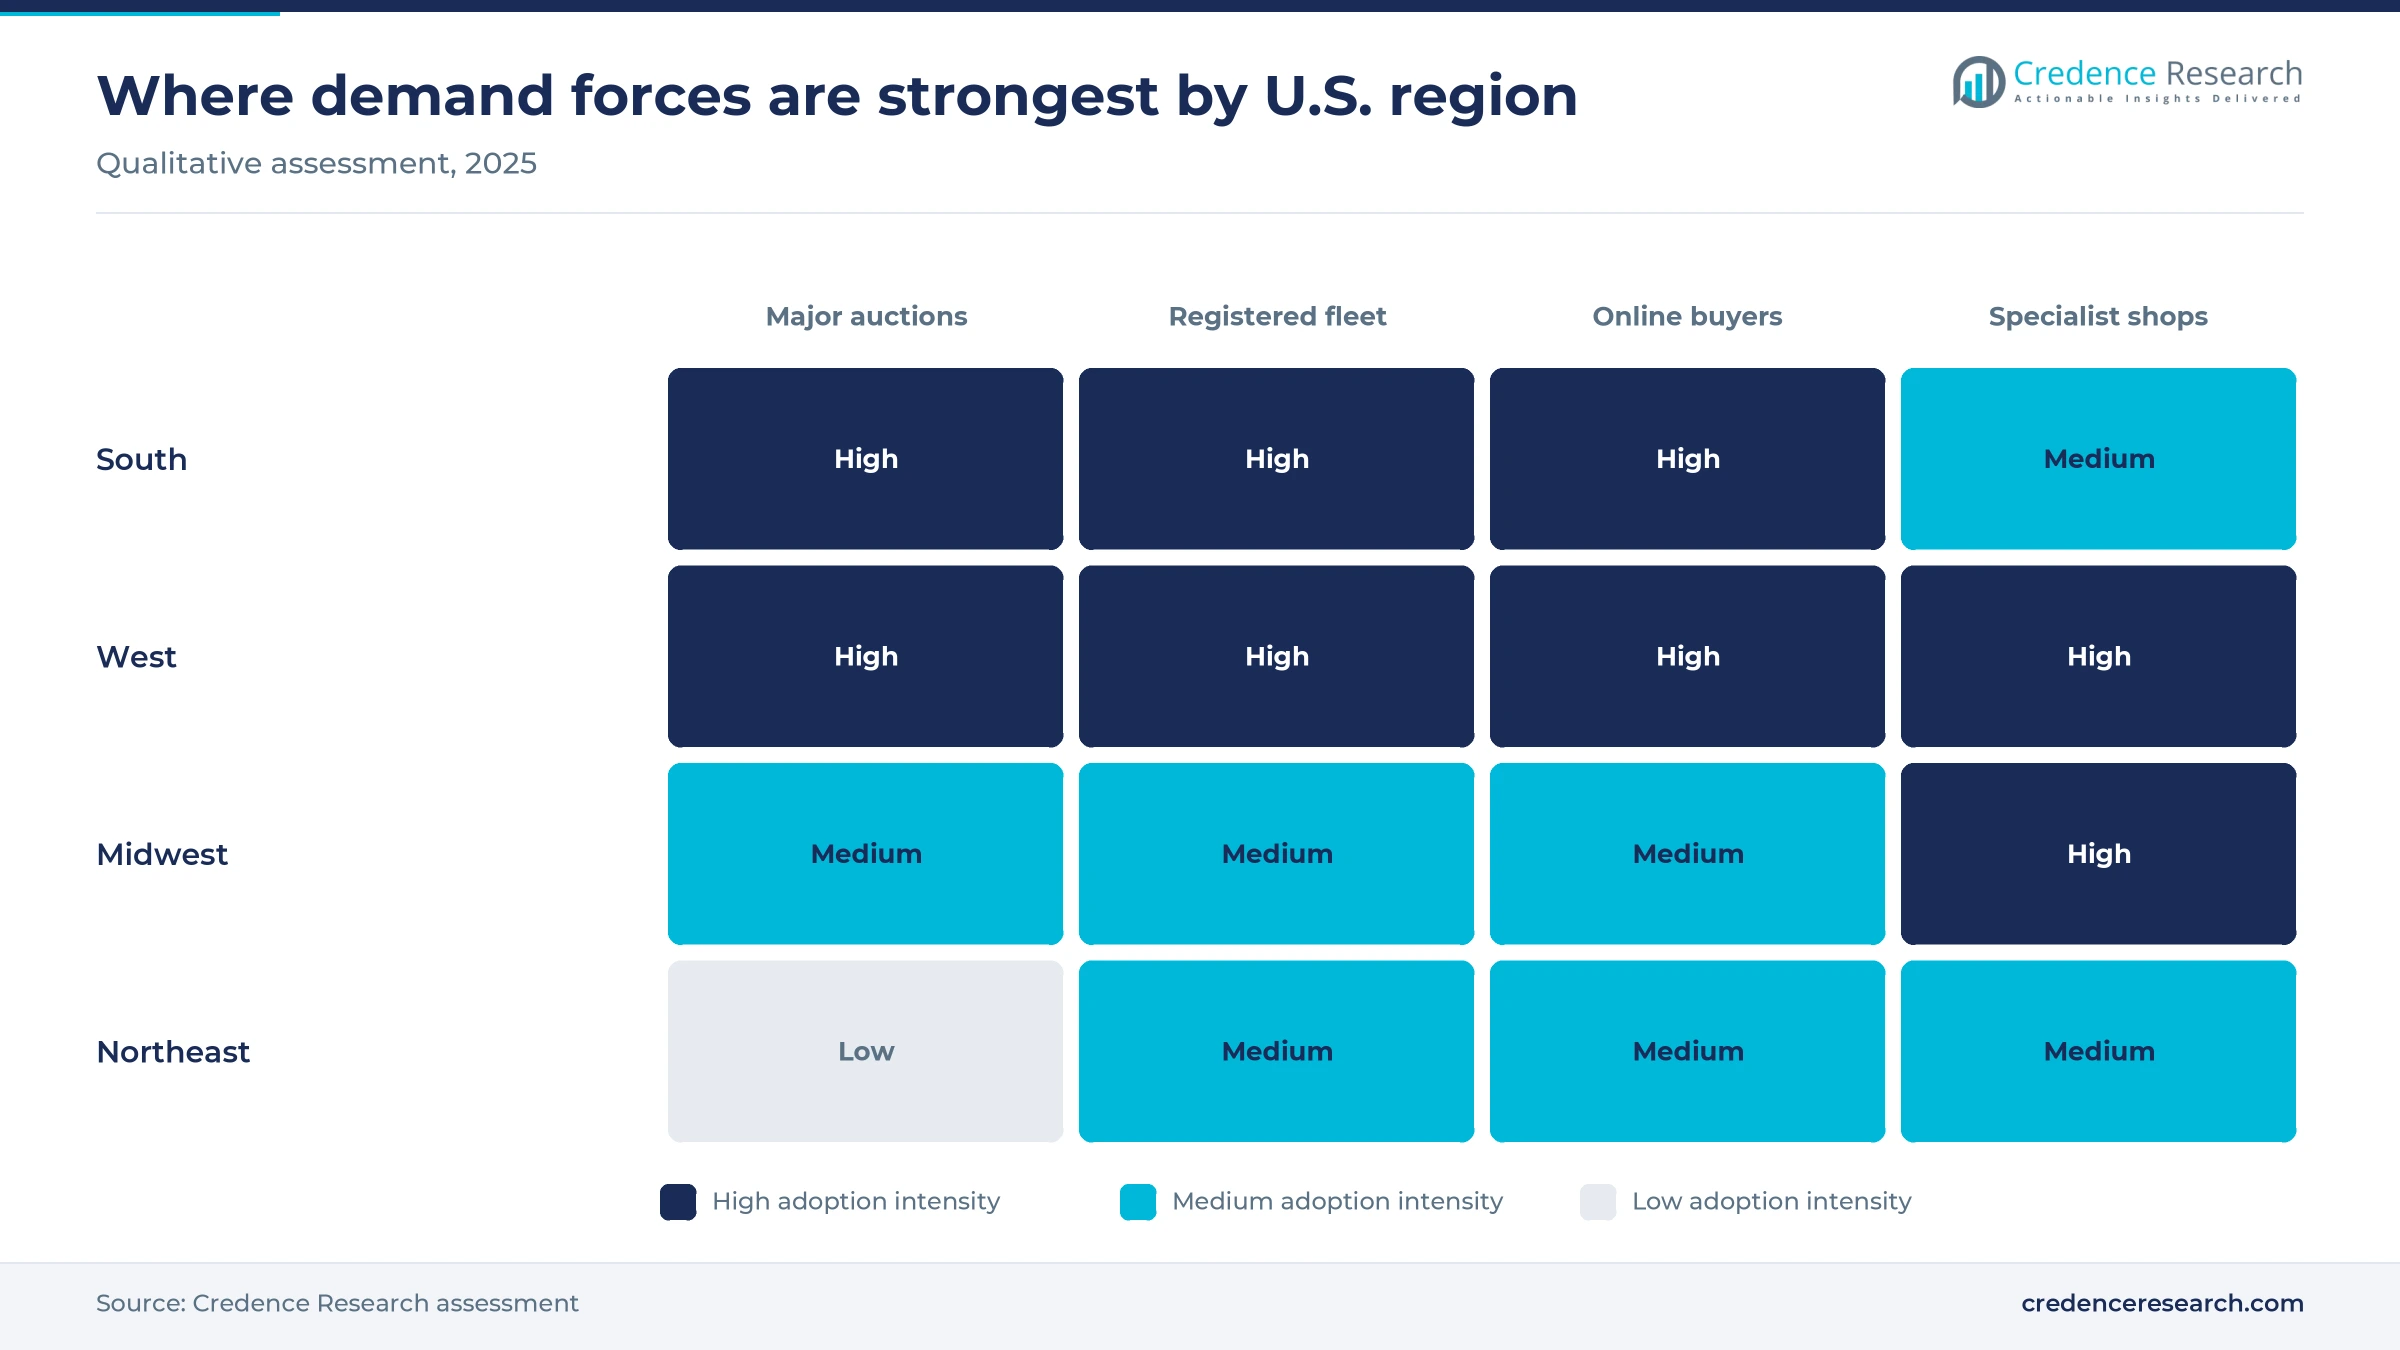
- The South held 37.0% of 2025 value, supported by Florida auctions, while the West grows fastest at 9.2% a year.
- Sports Cars led the type group with 41.0% of 2025 value, as coupes and supercars dominated the top results of major U.S. sales.
- Monterey Car Week auctions reached $747.9 million in August 2026, up 73% from 2025, according to Motorious, while mainstream values kept sliding.
- Bring a Trailer sold more than $1.7 billion in 2025, which puts online platforms in direct competition with auction houses for consignments.
Sports cars lead while online platforms grow fastest
Why do sports cars lead the U.S. collector market?
Based on type, the market is categorized into sports cars, luxury cars, convertibles, sedans and others. Sports Cars led with 41.0% of 2025 value because performance coupes command the highest prices, led at Monterey in August 2026 by a 1964 Shelby Cobra Daytona Coupe at $42,905,000, according to Motorious. The Others group, which holds trucks, SUVs and wagons, grows fastest at 9.5% a year, as Hagerty's Truck and SUV Index rose 2% in early 2026 while its British Car Index fell 6%, according to Collectors Car World in April 2026.
How does value divide between high and mainstream prices?
Based on price range, the market is categorized into high and low and medium tiers. Low & Medium led with 56.0% of 2025 value because most transactions involve ordinary collector cars, and the median U.S. auction sale was just $26,513 in January 2026, according to Motorious citing Hagerty. The High tier grows fastest at 9.5% a year, as money is concentrating at the top. Classic.com data cited by Borro in April 2026 showed first-quarter dollar volume up 31% and average prices up 27% on similar listing counts.
Why are custom builds the fastest restoration category?
Based on restoration level, the market is categorized into original condition, partial restoration, full restoration and custom restored. Partial Restoration led with 36.0% of 2025 value because most cars are maintained and improved in stages, and McKeel Hagerty counted about 48 million enthusiast vehicles in May 2025, far more than specialist shops could fully rebuild. Custom Restored vehicles grow fastest at 10.0% a year, as buyers pay heavily for modern engineering. Barrett-Jackson reported in February 2025 that a 1969 Chevrolet Nova custom coupe called Cha Cha Nova sold for $803,000.
Which sales channels handle the most collector value?
Based on distribution channel, the market is categorized into auction houses, classic car dealerships, online platforms, car shows and events, and others. Auction Houses led with 32.0% of 2025 value because headline sales concentrate liquidity, and New Atlas reported $441 million gross from 13 days at Mecum Kissimmee in January 2026. Online Platforms grow fastest at 10.5% a year, as remote bidding widens the buyer pool. Classic.com reported that online sell-through climbed to 68% in 2025 from 62% in 2024, with volume crossing $2 billion.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Sports Cars | 41.0% | Others | 9.5% |
| By Price Range | Low & Medium | 56.0% | High | 9.5% |
| By Restoration Level | Partial Restoration | 36.0% | Custom Restored | 10.0% |
| By Distribution Channel | Auction Houses | 32.0% | Online Platforms | 10.5% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Record auctions, insurance and exemptions lift demand
Record top-end auctions pull consignments and new capital
High-end sales are the clearest source of market growth, because record prices draw collections out of private garages and attract new capital. Motorious reported in August 2026 that Monterey Car Week auctions reached $747.9 million, up 73% from $432.8 million in 2025, on 844 cars sold from 1,124 lots. Borro's April 2026 review put Amelia Island sales near $180 million, against about $129 million a year earlier. New Atlas reported more than 140,000 attendees at Mecum Kissimmee in January 2026, when a 1962 Ferrari 250 GTO brought $38.5 million. As a result, auction houses have stronger arguments when competing for the next major estate.
Online auctions widen the national pool of bidders
Online platforms have removed the need to travel to a sale, which brings more bidders to ordinary collector cars. Bring a Trailer sold more than $1.7 billion across 49,486 listings in 2025, according to THE SHOP, with an 81% sell-through rate. Its registered community reached 1.65 million users after adding more than 255,000 during the year. This reach also lifts expensive consignments, because a 2014 Ferrari LaFerrari sold on the site for $4,475,000 in 2025. Online Platforms are therefore the fastest-growing channel at 10.5% a year. Hagerty's own marketplace reported private sales of $286.8 million in 2025, which shows that established insurers now also want a share of these transactions.
Specialty insurance and lending keep more owners active
Specialty coverage and lending lower the cost of holding a collector vehicle, and that keeps more owners in the market. Hagerty reported 2,819,179 insured vehicles at the end of 2025, up 9.4% from a year earlier, with 929,895 paid Drivers Club members. Its new insurance business count rose 33.3%, while a State Farm program reached 27 states in 2025. This specialty book of 1,684,935 policies sits apart from mainstream auto insurance, because it is built around collector vehicles rather than daily transport. Broad Arrow Capital also lifted its loan portfolio 81.4% to $103.3 million in 2025, which gives collectors another source of financing when bidding at auctions.
The 25-year tariff exemption protects older imports
Federal trade policy has left older vehicles in a favorable position, which supports imports and domestic values together. Customs guidance reported by Insurance Journal in April 2025 exempted passenger vehicles at least 25 years old from the 25% tariff imposed on March 26, 2025, leaving them at the existing 2.5% duty. Silver Tiger Logistics told the publication that it imports about 1,000 collectible cars a year. Later models remain exposed, including the 2010 Nissan GT-R cited in the same report. Each January, another model year crosses the threshold, so 2001 vehicles qualify in 2026. Because of this rule, Credence Research expects steady import supply for buyers of 1990s Japanese and European performance cars.
A split market favors supercars and younger classics
A two-speed market splits top-end and mainstream prices
Classic car prices are falling in the middle of the market even as the top sets records, so the answer depends on the price tier. Motorious reported in January 2026 that the Hagerty Market Rating fell to 58.28, its lowest level in nearly 15 years, after declining in 37 of the prior 43 months. Hagerty's Supercar Index, however, rose 19% in three months, with the Ferrari Enzo up 109%, according to Collectors Car World in April 2026. Its American Muscle Car Index was down only 1% over 12 months, while the 1950s American index lost 8%. Cars in the High tier grow at 9.5% a year as a result, and sellers now price each tier differently.
Emerging demand for 1980s, 1990s and 2000s collectibles
Buyer interest is moving toward cars that younger collectors remember from their own early years, which is changing what auction houses seek out. Hagerty's RADindex, which averages 21 collectible vehicles from the 1980s and 1990s, stood at an all-time high in April 2026, according to Collectors Car World, while the British Car Index touched a five-year low. Classic.com also described building interest in 1980s and 1990s cars in its 2025 review. THE SHOP reported in December 2024 that the Datsun 280ZX had gained 138% since 2019 and the DeLorean DMC-12 more than 73% on Hagerty's Bull Market list. However, boomers rebounded to 36% of Hagerty quotes at the end of 2025, so older buyers remain an important source of bids.
Opportunity in new regional auction calendars
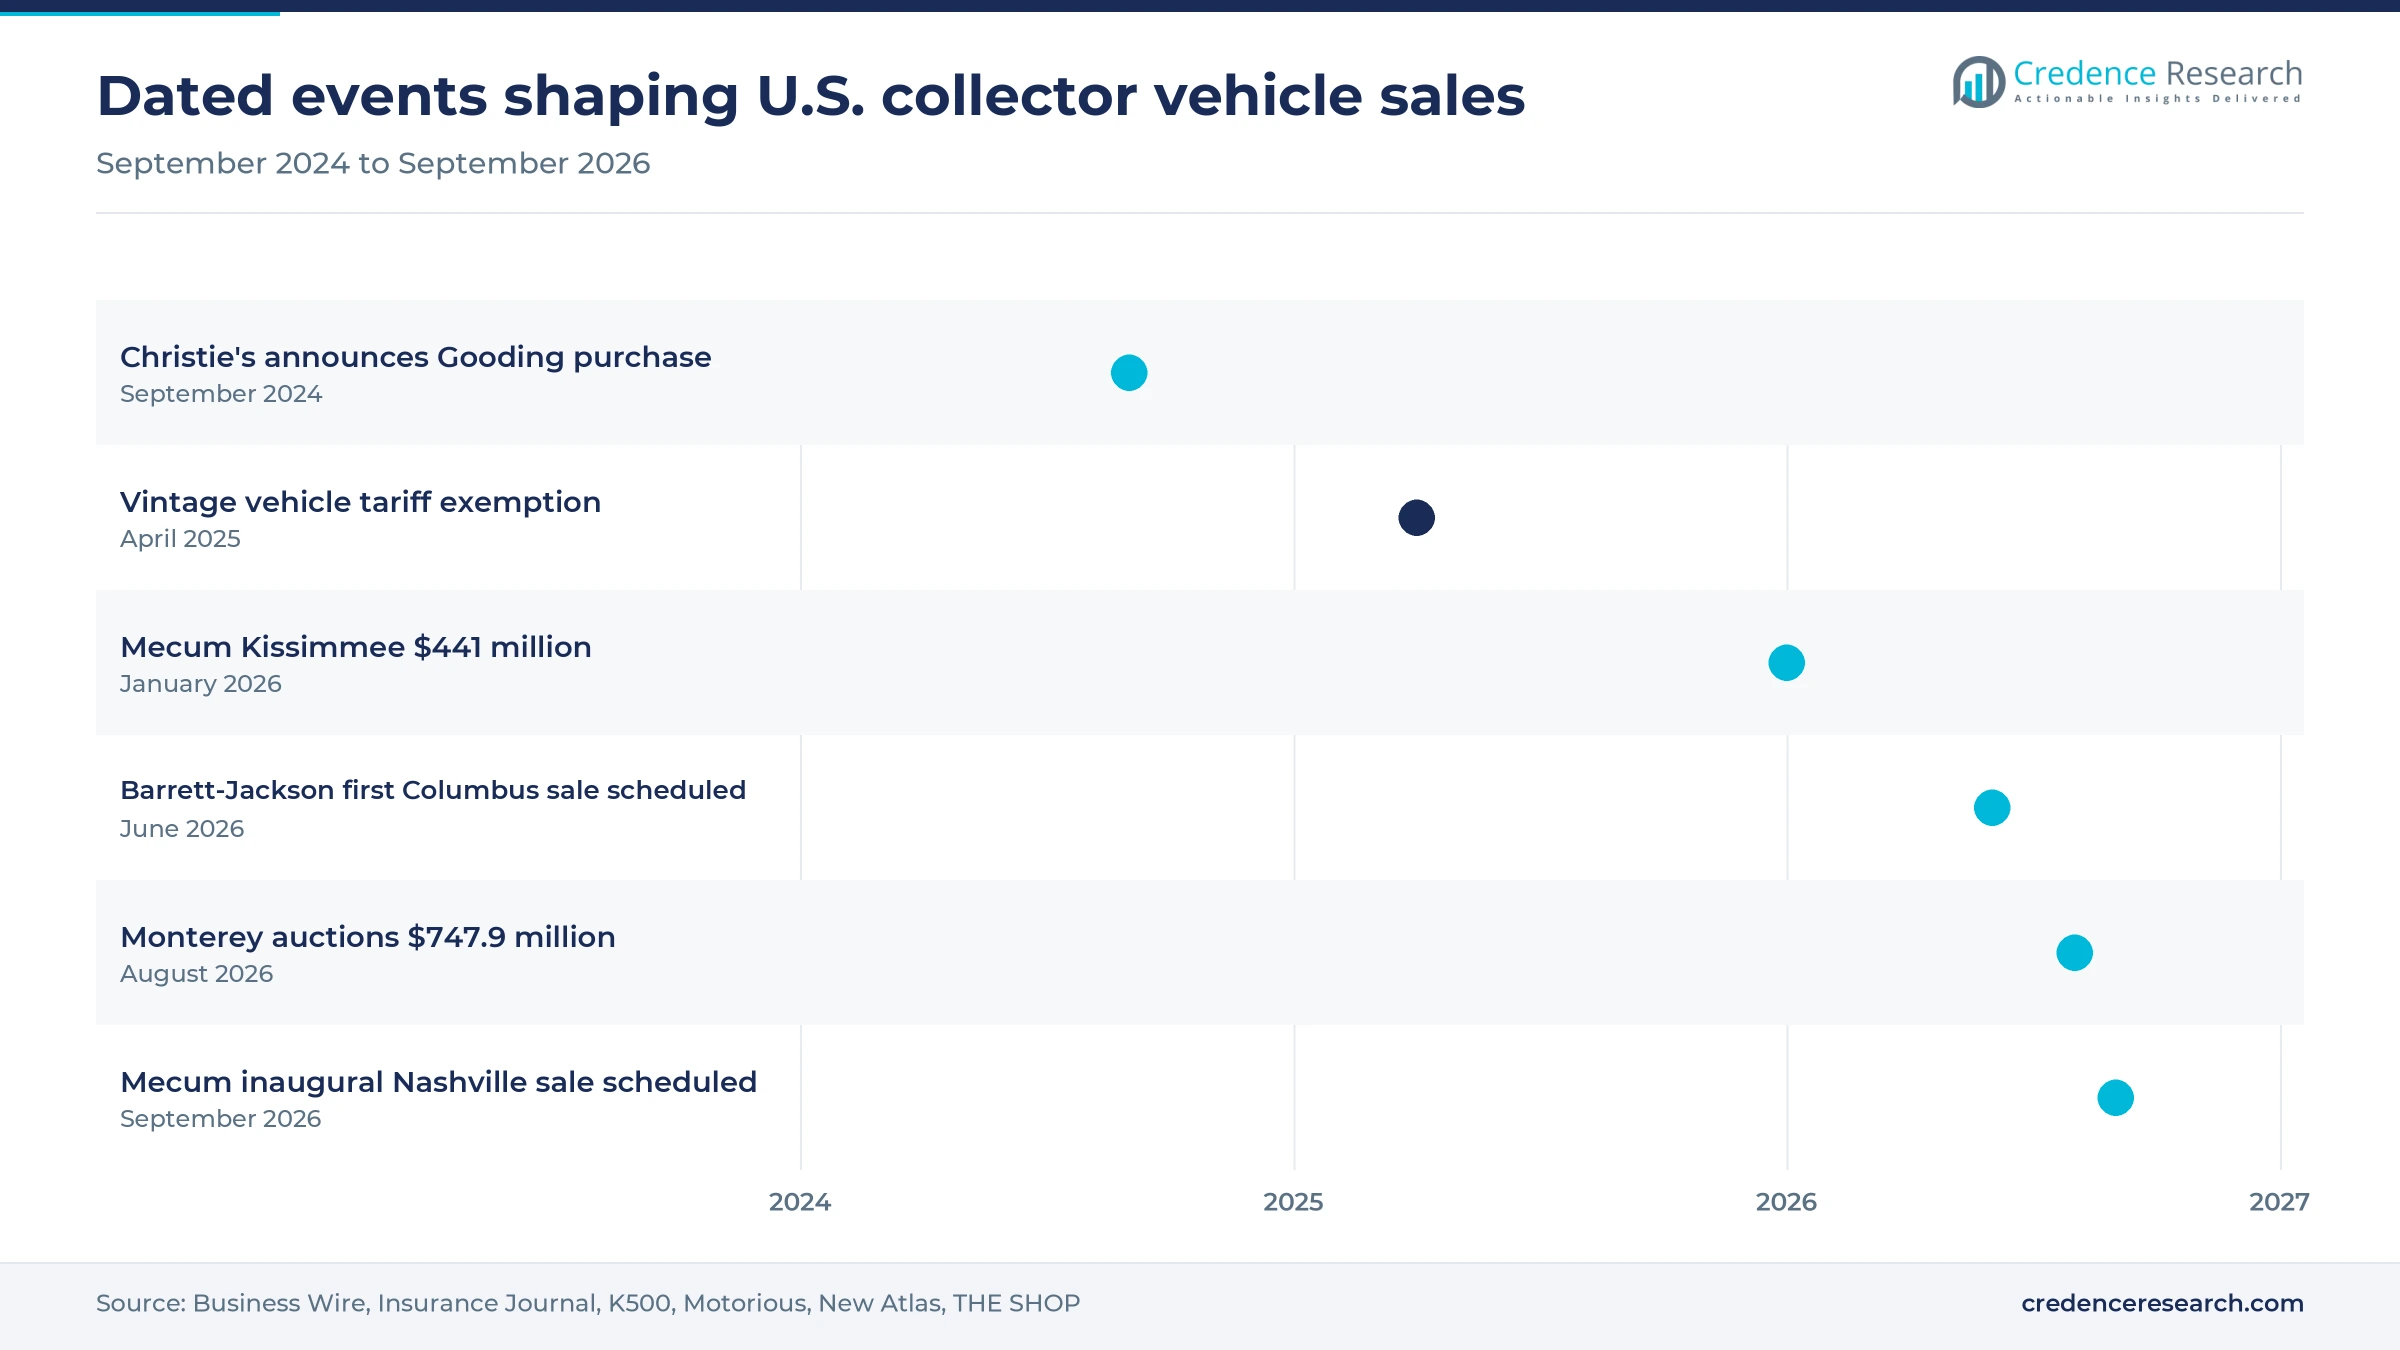
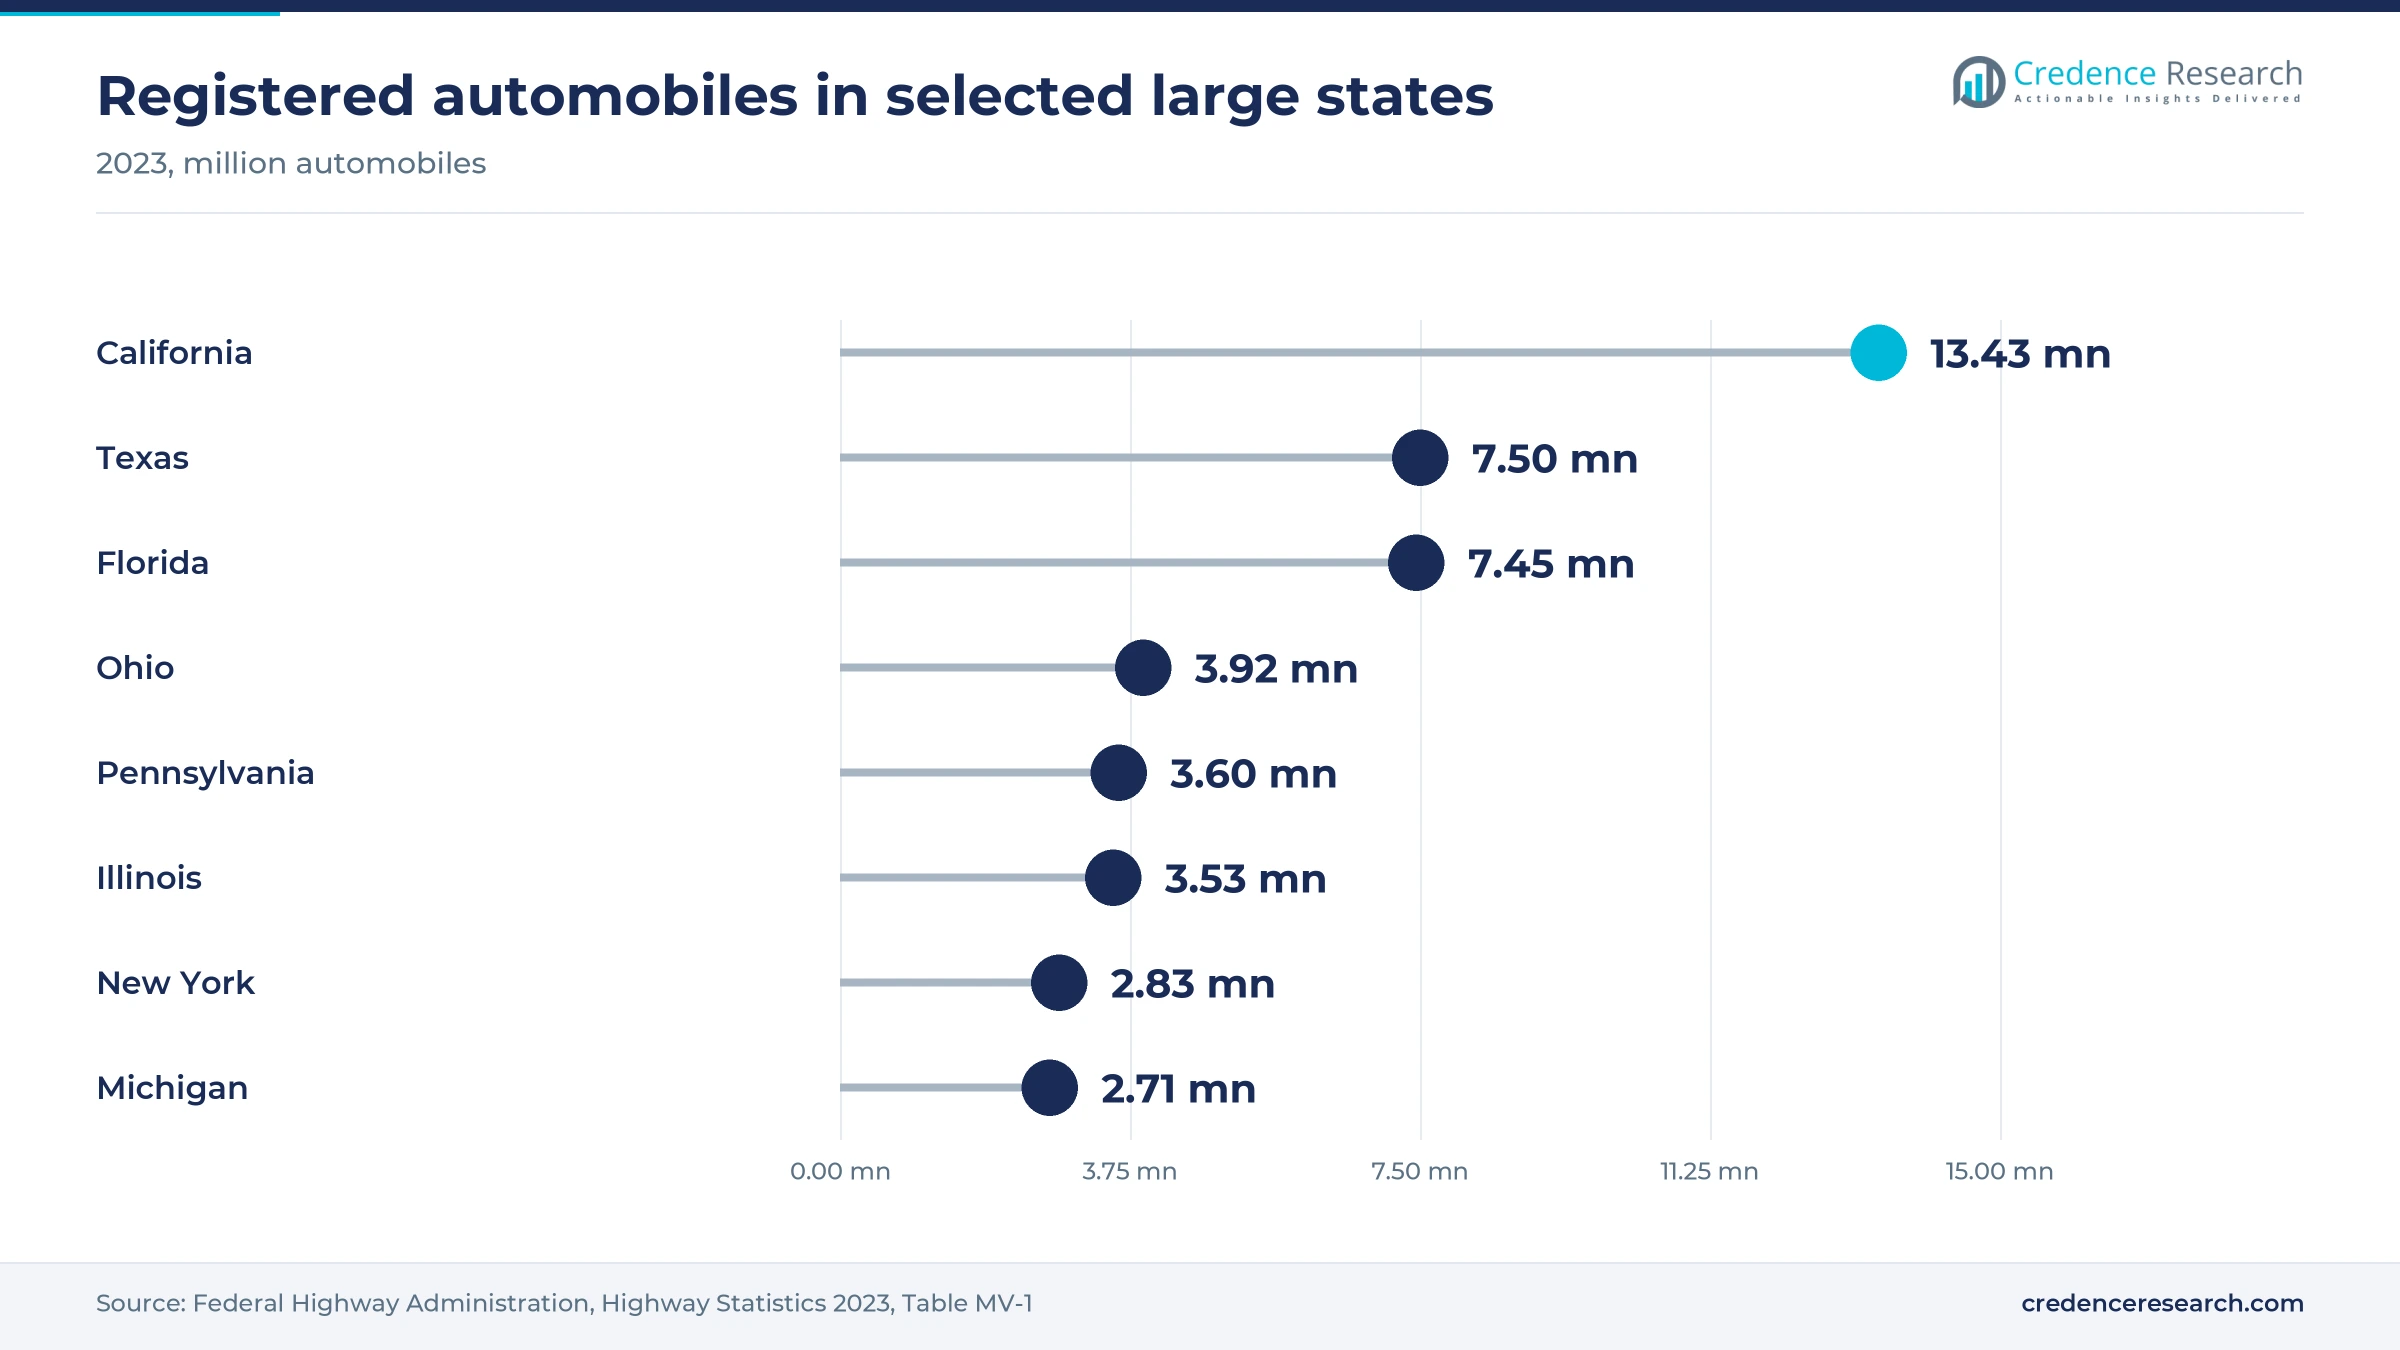
New regional sales offer an opening for houses that can reach collectors who rarely travel to Scottsdale or Monterey. Barrett-Jackson reported an inaugural Columbus auction scheduled for June 25-27, 2026, after its January Scottsdale sale of 1,911 no-reserve vehicles reached $195.2 million in total auction sales. THE SHOP reported in August 2026 that the inaugural Mecum Nashville auction would run Sept. 22-26, 2026, at Nashville Superspeedway with about 1,500 vehicles. These events reach states with large fleets, since Ohio alone registered about 3.92 million automobiles in 2023. As a result, operators that add regional dates can source lower-priced consignments closer to their owners and build repeat bidders.
Opportunity in custom builds and trained restoration talent
Custom restoration offers an opening for shops that can combine period styling with modern reliability, because those builds earn prices well above many originals. Barrett-Jackson reported in February 2025 that a 1957 Lincoln Continental Mark II custom coupe sold for $440,000 and a 1968 Chevrolet Camaro custom coupe brought $385,000. ClassicCars.com listings from Costa Mesa, California, describe Singer Vehicle Design as founded in 2009 and known for reworked Porsche 911 cars. Custom Restored vehicles grow at 10.0% a year on this demand. The Piston Foundation has also awarded 83 scholarships worth $298,750 since 2022, according to THE SHOP in August 2025, which begins to widen the pool of future builders.
Mid-market prices, skills and parts costs weigh on sales
Mainstream values keep slipping for ordinary owners
Falling mainstream prices are the biggest near-term problem, because owners of ordinary cars hesitate to sell at a loss. Only 35.2% of privately sold cars brought more than their insured value in January 2026, the lowest share in nearly four years, according to Motorious. Borro reported that Hagerty's private sales activity measure fell to 63.7 in April 2026. Dealers and insurers feel this first, through slower inventory and lower agreed values. Sellers can respond with realistic reserves and better condition documentation.
Wide sell-through gaps expose reserve price disputes
Sellers and bidders still disagree on prices outside the most curated sales, which leaves many lots unsold and consignors disappointed. Motorious reported early August 2026 sell-through of just 56% at Mecum Monterey, against 96% at Gooding Christie's and 87% at RM Sotheby's. Cars left unsold return to the market with a visible failed result, which can weaken their next price. Auction houses are responding through post-sale negotiations, and Mecum continued finalizing deals through its Bid Goes On department after the event.
Fewer specialists can repair and restore older vehicles
A shrinking pool of restorers threatens the upkeep of older vehicles, and the owners of prewar cars feel it most. McKeel Hagerty warned in May 2025 that fewer people can fix these machines, describing a mechanic who spent weeks hunting for a 1937 Packard V-12 synchronizer. The Piston Foundation received 140 scholarship applications in 2025 and could fund only 30, according to THE SHOP. Longer searches raise costs and delay sales, although training grants and apprenticeships are starting to add technicians.
Tariffs raise parts and material costs for restoration
Tariffs have made restoration budgets harder to plan, because exemptions for old cars do not remove higher costs on many inputs. Claims Journal reported in June 2025 that steel and aluminum tariffs had reached 50%, and that retail prices for original equipment parts rose 2.1% from the first to the second quarter, against 1% a year earlier. Suppliers of aftermarket automotive parts face the same pressure on imported inputs. Restorers can reduce the effect through reproduction parts made domestically and earlier ordering.
The South leads as Monterey results lift the West
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South | 5.08 | 37.0% | 9.0% |
| West | 4.25 | 31.0% | 9.2% |
| Midwest | 2.74 | 20.0% | 8.5% |
| Northeast | 1.65 | 12.0% | 8.0% |
The South leads on Florida auctions and Texas fleets
The South held 37.0% of 2025 value and grows at 9.0% a year, supported by Florida and Texas. Federal Highway Administration data show about 7.50 million registered automobiles in Texas and 7.45 million in Florida in 2023. Florida also hosts Mecum Kissimmee and the Amelia Island sales, where Broad Arrow reported $111 million in 2026. Mecum also announced an inaugural Nashville sale for September 2026, which gives Tennessee and neighboring collectors a closer venue.
The West grows fastest on Monterey and Scottsdale value
The West held 31.0% of 2025 value and is the fastest-growing region at 9.2% a year. California registered about 13.43 million automobiles in 2023, the largest fleet in the country, and Arizona added about 2.27 million. Monterey Car Week and the Scottsdale sales give the region the most valuable auction calendar in the United States. RM Sotheby's alone reported about $370 million at Monterey in August 2026, according to early figures published by Motorious.
The Midwest draws new sales and steady hobby ownership
The Midwest held 20.0% of 2025 value and grows at 8.5% a year, resting on ownership more than on headline prices. Ohio, Illinois and Michigan registered about 3.92 million, 3.53 million and 2.71 million automobiles respectively in 2023. Barrett-Jackson announced Columbus for a new sale in June 2026 at the Ohio Expo Center & State Fairgrounds, while Gateway Classic Cars, founded in 1999, lists 16 showrooms nationwide. That ownership base gives sellers across the region a closer alternative to the Arizona and Florida sales.
The Northeast relies on older collections and media reach
The Northeast held 12.0% of 2025 value and grows at 8.0% a year, the slowest pace of the four regions. Pennsylvania and New York registered about 3.60 million and 2.83 million automobiles in 2023, but none of the major sales cited in this report takes place there. Hemmings Motor News, based in Bennington, Vermont, gives the region a long-established marketplace that listed nearly 30,000 vehicles in November 2023, according to the Manchester Journal. Older private collections and estates should remain a steady source of regional supply.
Auction records and tariff rules marked 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In September 2024, Christie's announced its purchase of California-based Gooding & Company, according to K500. | Completed; the joint house now trades as Gooding Christie's |
| In April 2025, customs guidance exempted vehicles at least 25 years old from the 25% auto tariff, leaving a 2.5% duty, according to Insurance Journal. | In force at the time of reporting; protects older imports |
| In January 2026, Mecum Kissimmee posted $441 million gross over 13 days, including a 1962 Ferrari 250 GTO at $38.5 million, according to New Atlas. | Completed; New Atlas called it the biggest car auction in history |
| In January 2026, Barrett-Jackson sold 1,911 vehicles at no reserve in Scottsdale, and Craig Jackson named a 1955 Mercedes-Benz 300SL Gullwing at $2,530,000 as the top sale. | Completed; shows the depth of no-reserve mainstream bidding |
| In August 2026, THE SHOP reported that Mecum would hold its inaugural Nashville auction at Nashville Superspeedway in September with about 1,500 vehicles. | Scheduled when reported; extends the regional calendar |
Price indexes and online bidding reshape buying
- Hagerty's index family covers 11 market indexes plus a Market Rating, giving owners a public read on segments from Ferrari to affordable classics.
- Online timed auctions put full photo sets and bidder comments in public view, which helped Bring a Trailer reach an 81% sell-through rate in 2025.
- Classic.com sales tracking collects auction and online results in one searchable database, so buyers can compare a car against recent sales before bidding.
- Insured-value data shows how owners rate their own cars, and Hagerty counted only 35.2% of private sales above insured value in January 2026.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Auction houses and online sites compete for consignments
Competition centers on winning consignments, because a limited number of important cars and collections reach the market each year. RM Sotheby's ran nine of the ten biggest sales of 2025, according to Classic.com, while Broad Arrow and Gooding Christie's compete for the same top collections at Monterey and Amelia Island. Christie's announced its purchase of Gooding & Company in September 2024, which tied a global art house to that contest. Mecum and Barrett-Jackson work at much greater volume, with multiday events and large no-reserve or mixed dockets that serve mainstream sellers. Bring a Trailer and ClassicCars.com compete on reach and lower selling friction. Gateway Classic Cars and Hemmings serve buyers who prefer fixed-price listings and a longer selling window. Consignors often compare across these routes, and large U.S. estates also weigh worldwide collector demand before choosing a venue. Cars & Bids competes with Bring a Trailer for modern enthusiast cars from the 1980s onward and has begun listing older classics as well.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Mecum Auctions | Auction house | Runs high-volume U.S. sales including Kissimmee, Monterey and the new Nashville event |
| RM Sotheby’s | Auction house | Top-tier house and the largest Monterey seller in August 2026 |
| Barrett-Jackson | Auction house | No-reserve sales in Scottsdale, Palm Beach, Las Vegas and Columbus |
| Bring a Trailer | Online auction platform | Largest online venue, with 49,486 listings in 2025 |
| Gooding Christie’s | Auction house | California-founded house, now part of Christie's, active at Monterey and Amelia Island |
| Broad Arrow Auctions | Auction house | Hagerty marketplace brand with a $111 million Amelia Island sale in 2026 |
| Bonhams | Auction house | Single-day Monterey sale of about $12 million in August 2026 |
| Cars & Bids | Online auction platform | Online auctions of modern enthusiast cars from the 1980s onward, now adding older classics |
| Gateway Classic Cars | Consignment dealer | Sixteen showrooms and 2,178 classics listed on its website |
| Hemmings Motor News | Marketplace and publisher | Collector car classifieds, Hemmings Auctions online sales and the Hemmings Motor News magazine |
| ClassicCars.com | Online marketplace | Listing site that carries auction vehicles, including Singer-built Porsche 911 cars |
Credence Research sees a two-speed collector market
Credence Research's view is that the U.S. classic cars market is healthy in dollar terms but uneven underneath. Monterey and Kissimmee show deep demand for the best cars, yet the Hagerty Market Rating shows that ordinary owners have lost pricing power since 2022. This gap should narrow only if younger buyers take up the cars that boomers eventually sell. Sellers of mainstream cars should therefore plan around condition, documentation and realistic reserves. Investors should treat most classic cars as enjoyable assets with high carrying costs, because only a narrow top tier has recently delivered strong gains.
How the U.S. collector vehicle estimates were built
The report uses 2025 as the base year and 2035 as the forecast year. The market values come from the Credence Research model, with the earlier 2024 estimate carried to 2025 at its own growth rate and compared against a top-down check of the U.S. vehicle stock and public sale totals. Segment and regional splits are Credence Research estimates built from public sale and registration data. Sources are company releases, auction results, Federal Highway Administration statistics and trade publications. No interviews or surveys were conducted for this edition of the report.
Top-end strength must broaden to the mid-market by 2035
The U.S. classic cars market is expected to reach USD 31.94 billion by 2035, with growth of 8.82% a year over 2026–2035. This rate measures the value of cars sold rather than price appreciation, so it relies on mix shifting toward high-priced and online sales, and it also assumes a recovery in ordinary trading, which has been weak for several years. Every January adds another model year to the import exemption, and each new generation of buyers tends to favor newer cars. As a result, the 1980s to 2000s group should take a larger part of sales, and online platforms should gain share at the expense of dealerships.
Frequently Asked Questions
How big is the U.S. classic cars market?
Are classic car prices falling?
Are classic cars a good investment?
What are the current classic car market trends?
Which classic cars are collectors watching most closely?
Which U.S. region leads the classic cars market?
Who are the key players in the U.S. classic cars market?
How have online auctions changed classic car buying?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sports Cars
- 1.2.2 Luxury Cars
- 1.2.3 Convertibles
- 1.2.4 Sedans
- 1.2.5 Others
- 1.3 By Price Range
- 1.3.1 High
- 1.3.2 Low & Medium
- 1.4 By Restoration Level
- 1.4.1 Original Condition
- 1.4.2 Partial Restoration
- 1.4.3 Full Restoration
- 1.4.4 Custom Restored
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 13.72 billion → 2035: USD 31.94 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Classic Cars Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Classic Cars Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Classic Cars Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Classic Cars Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Classic Cars Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Classic Cars Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Classic Cars Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Classic Cars Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 13.72 billion → 2035: USD 31.94 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Classic Cars Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sports Cars
- 12.3.7.2 Luxury Cars
- 12.3.7.3 Convertibles
- 12.3.7.4 Sedans
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 High
- 12.4.7.2 Low & Medium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Restoration Level - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Original Condition
- 12.5.7.2 Partial Restoration
- 12.5.7.3 Full Restoration
- 12.5.7.4 Custom Restored
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Classic Cars Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Classic Cars Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Classic Cars Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mecum Auctions
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 RM Sotheby’s
- 17.4 Barrett-Jackson
- 17.5 Bring a Trailer
- 17.6 Gooding Christie’s
- 17.7 Broad Arrow Auctions
- 17.8 Bonhams
- 17.9 Cars & Bids
- 17.10 Gateway Classic Cars
- 17.11 Hemmings Motor News
- 17.12 ClassicCars.com
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

