
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Commercial High-Speed Oven Market Size 2024 | USD 3,049.30 million |
| Commercial High-Speed Oven Market, CAGR | 7.2% |
| Commercial High-Speed Oven Market Size 2032 | USD 5,318.12 million |
Market Overview:
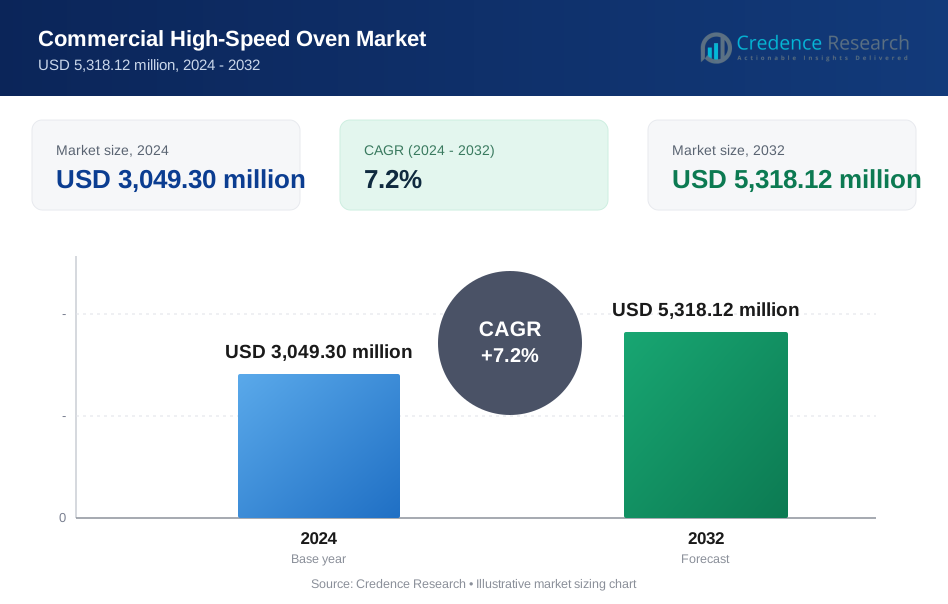
The Commercial High-Speed Oven Market is projected to grow from USD 3,049.30 million in 2024 to an estimated USD 5,318.12 million by 2032, with a compound annual growth rate (CAGR) of 7.2% from 2024 to 2032.
Key drivers of the commercial high-speed oven market include the increasing demand for faster cooking solutions in commercial kitchens, where time efficiency is crucial. High-speed ovens offer the advantage of cooking food quickly and evenly, making them highly attractive to businesses in the foodservice industry. Additionally, the growing trend of food delivery services and the expansion of quick-service restaurants (QSRs) are fueling the adoption of high-speed ovens. These ovens also align with the rising demand for energy-efficient appliances, as they reduce cooking times and energy consumption compared to traditional ovens. Technological advancements in oven design and features are another driving force. Modern high-speed ovens incorporate convection, microwave, and impingement cooking technologies, allowing for versatile cooking methods that appeal to a wide range of commercial food establishments. The focus on automation and smart cooking solutions also supports market growth, as these ovens enable more precise control over cooking times and temperatures.
Regionally, North America and Europe are leading the commercial high-speed oven market, driven by the demand from developed foodservice industries and established restaurant chains. In the Asia Pacific region, the market is anticipated to experience significant growth due to rapid urbanization, an expanding middle class, and increased investments in modern commercial kitchen equipment. The growing trend of quick-service dining in countries like China, India, and Japan is expected to boost demand for high-speed ovens. Latin America and the Middle East & Africa regions are also seeing increasing adoption of high-speed ovens as the foodservice sector modernizes and expands, contributing to the global market expansion.
Market Insights:
- The Commercial High-Speed Oven Market is projected to grow significantly, from USD 3,049.30 million in 2024 to USD 5,318.12 million by 2032, with a CAGR of 7.2%.
- The increasing demand for faster cooking solutions in commercial kitchens is a key driver, especially in quick-service restaurants and food delivery services.
- High-speed ovens offer time efficiency, energy savings, and cooking versatility, which is attracting businesses looking to optimize their operations.
- Technological advancements in cooking methods, such as combining microwave, convection, and impingement technologies, are enhancing the market growth.
- Rising labor costs and the need for automation in kitchens may limit the market's potential, as high-speed ovens require skilled handling and maintenance.
- North America and Europe lead the market, driven by the demand from well-established foodservice industries and restaurant chains.
- The Asia Pacific region is experiencing rapid growth due to urbanization, an expanding middle class, and increasing quick-service dining trends, while Latin America and the Middle East & Africa are also adopting high-speed ovens as part of their kitchen modernization.
Market Drivers
Increasing Demand for Faster Cooking Solutions:
The need for faster cooking solutions in commercial kitchens is increasing as foodservice businesses look to enhance operational efficiency. High-speed ovens are becoming essential in meeting the time-sensitive needs of environments such as quick-service restaurants (QSRs) and food delivery services. For instance, the U.S. Bureau of Labor Statistics reported that foodservice operations employed approximately 15.3 million people in 2023, highlighting the size of the industry that relies heavily on fast and efficient cooking equipment. The demand for high-speed ovens is particularly high in high-volume establishments aiming to serve large numbers of customers quickly.
Rising Preference for Energy-Efficient Appliances:
Energy efficiency is a growing concern in the foodservice industry, as energy costs continue to rise globally. High-speed ovens, which use less energy compared to traditional cooking methods, are increasingly seen as cost-effective solutions. The U.S. Department of Energy, for example, highlighted that commercial kitchen appliances account for approximately 3.4% of total commercial building energy use. For instance, the Energy Star program, which certifies energy-efficient appliances, reported that the total energy savings from certified commercial ovens in 2022 exceeded 800 million kilowatt-hours (kWh), providing a significant reduction in operating costs for businesses.
Technological Advancements in Cooking Technology:
Advancements in cooking technology, such as the integration of convection, microwave, and impingement heating, have driven the growth of high-speed ovens. For instance, the U.S. Department of Energy's research on advanced cooking technologies found that combining these cooking methods can reduce energy consumption by up to 40% compared to traditional ovens. This technology enables faster cooking while maintaining food quality, making it particularly attractive to large-scale foodservice operations looking to improve both efficiency and customer satisfaction.
Growth of Quick-Service Restaurants and Food Delivery Services:
The rapid growth of the quick-service restaurant sector is a key factor driving the demand for high-speed ovens. According to the National Restaurant Association, the U.S. restaurant industry generated $899 billion in sales in 2023, with QSRs contributing a substantial share of this revenue. For instance, the U.S. QSR market accounted for 58% of total restaurant industry sales. Additionally, food delivery services, which saw a surge during the COVID-19 pandemic, continue to grow, with the U.S. food delivery market valued at $31.9 billion in 2022. The growth of these sectors presents a significant opportunity for the adoption of high-speed ovens.
Market Trends:
Increased Adoption of Smart Cooking Solutions:
As the foodservice industry becomes more technology-driven, smart cooking solutions are increasingly popular. High-speed ovens that integrate IoT (Internet of Things) technology allow for real-time monitoring and remote control of cooking processes. For instance, the U.S. Department of Commerce has highlighted that the adoption of smart technologies in the manufacturing sector grew by 12% in 2022, with the foodservice industry increasingly investing in automation and digitalization to improve efficiency and consistency. This trend is aligned with broader automation efforts across various industries, driving innovation in cooking appliances like high-speed ovens.
Sustainability and Energy Efficiency Focus:
Sustainability remains a key trend in the commercial kitchen equipment market, with businesses looking for energy-efficient appliances to reduce their carbon footprint and operational costs. The European Commission's research on energy consumption in commercial kitchens showed that energy-efficient appliances can reduce energy usage by up to 30%, contributing significantly to sustainability goals. For Instance, The U.S. Environmental Protection Agency (EPA) also reported that the commercial kitchen sector accounts for over 12% of total commercial building energy consumption, making the shift towards energy-efficient ovens essential to meeting national energy conservation targets.
Customization and Versatility in Commercial Ovens:
Modern high-speed ovens are being designed with greater customization to cater to the specific needs of different commercial kitchens. For example, the U.S. Department of Agriculture (USDA) has reported a 20% increase in demand for versatile cooking equipment that can handle a variety of food items, from baking to roasting to grilling. This trend is being driven by the growing diversity of menu items offered by foodservice establishments that need appliances capable of adjusting to multiple cooking methods.
Regional Growth in Emerging Markets:
Emerging markets, particularly in Asia Pacific, are seeing rapid growth in the adoption of high-speed ovens as urbanization and disposable incomes rise. For Instance, according to the World Bank, developing economies in the Asia Pacific region grew by 7.3% in 2022, leading to an increase in demand for modern foodservice equipment, including high-speed ovens. The rise in quick-service restaurants (QSRs) and food delivery services in countries like China and India is further propelling the market in these regions.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs:
One of the key challenges facing the Commercial High-Speed Oven Market is the high upfront cost of purchasing and installing these advanced cooking appliances. Despite their long-term operational benefits, including energy savings and faster cooking times, the initial investment can be a significant barrier for small to medium-sized foodservice businesses. High-speed ovens often come with a premium price due to their advanced technology, which may not be immediately feasible for businesses operating on tight budgets. Additionally, ongoing maintenance and repair costs associated with these complex machines can be substantial. For instance, the U.S. Small Business Administration (SBA) estimates that over 60% of small businesses report difficulty in affording costly equipment upgrades, particularly in the foodservice industry. As a result, many businesses may hesitate to adopt these ovens despite their potential advantages, slowing down market growth in certain regions.
Operational Complexity and Workforce Training:
The operational complexity of high-speed ovens also poses a challenge to widespread adoption. These ovens typically incorporate multiple cooking technologies such as microwave, convection, and impingement, which require specialized knowledge to operate effectively. For instance, the U.S. Department of Labor's Occupational Safety and Health Administration (OSHA) has highlighted that improper training in handling complex kitchen equipment can lead to accidents and inefficiencies. As a result, businesses must invest in workforce training programs to ensure the safe and effective use of high-speed ovens. This requirement adds another layer of expense and operational complexity, particularly for smaller establishments with limited resources. Furthermore, as demand for these appliances grows, the need for skilled technicians to maintain and repair them is also increasing, which may further strain the available labor force and lead to higher operational costs.
Market Opportunities:
The growing demand for energy-efficient kitchen appliances presents significant opportunities for the Commercial High-Speed Oven Market. As businesses in the foodservice industry increasingly focus on reducing operating costs, high-speed ovens offer a viable solution. These ovens cook food faster while consuming less energy compared to traditional cooking methods, making them attractive to both large-scale operations and smaller establishments. Additionally, rising energy costs are prompting operators to seek more sustainable alternatives that not only lower electricity consumption but also reduce overall carbon footprints. This shift towards energy-efficient appliances aligns with the broader trend of sustainability in the foodservice sector, positioning high-speed ovens as a key investment for businesses aiming to improve operational efficiency and align with environmental standards.
Technological innovation is another major opportunity within the commercial high-speed oven market. As consumer preferences continue to evolve, there is an increasing demand for versatile cooking solutions that can handle a wide range of food items with precision and consistency. High-speed ovens equipped with advanced features, such as smart controls, automated cooking programs, and integration with kitchen management systems, are well-positioned to meet these needs. These innovations not only improve cooking times but also enhance food quality, allowing businesses to deliver a better customer experience. Furthermore, the rise of cloud-based kitchen management solutions opens new avenues for smart ovens, enabling real-time monitoring, remote diagnostics, and predictive maintenance, thus reducing downtime and improving productivity. The continuous development of these advanced technologies creates ample growth potential for market players looking to cater to the evolving demands of the global foodservice industry.
Market Segmentation Analysis:
By Product Type:
The market is divided into built-in ovens and countertop ovens. Built-in ovens are preferred for their seamless integration into kitchen designs, making them ideal for high-end restaurants and commercial kitchens with ample space. Countertop ovens, on the other hand, are favored for their portability and ease of installation, making them suitable for smaller establishments and food trucks.
By Category:
The market is segmented into electric and gas ovens. Electric high-speed ovens are gaining popularity due to their energy efficiency, precise temperature control, and ease of use. Gas ovens, while less common, are preferred in certain regions for their rapid heating capabilities and cost-effectiveness. The choice between electric and gas ovens often depends on the specific needs and preferences of the food service establishment.
By Sales Channel:
The market includes direct sales, distributors, and online sales. Direct sales channels are crucial for large-scale commercial kitchens and restaurant chains that require customized solutions and bulk purchases. Distributors play a significant role in reaching smaller establishments and regional markets. Online sales are growing rapidly, driven by the convenience of e-commerce platforms and the increasing adoption of digital procurement processes in the food service industry.
Segmentation:
By Product Typе
- Convеyor Ovеns
- Combi Ovеns
- Microwavе Ovеns
- Infrarеd Ovеns
- Rapid Cooking Ovеns
- Tunnеl Ovеns
By Catеgory
- Convеction High-spееd Ovеns
- Microwavе High-spееd Ovеns
- Impingеmеnt High-spееd Ovеns
- Hybrid High-spееd Ovеns
By Capacity
- 1000 to 2000 W
- 2000 to 4500 W
- 4500 to 6000 W
- Abovе 6000 W
By Fuеl Typе
- Elеctric
- Gas
- Dual Fuеl
By Salеs Channеl
- Authorizеd Dеalеrs
- Spеcialty Storеs
- Hypеrmarkеt/Supеrmarkеt
- Dirеct Salеs
- Onlinе
By End usе
- Rеstaurants
- Fast Food Chains
- Finе Dining Rеstaurants
- Catеring Sеrvicеs
- Hotеls and Rеsorts
- Commеrcial Bakеriеs
- Food Procеssing Industry
- Hеalthcarе Facilitiеs
- Othеrs
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America North America holds a dominant position in the Commercial High-Speed Oven Market, accounting for a significant market share due to the region's established foodservice industry. The United States, in particular, is a major contributor to this growth, with quick-service restaurants (QSRs) and large-scale food chains increasingly adopting high-speed ovens to enhance operational efficiency and meet growing consumer demand for fast food. The region's market share in the high-speed oven segment is estimated at 40%, driven by the growing preference for energy-efficient and time-saving cooking equipment. Moreover, the increasing focus on sustainability and energy conservation in commercial kitchens has led many businesses in North America to opt for energy-efficient ovens, further fueling market expansion. For instance, the U.S. Environmental Protection Agency (EPA) highlighted that energy-efficient commercial kitchen appliances saved over 800 million kWh in 2022.
Europe Europe follows closely, with a significant share in the global market. The European market for commercial high-speed ovens is driven by stringent regulations around energy efficiency and the growing focus on sustainable foodservice operations. Countries like Germany, the United Kingdom, and France are leaders in adopting advanced cooking technologies, as the demand for energy-efficient appliances rises. The European Union's policies promoting green technologies in commercial kitchens have boosted the market's growth. For Instance, in 2022, European Union regulations for energy efficiency required all new kitchen appliances to meet higher performance standards, further driving the demand for high-speed ovens. The region's market share is around 30%, with a notable increase in the adoption of combination ovens in full-service restaurants and hotels.
Asia Pacific Asia Pacific is the fastest-growing region in the Commercial High-Speed Oven Market, driven by rapid urbanization, rising disposable incomes, and an expanding middle class. Countries like China, Japan, and India are experiencing significant growth in their foodservice industries, particularly in quick-service restaurants and food delivery services. According to the World Bank, the region's GDP grew by 7.3% in 2022, leading to increased investments in modern commercial kitchen equipment. The market share in Asia Pacific is projected to reach 25%, with a focus on energy-efficient and versatile cooking solutions that cater to diverse culinary preferences. For instance, in China, the foodservice market has been growing rapidly, with QSRs and food delivery services heavily investing in high-speed ovens to meet the high demand for fast food preparation.
Key Player Analysis:
- Middleby Corporation
- Ali Group S.p.A.
- TurboChef Technologies (Welbilt Inc.)
- Rational AG
- Amana Commercial (Whirlpool Corporation)
- Hobart Corporation
- Vulcan (ITW Food Equipment Group)
- Moffat Limited
- Hatco Corporation
- Electrolux Professional
Competitive Analysis:
The Commercial High-Speed Oven Market is highly competitive, with several key players vying for market share through technological innovations and strategic partnerships. Companies like Middleby Corporation and Ali Group S.p.A. are leading the market, offering advanced high-speed oven solutions that cater to diverse customer needs in the foodservice industry. For instance, Middleby Corporation’s TurboChef brand is known for its state-of-the-art combination ovens that integrate multiple cooking technologies for faster cooking times and enhanced food quality. Additionally, Rational AG continues to dominate with its efficient and versatile ovens designed for commercial kitchens. To stay competitive, companies are focusing on product diversification, offering smart features like IoT connectivity and automation to improve kitchen efficiency. The market is also witnessing increased mergers and acquisitions as companies look to strengthen their product portfolios and expand into emerging regions such as Asia Pacific, where demand for high-speed ovens is growing rapidly.
Recent Developments:
- In April 2024, Middleby brands were selected for eight 2024 Kitchen Innovations Awards, recognizing their commitment to innovation in the foodservice industry. The awards highlighted products across categories such as cooking, mixing, robotics, ventless technologies, frying, and beverage dispense.
- In September 2022, Merrychef, a division of Welbilt Inc., launched the conneX® 16, a high-speed oven featuring a spacious 16-inch cavity within an 18-inch wide footprint. This innovation set new standards for compact design and functionality.
- In February 2024, Rational introduced the iHexagon, a new product category that combines steam, hot air, and microwave technology to deliver the highest food quality in the shortest possible time, evenly across all racks in the 6-1/1 unit.
- In September 2024, Hobart launched the CHEF'S COMBI, a versatile cooking and steaming solution for the hotel, restaurant, and foodservice industry, designed to be profitable from 30 meals per day.
- In July 2024, Vulcan also introduced the PreciPan™ Intelligent Braising Pan, which automates cooking with a food probe target core temperature, basket lifting, pan tilting, and tilt-free draining.
- In January 2024, Electrolux Professional Group acquired Tosei Corporation, marking a significant step in the company's strategic expansion and strengthening its market position.
Market Concentration & Characteristics:
The Commercial High-Speed Oven Market exhibits a moderate level of concentration, with a few dominant players controlling a significant portion of the market share. Major companies such as Middleby Corporation, Rational AG, and Ali Group S.p.A. lead the market, leveraging their established brand reputation, advanced product offerings, and global reach to maintain their competitive positions. These key players focus on innovation, integrating new technologies like IoT, energy efficiency, and automation to meet the evolving needs of commercial kitchens. While the market is driven by large, well-established companies, there is room for smaller players to innovate with niche products or regional offerings. Additionally, the growing demand in emerging markets, especially in Asia Pacific, is fueling market expansion, with companies actively seeking to enter these regions. The market is characterized by continuous product development, strategic partnerships, and increasing investments in energy-efficient and versatile cooking solutions.
Report Coverage:
The research report offers an in-depth analysis Based on Product Type, Based on Category, By Sales Channel, By Fuеl Typе, Based on End-User, Based on Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for quick and efficient cooking solutions in the food service industry.
- Advancements in oven technology, including energy-efficient and smart ovens.
- Growing popularity of quick-service restaurants and fast-casual dining formats.
- Expansion of product lines with multifunctional cooking capabilities.
- Rising adoption of high-speed ovens in commercial kitchens for improved operational efficiency.
- Enhanced user experience with intuitive touchscreen interfaces and programmable cooking presets.
- Integration of high-speed ovens into multi-functional kitchen equipment setups.
- Focus on sustainability with ovens designed to reduce energy consumption.
- Increased online sales and digital marketing strategies for reaching wider audiences.
- Continued innovation in cooking technology to cater to diverse consumer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Faster Cooking Solutions
Commercial kitchens, especially quick-service restaurants and food delivery services, require rapid food preparation to meet high customer volumes and reduce wait times. High-speed ovens enable faster and more consistent cooking, making them essential for operational efficiency.
Energy Efficiency and Sustainability
Rising energy costs and sustainability goals are pushing foodservice operators to adopt high-speed ovens, which consume less energy and reduce operational expenses compared to traditional ovens. These ovens help businesses lower their carbon footprint and comply with energy regulations.
Technological Advancements in Cooking Methods
The integration of convection, microwave, and impingement technologies in high-speed ovens allows for versatile and precise cooking. These innovations improve food quality, reduce cooking times, and appeal to a wide range of commercial food establishments.
Growth of Quick-Service Restaurants and Food Delivery
The expansion of QSRs and the ongoing popularity of food delivery services are driving the need for equipment that can handle high order volumes quickly. High-speed ovens are increasingly adopted to support these business models and maintain food quality under time constraints.
Adoption of Smart and Automated Kitchen Solutions
The trend toward automation and smart kitchen equipment is leading to increased adoption of high-speed ovens with IoT connectivity, programmable presets, and remote monitoring. These features enhance kitchen productivity and reduce labor requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Commercial High-Speed Oven Market?
What are the key drivers of the Commercial High-Speed Oven Market?
Which regions are leading the Commercial High-Speed Oven Market?
What technological advancements are contributing to the market growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Restaurants
- 1.2.2 Fast Food Chains
- 1.2.3 Hotels and Resorts
- 1.2.4 Catering Services
- 1.2.5 Commercial Bakeries
- 1.2.6 Food Processing Industry
- 1.3 By Category
- 1.3.1 Convection High-speed Ovens
- 1.3.2 Microwave High-speed Ovens
- 1.3.3 Impingement High-speed Ovens
- 1.3.4 Hybrid High-speed Ovens
- 1.4 By Fuel Type
- 1.4.1 Electric
- 1.4.2 Gas
- 1.4.3 Dual Fuel
- 1.5 By Product Type
- 1.5.1 Conveyor Ovens
- 1.5.2 Combi Ovens
- 1.5.3 Microwave Ovens
- 1.5.4 Infrared Ovens
- 1.5.5 Rapid Cooking Ovens
- 1.5.6 Tunnel Ovens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,049.30 million → 2032: USD 5,318.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Commercial High-Speed Oven Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Commercial High-Speed Oven Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Commercial High-Speed Oven Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Commercial High-Speed Oven Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Commercial High-Speed Oven Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Commercial High-Speed Oven Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Commercial High-Speed Oven Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Commercial High-Speed Oven Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,049.30 million → 2032: USD 5,318.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Commercial High-Speed Oven Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Restaurants
- 12.3.7.2 Fast Food Chains
- 12.3.7.3 Hotels and Resorts
- 12.3.7.4 Catering Services
- 12.3.7.5 Commercial Bakeries
- 12.3.7.6 Food Processing Industry
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Category - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Convection High-speed Ovens
- 12.4.7.2 Microwave High-speed Ovens
- 12.4.7.3 Impingement High-speed Ovens
- 12.4.7.4 Hybrid High-speed Ovens
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric
- 12.5.7.2 Gas
- 12.5.7.3 Dual Fuel
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Conveyor Ovens
- 12.6.7.2 Combi Ovens
- 12.6.7.3 Microwave Ovens
- 12.6.7.4 Infrared Ovens
- 12.6.7.5 Rapid Cooking Ovens
- 12.6.7.6 Tunnel Ovens
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Commercial High-Speed Oven End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Commercial High-Speed Oven Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Commercial High-Speed Oven Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Commercial High-Speed Oven Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Middleby Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ali Group S.p.A.
- 18.4 TurboChef Technologies (Welbilt Inc.)
- 18.5 Rational AG
- 18.6 Amana Commercial (Whirlpool Corporation)
- 18.7 Hobart Corporation
- 18.8 Vulcan (ITW Food Equipment Group)
- 18.9 Moffat Limited
- 18.10 Hatco Corporation
- 18.11 Electrolux Professional
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

