
Market Overview
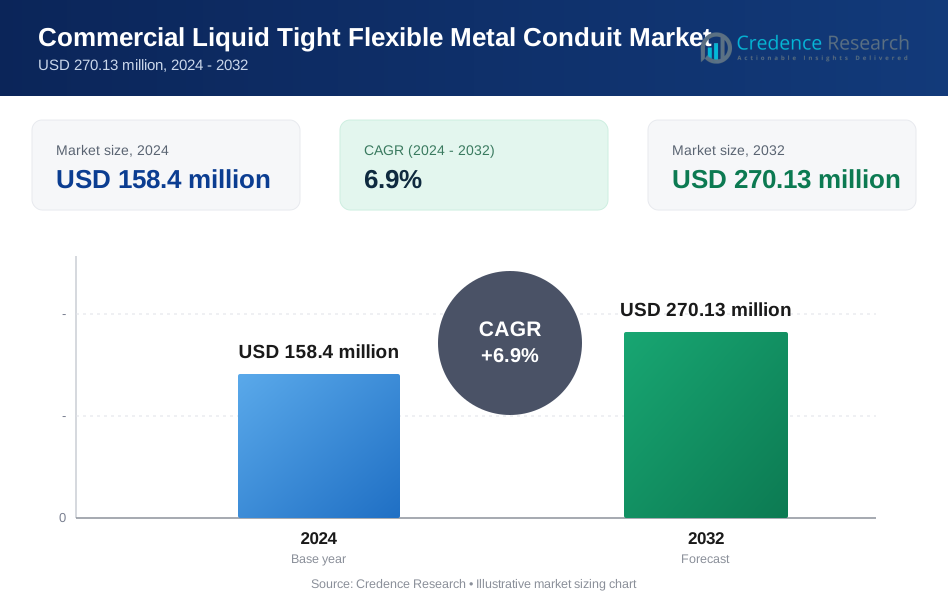
Commercial Liquid Tight Flexible Metal Conduit Market size was valued at USD 158.4 million in 2024 and is anticipated to reach USD 270.13 million by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Commercial Liquid Tight Flexible Metal Conduit Market Size 2024 | USD 158.4 million |
| Commercial Liquid Tight Flexible Metal Conduit Market, CAGR | 6.9% |
| Commercial Liquid Tight Flexible Metal Conduit Market Size 2032 | USD 270.13 million |
The Commercial Liquid-Tight Flexible Metal Conduit Market grows steadily, driven by rising commercial construction and infrastructure modernization globally. Increasing focus on electrical safety and regulatory compliance boosts demand for durable, moisture-resistant conduit solutions. The trend toward smart buildings and automation further propels market expansion, requiring flexible and reliable wiring protection. Manufacturers prioritize innovation in materials and design to meet evolving standards and environmental concerns. Urbanization in emerging regions also fuels demand, while cost efficiency and ease of installation remain critical factors influencing buyer preferences. These drivers and trends collectively shape the market’s dynamic and competitive landscape.
The Commercial Liquid-Tight Flexible Metal Conduit Market shows strong regional variations, with North America and Europe leading due to advanced infrastructure and stringent safety regulations. Asia Pacific experiences rapid growth driven by urbanization and industrialization, while Latin America and the Middle East & Africa offer emerging opportunities. Key players such as Atkore, ABB, Eaton, Electri-Flex Company, and Anamet Electrical Inc. dominate the market by leveraging innovation, extensive distribution networks, and regional expansion to meet diverse customer needs across these geographies.

Market Insights
- The Commercial Liquid Tight Flexible Metal Conduit Market size was valued at USD 158.4 million in 2024 and is expected to reach USD 270.13 million by 2032, growing at a CAGR of 6.9%.
- Rising commercial construction and infrastructure modernization globally drive steady market growth.
- Increasing focus on electrical safety and regulatory compliance raises demand for durable, moisture-resistant conduit solutions.
- The shift toward smart buildings and automation accelerates market expansion, emphasizing flexible and reliable wiring protection.
- Innovation in materials and design helps manufacturers meet evolving standards and environmental concerns.
- North America and Europe lead the market due to advanced infrastructure and strict regulations, while Asia Pacific shows rapid growth from urbanization and industrialization.
- Key players maintain competitive advantage by leveraging innovation, extensive distribution, and regional expansion to address diverse customer needs.
Market Drivers
Increasing Regulatory Emphasis on Electrical Safety and Protection Drives Demand
The Commercial Liquid Tight Flexible Metal Conduit Market benefits from a growing global emphasis on electrical safety across industrial, commercial, and residential sectors. Regulatory bodies and government agencies enforce stringent standards mandating the use of conduits that protect electrical wiring from moisture ingress, chemical exposure, corrosion, and mechanical damage. It ensures compliance with electrical safety codes designed to prevent hazards such as short circuits, fires, and equipment failure. The heightened awareness of workplace safety further motivates facility operators and contractors to adopt high-quality, liquid-tight conduit systems. Large-scale infrastructure projects and urban expansion globally create steady demand for conduits that maintain wiring integrity in harsh environments, including outdoor installations, substations, and manufacturing plants.
- For instance, Eaton’s Crouse-Hinds series of liquid-tight flexible metal conduits is tested to withstand temperatures up to 105°C and meets UL 360 standards for flexibility and liquid-tight integrity, providing certified protection against environmental hazards in demanding applications.
Urbanization and Expanding Construction Activity Fuel Market Growth
Rapid urbanization and industrialization, especially in emerging economies, drive considerable demand for liquid tight flexible metal conduits in commercial construction. These conduits provide the flexibility, strength, and protection necessary for complex electrical layouts found in office towers, data centers, healthcare facilities, and retail complexes. It supports installation in confined or difficult-to-access locations, streamlining project timelines and reducing labor costs. Renovation and retrofitting of older commercial and industrial buildings create additional opportunities, with architects and engineers preferring liquid-tight conduit systems for improved durability and safety. The continuous rise in new commercial projects and infrastructure modernization sustains the growth trajectory of the market by meeting the need for adaptable, reliable wiring protection solutions.
- For instance, Electri-Flex Company manufactures over 30 million feet of liquid-tight flexible metal conduit annually to meet the growing requirements of large-scale construction projects worldwide, demonstrating its capacity to support expanding infrastructure needs in urban areas.
Technological Innovations Enhance Durability, Efficiency, and Safety
Advancements in materials and manufacturing techniques significantly improve the functionality and lifespan of commercial liquid tight flexible metal conduits. Manufacturers now employ corrosion-resistant alloys, superior sealing technologies, and lightweight designs that ease installation while maintaining structural integrity. It reduces maintenance frequency and total lifecycle costs, benefiting end-users across demanding sectors such as chemical processing, oil and gas, marine, and outdoor electrical installations. Enhanced sealing prevents moisture ingress even in extreme weather conditions, preserving conductor safety and performance. Innovations in flexible conduit design also accommodate increased electrical loads and higher voltage requirements, meeting the evolving demands of modern electrical infrastructure.
Integration with Automation and Smart Infrastructure Expands Market Potential
The ongoing adoption of automation, smart buildings, and Industry 4.0 technologies propels the need for advanced conduit systems capable of protecting sensitive electrical and data cabling. The Commercial Liquid Tight Flexible Metal Conduit Market gains momentum from growing investments in automated manufacturing facilities, intelligent office complexes, and high-tech data centers. It ensures the protection of wiring against electromagnetic interference, moisture, and physical damage while enabling seamless integration with IoT devices and networked control systems. The emergence of smart cities and intelligent infrastructure initiatives globally reinforces the requirement for reliable conduit systems that uphold operational continuity, minimize downtime, and support real-time monitoring and maintenance. These trends position the market for sustained growth driven by innovation and expanding applications.
Market Trends
Increasing Adoption of Advanced Materials to Improve Durability and Environmental Resistance
The Commercial Liquid Tight Flexible Metal Conduit Market is witnessing a marked shift toward advanced materials that significantly enhance product durability, corrosion resistance, and flexibility. Manufacturers increasingly use stainless steel, aluminum alloys, and polymer-coated metals to meet the demands of harsh industrial environments, including chemical processing plants, oil refineries, and outdoor electrical installations exposed to moisture and extreme temperatures. It ensures conduits maintain structural integrity while providing effective protection against corrosive substances, abrasion, and physical impacts. The integration of lightweight yet robust materials also reduce installation time and labor costs, which improves overall project efficiency. This trend responds to growing requirements for longer-lasting, low-maintenance conduit solutions capable of withstanding challenging environmental conditions in sectors such as mining, manufacturing, and infrastructure development.
- For instance, ABB developed a liquid-tight flexible metal conduit that incorporates a stainless-steel outer jacket with a polymer inner lining, achieving a corrosion resistance rating of 316L stainless steel, which withstands exposure to chloride environments for over 2,000 hours in salt spray tests, substantially extending product lifespan in harsh conditions.
Growing Preference for Flexible, Easy-to-Install Conduits Supports Complex Electrical Designs
Flexibility and ease of installation have become critical drivers in the Commercial Liquid Tight Flexible Metal Conduit Market. Conduits that bend without losing mechanical strength allow electrical contractors to navigate intricate layouts, tight spaces, and irregular architectural designs with minimal use of connectors or fittings. It streamlines the installation process, reduces project timelines, and lowers labor expenses. The market increasingly embraces modular and pre-fabricated conduit assemblies, which facilitate faster deployment in commercial buildings, data centers, and industrial facilities. This trend aligns with the broader industry imperative to minimize downtime and optimize construction workflows. Demand also rises for conduits that comply with evolving safety standards while providing high levels of mechanical protection and liquid tightness.
- For instance, Atkore manufactures over 120 million feet of liquid-tight flexible metal conduit annually, supporting complex electrical designs with products engineered for optimal flexibility and durability.
Integration with Smart Infrastructure, IoT, and Automation Elevates Conduit Performance Requirements
The rapid expansion of smart infrastructure projects and automation across manufacturing, commercial, and municipal sectors drives the Commercial Liquid Tight Flexible Metal Conduit Market toward more sophisticated product offerings. Modern conduits must safeguard sensitive data and electrical wiring from electromagnetic interference (EMI), moisture, and mechanical damage, ensuring consistent performance of IoT devices, sensors, and networked control systems. It supports reliable data transmission and operational continuity in environments with high electrical noise or harsh weather conditions. Conduits that facilitate integration with telematics, asset tracking, and remote monitoring technologies gain preference, reflecting the market’s shift toward intelligent, connected electrical systems. This development promotes innovation in conduit design and materials to meet the increasing technical demands of Industry 4.0 and smart city deployments.
Sustainability and Regulatory Compliance Shape Product Development and Procurement Choices
Environmental sustainability and regulatory frameworks significantly influence trends in the Commercial Liquid Tight Flexible Metal Conduit Market. Manufacturers prioritize eco-friendly raw materials, energy-efficient production techniques, and recyclable components to reduce environmental impact and comply with international regulations. It drives the creation of conduits that minimize emissions during manufacture and support circular economy initiatives. Strict adherence to global safety and environmental standards compels companies to innovate while maintaining product reliability and performance. Buyers increasingly seek conduit systems that align with corporate sustainability goals and meet rigorous compliance requirements, influencing procurement strategies in industries ranging from construction to energy and transportation. This focus on sustainability encourages long-term market growth and fosters responsible manufacturing practices.
Market Challenges Analysis
Stringent Regulatory Compliance, Complex Installation Processes, and Elevated Costs Restrain Market Growth
The Commercial Liquid Tight Flexible Metal Conduit Market encounters significant challenges stemming from stringent regulatory frameworks and safety standards imposed by various international and regional authorities. Ensuring full compliance with electrical codes related to fire safety, moisture resistance, and mechanical durability requires manufacturers to invest heavily in research, testing, and certification processes. It raises production costs, which translates into higher prices for end-users. The specialized installation techniques demand skilled labor and precision, further escalating project expenses and extending installation timelines. In emerging economies with limited access to trained electricians, this complexity restricts widespread adoption despite increasing infrastructure investments. Contractors often face difficulties balancing regulatory adherence with budget constraints, which can delay or limit project approvals. These factors collectively create barriers for new entrants and restrict market penetration in price-sensitive regions, slowing the overall growth trajectory of the industry.
Competition from Alternative Wiring Protection Solutions and Market Fragmentation Impede Adoption
The Commercial Liquid Tight Flexible Metal Conduit Market contends with robust competition from substitute products such as flexible plastic conduits, rigid PVC pipes, and non-metallic tubing systems. These alternatives often appeal to sectors with less stringent environmental and mechanical protection requirements due to their lower upfront costs and simpler installation methods. It challenges the metal conduit segment to justify its premium pricing by emphasizing superior durability, flexibility, and long-term reliability. In residential and light commercial applications, decision-makers frequently opt for these cost-effective alternatives, limiting the metal conduit’s market share expansion. Furthermore, the market experiences fragmentation with numerous regional players offering varying quality standards, complicating procurement and supply chain processes for large-scale projects. Convincing end-users to transition from familiar, lower-cost materials to more advanced metal conduit systems requires ongoing innovation and education efforts. Overcoming this customer inertia remains a critical obstacle to broader adoption and sustained market growth.
Market Opportunities
Expansion into Emerging Markets with Growing Infrastructure and Industrialization Needs
The Commercial Liquid Tight Flexible Metal Conduit Market finds significant opportunities in emerging economies were rapid urbanization and industrialization drive demand for reliable electrical infrastructure. Governments in regions such as Asia-Pacific, Latin America, and the Middle East continue to invest heavily in public utilities, commercial buildings, and manufacturing facilities. It enables growth by creating a steady requirement for durable and flexible conduit systems capable of handling complex electrical layouts in harsh environments. Expanding construction activities in these regions also encourage adoption of liquid-tight conduits that offer superior protection against moisture and corrosion. Growing awareness of electrical safety and rising standards across developing countries further support market penetration. The expanding power generation and distribution networks in these markets present ongoing opportunities for product innovation and customization.
Technological Advancements and Integration with Smart Electrical Systems Foster Market Growth
Technological innovation presents promising prospects for the Commercial Liquid Tight Flexible Metal Conduit Market through enhanced product features and compatibility with smart infrastructure. The market can capitalize on developments in corrosion-resistant coatings, lightweight alloys, and improved sealing technologies to meet evolving customer demands. It enables longer product life, reduced maintenance, and better adaptability to diverse environmental conditions. Integration with intelligent electrical systems and IoT infrastructure increases the need for conduits that protect sensitive wiring from electromagnetic interference and physical damage. The growing emphasis on sustainable construction practices also encourages the adoption of eco-friendly conduit materials and manufacturing processes. These advancements position the market to serve high-value applications across commercial, industrial, and critical infrastructure sectors, driving future growth.
Market Segmentation Analysis:
By Material
The Commercial Liquid Tight Flexible Metal Conduit Market includes key materials such as aluminium, stainless steel, copper, and non-metallic types. Stainless steel dominates due to its high resistance to corrosion and superior mechanical strength, especially in chemically aggressive or high-moisture environments like oil refineries and marine facilities. Aluminium conduits offer a lightweight alternative that simplifies installation in commercial construction and reduces load on structural systems. Copper, though used less frequently due to its higher cost, provides excellent conductivity and durability in critical systems. Non-metallic conduits, typically made from PVC or polymer blends, are preferred in applications requiring electrical insulation, chemical resistance, or flexibility in confined spaces.
- For instance, Electri-Flex Company produces over 15 million feet of stainless steel liquid-tight flexible conduit annually, specifically engineered to meet the demanding conditions of industrial and marine applications, ensuring long-term durability and corrosion resistance.
By Application
Based on application, the Commercial Liquid Tight Flexible Metal Conduit Market is segmented into industrial, commercial, residential, and telecommunications. The industrial segment holds a leading position, driven by high demand for rugged conduit systems in manufacturing plants, processing facilities, and heavy equipment installations. The commercial sector also shows strong adoption, with office complexes, retail centers, and institutional buildings requiring flexible wiring systems to support modern layouts. Residential usage is comparatively limited but growing in areas prone to moisture or where code requirements demand sealed conduit protection. Telecommunications applications rely on these conduits to protect fiber optic and coaxial cables, particularly in outdoor or buried installations.
- For instance, according to a report by the National Electrical Manufacturers Association (NEMA), over 18 million feet of liquid-tight flexible metal conduit are utilized annually in industrial applications across North America, reflecting the essential role these products play in ensuring electrical safety and durability in demanding environments.
By End-User
End-user segmentation includes construction, manufacturing, telecommunications, and utilities. The construction sector remains the primary consumer, with demand supported by new building projects, infrastructure upgrades, and retrofitting efforts that require durable and weather-resistant conduit systems. Manufacturing operations use these conduits to ensure safe and efficient routing of electrical and control cables under continuous operating conditions. The telecommunications industry requires conduit systems that shield sensitive signal lines from mechanical damage and environmental interference. Utilities implement liquid tight conduits in power generation and distribution systems, substations, and control panels to enhance electrical safety and maintain long-term system performance. The Commercial Liquid Tight Flexible Metal Conduit Market serves each segment with tailored solutions that combine flexibility, resilience, and regulatory compliance.
Segments:
Based on Material:
- Aluminium
- Stainless Steel
- Copper
- Non-metallic
Based on Application:
- Industrial
- Commercial
- Residential
- Telecommunications
Based on End-User:
- Construction
- Manufacturing
- Telecommunications
- Utilities
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share, accounting for approximately 38% of the global commercial liquid tight flexible metal conduit market. This dominant position is primarily driven by a well-developed commercial infrastructure, a mature construction sector, and a strict regulatory environment surrounding electrical safety. The United States remains the core market within the region, fueled by the continual development of commercial office spaces, healthcare facilities, educational institutions, and smart buildings. The region places significant emphasis on building code compliance and fire safety, leading to widespread use of liquid tight flexible metal conduits in various commercial settings. Furthermore, the rise of data centers, industrial automation, and green building certifications (such as LEED) has intensified demand for robust and flexible electrical conduit solutions. North American manufacturers benefit from high domestic demand, and several companies invest heavily in R&D to create more efficient, corrosion-resistant, and installation-friendly conduit systems. This innovation cycle keeps the region ahead in both product quality and adoption rate.
Europe
Europe holds the second-largest share, contributing roughly 26% to the global market. The region’s success is rooted in its advanced infrastructure, strict regulatory compliance, and strong focus on energy efficiency and sustainability in construction. Western European countries such as Germany, the UK, and France have consistently updated their building and electrical standards, driving adoption of premium conduit systems that meet performance and environmental requirements. In addition to new construction projects, Europe experiences strong demand from refurbishment and modernization initiatives aimed at upgrading aging commercial buildings. Liquid tight flexible metal conduits are particularly favored in projects where both mechanical protection and environmental sealing are needed, such as underground wiring or industrial HVAC systems. The European Union’s push for net-zero buildings and green infrastructure also acts as a catalyst for the market. Moreover, the presence of several prominent manufacturers and distributors across the continent ensures a steady supply chain and customer support network, contributing to Europe’s stable market performance.
Asia Pacific
Asia Pacific commands a 21% market share, ranking third in size but first in growth rate. This region presents the most dynamic expansion opportunities, driven by rapid urbanization, population growth, and an aggressive push toward industrial and commercial development. Countries such as China, India, Japan, and South Korea are at the forefront of this growth, with large-scale investments in infrastructure, smart cities, IT parks, and transportation hubs. As construction activity accelerates, so does the need for safe, flexible, and durable electrical conduit systems. The growing adoption of building automation systems, increased awareness of fire safety, and updated electrical codes in several APAC countries further enhance market penetration. Additionally, many multinational manufacturers are shifting production and distribution centers to Asia to capitalize on lower labor costs and growing local demand. While the current market share remains behind North America and Europe, the region’s compound annual growth rate suggests it may overtake its counterparts in the near future if current trends continue.
Latin America
Latin America accounts for approximately 9% of the global market, reflecting a moderate yet growing demand for commercial liquid tight flexible metal conduits. Brazil and Mexico are the largest contributors in the region, supported by an increasing number of commercial construction projects and government initiatives aimed at upgrading infrastructure. While economic volatility and uneven regulatory enforcement have historically limited rapid growth, recent policy changes and urban development projects are improving market prospects. The adoption of modern building techniques, coupled with an increase in private sector investments, is encouraging the use of high-quality electrical conduit systems. Moreover, as Latin American nations continue to modernize their commercial spaces—particularly in retail, hospitality, and healthcare—the need for reliable and safe wiring protection solutions becomes more apparent. Although Latin America’s share remains smaller compared to global leaders, it is viewed as a developing market with significant untapped potential.
Middle East & Africa (MEA)
The Middle East & Africa holds the smallest share, contributing around 6% to the global market. Despite its current position, the region shows strong potential due to ambitious infrastructure development plans, particularly in the Gulf Cooperation Council (GCC) countries such as the UAE, Saudi Arabia, and Qatar. Major commercial projects—including business districts, hotels, airports, and retail centers—are underway as these nations strive to diversify their economies beyond oil. These developments necessitate reliable electrical systems, which in turn boost demand for liquid tight flexible metal conduits that can withstand high temperatures, moisture, and dust. In Africa, urbanization and electrification efforts are slowly creating market opportunities, although adoption remains lower due to economic and logistical challenges. Nonetheless, the gradual improvement of building codes and safety awareness is likely to drive steady demand. MEA remains a strategically important region for future growth, particularly as international manufacturers increase their presence through partnerships and local production units.
Key Player Analysis
- Kaiphone Technology Co., Ltd.
- Anamet Electrical, Inc.
- AFi ELEKTROMEKANIK
- Electri-Flex Company
- Eddy Group Limited
- ABB
- Atkore
- Heyco
- Eaton
- Delikon Electric Flexible Conduit
Competitive Analysis
The Commercial Liquid Tight Flexible Metal Conduit Market include Atkore, ABB, Eaton, Electri-Flex Company, Anamet Electrical Inc., Delikon Electric Flexible Conduit, Heyco, Kaiphone Technology Co., Ltd., AFi ELEKTROMEKANIK, and Eddy Group Limited. The Commercial Liquid Tight Flexible Metal Conduit market is highly competitive, driven by rapid technological advancements and growing demand for safe, durable, and flexible electrical wiring solutions across commercial and industrial sectors. Manufacturers continually invest in research and development to enhance product features such as moisture resistance, corrosion protection, mechanical strength, and ease of installation to comply with increasingly stringent global electrical safety regulations. Innovation focuses on improving conduit flexibility without compromising durability, enabling efficient routing in complex building infrastructures and smart facilities. The market landscape is further shaped by rising infrastructure development, urbanization, and the adoption of smart building technologies, which increase the need for flexible conduit systems that ensure both safety and operational efficiency. To sustain competitive advantage, companies prioritize expanding their geographical presence, particularly targeting emerging economies where commercial construction is booming.
Recent Developments
- In August 2025, Eddy Group Limited showcased the grand opening of a new showroom in Dieppe, which was designed in close collaboration with their team and partners.
- In September 2024, Atkore Flexicon expanded its LFMC offerings with new hinged fittings and locknuts designed for retrofit applications, enhancing system adaptability and simplifying installations in industrial and commercial settings.
- In 2024, the conduit market is seeing a rise in intelligent solutions featuring enhanced corrosion resistance, easier installation, and potential IoT integration for diagnostics and monitoring. This trend reflects a broader shift towards "Smart" infrastructure, where systems are designed for efficiency, real-time data analysis, and remote management.
Market Concentration & Characteristics
The Commercial Liquid-Tight Flexible Metal Conduit Market exhibits a moderately concentrated structure, dominated by several well-established players that hold significant market shares. These companies benefit from strong brand recognition, extensive distribution networks, and advanced manufacturing capabilities, which create high entry barriers for new competitors. The market demands high-quality, reliable products that comply with stringent safety and environmental regulations, driving continuous innovation and product differentiation among leading firms. It features a mix of global corporations and regional manufacturers, with global players focusing on broad product portfolios and geographic expansion to maintain leadership. Regional companies compete by offering cost-effective solutions tailored to local requirements and regulatory frameworks. Customer preferences emphasize durability, flexibility, and resistance to harsh environmental conditions, which influence product development strategies. The market’s growth stems from increasing commercial construction activities, infrastructure modernization, and adoption of smart building technologies, requiring flexible and liquid-tight conduit solutions for safe electrical wiring. Supply chain efficiency and strategic partnerships further strengthen the position of dominant players. Given these characteristics, the market maintains a competitive yet stable environment, where innovation, compliance, and market reach determine success. It continues to evolve with technological advancements and shifting end-user demands, encouraging key players to optimize their offerings and operational strategies to sustain growth.
Report Coverage
The research report offers an in-depth analysis based on Material, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by expanding commercial construction worldwide.
- Increasing adoption of smart building technologies will boost demand for flexible and reliable conduit systems.
- Manufacturers will focus on developing more durable and corrosion-resistant products to meet stricter safety standards.
- Emerging economies will offer significant growth opportunities due to urbanization and infrastructure development.
- Regulatory compliance and sustainability initiatives will drive innovation in environmentally friendly conduit materials.
- Companies will invest in automation and advanced manufacturing processes to improve product quality and reduce costs.
- The demand for customized conduit solutions will increase to address specific application requirements.
- Strategic partnerships and mergers will help key players expand their global footprint and technological capabilities.
- Integration of IoT and smart grid technologies will create new opportunities for advanced conduit products.
- Market competition will intensify as new entrants focus on regional markets with cost-effective offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Commercial Liquid-Tight Flexible Metal Conduit Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Commercial Liquid-Tight Flexible al Conduit Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Commercial Liquid-Tight Flexible Metal Conduit Market?
Who are the leading companies in the Commercial Liquid-Tight Flexible Metal Conduit Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Commercial Liquid Tight Flexible Metal Conduit Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Commercial Liquid Tight Flexible Metal Conduit Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 158.4 million → 2032: USD 270.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Commercial Liquid Tight Flexible Metal Conduit Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Commercial Liquid Tight Flexible Metal Conduit Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Commercial Liquid Tight Flexible Metal Conduit Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Commercial Liquid Tight Flexible Metal Conduit Market Drivers
- 3.3 Commercial Liquid Tight Flexible Metal Conduit Market Restraints & Challenges
- 3.4 Commercial Liquid Tight Flexible Metal Conduit Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Commercial Liquid Tight Flexible Metal Conduit Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Commercial Liquid Tight Flexible Metal Conduit Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Commercial Liquid Tight Flexible Metal Conduit category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Commercial Liquid Tight Flexible Metal Conduit Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Commercial Liquid Tight Flexible Metal Conduit Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Commercial Liquid Tight Flexible Metal Conduit market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Commercial Liquid Tight Flexible Metal Conduit Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Commercial Liquid Tight Flexible Metal Conduit Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Commercial Liquid Tight Flexible Metal Conduit Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Commercial Liquid Tight Flexible Metal Conduit (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Commercial Liquid Tight Flexible Metal Conduit Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Commercial Liquid Tight Flexible Metal Conduit Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Commercial Liquid Tight Flexible Metal Conduit Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Commercial Liquid Tight Flexible Metal Conduit Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Commercial Liquid Tight Flexible Metal Conduit Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Commercial Liquid Tight Flexible Metal Conduit Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Commercial Liquid Tight Flexible Metal Conduit Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Commercial Liquid Tight Flexible Metal Conduit Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Commercial Liquid Tight Flexible Metal Conduit Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
