
Germany Gift Card Market Overview:
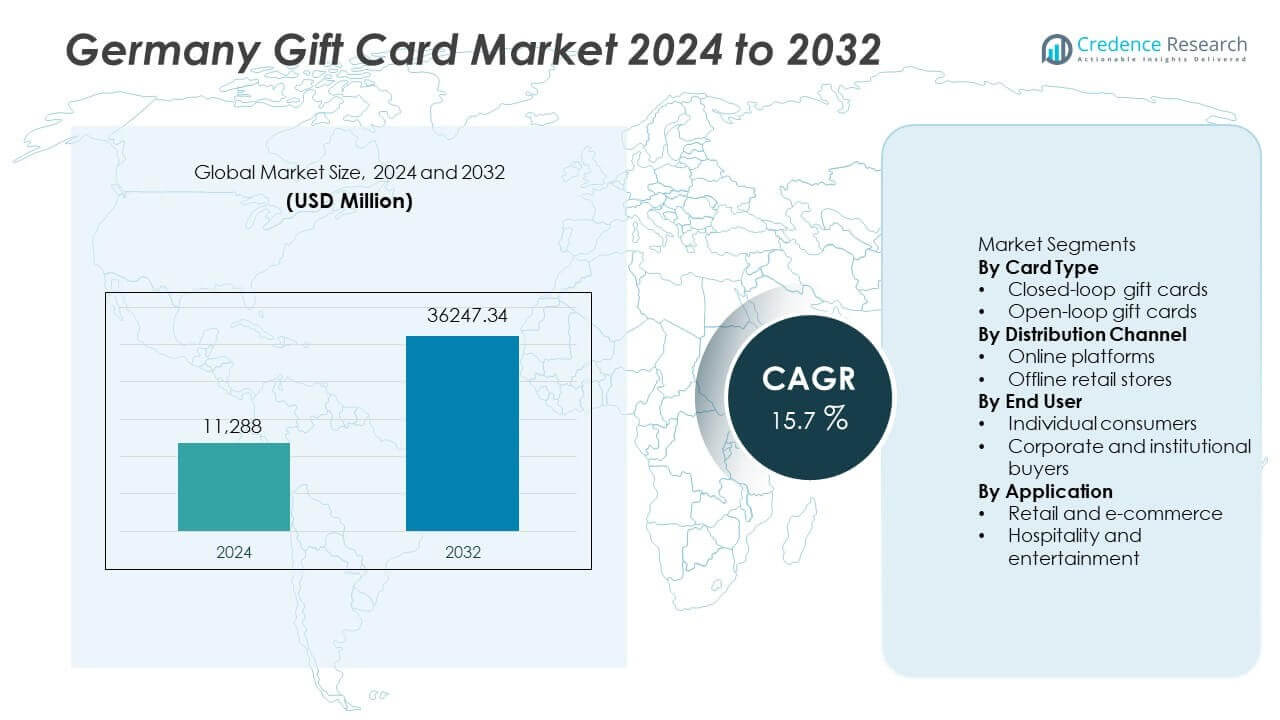
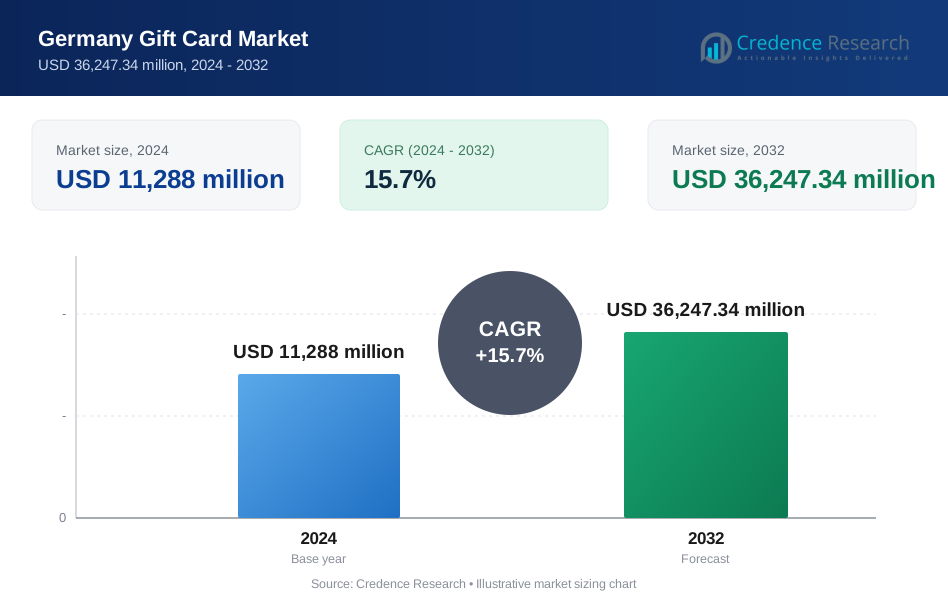
The Germany gift card market was valued at USD 11,288 million in 2024 and is projected to reach USD 36,247.34 million by 2032, registering a CAGR of 15.7% during the forecast period. (Credence Research)
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Gift Card Market Size 2024 | USD 11,288 million |
| Germany Gift Card Market, CAGR | 15.7% |
| Germany Gift Card Market Size 2032 | USD 36,247.34 million |
The Germany gift card market is led by major players such as Amazon Deutschland, REWE Group, Edeka Group, MediaMarktSaturn Retail Group, Zalando SE, IKEA Germany, Paysafecard Group, Blackhawk Network Germany, Apple Germany, and Google. These companies dominate through strong brand recognition, extensive retail and digital distribution, and integrated payment ecosystems. Amazon, Zalando, and Apple drive digital gift card adoption, while REWE, Edeka, and MediaMarktSaturn strengthen physical and omnichannel reach. Regionally, Western Germany leads the market with a 38.6% share, supported by dense retail networks, high corporate activity, and strong digital payment penetration. Southern Germany follows with 29.4% share, driven by high purchasing power and premium consumption patterns. Together, these regions form the core demand base for gift cards in Germany.
Germany Gift Card Market Insights
- The Germany gift card market was valued at USD 11,288 million in 2024 and is projected to reach USD 36,247.34 million by 2032, growing at a CAGR of 15.7% during the forecast period.
- Strong growth is driven by rising digital payment adoption, expanding e-commerce activity, and increasing use of gift cards in corporate incentive and employee reward programs across multiple industries.
- Market trends highlight rapid adoption of digital and personalized gift cards, with closed-loop gift cards leading the card type segment at a 64.2% market share due to strong retailer control and loyalty integration.
- Competitive dynamics remain intense, with leading players focusing on omnichannel distribution, instant digital delivery, fraud prevention, and experience-based gifting to strengthen customer engagement.
- Regionally, Western Germany dominates with a 38.6% market share, followed by Southern Germany at 29.4%, while Northern Germany holds 19.1% and Eastern Germany accounts for 12.9%, reflecting varied retail maturity and digital penetration levels.
Germany Gift Card Market Segmentation Analysis:
By Card Type
The card type segment in the Germany gift card market is led by closed-loop gift cards, which account for 64.2% market share. Closed-loop cards dominate due to strong adoption across large retail chains, supermarkets, fashion brands, and digital commerce platforms. These cards offer better control over redemption, brand-specific loyalty benefits, and lower processing costs for issuers. Retailers actively use closed-loop cards to drive repeat purchases and customer retention through exclusive rewards and promotions. Open-loop gift cards hold the remaining share and are mainly used for broader spending flexibility. However, tighter regulatory requirements and higher transaction fees limit faster adoption compared to closed-loop offerings.
- For instance, REWE Group integrated closed-loop gift cards across more than 3,800 German stores, enabling redemption within its POS systems.
By Distribution Channel
The distribution channel segment is dominated by online platforms, holding a 58.6% market share in Germany. Online channels lead due to rising e-commerce penetration, mobile payment usage, and instant digital gift card delivery. Consumers prefer online platforms for convenience, personalization options, and immediate redemption. Digital wallets and email-based gifting support seamless usage across retail and service categories. Corporate buyers also favor online channels for bulk purchases and automated distribution. Offline retail stores maintain relevance through impulse buying and seasonal demand, especially during holidays. However, limited customization and physical inventory constraints reduce their competitive advantage compared to digital-first platforms.
- For instance, Amazon Deutschland enables digital gift card delivery within seconds via email and app-based wallets. The platform supports multiple denomination options and large-scale corporate bulk issuance.
By End User
The end-user segment is led by individual consumers, representing 61.9% market share in the Germany gift card market. Individual buyers drive demand through personal gifting, festive spending, and everyday discretionary use. Gift cards are widely used for birthdays, holidays, and special occasions due to flexibility and ease of use. Digital adoption further supports individual usage through mobile apps and online marketplaces. Corporate and institutional buyers account for the remaining share, supported by employee rewards, incentive programs, and customer engagement campaigns. However, procurement cycles and budget controls slow adoption compared to the faster-growing individual consumer segment.
Key Growth Drivers
Rising Digital Payment Adoption
Digital payment adoption acts as a major growth driver in the Germany gift card market. Consumers increasingly prefer cashless transactions across retail, dining, and online services. Gift cards integrate smoothly with mobile wallets, banking apps, and e-commerce platforms. This compatibility improves convenience and redemption speed. Younger consumers favor digital gift cards due to instant delivery and ease of use. Retailers benefit from lower handling costs and reduced fraud exposure. Expanding contactless infrastructure across Germany further supports adoption. As digital payment habits strengthen nationwide, gift cards gain acceptance as both gifting tools and alternative payment instruments.
- For instance, PayPal supports a substantial number of active user accounts in Germany, enabling seamless digital gift card redemption across a vast network of merchants.
Growth of Corporate Incentives and Rewards Programs
Corporate incentives represent a strong growth driver for the Germany gift card market. Organizations use gift cards for employee rewards, sales incentives, and customer loyalty initiatives. Gift cards offer controlled spending and operational simplicity compared to cash rewards. Employers value tax efficiency and ease of digital distribution. Bulk issuance platforms support scalable deployment across large teams. Hybrid work models increase demand for digital rewards over physical benefits. Custom branding enhances engagement and program effectiveness. As companies focus on retention and motivation, gift cards remain a preferred incentive solution across multiple industry sectors.
- For instance, Edenred Germany serves over 1 million employees through digital benefit and reward card solutions used by thousands of employers.
Expansion of E-commerce and Organized Retail The rapid expansion of e-commerce and organized retail continues to drive gift card adoption in Germany. Online platforms actively promote gift cards during seasonal campaigns and checkout processes. Consumers use gift cards for prepaid purchases and flexible gifting. Organized retailers integrate gift cards into loyalty programs and omnichannel strategies. Seamless redemption across online and physical stores improves customer experience. Subscription services and digital entertainment platforms expand usage scenarios. Retailers benefit from upfront cash flow and improved customer retention. Continued growth in digital retail channels strengthens the role of gift cards in everyday transactions.
Key Trends & Opportunities
Shift Toward Digital and Personalized Gift Cards
Digital and personalized gift cards emerge as a key trend and opportunity. Consumers prefer instant delivery, customizable designs, and personalized messages. Digital formats reduce environmental impact and logistical costs. Retailers use customer data to offer targeted gift card recommendations. Personalization enhances emotional value and increases gifting frequency. Corporate buyers adopt branded digital cards for targeted engagement campaigns. Integration with mobile apps supports real-time tracking and promotional offers. This shift creates opportunities for technology providers delivering secure, scalable personalization solutions that enhance customer engagement and brand differentiation.
- For instance, Zalando enables digital gift card personalization across its app and website, supporting instant delivery to millions of active customer accounts.
Rising Popularity of Experience-Based Gifting
Experience-based gifting presents strong growth opportunities in the Germany gift card market. Consumers increasingly prioritize experiences over physical goods. Gift cards linked to travel, dining, wellness, and entertainment gain popularity. Younger demographics drive demand for lifestyle-focused rewards. Experience-based cards offer flexibility while supporting memorable consumption. Service providers benefit from higher engagement and repeat visits. Corporate reward programs also adopt experience gifting to improve satisfaction. As discretionary spending recovers, experience-driven gift cards expand beyond retail, supporting market diversification across service-based industries.
- For instance, Jochen Schweizer Arena offers experience gift cards covering hundreds of curated activities across Germany, including driving, flying, and wellness experiences.
Key Challenges
Regulatory Compliance and Tax Complexity
Regulatory compliance remains a major challenge in the Germany gift card market. Gift cards face complex tax treatment depending on redemption conditions and validity terms. Companies must comply with VAT rules and financial reporting standards. Cross-border usage introduces additional compliance requirements. These factors increase operational and administrative costs for issuers. Smaller players face difficulties in regulatory interpretation and implementation. Frequent regulatory updates require continuous system adjustments. Compliance complexity slows innovation and increases barriers to entry, highlighting the need for clearer frameworks and digital compliance solutions.
Fraud Risks and Unused Balances
Fraud risks and unused balances continue to challenge market stability. Digital gift cards face threats from phishing, code theft, and unauthorized access. Fraud incidents undermine consumer trust and increase security investments. Unredeemed balances also create reputational and regulatory concerns. Limited redemption options discourage usage in some cases. Retailers must balance security controls with customer convenience. Advanced monitoring and encryption systems raise operational costs. Addressing fraud while improving redemption flexibility remains critical to maintaining confidence and supporting long-term market growth.
Regional Analysis
Western Germany
Western Germany holds the largest share of the Germany gift card market at 38.6%, supported by strong economic activity and dense retail infrastructure. Major metropolitan areas such as North Rhine-Westphalia drive high gift card adoption through organized retail, e-commerce, and corporate incentive programs. High concentration of multinational companies increases demand for employee rewards and customer engagement tools. Digital gift cards gain strong traction due to advanced payment infrastructure and high smartphone usage. Retailers actively promote gift cards through omnichannel strategies. Strong consumer spending power and corporate presence continue to position Western Germany as the leading regional contributor.
Southern Germany
Southern Germany accounts for 29.4% market share, driven by strong purchasing power and a large base of premium consumers. Regions such as Bavaria and Baden-Württemberg support demand through high retail spending and widespread adoption of digital payments. Corporate gift card usage remains strong due to the presence of large manufacturing, automotive, and technology firms. Consumers prefer branded and experience-based gift cards, particularly in travel, dining, and lifestyle categories. High tourism activity also supports seasonal gift card sales. Strong digital infrastructure and preference for high-quality offerings reinforce steady growth across the southern region.
Northern Germany
Northern Germany holds 19.1% market share, supported by a balanced mix of retail, logistics, and service-sector activity. Urban centers such as Hamburg drive demand through e-commerce, entertainment, and hospitality-linked gift cards. Consumers show growing preference for digital formats, especially for online shopping and subscription services. Corporate gifting demand remains moderate but stable, supported by port operations, trade services, and logistics firms. Retail chains in the region actively integrate gift cards into loyalty programs. Increasing digital adoption and steady consumer spending contribute to consistent growth in Northern Germany.
Eastern Germany
Eastern Germany represents 12.9% market share, reflecting gradual adoption across developing retail and service ecosystems. Urban centers such as Berlin drive regional demand through digital platforms, startups, and experience-based gifting. Younger consumers favor digital gift cards for entertainment, dining, and online services. Corporate usage remains lower compared to western regions but shows steady improvement. Expansion of organized retail and rising e-commerce penetration support market growth. Government and private sector investments in digital infrastructure improve accessibility. As consumer awareness increases, Eastern Germany continues to offer long-term growth potential within the national market.
Germany Gift Card Market Segmentations:
By Card Type
- Closed-loop gift cards
- Open-loop gift cards
By Distribution Channel
- Online platforms
- Offline retail stores
By End User
- Individual consumers
- Corporate and institutional buyers
By Application
- Retail and e-commerce
- Hospitality and entertainment
By Geography
- Western Germany
- Southern Germany
- Northern Germany
- Eastern Germany
Competitive Landscape
Competitive landscape analysis of the Germany gift card market highlights strong competition among Amazon Deutschland, REWE Group, Edeka Group, MediaMarktSaturn Retail Group, Zalando SE, IKEA Germany, Paysafecard Group, Blackhawk Network Germany, Apple Germany, and Google. These players compete through broad brand acceptance, extensive distribution networks, and advanced digital platforms. Leading retailers focus on closed-loop ecosystems to improve customer retention and data-driven promotions. Digital-first players emphasize instant delivery, mobile wallet integration, and fraud prevention technologies. Corporate-focused providers strengthen positions through bulk issuance tools and customization capabilities. Partnerships with fintech firms support secure payment processing and regulatory compliance. Seasonal campaigns and omnichannel strategies remain key competitive levers. Smaller players face pressure from pricing, scale advantages, and technology investments by established brands. Continuous innovation in personalization, experience-based offerings, and digital redemption defines competitive differentiation in the German market.
Key Player Analysis
- Amazon Deutschland
- REWE Group
- Edeka Group
- MediaMarktSaturn Retail Group
- IKEA Germany
- Zalando SE
- Apple Germany
- Google (Google Play Gift Cards)
- Paysafecard Group
- Blackhawk Network Germany
Recent Developments
- In March 2025, Amazon Deutschland continued expanding digital and physical gift card options on its German platform.
- In 2025, REWE Group maintained its supermarket gift card presence as part of broader retail gift programs.
- In 2025, Edeka Group similarly upheld extensive gift card offerings across its stores. Edeka is highlighted as a leading gift card provider in Germany’s retail sector.
Report Coverage
The research report offers an in-depth analysis based on Card Type, Distribution Channel, End User, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Digital gift cards will gain wider adoption across retail, services, and entertainment platforms.
- Mobile wallet integration will improve ease of purchase, storage, and redemption.
- Corporate incentive programs will increase demand for bulk and customizable gift cards.
- Experience-based gift cards will expand across travel, dining, and wellness categories.
- Personalization features will strengthen customer engagement and repeat usage.
- Omnichannel redemption options will become a standard offering among retailers.
- Advanced security technologies will reduce fraud and improve consumer trust.
- Regulatory clarity will support smoother operations and faster product innovation.
- Regional demand will rise steadily in Northern and Eastern Germany.
- Strategic partnerships will strengthen distribution reach and market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Digital Payment Adoption
The increasing preference for cashless transactions and the integration of gift cards with mobile wallets, banking apps, and e-commerce platforms are making gift cards more convenient and accessible, driving market growth.
Growth of Corporate Incentives and Rewards Programs
German companies are increasingly using gift cards for employee rewards, sales incentives, and customer loyalty programs, benefiting from operational simplicity, tax efficiency, and scalable digital distribution.
Expansion of E-commerce and Organized Retail
The rapid growth of e-commerce and organized retail in Germany is boosting gift card adoption, as online and omnichannel retailers promote gift cards for prepaid purchases, flexible gifting, and loyalty integration.
Shift Toward Digital and Personalized Gift Cards
Consumers are favoring digital and personalized gift cards for instant delivery, customization, and ease of use, prompting retailers to invest in technology that enhances customer engagement and brand differentiation.
Rising Popularity of Experience-Based Gifting
There is a growing trend toward experience-based gift cards in categories like travel, dining, and wellness, as consumers - especially younger demographics - prioritize memorable experiences over physical goods.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Germany Gift Card market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Germany Gift Card market projected to grow between 2024 and 2032?
Which Germany Gift Card market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Germany Gift Card market?
Who are the leading companies in the Germany Gift Card market?
Which region commanded the largest share of the Germany Gift Card market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Individual consumers
- 1.2.2 Corporate and institutional buyers
- 1.3 By Card Type
- 1.3.1 Closed-loop gift cards
- 1.3.2 Open-loop gift cards
- 1.4 By Application
- 1.4.1 Retail and e-commerce
- 1.4.2 Hospitality and entertainment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,288 million → 2032: USD 36,247.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Gift Card Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Gift Card Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Germany Gift Card Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Germany Gift Card Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Gift Card Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Gift Card Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Gift Card Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Gift Card Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,288 million → 2032: USD 36,247.34 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Gift Card Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual consumers
- 12.3.7.2 Corporate and institutional buyers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Card Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Closed-loop gift cards
- 12.4.7.2 Open-loop gift cards
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Retail and e-commerce
- 12.5.7.2 Hospitality and entertainment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Gift Card End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Gift Card Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Gift Card Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Gift Card Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon Deutschland
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 REWE Group
- 18.4 Edeka Group
- 18.5 MediaMarktSaturn Retail Group
- 18.6 Zalando SE
- 18.7 IKEA Germany
- 18.8 Apple Germany
- 18.9 Google (Google Play Gift Cards)
- 18.10 Paysafecard Group
- 18.11 Blackhawk Network Germany
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

