
Market Overview:
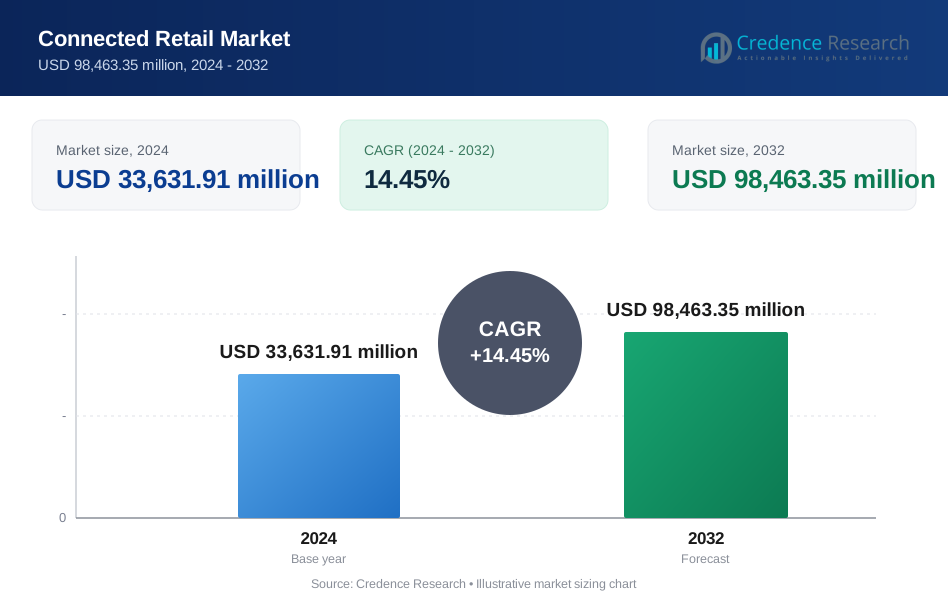
The Connected Retail Market size was valued at USD 21,200.00 million in 2018 to USD 33,631.91 million in 2024 and is anticipated to reach USD 98,463.35 million by 2032, at a CAGR of 14.45 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Connected Retail market Size 2023 | USD 33,631.91 million |
| Connected Retail market, CAGR | 14.45 % |
| Connected Retail market Size 2032 | USD 98,463.35 million |
Rising customer expectations for personalized experiences, along with technological advancements in IoT and AI, are driving adoption in the Connected Retail Market. It empowers retailers to bridge physical and digital commerce, using real-time data analytics, smart shelves, and automated checkout to optimize operations and enhance customer engagement. It enables agile inventory management, accurate demand forecasting, and faster fulfillment, significantly improving customer satisfaction and retention. The integration of connected retail solutions also supports dynamic pricing and targeted promotions, enhancing revenue potential.
North America and Europe are leading regions due to strong digital infrastructure and early technology adoption. Asia Pacific is an emerging region fueled by growing retail digitization in China and India. Latin America, the Middle East, and Africa are showing increased investment in smart retail technologies, supported by expanding e-commerce penetration and infrastructure improvements. The market is rapidly expanding across both developed and developing economies. Government initiatives supporting digital transformation in retail are further accelerating regional growth.
Market Insights:
- The Connected Retail Market was valued at USD 21,200.00 million in 2018 and is projected to reach USD 98,463.35 million by 2032, growing at a CAGR of 14.45%. The market is scaling rapidly due to the demand for integrated digital and physical shopping experiences globally.
- Real-time analytics is transforming retail operations by enabling dynamic pricing, inventory optimization, and customer behavior tracking. This shift toward data-driven decision-making enhances personalization and boosts operational efficiency.
- IoT devices such as smart shelves, RFID tags, and beacons are being widely deployed across stores. These technologies allow real-time inventory monitoring, automate stock replenishment, and enable targeted promotions, making physical stores more responsive.
- AI and machine learning are increasingly embedded in retail processes to drive personalization and forecast demand. AI applications like chatbots, recommendation engines, and predictive analytics are helping improve engagement and customer retention.
- Mobile commerce and contactless technologies are accelerating the adoption of connected retail platforms. Consumers prefer mobile payments, self-checkouts, and in-app experiences, pushing retailers to optimize for mobile-first interactions.
- Complex integration of legacy systems with cloud, AI, and IoT platforms remains a significant challenge. Many retailers are burdened with outdated IT infrastructure, making transformation costly and time-consuming.
- Data privacy and cybersecurity are critical concerns in the Connected Retail Market. As customer data flows through multiple platforms, retailers must ensure regulatory compliance and invest in robust security frameworks to maintain trust.

Market Drivers:
Retail Digital Transformation Driven by Real-Time Analytics The Connected Retail Market is expanding as retailers adopt advanced analytics to improve operational efficiency and customer engagement. Real-time data analysis enables optimized shelf management, customer tracking, and dynamic pricing strategies. It equips retailers to reduce costs, minimize waste, and tailor inventory based on live customer behavior. Data analytics transforms retail from reactive to predictive operations, enhancing sales conversion and experience personalization. Retailers that effectively utilize real-time analytics gain a competitive edge by responding swiftly to market trends.
Adoption of Internet of Things (IoT) Devices Across Storefronts Retailers are increasingly deploying IoT-enabled devices such as smart shelves, RFID tags, and beacons to digitize physical stores. The Connected Retail Market benefits from these systems, which monitor stock levels, trigger automated replenishments, and push real-time promotions. IoT integration improves product visibility, reduces manual labor, and aligns physical locations with omnichannel strategies. It turns stores into intelligent data hubs that support decision-making. This connectivity enhances store efficiency and helps create a seamless, interactive customer journey.
- For example, Walmart expanded RFID technology from apparel to all home and entertainment categories by 2022, mandating RFID-enabled inventory tracking for thousands of suppliers. As a direct outcome, shelf accuracy rates exceeded 95% in test markets, while average stock audits fell from once per day to twice per week, freeing up staff for revenue-driving tasks.
Integration of AI and Machine Learning in Retail Processes Artificial intelligence plays a growing role in the Connected Retail Market by enabling hyper-personalization, demand forecasting, and automated support. AI-driven chatbots, recommendation engines, and visual recognition systems enhance consumer journeys. Retailers use machine learning algorithms to identify buying patterns and predict inventory needs, improving revenue per square foot. This intelligent infrastructure strengthens customer loyalty and optimizes business outcomes. AI also enables adaptive pricing and targeted marketing based on real-time behavioral inputs.
Contactless Technologies and Mobile Commerce Ecosystem The shift toward contactless and mobile-first experiences accelerates investment in connected retail technologies. The Connected Retail Market gains from growing consumer use of mobile apps, digital wallets, and in-store navigation tools. Mobile checkouts, self-service kiosks, and QR-based payments improve checkout efficiency and safety. Retailers integrate mobile loyalty programs, coupons, and push notifications to drive conversions and customer retention. These solutions foster convenience and speed, aligning with changing consumer expectations for frictionless experiences.
- For example, Starbucks has indeed disclosed that a significant portion of their U.S. transactions are processed through their mobile app, with contactless methods contributing to both an increase in average transaction value and faster service.
Market Trends:
Rise of Edge Computing in Store Networks Retailers are deploying edge computing infrastructure to process data locally and reduce latency. The Connected Retail Market leverages edge solutions to support real-time decision-making, reduce cloud dependency, and improve privacy. It enhances responsiveness in digital signage, POS systems, and smart sensors. Edge computing enables offline continuity, even during network disruptions, supporting uninterrupted customer experiences. The architecture also helps manage bandwidth more efficiently by filtering and analyzing data closer to the source.
- For example, Ahold Delhaize, a global grocery conglomerate, deployed Scale Computing’s SC//Platform across more than 6,700 store locations worldwide. This hyperconverged edge solution significantly simplified IT management while enabling disaster recovery capabilities in seconds.
Expansion of AR and VR-Based Customer Engagement Tools Retailers are integrating augmented and virtual reality to create immersive shopping experiences. The Connected Retail Market is transforming through AR-based product visualization and VR-powered virtual stores. Shoppers explore furniture layouts or try on apparel digitally. These tools drive higher engagement and reduce return rates. The use of AR/VR also improves product discovery and enhances brand storytelling in competitive retail environments.
- For example, IKEA Place, IKEA’s AR app, allows shoppers to visualize over 2,500 IKEA products in 3Dwithin their own homes; this tool has now processed over 50 million product previews globally and reduced digital returns by 14%.
Growth in API-Based Retail Ecosystems and Open Platforms Retailers increasingly use API-based systems to connect loyalty programs, CRM tools, and third-party apps. The Connected Retail Market benefits from open ecosystems that facilitate seamless integration and modular scalability. Retailers build custom tech stacks tailored to brand experience and customer needs. API-first platforms support omnichannel retailing and real-time updates across inventory, pricing, and promotions. These ecosystems accelerate innovation by enabling faster onboarding of new features and partners.
Focus on Energy-Efficient and Sustainable Retail Technologies Sustainability is gaining prominence, with retailers investing in energy-efficient lighting, HVAC systems, and IoT-driven energy monitoring. The Connected Retail Market supports green retailing by tracking resource usage and enabling predictive maintenance. Smart thermostats, automated lighting, and digital signage reduce operational costs and environmental impact. It positions sustainability as both a compliance and brand value opportunity. Retailers are also integrating carbon footprint tracking to align with ESG goals and consumer expectations.
Market Challenges Analysis:
Complex Integration of Legacy and Digital Retail Infrastructure The Connected Retail Market faces challenges in integrating modern digital systems with legacy IT setups. Many retailers operate outdated POS systems, ERP platforms, and disconnected CRM tools. Synchronizing these with cloud services, IoT devices, and AI platforms requires significant investment and technical expertise. Integration delays limit operational efficiency and delay ROI realization. A lack of standardized protocols across platforms further complicates seamless data exchange and system interoperability. This complexity often results in fragmented customer experiences and operational silos that hinder agility.
Data Privacy, Cybersecurity, and Consumer Trust Issues As retailers handle sensitive data across cloud, edge, and mobile platforms, cybersecurity becomes a top concern. The Connected Retail Market must navigate global data protection laws and rising cyber threats. Breaches undermine customer trust and may incur regulatory penalties. Ensuring encrypted communication, user consent, and compliance frameworks is essential for safe and scalable deployment. Growing reliance on third-party vendors and APIs also increases the attack surface, requiring comprehensive risk management strategies. Retailers must continuously audit their digital systems and invest in adaptive security protocols to safeguard data integrity.
Market Opportunities:
Digital Retail Expansion in Emerging Markets The Connected Retail Market holds immense potential in emerging economies, where urbanization and smartphone adoption are growing. Governments and private players are investing in digital infrastructure, enabling affordable access to smart retail tools. Localized mobile apps, vernacular UX, and offline-first solutions cater to new user segments. These initiatives are helping bridge the digital divide and bringing first-time consumers into formal retail networks.
Omnichannel Strategies Linking E-Commerce and Physical Retail Retailers are aligning in-store and online operations to create seamless buyer journeys. The Connected Retail Market supports features like BOPIS (Buy Online Pick-up In Store), unified inventory management, and personalized digital engagements. It drives foot traffic, improves inventory turnover, and builds stronger customer relationships. Omnichannel integration also empowers staff with real-time insights, enhancing service quality across every customer touchpoint.
Market Segmentation Analysis:
The Connected Retail Market is segmented
By component into hardware, software, and services. Hardware dominates due to the widespread deployment of IoT-enabled devices such as smart shelves, sensors, and point-of-sale systems. Software plays a critical role in integrating real-time analytics, customer engagement tools, and backend operations. Services are gaining traction, with managed services leading the segment due to growing demand for outsourced IT management. Professional services provide consulting, integration, and system optimization, while remote device management services enable efficient control of distributed store systems.
- For example, Costa Coffee features vending machines equipped with IoT sensors for cashless payments, remote temperature monitoring, and loyalty card integration, resulting in optimized restocking and overstock reduction.
By technology, the market includes ZigBee, Wi-Fi, NFC (Near Field Communication), Bluetooth Low Energy, and other technologies. Wi-Fi holds a major share, supporting high-bandwidth data exchange across in-store systems. Bluetooth Low Energy is expanding in applications such as proximity marketing and contactless payments. NFC is preferred for secure mobile transactions, particularly in self-checkout and digital wallet integrations. ZigBee offers reliable short-range communication for low-power retail devices. The technology mix enables retailers to enhance operational efficiency and elevate the customer experience. Each component and technology segment contributes to building agile, data-driven retail environments that align with evolving consumer expectations.
- For example, leading retailers, including those using Apple Pay and Google Pay, equip checkout counters with NFC-enabled POS terminals to process contactless mobile payments. This reduces checkout time, streamlines loyalty program enrollment, and boosts payment security by enabling tap-and-go transactions.

Segmentation:
By Component
- Hardware
- Software
- Services
- Managed Services
- Professional Services
- Remote Device Management Services
By Technology
- ZigBee
- Wi-Fi
- NFC (Near Field Communication)
- Bluetooth Low Energy
- Other Technologies
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Connected Retail Market size was valued at USD 8,013.60 million in 2018 to USD 12,564.68 million in 2024 and is anticipated to reach USD 36,736.85 million by 2032, at a CAGR of 14.4% during the forecast period. North America holds the largest market share, accounting for 31.8% of the global market in 2024. The region benefits from a well-developed digital infrastructure and high adoption rates of advanced retail technologies. Leading retailers in the U.S. and Canada have invested heavily in omnichannel platforms, IoT-enabled stores, and AI-driven customer engagement. It supports rapid adoption of connected solutions across logistics, inventory, and customer analytics. Government initiatives and strategic partnerships further strengthen innovation in this space. High smartphone penetration and demand for seamless customer experiences continue to propel market expansion.
Europe
The Europe Connected Retail Market size was valued at USD 5,654.04 million in 2018 to USD 8,625.67 million in 2024 and is anticipated to reach USD 23,872.70 million by 2032, at a CAGR of 13.7% during the forecast period. Europe captures 21.8% of the global market in 2024. The region demonstrates steady growth driven by strong retail modernization programs across Germany, the UK, and France. It benefits from rising investment in digital transformation and integration of smart retail technologies. Regulatory support for consumer data privacy and sustainable operations contributes to increased deployment of connected retail solutions. E-commerce expansion and changing consumer behavior have also created demand for unified shopping experiences. Retailers are prioritizing automation and real-time data integration to improve efficiency.
Asia Pacific
The Asia Pacific Connected Retail Market size was valued at USD 4,770.00 million in 2018 to USD 7,931.94 million in 2024 and is anticipated to reach USD 25,827.01 million by 2032, at a CAGR of 16.0% during the forecast period. The region commands 20.0% of the global market share in 2024 and is expected to grow the fastest. Rapid urbanization, rising disposable income, and smartphone usage fuel digital engagement in countries like China, India, and Japan. It is witnessing large-scale adoption of cloud POS, mobile commerce, and AI-driven personalization. Domestic and international retailers are scaling operations with smart logistics, real-time inventory tracking, and connected in-store technologies. The competitive landscape is pushing continuous innovation in digital retail infrastructure. Government support for smart city and retail tech initiatives is contributing to market acceleration.
Latin America
The Latin America Connected Retail Market size was valued at USD 1,386.48 million in 2018 to USD 2,179.01 million in 2024 and is anticipated to reach USD 5,934.39 million by 2032, at a CAGR of 13.4% during the forecast period. Latin America accounts for 5.5% of the global market share in 2024. The market is gaining traction with increasing internet penetration and mobile device usage in countries like Brazil, Mexico, and Chile. It is supported by the growth of e-commerce platforms and demand for digitally enabled store formats. Retailers are adopting data analytics and cloud platforms to streamline supply chains and enhance customer experience. Rising competition among regional brands is also driving digital transformation efforts. Economic reforms and investments in IT infrastructure are strengthening long-term prospects.
Middle East
The Middle East Connected Retail Market size was valued at USD 824.68 million in 2018 to USD 1,227.35 million in 2024 and is anticipated to reach USD 3,249.83 million by 2032, at a CAGR of 13.0% during the forecast period. The region represents 3.1% of the global market share in 2024. The market is expanding due to growing smart city projects and retail digitization in the UAE and Saudi Arabia. It shows increasing interest in automated checkout, connected kiosks, and AI-powered retail analytics. Luxury retail and high-end consumer brands are leading in adopting omnichannel engagement tools. Infrastructure improvements and rising digital literacy are contributing to broader deployment. Government support and private sector investments are accelerating technology integration across the retail sector.
Africa
The Africa Connected Retail Market size was valued at USD 551.20 million in 2018 to USD 1,103.26 million in 2024 and is anticipated to reach USD 2,842.56 million by 2032, at a CAGR of 12.2% during the forecast period. Africa accounts for 2.8% of the global market share in 2024. The region is in the early stages of adopting connected retail technologies but shows strong potential. It is witnessing growth in mobile commerce, fintech adoption, and cloud-based retail systems, particularly in South Africa, Nigeria, and Kenya. Retailers are exploring digital channels to reach underserved and remote consumers. Infrastructure gaps and limited digital skills remain key barriers to adoption. However, regional governments and global tech firms are launching initiatives to bridge these challenges and enable digital retail transformation.
Key Player Analysis:
- NXP Semiconductors N.V.
- Honeywell International Inc.
- Cisco Systems, Inc.
- GE Digital
- International Business Machines Corporation (IBM)
- MindTree Ltd.
- PTC Inc.
- Rockwell Automation, Inc.
- UiPath Inc.
Competitive Analysis:
The Connected Retail Market is competitive, driven by continuous innovation and digital transformation. Key players focus on end-to-end retail solutions that integrate IoT, analytics, and automation. Companies like IBM, Cisco, and Honeywell offer scalable platforms supporting omnichannel retail, data security, and predictive intelligence. Smaller firms innovate in niche technologies like AR shopping and mobile POS. Strategic alliances, acquisitions, and product launches are common, with firms expanding their offerings to cover managed services, edge analytics, and AI integrations. It continues to evolve with demand for customization and interoperability. Competitive intensity is expected to rise as digital-first retailers seek faster deployment and scalable solutions.
Recent Developments:
- In January 2025, Cisco demonstrated its latest retail technology innovations, introducing new partnerships and next-generation network solutions like Wi-Fi 7, smart cameras, and Cisco Spaces that collectively create secure, connected in-store retail experiences.
- In January 2025, IBM’s partnership with Walmart integrated GoLocal last-mile delivery services into IBM Sterling Order Management. This collaboration specifically targets retail clients, enabling robust, connected, and scalable delivery solutions for retailers.
- In December 2023, Honeywell acquired Carrier Global's Global Access Solutions business. The acquisition strengthens Honeywell’s digital access and security portfolio for building automation, which directly supports connected retail infrastructure and modernizes in-store environments.
Market Concentration & Characteristics:
The Connected Retail Market features moderate concentration, with global technology firms and regional players shaping the ecosystem. It is defined by fast-paced innovation, modular architectures, and service-led differentiation. Major players leverage integrated platforms while niche firms focus on customization and agility. The market favors vendors offering scalable, secure, and interoperable solutions. Cross-industry collaboration with logistics, telecom, and fintech is enhancing ecosystem depth. It thrives on adaptability to consumer behavior and omni-environment interactions. Strategic investments in cloud-native infrastructure and AI-powered analytics are further influencing competitive positioning.
Report Coverage:
The research report offers an in-depth analysis based on Component and Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Retailers will prioritize AI-driven personalization to enhance customer engagement and loyalty across all channels.
- Edge computing adoption will increase to minimize latency and improve real-time decision-making at the store level.
- Smart shelves and electronic shelf labels will become standard tools in convenience and department store formats.
- Seamless omnichannel strategies will merge digital and physical retail experiences for consistent customer journeys.
- Innovation in energy-efficient technologies will accelerate in response to growing demand for sustainable retail operations.
- AR and VR solutions will shape purchase decisions by offering immersive and interactive product experiences.
- Cloud-native platforms will gradually replace outdated systems among mid-sized retailers seeking agility and scalability.
- Mobile point-of-sale systems and touchless checkouts will continue gaining traction in the post-pandemic retail landscape.
- Collaborations between technology providers and retailers will expand, enabling end-to-end connected retail ecosystems.
- Cybersecurity and regulatory compliance will remain a key focus as retailers handle more sensitive customer data.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Retail Digital Transformation Driven by Real-Time Analytics
Retailers are leveraging advanced analytics to optimize operations, personalize customer experiences, and enable dynamic pricing. Real-time data analysis transforms retail from reactive to predictive, improving sales conversion and operational efficiency.
Adoption of IoT Devices Across Storefronts
The deployment of IoT-enabled devices such as smart shelves, RFID tags, and beacons allows retailers to automate inventory management, monitor stock levels in real time, and deliver targeted promotions, making physical stores more responsive and efficient.
Integration of AI and Machine Learning in Retail Processes
AI and machine learning are being embedded in retail operations to enable hyper-personalization, demand forecasting, and automated customer support, which enhances engagement, loyalty, and revenue per square foot.
Growth of Contactless Technologies and Mobile Commerce
The increasing consumer preference for mobile payments, self-checkouts, and in-app experiences is driving retailers to adopt connected retail platforms that support frictionless, mobile-first interactions and improve checkout efficiency.
Expansion of Omnichannel and API-Based Retail Ecosystems
Retailers are integrating online and offline channels through API-based systems, unified inventory management, and seamless customer engagement tools, enabling consistent experiences and operational agility across all touchpoints.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Connected Retail Market?
What factors are driving the growth of the Connected Retail Market?
What are the key segments within the Connected Retail Market?
What are some challenges faced by the Connected Retail Market?
Who are the major players in the Connected Retail Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Technology
- 1.3.1 ZigBee
- 1.3.2 Wi-Fi
- 1.3.3 NFC (Near Field Communication)
- 1.3.4 Bluetooth Low Energy
- 1.3.5 Other Technologies
- 1.4 By Service Type
- 1.4.1 Managed Services
- 1.4.2 Professional Services
- 1.4.3 Remote Device Management Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33,631.91 million → 2032: USD 98,463.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Connected Retail Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Connected Retail Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Connected Retail Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Connected Retail Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Connected Retail Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Connected Retail Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Connected Retail Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Connected Retail Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33,631.91 million → 2032: USD 98,463.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Connected Retail Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ZigBee
- 12.4.7.2 Wi-Fi
- 12.4.7.3 NFC (Near Field Communication)
- 12.4.7.4 Bluetooth Low Energy
- 12.4.7.5 Other Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Managed Services
- 12.5.7.2 Professional Services
- 12.5.7.3 Remote Device Management Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Connected Retail Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Connected Retail Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Connected Retail Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 NXP Semiconductors N.V.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Honeywell International Inc.
- 17.4 Cisco Systems, Inc.
- 17.5 GE Digital
- 17.6 International Business Machines Corporation (IBM)
- 17.7 MindTree Ltd.
- 17.8 PTC Inc.
- 17.9 Rockwell Automation, Inc.
- 17.10 UiPath Inc.
- 17.11 Microsoft Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

