
Market Overview:
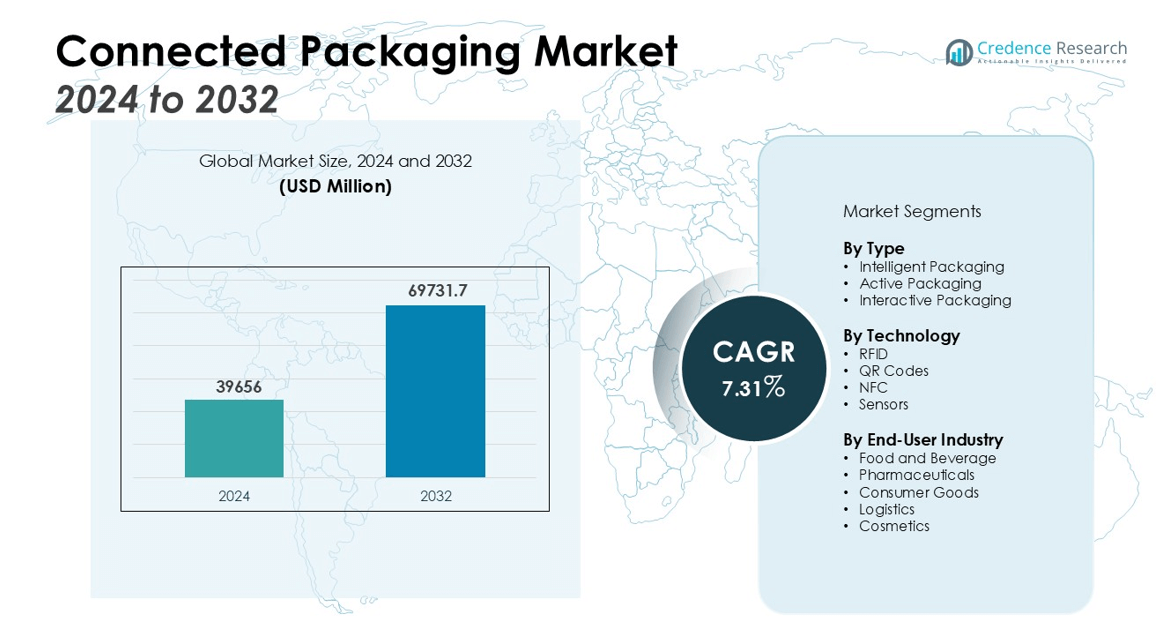
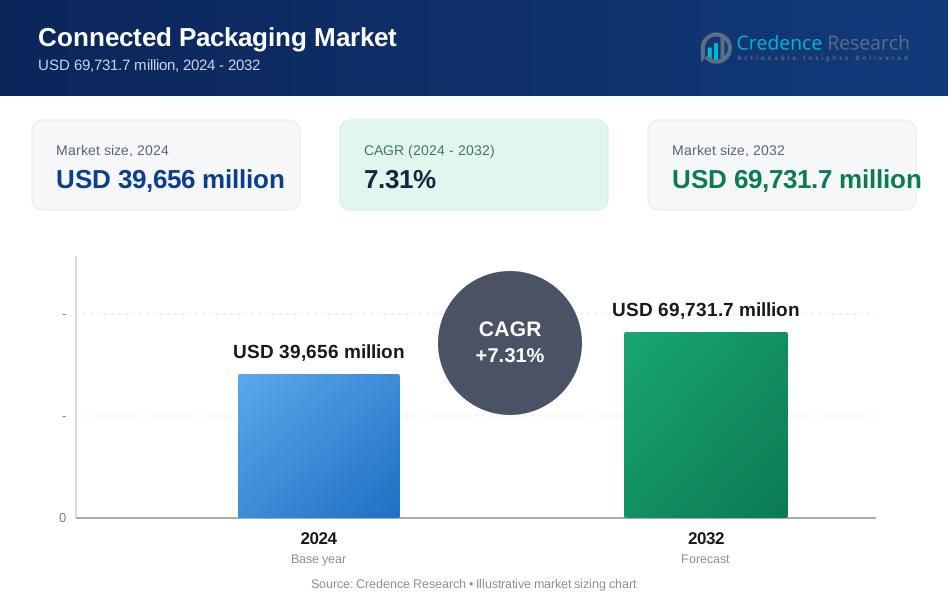
The Connected Packaging Market size was valued at USD 39656 million in 2024 and is anticipated to reach USD 69731.7 million by 2032, at a CAGR of 7.31% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Connected Packaging Market Size 2024 | USD 39656 million |
| Connected Packaging Market, CAGR | 7.31% |
| Connected Packaging Market Size 2032 | USD 69731.7 million |
Key drivers of market growth include the growing need for enhanced supply chain visibility, product authenticity, and consumer safety. The integration of RFID, QR codes, and NFC technology into packaging allows manufacturers to provide real-time data on product status, expiration dates, and origin. Additionally, the rise in demand for sustainable packaging solutions and personalized consumer experiences further fuels the market. As consumer awareness about product transparency increases, brands are increasingly adopting connected packaging to meet these expectations. These factors are encouraging significant investments in connected packaging innovations across multiple sectors, including food and beverage, pharmaceuticals, and consumer goods.
Regionally, North America holds the largest market share, owing to the rapid adoption of advanced packaging technologies and a strong presence of major players. The growing trend of sustainability and the adoption of eco-friendly solutions in the region also support market growth. However, the Asia Pacific region is expected to witness the highest growth rate during the forecast period, driven by increasing industrialization, urbanization, and demand for connected solutions in countries like China and India. This rapid growth in APAC is further fueled by expanding e-commerce, where connected packaging offers added convenience and security for online transactions.
Market Insights:
- The Connected Packaging Market is valued at USD 39656 million in 2024 and is expected to reach USD 69731.7 million by 2032, growing at a CAGR of 7.31% during the forecast period.
- Key drivers include increasing demand for supply chain transparency, product authenticity, and consumer safety through the integration of RFID, QR codes, and NFC technology into packaging.
- The rising focus on sustainability and eco-friendly solutions is pushing the demand for connected packaging, particularly in industries like food and beverage, pharmaceuticals, and consumer goods.
- Personalized consumer experiences are becoming a significant growth driver as connected packaging allows brands to engage customers with tailored content, loyalty programs, and promotions.
- High implementation costs and complex integration processes pose challenges for small and medium enterprises looking to adopt connected packaging solutions.
- Data privacy and security concerns related to the storage and protection of real-time consumer and supply chain data are major market obstacles.
- North America leads the market with a 35% share, followed by Europe at 28%, and the Asia Pacific region is witnessing rapid growth due to industrialization, urbanization, and rising demand for smart packaging solutions.
Market Drivers:
Increasing Demand for Supply Chain Transparency
The Connected Packaging Market is experiencing substantial growth due to the increasing demand for supply chain transparency. Companies across industries are seeking real-time visibility into their product’s journey, from manufacturing to delivery. By integrating smart technologies like RFID, NFC, and QR codes, businesses can track their products in real time, ensuring efficient inventory management and improved logistics. This technology also provides valuable insights into product condition during transit, minimizing the risks associated with fraud, counterfeiting, and spoilage. The adoption of connected packaging helps enhance operational efficiency and lowers operational costs by streamlining the entire supply chain process.
- For example, Toppan Printing developed NFC-based, tamper-evident packaging that embeds NFC chips directly into the package structure, resulting in four new types of commercially available NFC-enabled paper packaging designs.
Rising Consumer Expectations for Product Authentication and Safety
Consumers are becoming more conscientious about the authenticity and safety of products they purchase. The Connected Packaging Market addresses this by offering innovative solutions that help verify product authenticity, particularly in industries like pharmaceuticals and luxury goods. Through the use of unique identifiers, such as QR codes or holograms, consumers can easily verify the origin of their purchased items. This technology fosters a higher level of trust between brands and consumers. As counterfeit goods become an increasing concern globally, businesses are incorporating connected packaging to ensure that their products meet safety standards and comply with regulatory requirements.
Growing Focus on Sustainability and Eco-friendly Solutions
Sustainability is a growing concern for both businesses and consumers, driving the demand for eco-friendly packaging solutions. The Connected Packaging Market has responded by integrating sustainable practices with advanced technology. Smart packaging solutions are now capable of reducing waste by offering features like reusable and recyclable materials. Connected packaging can also assist in minimizing carbon footprints by providing more efficient product delivery options. This trend is particularly visible in industries like food and beverage, where companies are increasingly adopting sustainable packaging options to meet both consumer demand and regulatory standards.
- For instance, General Mills introduced connected packaging with a QR code and How2Recycle label on Pillsbury Frozen Pie Crust, enabling consumers to check local recycling access based on ZIP code for each package component.
Personalization of Consumer Experience
Personalized consumer experiences are becoming a significant driver of growth in the Connected Packaging Market. Through connected packaging, brands can engage customers by offering tailored content, special offers, or loyalty programs. Consumers can interact with packaging through mobile applications or smart devices to access personalized product information or promotional campaigns. This technology enhances customer engagement, creates brand loyalty, and allows companies to collect valuable data on consumer behavior. By leveraging this data, businesses can further refine their offerings and create more targeted marketing strategies.
Market Trends:
Growing Integration of IoT and Smart Sensors
The Connected Packaging Market is seeing a significant trend toward the integration of Internet of Things (IoT) technology and smart sensors into packaging solutions. These advancements allow for real-time monitoring of various factors such as temperature, humidity, and location, which are crucial for maintaining product quality, particularly in sensitive industries like pharmaceuticals and food. IoT-enabled packaging solutions provide greater control over inventory and logistics, improving supply chain efficiency. These technologies also offer predictive capabilities, enabling businesses to foresee potential issues before they occur, reducing the risk of product loss or damage. This trend is helping companies not only track their products more effectively but also enhance overall customer satisfaction by ensuring product integrity.
- For instance, a 2025 Deloitte survey found that 70 pharmaceutical companies have implemented or plan to implement IoT-enabled smart packaging to monitor product conditions throughout the supply chain, ensuring drug safety and integrity.
Increasing Adoption of Blockchain for Improved Traceability
Blockchain technology is becoming increasingly important in the Connected Packaging Market for enhancing traceability and security. By providing a secure and immutable record of transactions, blockchain ensures that data related to product origin, movement, and handling is accurate and tamper-proof. This trend is particularly critical for industries where product authenticity and safety are paramount, such as pharmaceuticals and luxury goods. Blockchain integration into packaging solutions allows consumers to verify the authenticity of their products quickly and confidently. It also helps businesses comply with regulatory requirements related to product safety and quality control. As demand for secure, transparent supply chains increases, the adoption of blockchain technology in packaging solutions is expected to rise steadily.
- For instance, the eZTracker blockchain system has been successfully used to track more than 2 million labeled pharmaceutical products for real-time verification and anti-counterfeit measures in 2022.
Market Challenges Analysis:
High Implementation Costs and Complex Integration
One of the key challenges in the Connected Packaging Market is the high implementation costs and complexity involved in integrating smart packaging technologies. Businesses, particularly small and medium enterprises, often face financial barriers in adopting RFID, IoT sensors, or blockchain systems, which can be costly to develop and deploy. Furthermore, integrating these advanced technologies into existing supply chains and production lines requires significant investments in infrastructure and employee training. This complexity can slow down adoption, especially for companies with limited resources or those operating in less technologically advanced markets.
Data Privacy and Security Concerns
Data privacy and security remain major concerns for the Connected Packaging Market as the use of smart packaging solutions grows. The increasing collection of real-time data from consumers and supply chains raises issues around how to store, manage, and protect sensitive information. Vulnerabilities in these systems can lead to potential data breaches, posing risks to both consumers and businesses. Companies must invest heavily in securing their data and ensuring compliance with regulatory standards, such as GDPR. The lack of standardized protocols across different technologies also complicates the ability to ensure uniform security measures, further hindering widespread adoption.
Market Opportunities:
Expansion in Emerging Markets and Industries
The Connected Packaging Market presents significant opportunities for growth in emerging markets, where industries are increasingly adopting advanced technologies. As supply chains in regions like Asia Pacific, Latin America, and the Middle East modernize, there is a growing demand for smart packaging solutions. Industries such as food and beverage, pharmaceuticals, and personal care are poised to benefit from enhanced product traceability and safety features. The rising middle class and increasing e-commerce activities in these regions provide further impetus for the adoption of connected packaging, offering new market avenues for technology providers. Expanding these solutions into these markets allows businesses to enhance their product offerings and strengthen brand loyalty among consumers.
Integration with Sustainability Initiatives
The growing emphasis on sustainability provides a promising opportunity for the Connected Packaging Market. With increasing consumer demand for eco-friendly products and packaging, there is a strong push for smart packaging solutions that are both efficient and sustainable. Companies can integrate connected packaging with recyclable and biodegradable materials, thus addressing the environmental concerns of consumers. This trend is particularly relevant in industries like food and beverage, where reducing packaging waste and improving recycling rates are top priorities. As sustainability becomes a key driver for consumer choices, connected packaging solutions that align with these goals can give businesses a competitive edge.
Market Segmentation Analysis:
By Type
The Connected Packaging Market is segmented into intelligent packaging, active packaging, and interactive packaging. Intelligent packaging dominates the market due to its ability to provide real-time data on product status, ensuring product integrity and traceability. Active packaging, focused on controlling the internal environment of the packaging, is gaining popularity, particularly in the food and pharmaceutical industries for extending product shelf life. Interactive packaging, while still emerging, offers consumer engagement through features like QR codes and NFC, allowing customers to access product information.
- For instance, ITENE developed antimicrobial cardboard containers for red and sliced fruit, resulting in a reduction of spoilage microorganisms in laboratory tests of 200 packaging units during a six-month project, supporting safer, longer-lasting produce.
By Technology
The market incorporates technologies such as RFID, QR codes, NFC, and sensors. RFID technology leads due to its efficiency in tracking products across supply chains, providing transparency and reducing losses. QR codes and NFC technologies enhance consumer interaction by offering easy access to product details, promotional content, and authentication. The rising demand for real-time product monitoring and enhanced security is driving the widespread adoption of these technologies in connected packaging solutions.
- For instance, Levi’s Brazil reported an increase in inventory accuracy from 67 to 100 after implementing RFID technology over an 18-month period, significantly reducing stock discrepancies and improving supply chain visibility.
By End-User Industry
The Connected Packaging Market serves a wide range of industries, including food and beverage, pharmaceuticals, consumer goods, and logistics. The food and beverage sector holds the largest share, driven by the need for freshness monitoring and traceability. The pharmaceutical industry follows closely, driven by stringent regulatory requirements for tamper-proof packaging and product safety. The growing trend of e-commerce also supports the adoption of connected packaging across various industries, enhancing consumer experience and supply chain management.
Segmentations:
By Type
- Intelligent Packaging
- Active Packaging
- Interactive Packaging
By Technology
- RFID
- QR Codes
- NFC
- Sensors
By End-User Industry
- Food and Beverage
- Pharmaceuticals
- Consumer Goods
- Logistics
- Cosmetics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America: Market Leadership and Technological Advancements
North America accounts for the largest market share in the Connected Packaging Market, capturing 35% of the global market. The region’s rapid adoption of advanced technologies like IoT, RFID, and blockchain has driven the demand for smart packaging solutions. Major players in the packaging and technology sectors, such as Intel, IBM, and Zebra Technologies, are actively investing in innovations to enhance supply chain visibility and product traceability. The food and beverage, pharmaceutical, and consumer goods industries are the primary sectors driving demand for connected packaging solutions in the region. With strong regulatory support for product safety and transparency, North America is expected to maintain its leadership throughout the forecast period.
Europe: Steady Growth with a Focus on Sustainability
Europe holds a 28% market share in the Connected Packaging Market, driven by stringent regulations related to product safety and sustainability. The European Union’s focus on reducing plastic waste and promoting circular economies has created favorable conditions for the adoption of sustainable smart packaging solutions. Countries like Germany, France, and the UK are leading the way in implementing advanced packaging technologies. The pharmaceutical and food industries in Europe are increasingly turning to connected packaging for better traceability and consumer engagement. With a growing preference for eco-friendly and efficient packaging, the region is expected to witness steady growth in the connected packaging sector.
Asia Pacific: High Growth Potential with Industrialization
Asia Pacific represents a rapidly growing segment, holding 25% of the global market share in the Connected Packaging Market. Driven by industrialization, urbanization, and rising consumer demand, countries like China, India, and Japan are increasingly adopting advanced packaging technologies. The expanding e-commerce sector and rising middle class in these nations create a robust market for smart packaging solutions. Industries such as food and beverage, healthcare, and retail are adopting connected packaging to enhance supply chain transparency and meet growing consumer expectations for product authenticity. The region’s demand for connected packaging solutions is further fueled by increasing regulatory requirements and a strong focus on sustainability.
Key Player Analysis:
- 3M
- Stora Enso
- Amcor plc
- Klöckner Pentaplast
- Thermal Instruments
- International Paper
- Avery Dennison Corporation
- Thin Film Electronics ASA
- Huhtamaki Oyj
- R. Donnelley & Sons Company
- Tetra Pak
- Westrock Company
- Constantia Flexibles
- American
Competitive Analysis:
The Connected Packaging Market is highly competitive, with several key players leading the innovation in smart packaging solutions. Companies like Zebra Technologies, Smartrac, and Honeywell International dominate the market, offering advanced RFID, NFC, and IoT-based packaging technologies. These companies focus on providing end-to-end solutions that enhance supply chain transparency, product authentication, and consumer engagement. Smaller players and startups are also emerging with specialized technologies, targeting specific industries such as pharmaceuticals, food, and luxury goods. The market is characterized by a high level of investment in research and development to introduce innovative, sustainable, and cost-effective solutions. Players are increasingly forming strategic partnerships and collaborations to expand their product offerings and strengthen their market presence. The growing demand for eco-friendly solutions and personalized consumer experiences has intensified competition, pushing companies to continuously innovate to meet evolving consumer and regulatory demands.
Recent Developments:
- In July 2025, Amcor launched the Hector Child Resistant Closure (CRC), a lightweight, recyclable closure for bleach and toilet cleaner bottles, focused on sustainability and design.
- In March 2025, 3M pledged to launch 1,000 new products over three years, backed by $3.5 billion in research and development investments to accelerate innovation using AI and digital materials hubs.
- In April 2025, Stora Enso launched Performa Nova, a next-generation folding boxboard for consumer packaging, produced on a new fiber-based consumerboard line in Finland.
Market Concentration & Characteristics:
The Connected Packaging Market exhibits moderate concentration, with a few large players holding significant market share. Key companies such as Zebra Technologies, Smartrac, and Honeywell International lead the market by offering comprehensive solutions integrating RFID, NFC, and IoT technologies. These companies invest heavily in research and development to drive innovation and meet the growing demand for secure, sustainable, and transparent packaging solutions. Smaller players, often focused on niche applications or specific industries like food, pharmaceuticals, and luxury goods, are gaining ground by providing tailored solutions. The market is characterized by rapid technological advancements, with a strong focus on sustainability and eco-friendly packaging. Competitive strategies often include strategic partnerships, acquisitions, and collaborations to enhance technological capabilities and expand market reach. The demand for personalized consumer experiences and real-time product tracking is pushing companies to continually innovate.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Connected Packaging Market is projected to experience steady growth driven by technological innovation, shifting consumer behavior, and expanding global demand.
- Key trends shaping the market include digital transformation, sustainability initiatives, and increased automation across value chains.
- Market players are focusing on R&D, strategic partnerships, and regional expansions to gain a competitive advantage.
- Regulatory developments and evolving trade policies are expected to influence pricing strategies and supply chain dynamics.
- The rise of emerging markets and adoption of data-driven decision-making will further fuel growth.
- The market is expected to witness diversification, increased product customization, and greater integration of AI and IoT technologies.
- North America is expected to maintain its leadership in the market, owing to rapid adoption of advanced packaging technologies and a strong presence of major players.
- The Asia Pacific region is expected to witness the highest growth rate during the forecast period, driven by increasing industrialization, urbanization, and demand for connected solutions.
- The growing trend of sustainability and the adoption of eco-friendly solutions in the region also support market growth.
- The Connected Packaging Market is expected to witness robust growth in the coming years, driven by the increasing adoption of IoT, rising consumer expectations, and the need for supply chain optimization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Supply Chain Transparency
Businesses are integrating RFID, NFC, and QR code technologies into packaging to enable real-time tracking and monitoring of products throughout the supply chain, reducing losses from counterfeiting and spoilage and improving operational efficiency.
Rising Consumer Expectations for Product Authentication and Safety
Consumers are seeking assurance of product authenticity and safety, especially in pharmaceuticals and luxury goods, prompting brands to adopt connected packaging with unique identifiers and tamper-evident features to build trust and comply with regulations.
Growing Focus on Sustainability and Eco-friendly Solutions
The market is driven by the need for sustainable packaging, with companies integrating connected features into recyclable and reusable materials to meet regulatory requirements and consumer demand for environmentally responsible products.
Personalization of Consumer Experience
Connected packaging enables brands to deliver tailored content, loyalty programs, and interactive experiences via mobile devices, enhancing customer engagement and allowing companies to collect valuable behavioral data for targeted marketing.
Expansion in Emerging Markets and E-commerce
Rapid industrialization, urbanization, and the growth of e-commerce in regions like Asia Pacific are accelerating the adoption of connected packaging, as these solutions offer enhanced convenience, security, and traceability for online transactions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Connected Packaging Market?
What factors are driving the growth of the Connected Packaging Market?
What are some challenges faced by the Connected Packaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Intelligent Packaging
- 1.2.2 Active Packaging
- 1.2.3 Interactive Packaging
- 1.3 By Technology
- 1.3.1 RFID
- 1.3.2 QR Codes
- 1.3.3 NFC
- 1.3.4 Sensors
- 1.4 By End-User Industry
- 1.4.1 Food and Beverage
- 1.4.2 Pharmaceuticals
- 1.4.3 Consumer Goods
- 1.4.4 Logistics
- 1.4.5 Cosmetics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 39,656 million → 2032: USD 69,731.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Connected Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Connected Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Connected Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Connected Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Connected Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Connected Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Connected Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Connected Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 39,656 million → 2032: USD 69,731.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Connected Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Intelligent Packaging
- 12.3.7.2 Active Packaging
- 12.3.7.3 Interactive Packaging
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 RFID
- 12.4.7.2 QR Codes
- 12.4.7.3 NFC
- 12.4.7.4 Sensors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage
- 12.5.7.2 Pharmaceuticals
- 12.5.7.3 Consumer Goods
- 12.5.7.4 Logistics
- 12.5.7.5 Cosmetics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Connected Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Connected Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Connected Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Connected Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stora Enso
- 18.4 Amcor plc
- 18.5 Avery Dennison Corporation
- 18.6 Huhtamaki Oyj
- 18.7 Tetra Pak
- 18.8 Westrock Company
- 18.9 Zebra Technologies
- 18.10 Honeywell International
- 18.11 Klöckner Pentaplast
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

