
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
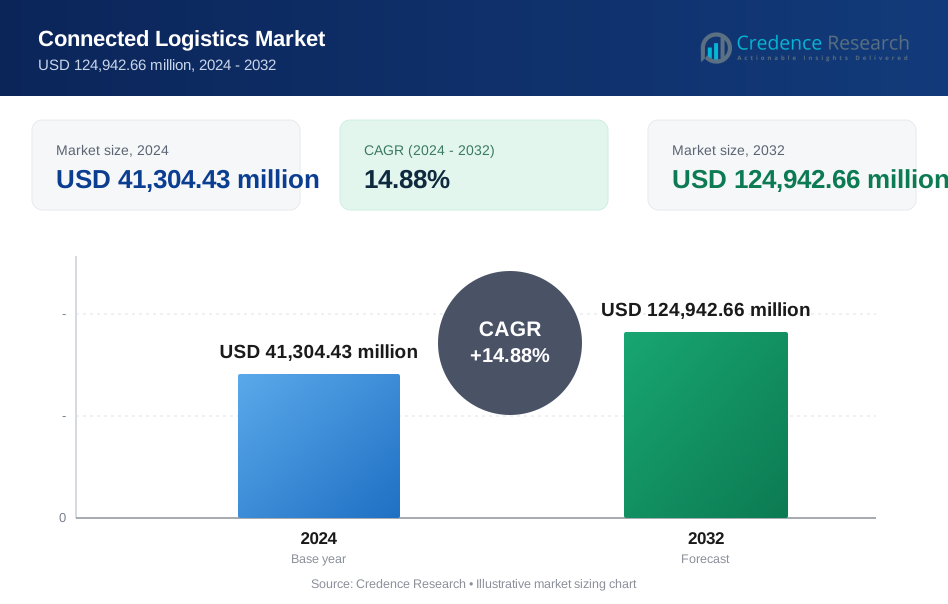
| Connected Logistics Market Size 2024 | USD 41,304.43 million |
| Connected Logistics Market, CAGR | 14.88% |
| Connected Logistics Market Size 2032 | USD 1,24,942.66 million |
Market Overview
The Global Connected Logistics Market is projected to grow from USD 41,304.43 million in 2024 to an estimated USD 1,24,942.66 million by 2032, with a compound annual growth rate (CAGR) of 14.88% from 2025 to 2032.
Key drivers propelling the growth of the connected logistics market include the rising demand for faster delivery services, improved supply chain visibility, and the need to reduce operational costs. Growing e-commerce activities and the increasing penetration of smart devices are significantly boosting market growth. Additionally, the integration of autonomous vehicles and drone-based delivery systems is emerging as a prominent trend, enhancing last-mile delivery efficiency. Companies are increasingly focusing on advanced predictive analytics and blockchain solutions to ensure supply chain transparency and security.
Geographically, North America holds a significant share of the connected logistics market due to strong technological infrastructure and high adoption of smart logistics solutions. Asia-Pacific is anticipated to witness the fastest growth, driven by rapid industrialization, expanding e-commerce sectors, and increasing investments in smart transportation systems across countries like China and India. Major players operating in the global market include Cisco Systems, Inc., IBM Corporation, AT&T Inc., SAP SE, Intel Corporation, Oracle Corporation, and Eurotech S.p.A., among others.
Market Insights
- The Global Connected Logistics Market is expanding rapidly, projected to reach USD 124,942.66 million by 2032 with a CAGR of 14.88%.
- Advanced technologies like IoT, AI, and cloud platforms drive growth by enabling real-time tracking and improved supply chain efficiency.
- Rising e-commerce activities and demand for faster, transparent deliveries significantly boost market adoption worldwide.
- High implementation costs and complex system integration remain major restraints for small and medium enterprises.
- North America holds a dominant market share due to strong infrastructure and early technology adoption.
- Asia-Pacific shows the fastest growth potential, fueled by industrialization and expanding smart transportation investments.
- Autonomous vehicles and drone delivery integration represent emerging trends that will further transform connected logistics.
Market Drivers
Increasing Demand for Real-Time Supply Chain Visibility Accelerates Market Growth
The Global Connected Logistics Market is experiencing strong growth due to rising demand for real-time supply chain visibility. Businesses across industries seek to track shipments and assets with greater precision to reduce losses and improve delivery accuracy. Real-time data helps companies respond quickly to disruptions and changing customer requirements. It enables proactive decision-making that enhances overall supply chain efficiency. Companies now prioritize end-to-end tracking to build customer trust and meet service level expectations. The demand for seamless logistics management is pushing companies to invest in advanced tracking solutions and smart sensors.
- For instance, LM Ericsson reported that IoT connections in logistics are projected to increase from 100 million in 2020 to 292 million by 2030, reflecting rapid adoption of connected devices and cloud-based logistics platforms worldwide
Rising E-Commerce Activities and Consumer Expectations Drive Technology Adoption
The expansion of the e-commerce sector significantly supports the growth of the Global Connected Logistics Market. Rapid online shopping adoption fuels the need for faster, more reliable deliveries and transparent order tracking. Consumers expect quick fulfillment and real-time shipment updates, pressuring logistics providers to upgrade their systems. Retailers are deploying connected logistics solutions to ensure timely deliveries and to handle increasing order volumes efficiently. Businesses that integrate these technologies gain a competitive edge by offering superior customer experiences. Growing consumer demand for flexible delivery options further encourages the adoption of connected logistics platforms.
- For instance, over 60 out of every 100 logistics and retail companies are actively investing in autonomous delivery technology, according to recent industry surveys, highlighting widespread adoption and pilot deployments of drones and self-driving vehicles in logistics operations
Cost Optimization and Process Efficiency Encourage Market Expansion
The Global Connected Logistics Market benefits from the growing need to optimize logistics costs and streamline operations. Companies aim to reduce fuel consumption, minimize idle times, and prevent shipment delays by leveraging connected solutions. It helps businesses monitor fleet performance, route efficiency, and warehouse operations in real time. These improvements significantly lower operational expenses and support sustainable logistics practices. The focus on process automation and predictive maintenance also strengthens the market. Businesses see connected logistics as a reliable strategy to achieve both cost savings and efficiency gains.
Technological Advancements and Integration of IoT Shape Market Dynamics
Technological innovations such as IoT, Artificial Intelligence, and advanced telematics play a crucial role in shaping the Global Connected Logistics Market. The integration of IoT devices improves asset tracking, environmental monitoring, and fleet management. Companies use AI-driven analytics to predict supply chain risks and optimize resource allocation. The combination of IoT and cloud-based platforms creates a robust ecosystem that enhances supply chain transparency. It supports intelligent decision-making and improves response times across logistics networks. Continuous investment in smart technologies strengthens the position of connected logistics in modern supply chains.
Market Trends
Rising Integration of IoT and Cloud Platforms Enhances Connected Logistics Capabilities
The Global Connected Logistics Market is witnessing a significant trend toward the integration of IoT and cloud platforms. Companies are using IoT devices to track assets, monitor cargo conditions, and ensure timely deliveries. Cloud-based systems enable seamless data sharing across supply chain stakeholders, improving coordination and decision-making speed. It supports scalable solutions that adapt to changing business needs and increasing shipment volumes. The combination of real-time tracking and cloud storage enhances supply chain visibility and responsiveness. Businesses are actively shifting to these connected ecosystems to gain operational control and reduce risks.
- For instance, Hapag-Lloyd equipped over 1,500,000 shipping containers-covering 90% of its global fleet-with smart tracking devices integrated into an AI-powered asset visibility platform, enabling real-time location data and predictive inland ETAs for customers across multiple transportation networks
Growing Adoption of Autonomous and Drone Delivery Solutions Gains Momentum
The Global Connected Logistics Market is evolving with the increasing focus on autonomous delivery vehicles and drone-based solutions. Logistics providers are investing in autonomous trucks and drones to improve last-mile delivery efficiency and reduce human intervention. It supports faster, more reliable deliveries in urban and remote areas. Companies are deploying these technologies to address driver shortages and rising labor costs. The push for contactless delivery further strengthens the interest in autonomous logistics systems. Several leading players are testing pilot projects to integrate drones and driverless vehicles into mainstream logistics operations.
- For instance, in 2024, the U.S. market saw approximately 100,890 autonomous trucks and self-driving vehicles in operation, while global drone delivery pilot programs resulted in over 350 companies deploying thousands of drones for logistics and last-mile delivery projects
Expansion of Predictive Analytics and Artificial Intelligence Drives Smart Decision-Making
The use of predictive analytics and Artificial Intelligence (AI) is transforming the Global Connected Logistics Market. Companies are using AI tools to forecast demand, detect supply chain risks, and optimize delivery routes. It helps businesses make smarter, data-driven decisions that enhance logistics performance. Predictive models improve inventory management and prevent delays by identifying potential disruptions in advance. Companies are adopting these solutions to increase efficiency and reduce wastage across supply chain networks. AI-powered logistics platforms support faster responses to changing market conditions and customer expectations.
Increasing Focus on Blockchain Integration for Supply Chain Transparency
Blockchain technology is becoming a key trend in the Global Connected Logistics Market to improve supply chain transparency and security. Companies are adopting blockchain solutions to enable tamper-proof data sharing and build trust among supply chain partners. It provides a decentralized framework that enhances traceability from origin to destination. Businesses use blockchain to verify shipment authenticity and track product movements in real time. The demand for secure and transparent logistics processes is pushing companies to explore blockchain-based applications. This trend supports more reliable, accountable, and efficient supply chain management.
Market Challenges
High Implementation Costs and Complex System Integration Limit Market Accessibility
The Global Connected Logistics Market faces significant challenges due to high implementation costs and complex system integration. Many small and medium-sized businesses struggle to adopt connected logistics solutions because of limited budgets and resource constraints. It requires substantial investment in IoT infrastructure, cloud platforms, and advanced analytics tools. Integrating new technologies with existing legacy systems creates operational difficulties and increases transition costs. Companies often face delays and technical issues when synchronizing different platforms and devices. These financial and technical barriers slow the adoption rate across less mature markets.
- For instance, according to a 2024 survey by the Council of Supply Chain Management Professionals (CSCMP), the average upfront investment required for a mid-sized logistics company to implement a connected logistics solution exceeds $250,000, while integration projects typically involve coordinating more than 10 different software and hardware platforms, highlighting the scale of both financial and technical challenges.
Cybersecurity Threats and Data Privacy Concerns Impact Market Growth
Cybersecurity threats and data privacy concerns present major obstacles for the Global Connected Logistics Market. Connected logistics systems generate large volumes of sensitive data that attract cybercriminals. It remains vulnerable to data breaches, system hacking, and unauthorized access if security measures are inadequate. Companies must invest heavily in advanced security protocols to protect critical logistics information. The fear of data misuse discourages some businesses from fully adopting connected solutions. Regulatory compliance with strict data protection laws further complicates system deployment and limits market expansion.
Market Opportunities
Growing Demand for Smart Transportation Systems Creates New Opportunities
The Global Connected Logistics Market holds strong opportunities due to the rising demand for smart transportation systems. Governments and private sectors are investing in intelligent transport infrastructure to support seamless logistics operations. It benefits from the increasing focus on traffic management, route optimization, and real-time vehicle tracking. Smart transportation initiatives help improve delivery speed, reduce congestion, and enhance fleet efficiency. Companies that offer integrated solutions aligned with smart city projects can capture significant market share. The demand for sustainable and technology-driven logistics supports future growth in this segment.
Expansion into Emerging Markets Strengthens Growth Potential
Emerging economies present valuable opportunities for the Global Connected Logistics Market due to growing industrialization and expanding e-commerce sectors. Countries in Asia-Pacific, Latin America, and the Middle East are increasing their investment in logistics infrastructure and smart technologies. It can capitalize on the rising need for advanced supply chain management in these fast-developing regions. Local businesses seek reliable logistics partners who can offer transparent and efficient delivery services. The increasing penetration of mobile and internet services supports the adoption of connected logistics solutions. Companies that enter these markets early can build strong networks and long-term growth advantages.
Market Segmentation Analysis
By Component
The Global Connected Logistics Market is segmented by component into hardware, software, and services. The hardware segment holds a significant share, driven by the use of RFID tags, sensors, communication devices, and tracking systems that enable real-time supply chain visibility. Companies rely on these hardware solutions to monitor assets, improve shipment tracking, and support efficient logistics operations. The software segment includes warehouse management, fleet management, freight transportation management, asset tracking, and data analytics, which help optimize logistics processes and improve decision-making. It enables businesses to streamline operations and manage complex supply chain networks effectively. The services segment, covering consulting, integration and deployment, support and maintenance, and managed services, plays a key role in assisting companies to implement and sustain connected logistics solutions.
- For instance, Zebra Technologies reported shipping more than 500 million RFID tags and sensors for connected logistics applications globally in 2024, underlining the scale of hardware deployment in the market.
By Transportation Mode
The Global Connected Logistics Market is categorized by transportation mode into roadways, railways, airways, and waterways. Roadways dominate the segment due to the high demand for road transport in domestic and last-mile delivery operations. It supports large-scale road logistics by offering real-time tracking and route optimization solutions. Railways contribute to efficient long-distance freight movement, especially for bulk goods. The airways segment focuses on fast, high-value shipments that require precise tracking and time-sensitive delivery. Waterways support the transportation of heavy cargo across international shipping routes, helping reduce costs for large volumes.
- For instance, over 13 billion tons of freight were transported by roadways in the United States alone in 2024, demonstrating the dominance of road transport in connected logistics.
By Vertical
The Global Connected Logistics Market is divided by vertical into retail and e-commerce, automotive, aerospace and defense, healthcare, energy, electronics and semiconductors, and others. The retail and e-commerce segment holds a substantial share due to rising consumer demand for quick deliveries and real-time shipment updates. It drives adoption of connected logistics to meet customer expectations and manage high order volumes efficiently. The automotive, aerospace, and healthcare sectors rely on connected logistics to ensure timely deliveries and secure transport of critical components and products. The energy and electronics industries also benefit from connected systems that improve tracking and safety across complex supply chains.
Segments
Based on Component
- Hardware
- RFID Tags
- Sensors
- Communication Devices
- Tracking Devices
- Others
- Software
- Warehouse Management
- Fleet Management
- Freight Transportation Management
- Asset Tracking and management
- Data Management and Analytics
- Others
- Services
- Consulting
- Integration and Deployment
- Support & Maintenance
- Managed Service
Based on Transportation Mode
- Roadways
- Railways
- Airways
- Waterways
Based on Vertical
- Retail & E-commerce
- Automotive
- Aerospace & Defense
- Healthcare
- Energy
- Electronics & Semiconductors
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Connected Logistics Market
The North America Connected Logistics Market holds the largest regional share, accounting for 36.12% of the global market in 2024 with a market size of USD 14,920.19 million. It is projected to reach USD 45,361.06 million by 2032, growing at a CAGR of 15.0% from 2025 to 2032. The region benefits from advanced technological infrastructure, high adoption of IoT, and strong demand for real-time logistics tracking solutions. It continues to attract significant investments from major logistics providers and technology companies aiming to optimize transportation networks. The presence of leading players and a mature e-commerce sector further supports rapid market expansion. North America remains a key driver of innovation and development in the connected logistics space.
Europe Connected Logistics Market
The Europe Connected Logistics Market represents 22.48% of the global market share in 2024, with a market value of USD 9,284.11 million. It is expected to reach USD 26,084.61 million by 2032, registering a CAGR of 13.8% during the forecast period. The region benefits from strong regulatory support for supply chain transparency and increasing investments in smart transportation systems. It shows steady growth due to the expansion of cross-border trade and rising demand for efficient, technology-driven logistics services. European countries focus on integrating green logistics and sustainable transportation to reduce carbon emissions. The demand for connected logistics solutions continues to grow across industries such as automotive, retail, and healthcare.
Asia Pacific Connected Logistics Market
The Asia Pacific Connected Logistics Market holds 29.77% of the global market share in 2024, valued at USD 12,302.35 million. It is projected to grow at the fastest CAGR of 16.0%, reaching USD 40,221.39 million by 2032. The rapid expansion of e-commerce, increasing industrialization, and growing investments in smart logistics infrastructure drive market growth in this region. Countries like China, India, and Japan lead the adoption of connected logistics to meet the rising demand for fast and efficient supply chain solutions. It continues to benefit from improving digital connectivity and supportive government policies. Asia Pacific remains a highly attractive market for both domestic and international logistics providers.
Latin America Connected Logistics Market
The Latin America Connected Logistics Market accounts for 6.45% of the global market share in 2024, with a market size of USD 2,659.59 million. It is expected to reach USD 7,542.79 million by 2032, growing at a CAGR of 14.0%. The region shows steady growth driven by the expansion of the retail sector and increasing demand for advanced logistics solutions. It faces challenges such as infrastructure gaps, but the adoption of connected logistics is improving due to growing investments in smart transportation and e-commerce distribution. Brazil and Mexico lead the regional market with strong logistics modernization efforts. Latin America continues to present untapped potential for connected logistics providers.
Middle East Connected Logistics Market
The Middle East Connected Logistics Market holds 3.47% of the global market share in 2024, valued at USD 1,428.86 million. It is projected to reach USD 3,947.38 million by 2032, registering a CAGR of 13.6%. The market benefits from strategic investments in logistics hubs and smart infrastructure projects, particularly in the United Arab Emirates and Saudi Arabia. It continues to focus on improving supply chain efficiency to support growing trade volumes across the region. The Middle East plays a critical role in global logistics networks due to its geographic location and established ports. Companies are adopting connected logistics solutions to enhance fleet management and real-time cargo tracking.
Africa Connected Logistics Market
The Africa Connected Logistics Market represents 1.72% of the global market share in 2024, with a market value of USD 709.32 million. It is expected to reach USD 1,785.44 million by 2032, growing at a CAGR of 12.3%. The market shows gradual development, supported by efforts to improve transportation infrastructure and logistics capabilities. It faces challenges such as limited digital adoption and underdeveloped supply chain networks. However, increasing investments in mobile connectivity and e-commerce logistics are opening new growth avenues. Countries like South Africa and Nigeria are advancing logistics operations through technology-driven solutions. Africa offers long-term potential for connected logistics providers aiming to expand in emerging markets.
Key players
- Intel Corporation
- Infosys Limited
- Cisco System Inc.
- HCL Technology Limited
- IBM Corporation
- SAP SE
- ORBCOMM
- Freightgate Inc.
- Honeywell International Inc.
- NEC Corporatio
Competitive Analysis
The Global Connected Logistics Market is highly competitive, with major players focusing on technological innovation and service expansion to strengthen their market positions. Companies such as Intel Corporation, Cisco System Inc., and IBM Corporation lead the market with strong portfolios in IoT, cloud platforms, and advanced analytics. It is driven by continuous investment in smart logistics solutions that improve efficiency and supply chain visibility. Key players also focus on strategic partnerships and regional expansions to capture emerging markets. Honeywell International Inc., SAP SE, and ORBCOMM actively develop integrated logistics platforms that support real-time tracking and predictive analytics. Infosys Limited, HCL Technology Limited, Freightgate Inc., and NEC Corporation contribute to the market with advanced software and consulting services. The competition centers on offering scalable, secure, and cost-effective logistics solutions that meet evolving customer demands.
Recent Developments
- Between 2023 and 2025, Cisco Systems has indeed expanded its focus on connected logistics infrastructure within its transportation portfolio encompassing smart roadways, rail, and airports. This expansion involves enhancing smart infrastructure and developing solutions for efficient and profitable operations in various transportation sectors.
- In April 2025, ORBCOMM launched the SKYWAVE Connect partner program to support IoT solution providers and system integrators. This program provides early access to satellite-connected logistics modules and other resources to help partners accelerate their IoT solution development and market expansion
Market Concentration and Characteristics
The Global Connected Logistics Market shows moderate to high market concentration with a few major players holding significant shares. It features a mix of established technology leaders and specialized logistics solution providers. The market is characterized by rapid technological advancements, strong demand for real-time visibility, and growing adoption of IoT and cloud-based systems. Companies compete on innovation, system integration capabilities, and service flexibility to meet diverse customer needs. It requires continuous investment in cybersecurity, data management, and system scalability to maintain competitiveness. The market also shows a high degree of collaboration between technology providers, logistics companies, and transportation networks to deliver fully connected supply chain solutions.
Report Coverage
The research report offers an in-depth analysis based on Component, Transportation Mode, Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Connected Logistics Market will continue to grow rapidly, driven by increased adoption of IoT and AI technologies across supply chains.
- Real-time tracking and end-to-end visibility will become standard requirements, improving operational efficiency and customer satisfaction globally.
- Integration of autonomous vehicles and drone delivery will reshape last-mile logistics, enhancing speed and reducing costs in urban and remote areas.
- Expansion of 5G networks will enable faster, more reliable communication among connected logistics devices, supporting advanced data analytics.
- Predictive analytics and AI-powered decision-making tools will enhance demand forecasting and risk management, reducing delays and disruptions.
- Blockchain technology will gain prominence, providing secure and transparent transaction records to strengthen supply chain trust and compliance.
- Cloud-based logistics platforms will see wider adoption, allowing scalable, flexible, and collaborative supply chain management across regions.
- Sustainability and green logistics will shape market trends, encouraging adoption of energy-efficient and carbon-neutral connected logistics solutions.
- Emerging markets in Asia-Pacific, Latin America, and Africa will present significant growth opportunities due to rising e-commerce and infrastructure investments.
- Increasing cybersecurity investments will protect connected logistics networks from data breaches and cyber threats, safeguarding sensitive supply chain information.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Connected Logistics Market in 2023, and what is the forecast through 2032?
Which factors primarily propel demand in the connected logistics market?
How is the integration of autonomous vehicles and drones impacting connected logistics?
Which regions dominate the connected logistics market, and where is the fastest growth expected?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Connected Logistics Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Connected Logistics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 41,304.43 million → 2032: USD 124,942.66 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Connected Logistics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Connected Logistics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Connected Logistics Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Connected Logistics Market Drivers
- 3.3 Connected Logistics Market Restraints & Challenges
- 3.4 Connected Logistics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Connected Logistics Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Connected Logistics Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Connected Logistics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Connected Logistics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Connected Logistics Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Connected Logistics. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Connected Logistics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Connected Logistics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Connected Logistics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Connected Logistics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Connected Logistics
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Connected Logistics Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Connected Logistics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Connected Logistics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Connected Logistics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Connected Logistics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Connected Logistics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Connected Logistics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Connected Logistics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
