
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Contract Lifecycle Management Software Market Size 2024 | USD 2,525 Million |
| Contract Lifecycle Management Software Market, CAGR | 12.4% |
| Automated Storage and Retrieval System (ASRS) Market Size 2032 | USD 6,432.68 Million |
Market Overview
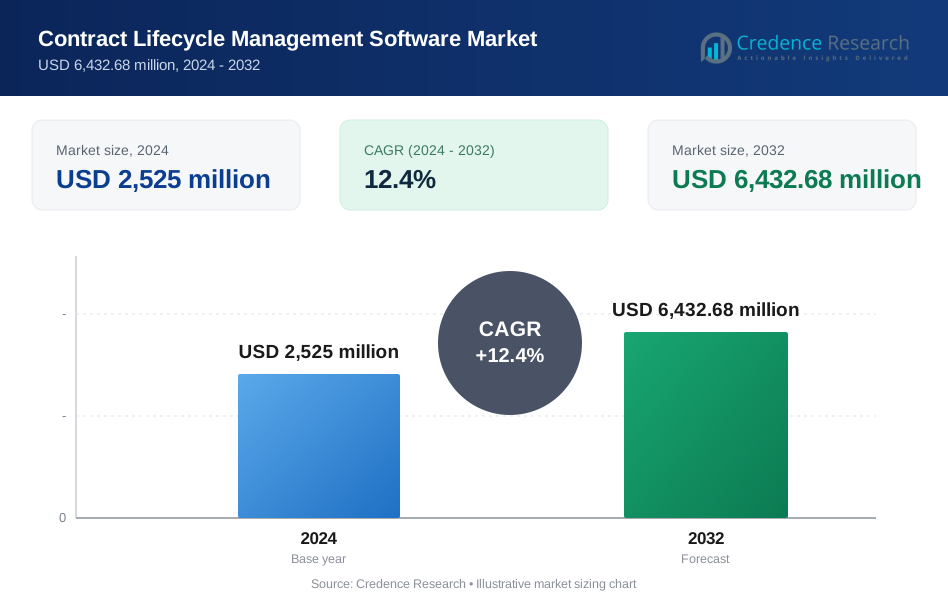
The Contract Lifecycle Management Software Market is projected to grow from USD 2,525 million in 2024 to USD 6,432.68 million by 2032, reflecting a compound annual growth rate (CAGR) of 12.4%.
The Contract Lifecycle Management (CLM) Software Market is driven by the increasing need for businesses to streamline contract processes, improve compliance, and reduce risks. As organizations handle growing volumes of contracts, CLM solutions provide automation, real-time tracking, and data-driven insights, enhancing efficiency and decision-making. The shift toward digital transformation and the integration of advanced technologies such as AI and machine learning further fuels market growth, enabling smarter contract analysis and management. Additionally, the rise in regulatory requirements and the need for secure, transparent contract workflows are key trends shaping the demand for CLM software.
The Contract Lifecycle Management (CLM) Software market is dominated by North America, accounting for approximately 40% of the global market share due to the early adoption of advanced technologies and the presence of major industry players such as Icertis, Coupa Software Inc., and SAP SE. Europe follows closely, driven by stringent regulatory requirements and increasing demand for efficient contract management. Asia Pacific is emerging rapidly, spurred by digital transformation and the expansion of businesses in countries like India and China. Key players, including Agiloft Inc. and Zycus Inc., are driving innovation, focusing on automation, compliance, and risk management in contract processes.
Market Drivers
Increased Regulatory Compliance The growing complexity of global regulations demands that businesses maintain strict adherence to compliance standards. Contract Lifecycle Management (CLM) software helps organizations manage these obligations by tracking compliance across multiple contracts, minimizing the risk of penalties and fines. For instance, Johnson & Johnson implemented a CLM solution to centralize their contract management process, resulting in increased speed and accuracy in their contract execution process. With data privacy regulations like GDPR and CCPA becoming more stringent, CLM software ensures that contracts meet these standards, protecting sensitive information and reducing the likelihood of breaches. In an increasingly regulated environment, CLM software provides a secure, efficient way to manage contracts while ensuring that legal and regulatory requirements are met.
Growing Business Complexity
As businesses expand across regions and industries, managing contracts with diverse terms, conditions, and contract types becomes increasingly complex. CLM software offers a centralized platform for managing contracts globally, providing uniformity across varying jurisdictions. For instance, DHL Global Forwarding uses a well-developed contract management system built on automated workflows to effectively manage their numerous contracts while reducing the risk of errors and non-compliance. This is especially important for companies dealing with service agreements, non-disclosure agreements, and vendor contracts, where manual processes can lead to inefficiencies. CLM software automates the creation, negotiation, and execution of contracts, allowing organizations to handle their diverse contractual obligations more effectively and efficiently.
Digital Transformation The ongoing shift toward digital workflows is accelerating the adoption of CLM software, which plays a pivotal role in transitioning businesses away from paper-based processes. By digitizing contract management, organizations reduce paper consumption, improve security, and enhance operational efficiency. Moreover, CLM software integrates with other key business systems like CRM, ERP, and HR platforms, ensuring smooth data flow and improving overall accuracy. This integration helps businesses maintain seamless contract workflows, driving faster decision-making and improved contract visibility across departments.
Need for Improved Efficiency and Cost Reduction CLM software significantly enhances operational efficiency by automating time-consuming manual tasks involved in contract management. This reduces time-to-contract, streamlines workflows, and eliminates human errors. Additionally, by automating contract tracking and ensuring accuracy, CLM solutions help organizations save on administrative costs and avoid expensive legal disputes. The result is a more cost-effective, streamlined process that allows companies to focus resources on higher-value tasks, leading to overall business growth and improved contract outcomes.
Market Trends
Artificial Intelligence (AI) and Machine Learning (ML) Transforming CLM The integration of AI and Machine Learning into Contract Lifecycle Management (CLM) software is revolutionizing contract creation, review, and analysis. AI-powered systems can automate the drafting of contracts using predefined templates and data, minimizing manual efforts and improving overall accuracy. For instance, a survey conducted by a leading CLM software provider revealed that businesses using AI-powered CLM solutions experienced a significant reduction in contract drafting time. Machine Learning algorithms further streamline the process by reviewing contracts for potential risks, inconsistencies, and non-compliance, significantly reducing errors and speeding up the review process. Moreover, AI-driven predictive analytics is becoming a key feature in CLM, enabling businesses to forecast contract performance, identify risks, and optimize contract terms. This technology not only improves operational efficiency but also enhances decision-making, allowing organizations to mitigate risks proactively and drive better outcomes in their contract management processes.
Cloud-Based CLM Solutions Enabling Scalability and Collaboration Cloud-based CLM solutions are becoming the preferred choice for businesses due to their scalability, flexibility, and cost-efficiency. These solutions eliminate the need for expensive on-premises infrastructure, reducing IT overhead and making CLM accessible to organizations of all sizes. Cloud-based CLM platforms allow teams to collaborate remotely, offering real-time access to contracts and enabling faster decision-making and execution. This enhanced accessibility supports seamless collaboration between departments and stakeholders, ensuring that contract management processes remain streamlined, even for distributed teams. Moreover, with the growing emphasis on remote work and global partnerships, the ability to access and manage contracts from any location is a critical advantage. Businesses adopting cloud-based CLM solutions benefit from reduced operational costs, improved collaboration, and greater flexibility, ensuring they can scale efficiently as their contract management needs evolve. The cloud's agility and cost-effectiveness are key drivers in the increasing adoption of cloud-based CLM across various industries.
Market Challenges Analysis
Complexity and Customization in CLM Software Implementation Managing the diverse range of contract types across organizations presents a significant challenge for Contract Lifecycle Management (CLM) software. Each contract type, from vendor agreements to non-disclosure agreements, has unique requirements, demanding a flexible yet consistent approach to contract management. Ensuring that CLM software accommodates these variations while maintaining efficiency can be complex. For instance, a survey by a leading CLM software provider revealed that organizations often require customizations to align the software with their specific workflows and internal processes. These customizations, while necessary for optimal functionality, can be both time-consuming and costly, especially when addressing intricate operational needs. Balancing customization with software efficiency is a critical hurdle that organizations must navigate when implementing CLM solutions.
Data Quality and Integration Challenges Data accuracy is paramount in contract management, and ensuring that CLM software operates with reliable, up-to-date data is essential for effective decision-making and compliance. Poor data quality, whether due to outdated information or incorrect entries, can lead to significant inefficiencies, errors, and legal risks. Additionally, integrating CLM software with other business systems like Customer Relationship Management (CRM) or Enterprise Resource Planning (ERP) can be complex and require specialized technical expertise. These integration challenges not only demand significant time and resources but also increase the risk of data inconsistencies between systems. Organizations must prioritize both data accuracy and seamless integration to maximize the benefits of their CLM software.
Market Segmentation Analysis:
By Solution:
The Contract Lifecycle Management (CLM) Software market is segmented by solution type, including CLM software and associated services. CLM software is the core component, providing automation and management capabilities for contract creation, negotiation, execution, and renewal. In addition to the software, CLM services like professional services, risk & compliance assessment, and implementation & integration play crucial roles in ensuring successful adoption and integration within organizations. Support & maintenance services help maintain the system's efficiency over time, while managed services offer outsourced contract management solutions. These combined services enhance the value of CLM software, ensuring smooth implementation, ongoing support, and risk mitigation.
By Business Function: The CLM market is also segmented by business function, reflecting its widespread application across different departments. Legal teams use CLM software for contract drafting and compliance management, while finance departments leverage it for contract-related financial forecasting and audit preparation. Procurement uses CLM to manage supplier contracts and ensure compliance, while sales teams track agreements with customers. Operations benefit from streamlined contract management, ensuring process efficiency, and human resources utilize CLM for employment agreements and related contracts. Information Technology (IT) departments are vital in overseeing the software’s implementation, integration, and ongoing functionality across the organization, ensuring security and compliance are maintained.
Segments:
Based on Solution:
- Contract Lifecycle Management Software
- Contract Lifecycle Management Services
- Professional Services
- Risk & Compliance Assessment
- Implementation & Integration
- Support & Maintenance
- Managed Services
- Professional Services
Based on Business Function:
- Legal
- Finance
- Procurement
- Sales
- Operations
- Human Resource
- Information Technology
Based on Industry:
- BFSI
- IT & Telecom
- Government & Public Sector
- Energy & Utilities
- Manufacturing
- Healthcare & Pharma
- Life Sciences
- Retail
- Real Estate
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant position in the Contract Lifecycle Management (CLM) Software market, accounting for approximately 40% of the global market share. This region's leadership is driven by the strong presence of major technology vendors, early adoption of advanced digital solutions, and strict regulatory requirements that necessitate robust contract management systems. The U.S. and Canada, in particular, have experienced significant adoption of CLM software due to the need for regulatory compliance, especially in industries like healthcare, finance, and pharmaceuticals. Additionally, the push for digital transformation across sectors has led to increased demand for automation, streamlining contract workflows, and improving overall efficiency in contract management. North America’s business environment, with its focus on operational efficiency and cost reduction, continues to fuel the growth of the CLM market.
Asia Pacific Asia Pacific is emerging as a rapidly growing market for CLM software, capturing nearly 25% of the global market share. The region’s growth is driven by increasing digitalization efforts, expanding business operations, and the need for contract management solutions across diverse sectors such as manufacturing, retail, and financial services. Countries like China, India, and Japan are witnessing a surge in demand for CLM software, driven by complex regulatory landscapes, global business expansion, and the rising need for operational transparency. The growing adoption of cloud-based solutions in Asia Pacific has further accelerated the demand for CLM software, as companies seek scalable, cost-effective solutions that provide real-time data and help streamline contract processes. Government initiatives to promote digital infrastructure and automation in business processes are also contributing to the market’s growth in this region.
Key Player Analysis
- Ivalua Inc.
- Agiloft Inc.
- Concord
- Zycus Inc.
- Symfact
- Icertis
- Infor
- GEP
- Synertrade (Econocom Group)
- CobbleStone Software
- Apttus
- Infosys Limited
- Trackado
- SecureDocs, Inc.
- Coupa Software Inc. (Exari)
- SAP SE
- Newgen Software Technologies Limited
- Corcentric
- Information Services Group, Inc.
- Contract Logix, LLC
- Model N, Inc.
- iContracts, Inc.
- ASC Networks Inc.
- SpringCM
- Conga
- Jaggaer
Competitive Analysis
The Contract Lifecycle Management (CLM) Software market is highly competitive, with leading players offering comprehensive solutions to address the growing complexity of contract management. Companies like Icertis, Coupa Software Inc., SAP SE, and Agiloft Inc. dominate the market by providing innovative features such as AI-powered contract analysis, automation, and seamless integration with other enterprise systems like ERP and CRM. These players focus on scalability, flexibility, and enhanced compliance features to cater to the diverse needs of global enterprises. In addition to providing cloud-based solutions, they are investing heavily in AI and machine learning technologies to offer predictive analytics and risk management capabilities. Competitive differentiation often hinges on the ability to offer end-to-end contract management, along with strong security and data privacy features. As the demand for digital transformation increases, these market leaders are positioned to continue shaping the evolution of the CLM software landscape.
Recent Developments
- In July 2024, Icertis received the AI Breakthrough Award for AI Platform Innovation for its contract intelligence platform.
- In May 2024, Infor was positioned as a Leader in the 2024 Gartner Magic Quadrant for Warehouse Management Systems.
- In January 2024, Agiloft was selected by Epicor to digitally transform its contract-driven processes across global operations.
- In December 2023, Concord published an article highlighting the top 10 reasons to buy contract management software in 2024.
- In August 2023, Ivalua announced the general availability of its new platform release 178, which includes AI-powered contract digitization and analytics.
Market Concentration & Characteristics
The Contract Lifecycle Management (CLM) Software market exhibits a moderate to high level of market concentration, with a few dominant players holding significant market share. Companies like Icertis, Coupa Software Inc., and SAP SE lead the industry with their advanced CLM solutions, offering robust features such as AI-driven contract analytics, automation, and seamless integration with enterprise systems. These key players benefit from strong customer bases, global reach, and continuous investment in innovation. However, the market also provides opportunities for smaller and niche players, who often cater to specific industries or offer highly customizable solutions. The market is characterized by the growing demand for cloud-based CLM solutions, enhanced security and compliance capabilities, and the integration of AI and machine learning to streamline contract management. As businesses prioritize efficiency and risk management, the CLM market is expected to witness further growth, with both large and emerging players driving advancements in the field.
Report Coverage
The research report offers an in-depth analysis based on Solution, Business Function, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cloud-based contract lifecycle management solutions will continue to rise due to their scalability and flexibility.
- AI and machine learning will increasingly automate contract creation, analysis, and risk management.
- Integration with enterprise systems such as ERP and CRM will become a standard feature in CLM platforms.
- Real-time contract analytics will help organizations make data-driven decisions and optimize contract performance.
- The focus on data privacy and compliance will drive the adoption of enhanced security features in CLM solutions.
- CLM solutions will play a key role in helping businesses meet evolving regulatory requirements globally.
- The adoption of mobile-friendly CLM platforms will grow, offering access to contracts anytime and anywhere.
- Small and medium-sized enterprises (SMEs) will increasingly adopt CLM solutions as they become more affordable and user-friendly.
- Automation of workflows and approval processes will reduce manual efforts and improve contract turnaround times.
- The growing need for transparency and accountability will drive CLM adoption in industries with complex compliance requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Regulatory Compliance
The growing complexity of global regulations and stricter data privacy laws like GDPR and CCPA are pushing organizations to adopt CLM software to ensure contracts meet compliance standards, minimize legal risks, and avoid penalties.
Growing Business Complexity
As organizations expand across regions and industries, the diversity and volume of contracts increase, making centralized, automated CLM solutions essential for managing varied contract types, reducing errors, and ensuring consistency.
Digital Transformation
The shift from paper-based to digital workflows is accelerating CLM adoption, as businesses seek to improve efficiency, security, and integration with other enterprise systems such as CRM and ERP.
Need for Improved Efficiency and Cost Reduction
CLM software automates manual contract processes, reducing time-to-contract, minimizing human errors, and lowering administrative costs, which enables organizations to focus resources on higher-value activities.
AI and Machine Learning Integration
The incorporation of AI and machine learning into CLM platforms enables advanced contract analysis, risk identification, and predictive analytics, driving smarter decision-making and further streamlining contract management processes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Contract Lifecycle Management Software Market?
What factors are driving the growth of the Contract Lifecycle Management Software Market?
What are the key segments within the Contract Lifecycle Management Software Market?
What are some challenges faced by the Contract Lifecycle Management Software Market?
Who are the major players in the Contract Lifecycle Management Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 BFSI
- 1.2.2 IT & Telecom
- 1.2.3 Government & Public Sector
- 1.2.4 Energy & Utilities
- 1.2.5 Manufacturing
- 1.2.6 Healthcare & Pharma
- 1.2.7 Life Sciences
- 1.2.8 Retail
- 1.2.9 Real Estate
- 1.2.10 Others
- 1.3 By Solution
- 1.3.1 Contract Lifecycle Management Software
- 1.3.2 Professional Services
- 1.3.3 Risk & Compliance Assessment
- 1.3.4 Implementation & Integration
- 1.3.5 Support & Maintenance
- 1.3.6 Managed Services
- 1.4 By Business Function
- 1.4.1 Legal
- 1.4.2 Finance
- 1.4.3 Procurement
- 1.4.4 Sales
- 1.4.5 Operations
- 1.4.6 Human Resource
- 1.4.7 Information Technology
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,525 million → 2032: USD 6,432.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Contract Lifecycle Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Contract Lifecycle Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Contract Lifecycle Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Contract Lifecycle Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Contract Lifecycle Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Contract Lifecycle Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Contract Lifecycle Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Contract Lifecycle Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,525 million → 2032: USD 6,432.68 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Contract Lifecycle Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 BFSI
- 12.3.6.2 IT & Telecom
- 12.3.6.3 Government & Public Sector
- 12.3.6.4 Energy & Utilities
- 12.3.6.5 Manufacturing
- 12.3.6.6 Healthcare & Pharma
- 12.3.6.7 Life Sciences
- 12.3.6.8 Retail
- 12.3.6.9 Real Estate
- 12.3.6.10 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Contract Lifecycle Management Software
- 12.4.6.2 Professional Services
- 12.4.6.3 Risk & Compliance Assessment
- 12.4.6.4 Implementation & Integration
- 12.4.6.5 Support & Maintenance
- 12.4.6.6 Managed Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Business Function - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Legal
- 12.5.6.2 Finance
- 12.5.6.3 Procurement
- 12.5.6.4 Sales
- 12.5.6.5 Operations
- 12.5.6.6 Human Resource
- 12.5.6.7 Information Technology
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Contract Lifecycle Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Contract Lifecycle Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Contract Lifecycle Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Contract Lifecycle Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Icertis
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Coupa Software Inc.
- 18.4 SAP SE
- 18.5 Agiloft Inc.
- 18.6 Zycus Inc.
- 18.7 Infor
- 18.8 Concord
- 18.9 CobbleStone Software
- 18.10 Conga
- 18.11 Jaggaer
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

