
Market Overview:
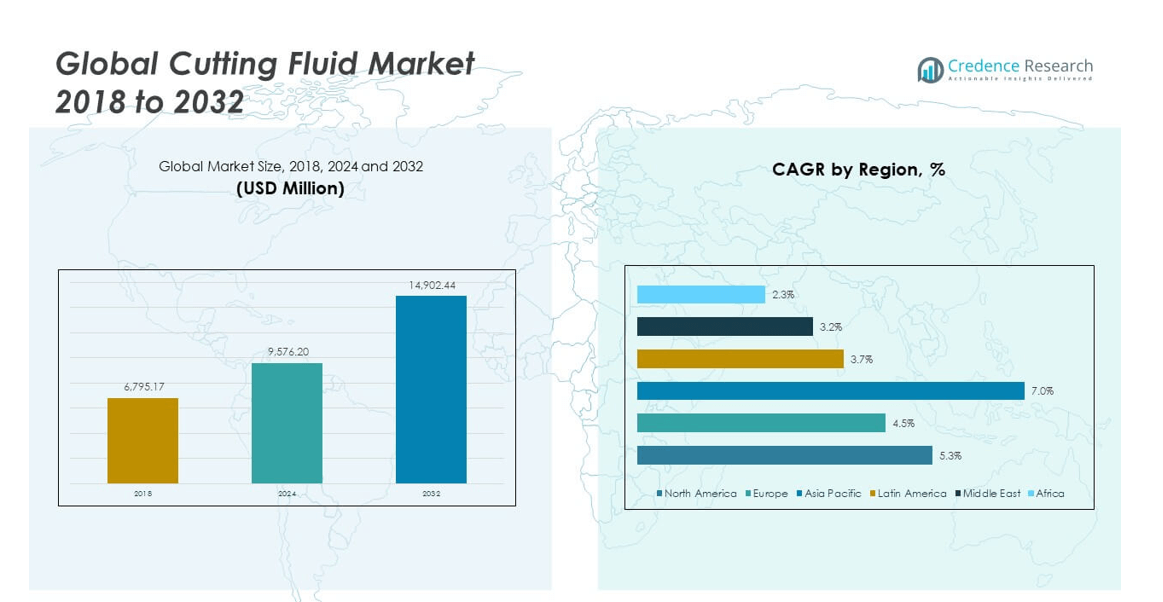
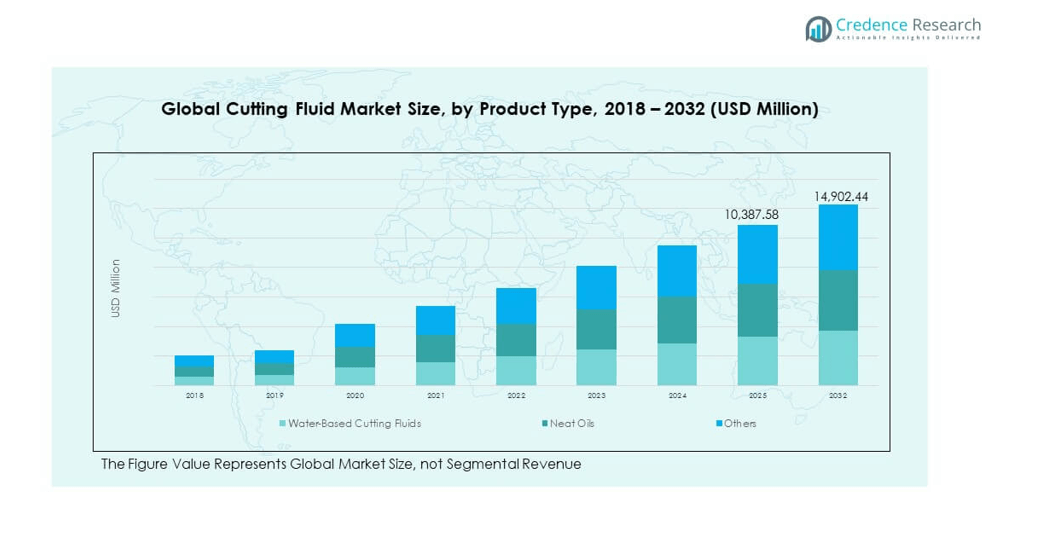
The Global Cutting Fluid Market size was valued at USD 6,795.17 million in 2018 to USD 9,576.20 million in 2024 and is anticipated to reach USD 14,902.44 million by 2032, at a CAGR of 5.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cutting Fluid Market Size 2024 | USD 9,576.20 million |
| Cutting Fluid Market, CAGR | 5.29% |
| Cutting Fluid Market Size 2032 | USD 14,902.44 million |
Growth in this market is driven by rising demand from the automotive, aerospace, and metalworking industries. Cutting fluids enhance tool life, improve machining quality, and reduce operational costs. Increasing industrialization and precision engineering requirements are fueling the need for advanced fluid formulations. The surge in global manufacturing and the adoption of high-performance machinery are further expanding market opportunities. Companies are also investing in sustainable and bio-based cutting fluids, supporting stricter environmental regulations.
The market shows regional diversity with Asia Pacific leading due to rapid industrialization, large manufacturing hubs, and automotive expansion. North America and Europe remain significant markets, backed by strong aerospace and automotive production. Emerging economies in Latin America and the Middle East are experiencing steady adoption, driven by infrastructure and energy projects. Africa shows slow but stable growth, reflecting gradual industrial developments. The mix of mature and emerging regions ensures sustained long-term demand.
Market Insights:
- The Global Cutting Fluid Market was valued at USD 9,576.20 million in 2024 and will reach USD 14,902.44 million by 2032.
- Growth is fueled by rising demand in automotive, aerospace, and metalworking industries.
- Market restraints include regulatory challenges and competition from dry machining.
- Asia Pacific leads due to industrial expansion, while North America and Europe remain strong markets.
- Latin America and Middle East show steady demand driven by infrastructure projects.
- Africa grows slower, limited by industrial capacity.
- Sustainability and innovation shape future growth across all regions.
Market Drivers:
Expanding Metalworking and Manufacturing Applications:
The Global Cutting Fluid Market grows steadily as industries rely heavily on machining operations. Fluids extend tool life, improve cutting accuracy, and enhance overall surface quality. Automotive, aerospace, and heavy machinery sectors create consistent demand worldwide. CNC machines and automation increase reliance on advanced fluid solutions. Growth in shipbuilding, defense, and construction equipment manufacturing strengthens adoption. End-users focus on productivity and operational cost reduction through effective fluids. Metalworking expansion across emerging economies amplifies usage. This broad industrial base secures long-term growth opportunities.
- For instance, Sandvik Coromant reported that use of their CoroCut® 2 cutting fluid in high-speed steel milling reduced tool wear by up to 40%, while improving surface finish consistency by 30% when applied in automotive parts manufacturing plants in India, demonstrating clear efficiency gains in emerging markets.
Rising Demand for High-Performance and Eco-Friendly Fluids:
The Global Cutting Fluid Market is shifting toward high-performance and eco-friendly solutions. Industries prefer bio-based and synthetic fluids that reduce environmental risks. Stricter regulations push companies away from hazardous mineral oil-based products. Worker safety drives adoption of fluids with reduced mist and skin irritation. Aerospace and defense sectors need specialized formulations for advanced materials. Research investments target biodegradable products without losing performance. Growing customer preference aligns with sustainable fluid innovation. Manufacturers delivering such solutions maintain a competitive edge globally.
- For instance, Lubrizol's EcoCool line (via Fuchs, who markets EcoCool) offers aerospace-grade water-miscible machining coolants with approvals from Airbus and Boeing, tailored for effective machining of high-performance metals.
Automotive and Aerospace Industry Growth Stimulating Adoption:
The Global Cutting Fluid Market gains strong traction from automotive and aerospace expansion. Automakers rely on fluids for machining engines, transmissions, and gear systems. EV growth introduces new material demands requiring advanced formulations. Aerospace industries machine titanium, composites, and lightweight metals needing superior lubrication. Defense and commercial aviation projects boost global machining volumes. Asia Pacific production hubs support export-driven demand for cutting fluids. North America and Europe remain vital with strong aerospace output. These sectors provide consistent, long-term consumption growth.
Technological Advancements in Machining Solutions:
The Global Cutting Fluid Market evolves alongside rapid changes in machining technologies. CNC, high-speed, and multi-axis systems demand superior thermal stability. Fluids ensure precision, reduced downtime, and extended tool life. Industry 4.0 integration supports real-time monitoring of fluid quality. Advanced formulations enhance performance in automated manufacturing. Sectors like medical devices and aerospace demand specialized fluids. R&D focuses on hybrid solutions offering lubrication and cooling efficiency. Technology-driven innovation sustains steady demand across industries worldwide.
Market Trends:
Shift Toward Sustainable and Bio-Based Solutions:
The Global Cutting Fluid Market is witnessing strong growth in sustainable product development. Bio-based and synthetic fluids are gaining traction across industries. Companies emphasize renewable resources to reduce environmental footprint. Regulatory frameworks are pushing industries away from mineral oil-based fluids. Growing acceptance of biodegradable cutting fluids strengthens market appeal. Customers seek solutions that enhance safety and sustainability. Adoption of green alternatives continues to rise in developed and emerging regions alike.
- For instance, Fuchs Petrolub's Ecocut and Plantocut fluid ranges emphasize biodegradability, low emission, and suitability for demanding alloys including aerospace metals, meeting ecological and workplace safety standards.
Integration of Smart Monitoring in Fluid Management:
Industries are adopting smart systems for cutting fluid monitoring. IoT-enabled sensors now track fluid condition and performance in real time. Predictive maintenance models help reduce downtime and extend fluid life. Automation ensures fluids remain consistent in concentration and quality. Cost savings drive industries toward these innovations. Smart monitoring reduces waste and aligns with sustainability goals. The Global Cutting Fluid Market grows as digital solutions merge with fluid systems.
- For instance, BMW’s Regensburg plant uses AI-driven predictive maintenance and IoT sensors to reduce unexpected downtime significantly, documented as saving over 500 minutes yearly in disruptions, exemplifying smart fluid monitoring applications.
Customization and Application-Specific Formulations:
Manufacturers are developing fluids tailored for specific applications. Aerospace machining requires coolants for titanium alloys, while automotive sectors demand solutions for high-volume production. Medical device manufacturing needs biocompatible formulations for sensitive applications. Customized solutions reduce wear, enhance tool life, and improve product quality. This demand is encouraging R&D in niche formulations. End-users increasingly prefer fluids that match their industry-specific needs. The Global Cutting Fluid Market benefits from this shift toward customization.
Increasing Emphasis on Worker Health and Safety Standards:
Industries are focusing on reducing health risks associated with cutting fluids. Formulations with reduced volatile compounds are in demand. Companies prioritize fluids with minimal skin irritation and low mist formation. Worker protection regulations in North America and Europe drive stricter adoption. Safer alternatives are replacing traditional oil-based formulations. Corporate ESG initiatives emphasize worker well-being and safer workplaces. The Global Cutting Fluid Market aligns with these priorities by promoting safer products.
Market Challenges Analysis:
Regulatory and Environmental Compliance Pressures:
The Global Cutting Fluid Market faces strict regulations regarding disposal and environmental safety. Used fluids often contain contaminants, making disposal complex and costly. Industries must comply with hazardous waste rules, adding operational expenses. Increasing restrictions on mineral oils challenge traditional formulations. Smaller manufacturers struggle with compliance costs, limiting competitiveness. Meeting evolving regulatory frameworks requires continuous R&D. Market participants face pressure to innovate sustainable alternatives. These regulatory hurdles remain a key challenge.
High Costs and Competitive Alternatives:
High development and maintenance costs hinder adoption in smaller industries. Specialty fluids designed for high-performance machining are expensive. Recycling and filtration systems add to operational expenses. Alternatives such as dry machining and minimum quantity lubrication are gaining traction. These methods reduce dependence on cutting fluids altogether. Competition from such technologies threatens long-term demand. The Global Cutting Fluid Market must adapt with value-added solutions. Price-sensitive markets remain vulnerable to slower adoption.
Market Opportunities:
Expanding Growth in Asia Pacific and Emerging Economies:
The Global Cutting Fluid Market holds significant opportunities in Asia Pacific and emerging regions. Rapid industrialization in China, India, and Southeast Asia drives demand. Automotive and infrastructure investments expand machining operations. Local production hubs encourage adoption of advanced fluids. Growing aerospace and energy projects enhance regional opportunities. Manufacturers expanding footprints in these markets benefit from high growth potential. Rising investments in sustainable products also open new possibilities.
Innovation and Development of High-Performance Solutions:
Opportunities lie in the creation of advanced, multi-functional cutting fluids. Hybrid fluids offering cooling, lubrication, and environmental safety are gaining attention. Innovation in nanotechnology supports next-gen formulations. Aerospace, EV, and precision engineering industries demand specialized solutions. Partnerships with equipment manufacturers foster tailored fluid integration. Market leaders investing in advanced R&D strengthen future opportunities. The Global Cutting Fluid Market is positioned to capitalize on evolving industry needs.
Market Segmentation Analysis:
Product Type
In the Global Cutting Fluid Market, water-based fluids dominate due to strong cooling efficiency, low costs, and versatility across multiple machining applications. Neat oils remain vital in operations requiring high lubrication and durability, such as heavy-duty metal cutting and aerospace machining. Other specialized fluids serve niche needs in high-performance industries where conventional options fall short.
- For instance, Castrol Syntilo series is confirmed for high-speed machining cooling and lubrication that extends tool life while managing extreme temperatures in automotive and aerospace applications.
End User Industry
The automotive industry represents a major share, requiring cutting fluids for engines, transmissions, and precision components. Aerospace machining also drives significant demand for fluids with superior cooling and performance capabilities. Oil & gas and general manufacturing industries maintain consistent consumption, supported by large-scale equipment production. Expanding industrialization ensures sustained demand across these verticals.
- For instance, Boeing's use of advanced cutting fluids in aerospace machining aligns with jet engine component production needs, supported by their published innovation practices.
Segmentation:
By Product Type
- Water-Based Cutting Fluids
- Neat Oils
- Others
By End User Industry
- Metal Working Industry
- Oil & Gas Industry
- Automotive Industry
- General Manufacturing Industry
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Cutting Fluid Market size was valued at USD 3,011.09 million in 2018 to USD 4,200.01 million in 2024 and is anticipated to reach USD 6,553.92 million by 2032, at a CAGR of 5.3% during the forecast period. North America holds 27.5% share in 2024, driven by its strong aerospace, defense, and automotive industries. The U.S. leads the region with extensive manufacturing infrastructure and R&D investment. Canada contributes with metalworking and oil & gas projects, while Mexico supports demand through its growing automotive supply chains. Advanced CNC machining adoption fuels high-performance fluid usage. Environmental regulations push industries toward bio-based alternatives. North America continues to sustain growth through advanced technology integration.
Europe
The Europe Global Cutting Fluid Market size was valued at USD 1,885.36 million in 2018 to USD 2,559.04 million in 2024 and is anticipated to reach USD 3,743.92 million by 2032, at a CAGR of 4.5% during the forecast period. Europe represents 26.7% share in 2024, supported by aerospace, automotive, and energy sectors. Germany, the UK, and France remain key contributors, focusing on advanced precision machining. Strong regulatory frameworks encourage the adoption of sustainable fluids. Automotive hubs in Italy and Spain add further demand. Russia and Eastern Europe drive steady growth in heavy industries. Europe balances innovation with environmental responsibility, reinforcing long-term stability.
Asia Pacific
The Asia Pacific Global Cutting Fluid Market size was valued at USD 1,266.25 million in 2018 to USD 1,938.99 million in 2024 and is anticipated to reach USD 3,429.35 million by 2032, at a CAGR of 7.0% during the forecast period. Asia Pacific commands 20.2% share in 2024, fueled by rapid industrialization and large-scale automotive and aerospace manufacturing. China dominates with extensive metalworking and automotive exports. India shows rapid growth with strong automotive and infrastructure investments. Japan and South Korea contribute with advanced machining technologies. Southeast Asia expands demand through industrial clusters and export-driven manufacturing. Asia Pacific remains the fastest-growing regional market.
Latin America
The Latin America Global Cutting Fluid Market size was valued at USD 328.51 million in 2018 to USD 457.34 million in 2024 and is anticipated to reach USD 631.83 million by 2032, at a CAGR of 3.7% during the forecast period. Latin America holds 4.8% share in 2024, with Brazil leading demand through its automotive and oil & gas industries. Argentina supports growth with manufacturing expansion, while Mexico overlaps with North American supply chains. Infrastructure development projects stimulate machining demand. Despite economic fluctuations, steady industrial activity supports gradual adoption. Latin America remains a secondary but important growth region.
Middle East
The Middle East Global Cutting Fluid Market size was valued at USD 198.65 million in 2018 to USD 256.91 million in 2024 and is anticipated to reach USD 340.19 million by 2032, at a CAGR of 3.2% during the forecast period. The Middle East holds 2.7% share in 2024, driven by oil & gas projects and growing industrial diversification. GCC countries are investing in advanced manufacturing capabilities. Turkey contributes with its automotive and machinery exports. Israel supports adoption through high-tech precision industries. Regional energy projects maintain steady demand for fluids. Expansion into industrial clusters creates gradual opportunities for market players.
Africa
The Africa Global Cutting Fluid Market size was valued at USD 105.30 million in 2018 to USD 163.93 million in 2024 and is anticipated to reach USD 203.24 million by 2032, at a CAGR of 2.3% during the forecast period. Africa holds 1.7% share in 2024, reflecting slower growth compared to other regions. South Africa leads adoption with its automotive and mining industries. Egypt supports demand through its manufacturing and construction projects. Other African nations show limited but emerging usage. Industrial development remains concentrated in select economies. Growth is gradual, tied to infrastructure and energy projects.
Key Player Analysis:
- Quaker Houghton
- Fuchs Petrolub
- Blaser Swisslube
- Henkel AG & Co. KGaA
- Chemetall GmbH
- Cimcool Industrial Products
- Castrol
- ExxonMobil
- Master Fluid Solutions
- Houghton International Inc.
Competitive Analysis:
The Global Cutting Fluid Market is characterized by intense competition among international and regional players. It includes established firms such as Quaker Houghton, Fuchs Petrolub, Castrol, ExxonMobil, and Blaser Swisslube. These companies dominate through extensive product portfolios, global distribution networks, and consistent R&D investments. The market also features specialized firms like Cimcool, Master Fluid Solutions, and Chemetall GmbH. Innovation in sustainable and high-performance fluids strengthens their positioning. Competitive strategies focus on acquisitions, regional expansion, and partnerships with OEMs. The Global Cutting Fluid Market continues to evolve, with innovation and compliance shaping the landscape.
Recent Developments:
- In July 2024, Quaker Houghton broke ground on a new state-of-the-art manufacturing facility in Zhangjiagang, China. This facility will expand their production capabilities to support growth in the Asia-Pacific region and is expected to be operational by the second quarter of 2026. Quaker Houghton also announced a strategic partnership with Idemitsu Kosan in April 2025 to offer their wide range of water-soluble metalworking fluids to Japanese customers across key markets.
- In April 2025, Henkel AG & Co. KGaA announced a strategic partnership and supply agreement with Synthomer. This collaboration focuses on enabling carbon emission reductions in Henkel's TECHNOMELT® hot melt adhesive product portfolio across Europe, India, the Middle East, and Africa, highlighting their commitment to sustainability. Additionally, in July 2025, Henkel launched a solvent-free adhesive system, Loctite Liofol LA 7837/LA 6265, designed for safe and sustainable high-performance packaging applications.
- Blaser Swisslube introduced several innovative metalworking fluids in 2024 to the Indian market, including B-Cool Motec 501 and Blasocut 201, emphasizing sustainability and enhanced machining performance.
- Chemetall GmbH made significant progress towards sustainability in May 2025 by transitioning its Langelsheim production facility in Germany to 100% renewable electricity, aiming to reduce carbon footprint as part of its 2025 sustainability goals. No recent new product launches in cutting fluids were found.
- Cimcool Industrial Products announced a new synthetic lubricant technology in 2012 aimed at improving machining and grinding of hard metals without using chlorine or high levels of extreme-pressure additives, boosting productivity up to 300% compared to older technologies.
- Castrol unveiled new branding and extended oil change interval claims for its synthetic motor oil brands in mid-2024, including Castrol EDGE Extended Performance with a 25,000-mile oil change interval, emphasizing superior performance and protection.
Report Coverage:
The research report offers an in-depth analysis based on product types, end-user industries, and regional segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will increase in precision machining across automotive and aerospace industries.
- Eco-friendly and bio-based cutting fluids will gain stronger market penetration.
- Asia Pacific will remain the fastest-growing regional market.
- North America and Europe will continue to dominate high-value advanced fluid consumption.
- Customization of fluids for specialized applications will expand.
- Worker safety and ESG commitments will drive product innovation.
- Smart monitoring and IoT-enabled fluid management systems will see wider adoption.
- Competition will intensify with R&D-focused players expanding offerings.
- EV and lightweight material machining will create new fluid requirements.
- Long-term opportunities will favor companies aligning with sustainability and efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Metalworking and Manufacturing Applications
The increasing reliance on machining operations in automotive, aerospace, and heavy machinery sectors is driving demand for cutting fluids, as these fluids extend tool life, improve cutting accuracy, and enhance surface quality. Growth in CNC machines, automation, and industrialization in emerging economies further amplifies usage across a broad industrial base.
Rising Demand for High-Performance and Eco-Friendly Fluids
Stricter environmental regulations and a shift toward sustainability are pushing industries to adopt bio-based and synthetic cutting fluids that reduce environmental and worker health risks. Companies investing in innovative, eco-friendly formulations are gaining a competitive edge as customers increasingly prefer sustainable solutions.
Automotive and Aerospace Industry Growth
The expansion of automotive and aerospace manufacturing, including the rise of electric vehicles and advanced materials, is stimulating the adoption of specialized cutting fluids. These industries require fluids that can handle high-performance machining of complex components, ensuring consistent, long-term consumption growth.
Technological Advancements in Machining Solutions
The evolution of machining technologies such as CNC, high-speed, and multi-axis systems demands cutting fluids with superior thermal stability and performance. Integration of Industry 4.0 and smart monitoring systems is driving the need for advanced fluid formulations that support precision, reduced downtime, and extended tool life.
Regional Industrialization and Infrastructure Development
Rapid industrialization in Asia Pacific and infrastructure projects in emerging markets like Latin America and the Middle East are expanding the market for cutting fluids. Local production hubs and investments in manufacturing and energy sectors are creating new opportunities for market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Cutting Fluid Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Cutting Fluid Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Global Cutting Fluid Market?
Who are the leading companies in the Global Cutting Fluid Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Water-Based Cutting Fluids
- 1.2.2 Neat Oils
- 1.2.3 Others
- 1.3 By End User Industry
- 1.3.1 Metal Working Industry
- 1.3.2 Oil & Gas Industry
- 1.3.3 Automotive Industry
- 1.3.4 General Manufacturing Industry
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,576.20 million → 2032: USD 14,902.44 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cutting Fluid Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cutting Fluid Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cutting Fluid Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cutting Fluid Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cutting Fluid Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cutting Fluid Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cutting Fluid Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cutting Fluid Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,576.20 million → 2032: USD 14,902.44 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cutting Fluid Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Water-Based Cutting Fluids
- 12.3.7.2 Neat Oils
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metal Working Industry
- 12.4.7.2 Oil & Gas Industry
- 12.4.7.3 Automotive Industry
- 12.4.7.4 General Manufacturing Industry
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cutting Fluid End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cutting Fluid Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cutting Fluid Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cutting Fluid Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Quaker Houghton
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Fuchs Petrolub
- 18.4 Blaser Swisslube
- 18.5 Henkel AG & Co. KGaA
- 18.6 Chemetall GmbH
- 18.7 Cimcool Industrial Products
- 18.8 Castrol
- 18.9 ExxonMobil
- 18.10 Master Fluid Solutions
- 18.11 Houghton International Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

