
Dairy Ingredients Market Overview:
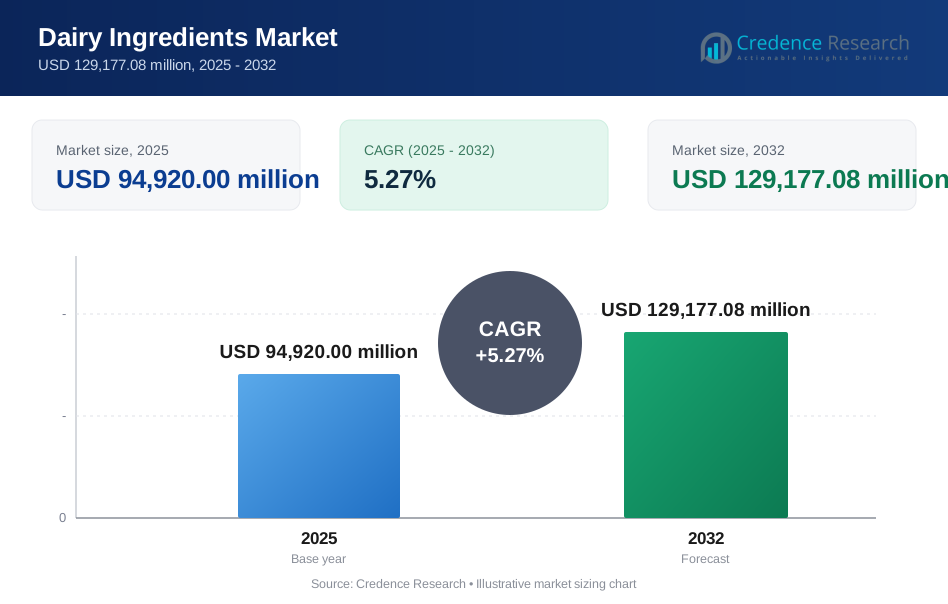
The global Dairy Ingredients Market size was estimated at USD 94,920.00 million in 2025 and is expected to reach USD 129,177.08 million by 2032, growing at a CAGR of 5.27% from 2025 to 2032. Demand is primarily driven by higher formulation intensity of dairy proteins and solids in packaged foods and nutrition products, where performance attributes such as texture, stability, and protein enrichment remain commercially important. Asia Pacific remains a major consumption and processing center, supported by expanding nutrition demand and scaled dairy value chains across large markets.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Dairy Ingredients Market Size 2025 | USD 94,920.00 million |
| Dairy Ingredients Market, CAGR | 5.27% |
| Dairy Ingredients Market Size 2032 | USD 129,177.08 million |
Key Market Trends & Insights
- The market is projected to expand from USD 94,920.00 million in 2025 to USD 129,177.08 million by 2032, reflecting a 5.27% CAGR during 2025–2032.
- Asia Pacific accounted for 38.4% of 2025 revenue, supported by large-scale dairy processing and strong demand from nutrition-led end uses.
- North America represented 28.6% of 2025 revenue, reflecting strong penetration of functional foods and performance nutrition channels.
- Milk-based ingredients led the source mix with a 77.3% share in 2025, supported by broad applicability across solids, proteins, and lactose systems.
- Food applications held the largest application share at 46.1% in 2025, driven by volume demand from bakery, confectionery, beverages, and mainstream processed foods.

Segment Analysis
Dairy ingredients demand is shaped by how manufacturers balance cost efficiency with performance requirements such as solubility, emulsification, heat stability, water-binding, and sensory outcomes. Food manufacturers drive consistent baseline consumption through large-volume categories that rely on dairy solids and functional proteins for formulation consistency. Nutrition-oriented categories raise the value mix by requiring higher protein density, cleaner taste, and more specialized processing that improves dispersion and stability in finished products.
Buyer preferences continue to shift toward targeted nutrition, which increases product development activity in high-protein, low-sugar, and function-forward formats. Ingredient selection is increasingly influenced by application support, supply reliability, and the ability to meet reformulation goals without compromising texture or shelf stability. Processing choices also reflect clean-label positioning, where manufacturers aim to deliver performance with fewer additives, supporting demand for better-engineered dairy systems.
By Ingredient Type Insights
Proteins remain central to dairy ingredient strategies because manufacturers use protein systems to deliver nutrition claims and functional performance across multiple food matrices. Lactose demand is sustained by its role in infant nutrition and as a formulation aid in select food and pharmaceutical use cases, although intolerance concerns influence product positioning in some channels. Mineral ingredients retain steady relevance where fortification and calcium-led nutrition messaging matter, especially in everyday consumption products that compete on health cues and label clarity.
By Source Insights
Milk accounted for the largest share of 77.3% in 2025. Milk-based streams provide the broadest functional coverage across powders, proteins, lactose, and mineral fractions, making them the preferred input for high-volume manufacturing. Procurement scale and ingredient standardization support repeatable product quality for large food brands. Product developers also rely on milk-derived systems to simplify formulations while maintaining texture and sensory stability across processing conditions.
By Application Insights
Food accounted for the largest share of 46.1% in 2025. Packaged food producers use dairy ingredients to achieve consistent mouthfeel, structure, and taste across bakery, confectionery, beverages, and dairy-based formulations. High-volume food manufacturing favors ingredients that perform reliably at scale and remain cost-effective across fluctuating input conditions. Innovation in everyday food formats also increases usage intensity for proteins and solids in reformulated and better-for-you offerings.
By Processing Level Insights
Standard ingredients remain essential for scale-driven food manufacturing where cost, availability, and specification consistency are the primary decision factors. Specialty ingredients gain importance in nutrition-led applications that demand higher purity, improved dispersibility, and tailored performance under heat, pH, and shear stress. Processing-led differentiation is increasingly used to support cleaner labels, better sensory outcomes, and simplified formulations. Application-specific support and performance validation reinforce preference for specialty systems in premium end uses.
Dairy Ingredients Market Drivers
Rising protein fortification across mainstream and nutrition categories
Food and beverage developers are expanding protein enrichment across everyday formats, which raises demand for dairy proteins that deliver both nutrition and functionality. Dairy protein systems are frequently selected for taste, texture, and formulation flexibility in ready-to-mix, ready-to-drink, and structured foods. Brand competition around protein claims increases reformulation cycles and broadens usage occasions. Ingredient suppliers benefit when customers seek consistent performance across multiple production sites and processing conditions.
Expansion of packaged food production and formulation complexity
Large-scale packaged food growth supports sustained consumption of dairy solids and functional components used for structure, mouthfeel, and stability. Manufacturers increasingly optimize recipes for shelf life and transport durability, which favors ingredients that improve water-binding and texture retention. As product portfolios widen, procurement strategies prioritize specification consistency and supply reliability. Dairy ingredients remain embedded in many core categories, supporting recurring demand.
- For instance, AMCO Proteins markets its CMP-8000 and CMP-8500 milk protein concentrates at 80% and 85% protein, respectively, for fermented and cultured dairy applications where texture and stability are critical, reflecting the preference for ingredients with tightly defined functional specifications in scaled packaged-food production.
Premiumization in infant and specialized nutrition
Infant and specialized nutrition categories emphasize tighter nutritional specifications and performance needs, supporting uptake of higher-value dairy components. Manufacturers require ingredients with predictable digestibility, stability, and clean sensory profiles to meet strict product expectations. Premiumization also drives demand for differentiated protein systems and refined carbohydrate components. Strong compliance requirements encourage long-term supplier relationships and validated ingredient performance.
- For instance, Lactalis Ingredients produces Prolacta soluble milk protein for infant formula through membrane technology and low-temperature processing, and the range is specified at 80% to 95% protein minimum on a dry basis while also offering low-spore and heat-stable quality, underscoring the premium placed on controlled composition and process integrity.
Processing innovation and functionality-driven differentiation
Ingredient processors continue to improve functional performance through refining and application-focused engineering. Better dispersibility, stability, and sensory outcomes support higher inclusion rates in beverages, bars, and fortified foods. Clean-label goals increase the value of ingredients that deliver functionality with fewer additives. This dynamic supports ongoing investment in specialized processing pathways and technical support capabilities.
Dairy Ingredients Market Challenges
Volatility in raw milk availability and input pricing can pressure margins and complicate long-term contracting for ingredient buyers. Cost inflation influences formulation decisions, including partial substitution, recipe optimization, and tighter specification tolerances. Supply shocks can also raise lead times and disrupt production planning for high-volume food categories. These pressures increase the importance of diversified sourcing and strong supplier qualification processes.
Regulatory and labeling expectations across regions can raise compliance complexity for multinational product portfolios. Requirements related to allergens, nutrition claims, and traceability influence product design and documentation needs. Manufacturers must also manage consumer sensitivity around sugar, calories, and perceived processing, which can constrain certain ingredient choices. Meeting performance goals under these constraints can increase R&D time and qualification cycles.
- For instance, Firmenich and Novozymes reported that their TasteGEM SWL with Saphera lactase solution enables up to 50% sugar reduction in yogurt without the use of sweeteners, while also lowering lactose levels, giving manufacturers a quantified formulation route to address cleaner-label and nutrition-focused product requirements.
Market Trends and Opportunities
High-protein beverages and hybrid dairy-based nutrition formats are expanding product development pipelines, creating incremental opportunities for specialty whey and milk proteins. Formulators increasingly prioritize clean taste, high solubility, and stability in low-sugar matrices, which supports demand for improved functional systems. Innovation in convenient formats increases the number of use occasions, expanding volume potential beyond traditional dairy categories. Ingredient suppliers that provide application support and rapid prototyping gain an advantage.
- For instance, Ascent Protein launched its Clear Whey Protein Isolate in October 2024 in two flavors, with 20 grams of whey protein and 100 calories per serving, demonstrating how lighter, juice-style formats can extend protein consumption beyond conventional shake occasions.
Clean-label reformulation remains a sustained opportunity as brands seek simpler ingredient decks without sacrificing texture and shelf stability. This trend supports solutions that deliver emulsification, viscosity, and structure without additional additives. Specialty processing can enable performance improvements that allow brands to maintain consumer-acceptable sensory profiles. Demand also grows for ingredients that enable fortification while minimizing negative taste or texture impacts.
Regional Insights
North America
North America held 28.6% of 2025 revenue, supported by strong demand from functional foods and performance nutrition applications. Large-scale food manufacturing and advanced ingredient processing capacity reinforce steady procurement of proteins, powders, and specialized systems. Product innovation in convenient high-protein formats supports higher-value mix expansion. Supplier differentiation is strongly influenced by technical service, consistency, and the ability to meet complex formulation targets.
Europe
Europe accounted for 24.1% of 2025 revenue, reflecting a mature market with established dairy processing ecosystems and strong adoption of value-added ingredients. Demand is supported by packaged foods, dairy processing, and nutrition categories that prioritize quality, safety, and sourcing standards. Competitive positioning often centers on traceability, specification discipline, and application performance under varied processing conditions. Innovation remains active in better-for-you reformulation and premium dairy-based offerings.
Asia Pacific
Asia Pacific led with 38.4% of 2025 revenue, driven by scale in dairy consumption and processing, alongside expanding demand for nutrition-oriented products. Growth is reinforced by modernization of food manufacturing and rising interest in protein-forward products across broader consumer segments. Regional supply chains increasingly emphasize ingredient standardization to support packaged food expansion. This environment sustains demand for both cost-efficient solids and higher-functionality proteins.
Latin America
Latin America represented 5.7% of 2025 revenue, supported by growth in packaged foods and localized dairy manufacturing in leading economies. Demand is influenced by affordability considerations, which sustains high usage of standard ingredients in mass-market products. At the same time, premiumization in select urban segments supports gradual adoption of specialty proteins. Supply reliability and cost-effective performance remain the primary decision factors.
Middle East & Africa
Middle East & Africa accounted for 3.2% of 2025 revenue, supported by expanding packaged food consumption and growing nutrition awareness in key markets. Import reliance and variable cold-chain and processing infrastructure can influence ingredient availability and product mix. Standard dairy solids remain important for mainstream manufacturing, while specialty adoption grows more selectively in premium channels. Suppliers with stable logistics and consistent specifications are better positioned in this region.
Competitive Landscape
Competition centers on scale, processing sophistication, application support, and the ability to supply consistent specifications across global manufacturing footprints. Companies differentiate through specialty protein performance, formulation partnership models, and tailored ingredient systems for food, infant, and sports nutrition use cases. Portfolio breadth across proteins, lactose, and functional systems helps suppliers address multiple end markets while balancing commodity exposure and value-added positioning.
Arla Foods Ingredients emphasizes functional whey and milk-based solutions supported by application development capabilities that help customers translate ingredient performance into finished-product outcomes. Product development support, sensory optimization, and stability validation strengthen adoption in beverages and nutrition formats that demand clean taste and reliable dispersion. The company’s ingredient strategy benefits from aligning protein functionality with evolving consumer preferences for protein-forward products. Technical collaboration remains a key lever for customer retention and new application penetration.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Arla Foods Ingredients
- FrieslandCampina
- Fonterra
- Lactalis Ingredients
- Kerry Group
- Glanbia
- DSM
- Saputo
- AMCO Proteins
- Hilmar Cheese
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In a May 2025 press release, Arla Foods Ingredients launched its “Maximum yield, no acid whey” concept for strained dairy production. The company said the new concept uses its Nutrilac HighYield milk proteins to eliminate acid whey from the process and deliver 100% milk yield, helping dairy producers improve efficiency and reduce waste.
- In a March 2025 update, Arla Foods Ingredients entered into a partnership with Valley Queen in South Dakota to manufacture dairy ingredients in the United States. Under the agreement, Valley Queen will produce ingredients from Arla Foods Ingredients’ Nutrilac ProteinBoost range, supporting rising demand for protein-enriched dairy products in the U.S. market.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 94,920.00 million |
| Revenue forecast in 2032 | USD 129,177.08 million |
| Growth rate (CAGR) | 5.27% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Ingredient Type Outlook: Proteins, Lactose, Minerals; By Source Outlook: Milk, Whey; By Application Outlook: Food, Infant Formula, Sports Nutrition; By Processing Level Outlook: Standard, Specialty |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Arla Foods Ingredients, FrieslandCampina, Fonterra, Lactalis Ingredients, Kerry Group, Glanbia, DSM, Saputo, AMCO Proteins, Hilmar Cheese |
| No.of Pages | 326 |
Segmentation
By Ingredient Type
- Proteins
- Lactose
- Minerals
By Source
- Milk
- Whey
By Application
- Food
- Infant Formula
- Sports Nutrition
By Processing Level
- Standard
- Specialty
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising protein fortification across mainstream and nutrition categories
Food and beverage developers are increasingly enriching products with dairy proteins to meet consumer demand for higher protein content, driving up the use of functional dairy ingredients in both everyday and specialized nutrition products.
Expansion of packaged food production and formulation complexity
Growth in large-scale packaged food manufacturing supports sustained demand for dairy solids and functional components, as manufacturers seek ingredients that enhance structure, mouthfeel, and shelf stability in a wide range of processed foods.
Premiumization in infant and specialized nutrition
Infant formula and specialized nutrition segments require dairy ingredients with precise nutritional profiles and high purity, supporting the uptake of premium proteins and refined carbohydrate components that meet strict regulatory and performance standards.
Processing innovation and functionality-driven differentiation
Advancements in ingredient processing are enabling improved dispersibility, stability, and sensory outcomes, which increases the value of specialty dairy ingredients that support clean-label reformulation and higher inclusion rates in innovative food and beverage formats.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Dairy Ingredients Market?
What is the CAGR for the Dairy Ingredients Market?
What is the largest segment in the Dairy Ingredients Market?
What factors are driving growth in the Dairy Ingredients Market?
Which companies are leading in the Dairy Ingredients Market?
Which region leads the Dairy Ingredients Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Milk
- 1.2.2 Whey
- 1.3 By Application
- 1.3.1 Food
- 1.3.2 Infant Formula
- 1.3.3 Sports Nutrition
- 1.4 By Ingredient Type
- 1.4.1 Proteins
- 1.4.2 Lactose
- 1.4.3 Minerals
- 1.5 By Processing Level
- 1.5.1 Standard
- 1.5.2 Specialty
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 94,920.00 million → 2032: USD 129,177.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dairy Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dairy Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dairy Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dairy Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dairy Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dairy Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dairy Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dairy Ingredients Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 94,920.00 million → 2032: USD 129,177.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dairy Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Milk
- 12.3.7.2 Whey
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food
- 12.4.7.2 Infant Formula
- 12.4.7.3 Sports Nutrition
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Ingredient Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Proteins
- 12.5.7.2 Lactose
- 12.5.7.3 Minerals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Processing Level - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Standard
- 12.6.7.2 Specialty
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dairy Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dairy Ingredients Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dairy Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dairy Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arla Foods Ingredients
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 FrieslandCampina
- 18.4 Fonterra
- 18.5 Lactalis Ingredients
- 18.6 Kerry Group
- 18.7 Glanbia
- 18.8 DSM
- 18.9 Saputo
- 18.10 AMCO Proteins
- 18.11 Hilmar Cheese
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

