
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Data Center Cooling Market Size 2024 | USD 12,839.45 million |
| Data Center Cooling Market, CAGR | 12.10% |
| Data Center Cooling Market Size 2032 | USD 41,861.20 million |
Market Overview
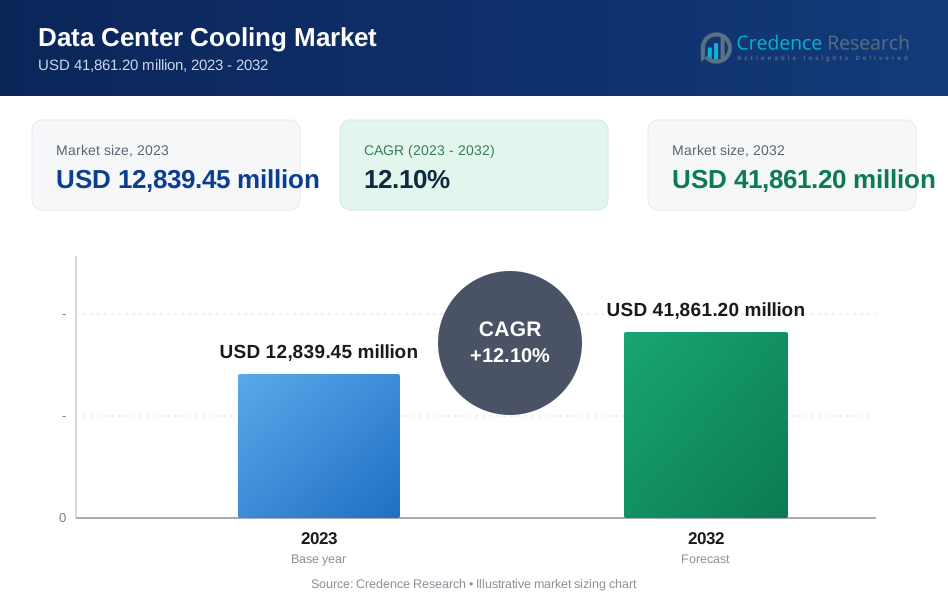
The global Data Center Cooling Market is projected to grow from USD 12,839.45 million in 2023 to an estimated USD 41,861.20 million by 2032, with a compound annual growth rate (CAGR) of 12.10% from 2024 to 2032. This significant growth is driven by the rising demand for energy-efficient cooling solutions in data centers, which are critical for ensuring optimal performance and preventing overheating as the adoption of cloud computing, AI, and big data accelerates worldwide.
Key market drivers include the increasing data center capacity, the need for sustainable and eco-friendly cooling systems, and regulatory mandates aimed at reducing carbon footprints. Trends like liquid cooling technologies, modular data centers, and the integration of AI for optimizing cooling efficiency are also gaining traction, supporting the market's expansion.
Geographically, North America is anticipated to dominate the market due to the high concentration of data centers in the U.S. and Canada. Meanwhile, Asia-Pacific is expected to witness the fastest growth, driven by rapid digitalization in countries like China and India. Leading players in the market include Schneider Electric, Vertiv Group Corp., and Huawei Technologies Co., Ltd., who are at the forefront of innovation in data center cooling solutions.
Market Drivers
Rising Data Center Demand and Capacity Expansion
The continuous expansion of data centers globally is one of the most significant drivers of the data center cooling market. As digital transformation accelerates, organizations across industries are increasingly relying on data centers to store, process, and manage vast amounts of information. The demand for data centers has been fueled by emerging technologies such as cloud computing, big data, and the Internet of Things (IoT). For instance, according to the International Energy Agency, global data center electricity use in 2022 was around 240-340 TWh, or 1-1.3% of global final electricity demand. This figure is expected to grow substantially in the coming years as data usage increases. The rapid growth of hyperscale data centers is also driving demand for advanced cooling solutions. For example, Google announced plans to invest $9.5 billion in new offices and data centers across the U.S. in 2022, highlighting the scale of expansion in the industry. As these facilities grow in size and capacity, the need for efficient and scalable cooling systems becomes increasingly critical to maintain optimal performance and prevent equipment failures due to overheating.
Need for Energy Efficiency and Sustainability
The growing emphasis on energy efficiency and sustainability is another key driver shaping the global data center cooling market. Data centers are known to consume large amounts of energy, much of which is attributed to cooling systems. For instance, the U.S. Department of Energy reports that cooling can account for up to 40% of a data center's total energy consumption. This has led to increased pressure on operators to adopt more sustainable cooling solutions. Many companies are setting ambitious sustainability goals. For example, Microsoft has pledged to be carbon negative by 2030 and to remove all of its historical carbon emissions by 2050. To achieve these goals, the company is investing in innovative cooling technologies for its data centers. In one case study, Microsoft successfully deployed a two-phase immersion cooling solution that reduced power consumption for cooling by up to 95% compared to traditional air cooling. Government initiatives are also driving this trend. The European Union's Code of Conduct for Energy Efficiency in Data Centres provides guidelines for improving energy efficiency, including best practices for cooling systems.
Technological Advancements in Cooling Solutions
The data center cooling market is witnessing rapid technological advancements, which are significantly driving market growth. Innovations in cooling technologies are addressing the growing need for efficient and cost-effective solutions to manage heat generated by high-density data centers. For example, Google has been experimenting with AI-powered cooling systems in its data centers. The company reported that its DeepMind AI system reduced energy use for cooling by up to 40% in its data centers, resulting in significant cost savings and environmental benefits. Liquid cooling technologies are also gaining traction. The Uptime Institute's 2023 Global Data Center Survey found that 41% of data center operators were either using or planning to use liquid cooling for at least some of their IT loads within the next two years. This trend is driven by the increasing power density of modern servers and the limitations of traditional air cooling methods. Another innovative approach is the use of natural resources for cooling. For instance, Facebook's data center in Luleå, Sweden, uses the cold Nordic air and water from nearby rivers to cool its servers, significantly reducing energy consumption and environmental impact.
Growing Adoption of Cloud Computing, AI, and Big Data
The increasing adoption of cloud computing, artificial intelligence (AI), and big data is a major factor driving the global data center cooling market. These technologies are reshaping industries by enabling faster data processing, real-time analytics, and enhanced decision-making capabilities. However, the widespread use of cloud computing and AI applications generates massive amounts of data that require storage and processing in data centers. This surge in data traffic places a significant strain on data center infrastructure, leading to increased heat generation and a higher demand for efficient cooling solutions. Cloud service providers, in particular, are expanding their data center networks to accommodate the growing number of enterprises migrating to the cloud. The need to ensure high levels of uptime and availability for cloud services has made cooling systems an integral part of data center operations. AI, which requires high-performance computing (HPC) environments, also contributes to the demand for advanced cooling solutions. AI workloads are often computationally intensive and generate substantial heat, making traditional cooling methods inadequate. Moreover, big data analytics, which involves processing vast amounts of structured and unstructured data, requires data centers to operate at optimal temperatures to avoid overheating and system failures. As organizations continue to embrace AI, big data, and cloud computing, the demand for advanced data center cooling technologies will rise, driving market growth.
Market Trends
Shift Towards Liquid Cooling Solutions for High-Density Data Centers
The global data center cooling market is experiencing a significant shift towards liquid cooling technologies, particularly for high-density computing environments. This trend is driven by the increasing demand for high-performance computing and artificial intelligence applications, which generate substantial heat loads that traditional air-based cooling methods struggle to manage efficiently. Liquid cooling solutions, utilizing water or dielectric fluids, offer superior thermal management capabilities and are becoming increasingly popular in hyperscale and colocation data centers. For instance, Google has been at the forefront of adopting liquid cooling technologies in its data centers. The company has implemented a two-phase liquid cooling system in some of its facilities, which has shown remarkable improvements in energy efficiency. Similarly, Microsoft has been exploring advanced liquid cooling solutions for its Azure cloud services, including the use of two-phase immersion cooling for high-density server racks. These examples highlight the growing acceptance of liquid cooling as a viable solution for managing the thermal challenges posed by modern data centers.
AI and Machine Learning Integration for Optimized Cooling Efficiency
The integration of artificial intelligence (AI) and machine learning (ML) into data center cooling systems represents another significant trend in the market. These advanced technologies are being leveraged to optimize cooling efficiency, reduce energy consumption, and enhance overall data center performance. AI-powered cooling systems can continuously monitor and analyze environmental conditions, making real-time adjustments to maintain optimal temperature and airflow. For instance, DeepMind, in collaboration with Google, has implemented an AI-driven cooling system in Google's data centers. This system has demonstrated the ability to reduce cooling energy consumption by up to 40% compared to traditional methods. Similarly, Huawei has developed an AI-powered iCooling solution that optimizes cooling efficiency based on real-time workload and environmental data. These examples illustrate how AI and ML are revolutionizing data center cooling management, leading to substantial improvements in energy efficiency and operational costs.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
A major restraint in the global data center cooling market is the high upfront cost and ongoing maintenance expenses of advanced cooling solutions. For instance, a survey by Uptime Institute found that increased cost was cited as the top barrier to deploying direct liquid cooling by respondents. The complex nature of modern cooling systems like liquid and immersion cooling requires specialized infrastructure and regular maintenance, driving up total costs of ownership. Small and medium enterprises in particular struggle to justify such large capital expenditures. Buyers are seeking modular, scalable cooling solutions that can grow with changing needs to help manage costs. However, transitioning entire facilities to new cooling technologies remains prohibitively expensive for many operators. The high costs create a significant hurdle for widespread adoption, especially in regions with limited financial resources. As data centers expand to meet rising demand, the industry faces a key challenge in balancing the need for efficient cooling with cost considerations.
Environmental and Regulatory Compliance Challenges
Stringent environmental regulations pose a major challenge for the data center cooling market globally. For instance, environmental sustainability was one of the top factors driving interest in direct liquid cooling adoption. Traditional air-based cooling systems rely heavily on electricity and use refrigerants with high global warming potential, conflicting with carbon reduction goals. Adapting cooling infrastructure to meet evolving efficiency standards and emissions targets is technologically and financially challenging for many operators. The pressure to reduce energy consumption and support sustainability goals is driving interest in liquid cooling and AI-driven optimization. However, transitioning entire facilities to eco-friendly cooling methods that utilize natural refrigerants or renewable energy remains complex. The industry faces a critical challenge in developing solutions that meet both performance requirements and regulatory standards across different regions without compromising operational efficiency or dramatically increasing costs.
Market Segmentation Analysis
By Component
The global Data Center Cooling market is segmented into Solutions and Services, with Solutions commanding the larger market share. This dominance is driven by the increasing demand for energy-efficient cooling technologies as data centers strive to reduce operational costs and environmental impact. For instance, a majority of data center operators plan to invest in advanced cooling solutions within the next few years. Liquid cooling systems, in particular, are gaining popularity due to their superior heat dissipation capabilities, especially for high-density server racks. The Services segment, while smaller, is experiencing steady growth as data center operators recognize the importance of professional installation, maintenance, and consulting services. A government report on data center energy consumption highlighted that proper implementation and ongoing maintenance of cooling systems can significantly improve overall efficiency. This has led to increased demand for specialized cooling services, with many operators opting for comprehensive service contracts to ensure optimal performance of their cooling infrastructure.
By Application
The Data Center Cooling market serves various industries, with Telecom & IT representing the largest segment. This dominance is fueled by the rapid growth of cloud computing, big data analytics, and artificial intelligence applications, all of which require robust cooling solutions to maintain optimal performance. For instance, a recent industry survey revealed that a significant portion of IT companies are expanding their data center capacities, driving demand for advanced cooling technologies. The Retail & BFSI sector is also a major consumer of data center cooling solutions, as financial institutions and e-commerce platforms require reliable infrastructure to handle large volumes of transactions and sensitive data. Healthcare is emerging as a fast-growing segment, with hospitals and research institutions increasingly relying on data-intensive applications for patient care and medical research. A government healthcare digitization initiative reported a substantial increase in the adoption of electronic health records, necessitating more robust data center infrastructure. The Energy sector is also seeing increased adoption of data center cooling solutions as utility companies implement smart grid technologies and analyze vast amounts of consumption data to improve efficiency.
Segments
Based on Component
- Solution
- Services
Based on Application
- Telecom & IT
- Retail & BFSI
- Healthcare
- Energy
- Others
Based on Solution
- Air Conditioners
- Precision Air Conditioners
- Chillers
- Air Handling Units
- Others
Based on Containment
- Raised Floor with Containment
- Hot Aisle Containment (HAC)
- Cold Aisle Containment (CAC)
- Raised Floor without Containment
Based on Services
- Installation & Deployment
- Support & Consulting
- Maintenance Services
Based on Cooling Type
- Raised Floor
- Non-Raised Floors
Based on Structure
- Rack-based Cooling
- Row-based Cooling
- Room-based Cooling
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%):
North America dominates the global data center cooling market, accounting for approximately 35% of the total market share in 2023. The presence of hyperscale data centers operated by tech giants like Google, Amazon, and Microsoft fuels growth. For instance, according to a 2023 report by the U.S. Department of Energy, data centers in the country consumed approximately 70 billion kilowatt-hours of electricity, highlighting the need for efficient cooling solutions. The rapid adoption of advanced technologies and stringent environmental regulations are driving demand for energy-efficient and sustainable cooling systems. The region's market leadership is further solidified by ongoing investments in data center infrastructure.
Europe (25%):
Europe holds the second-largest share in the global data center cooling market, with a market share of about 25%. The region's focus on sustainability and energy efficiency is driving adoption of innovative cooling solutions. For instance, a 2023 survey by the European Data Centre Association found that over 75% of European data centers have implemented or plan to implement free cooling technologies within the next two years. The expansion of cloud services and colocation data centers is also boosting demand for efficient cooling technologies. European initiatives like the Climate Neutral Data Centre Pact are further accelerating the shift towards sustainable data center operations.
Key players
- Air Enterprises
- Asetek, Inc.
- Climaveneta
- Coolcentric
- Dell Technologies Inc.
- Fujitsu
- Hitachi, Ltd.
- Johnson Controls
- Mitsubishi Electric Corporation
- Nortek Air Solutions, LLC
- NTT Limited
- Rittal GmBH & Co. KG
- Schneider Electric SE
- STULZ GMBH
- Telx Inc.
Competitive Analysis
The global data center cooling market is highly competitive, with key players focusing on innovation, energy efficiency, and sustainability to maintain a competitive edge. Companies such as Schneider Electric SE, Johnson Controls, and Mitsubishi Electric Corporation are leading the market with their advanced cooling technologies and sustainable solutions. Asetek, Inc. and Coolcentric are pioneers in liquid cooling solutions, offering energy-efficient alternatives to traditional air-based systems. Dell Technologies Inc. and Fujitsu provide integrated solutions, combining IT infrastructure with efficient cooling technologies. Players like Rittal GmBH & Co. KG and STULZ GMBH are renowned for their precision air-conditioning systems. Furthermore, NTT Limited and Telx Inc. are expanding their data center infrastructure, driving the demand for cooling solutions. The intense competition is pushing companies to innovate continually, enhance energy efficiency, and adopt eco-friendly technologies to meet evolving customer needs.
Recent Developments
- In September 2024, Dell announced the upcoming launch of the PowerEdge XE9680L server, featuring direct liquid cooling (DLC) capabilities. This new server is designed to deliver high rack-scale density with DLC, optimizing cold plates for 25% better thermal performance compared to traditional air-cooled servers.
- In June 2024, Johnson Controls launched a new global data center-focused organization called Global Data Center Solutions. This new business aims to leverage integrated solutions and technologies to minimize costs and maximize efficiency for data center customers.
- In September 2024, Schneider Electric inaugurated a new cooling factory in Bengaluru, India. The factory, built with an investment of Rs 100 Crores (~10Mn Euro), will focus on developing innovative cooling solutions to meet the growing demand for data center ecosystems in the country.
- In May 2024, STULZ announced the launch of its innovative CyberCool CMU coolant management and distribution unit (CDU) for maximizing heat exchange efficiency in liquid cooling solutions. The product was showcased at Data Centre World in Frankfurt.
- In July 2024, Johnson Controls and Hitachi confirmed an agreement to sell their European air conditioning joint venture business to German manufacturer Robert Bosch in an $8.1 billion deal. This transaction includes the North America ducted business and global residential joint venture with Hitachi.
Market Concentration and Characteristics
The global data center cooling market is moderately concentrated, with a mix of prominent multinational corporations and regional players competing for market share. Major companies such as Schneider Electric SE, Johnson Controls, Mitsubishi Electric Corporation, and STULZ GMBH dominate the market, driven by their innovative cooling solutions, strong global presence, and extensive research and development efforts. These companies offer a wide range of cooling technologies, including liquid cooling, precision air conditioning, and energy-efficient solutions. However, the market also includes several specialized firms like Asetek, Inc. and Coolcentric, which focus on niche technologies such as liquid immersion cooling. Market characteristics include a growing emphasis on energy efficiency, sustainability, and regulatory compliance, with companies increasingly adopting AI-driven and eco-friendly cooling technologies to meet the demands of hyperscale and colocation data centers. The competitive landscape is evolving as companies focus on innovation, mergers, and strategic partnerships to strengthen their market positions.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Solution, Containment, Services, Cooling Type, Structure and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for hyperscale data centers will continue to rise, driving the need for efficient cooling solutions to manage increased heat loads and ensure optimal performance.
- Liquid cooling technologies, including immersion cooling and direct-to-chip cooling, will gain significant traction as data centers seek more energy-efficient and high-performance cooling systems.
- AI-driven cooling systems will become more widespread, optimizing energy consumption and improving operational efficiency by adjusting cooling parameters in real-time.
- As sustainability becomes a priority, data centers will increasingly adopt eco-friendly cooling systems that minimize energy usage and reduce carbon footprints.
- The proliferation of edge computing will lead to an increase in smaller, distributed data centers, driving demand for compact, modular cooling solutions that can be deployed rapidly.
- The integration of renewable energy sources, such as solar and wind, with data center cooling systems will become more common as operators strive to reduce dependence on traditional power sources.
- Governments worldwide will impose stricter environmental regulations, pushing data center operators to adopt energy-efficient cooling technologies and reduce greenhouse gas emissions.
- Hybrid cooling systems that combine liquid and air cooling will gain popularity as data centers look to balance cost, energy efficiency, and cooling performance.
- Emerging economies, particularly in Asia-Pacific and Latin America, will experience rapid growth in data center infrastructure, driving the demand for advanced cooling technologies in these regions.
- Technological advancements in precision air conditioning and cooling systems will allow data centers to achieve greater control over temperature and humidity, improving server efficiency and longevity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Data Center Capacity Expansion
The rapid growth of hyperscale and colocation data centers, driven by digital transformation and increased data usage, is fueling demand for advanced cooling solutions to manage higher heat loads and ensure reliable operations.
Emphasis on Energy Efficiency and Sustainability
Operators are under pressure to reduce energy consumption and carbon emissions, leading to increased adoption of energy-efficient and eco-friendly cooling technologies that help meet regulatory and corporate sustainability goals.
Technological Advancements in Cooling
Innovations such as liquid cooling, immersion cooling, and AI-driven optimization are enabling more effective thermal management for high-density computing environments, supporting the market's growth.
Proliferation of Cloud Computing, AI, and Big Data
The widespread adoption of cloud services, artificial intelligence, and big data analytics is increasing the computational intensity and heat output of data centers, necessitating more robust and efficient cooling systems.
Regulatory Mandates and Environmental Compliance
Stricter government regulations on energy efficiency and emissions are compelling data center operators to upgrade or replace legacy cooling systems with advanced, compliant technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global data center cooling market in 2023 and itsprojected size by 2032?
What are the main drivers for the growth of the data center cooling market?
What technological advancements are influencing the data center cooling market?
Which regions dominate the data center cooling market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution
- 1.2.1 Air Conditioners
- 1.2.2 Precision Air Conditioners
- 1.2.3 Chillers
- 1.2.4 Air Handling Units
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Solution
- 1.3.2 Services
- 1.4 By Application
- 1.4.1 Telecom & IT
- 1.4.2 Retail & BFSI
- 1.4.3 Healthcare
- 1.4.4 Energy
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 12,839.45 million → 2032: USD 41,861.20 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Center Cooling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Center Cooling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Center Cooling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Center Cooling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Center Cooling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Center Cooling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Center Cooling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Center Cooling Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 12,839.45 million → 2032: USD 41,861.20 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Center Cooling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Air Conditioners
- 12.3.7.2 Precision Air Conditioners
- 12.3.7.3 Chillers
- 12.3.7.4 Air Handling Units
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solution
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Telecom & IT
- 12.5.7.2 Retail & BFSI
- 12.5.7.3 Healthcare
- 12.5.7.4 Energy
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Center Cooling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Center Cooling Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Center Cooling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Center Cooling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson Controls
- 18.4 Mitsubishi Electric Corporation
- 18.5 STULZ GMBH
- 18.6 Asetek, Inc.
- 18.7 Coolcentric
- 18.8 Dell Technologies Inc.
- 18.9 Fujitsu
- 18.10 Rittal GmBH & Co. KG
- 18.11 NTT Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

