
Market Overview:
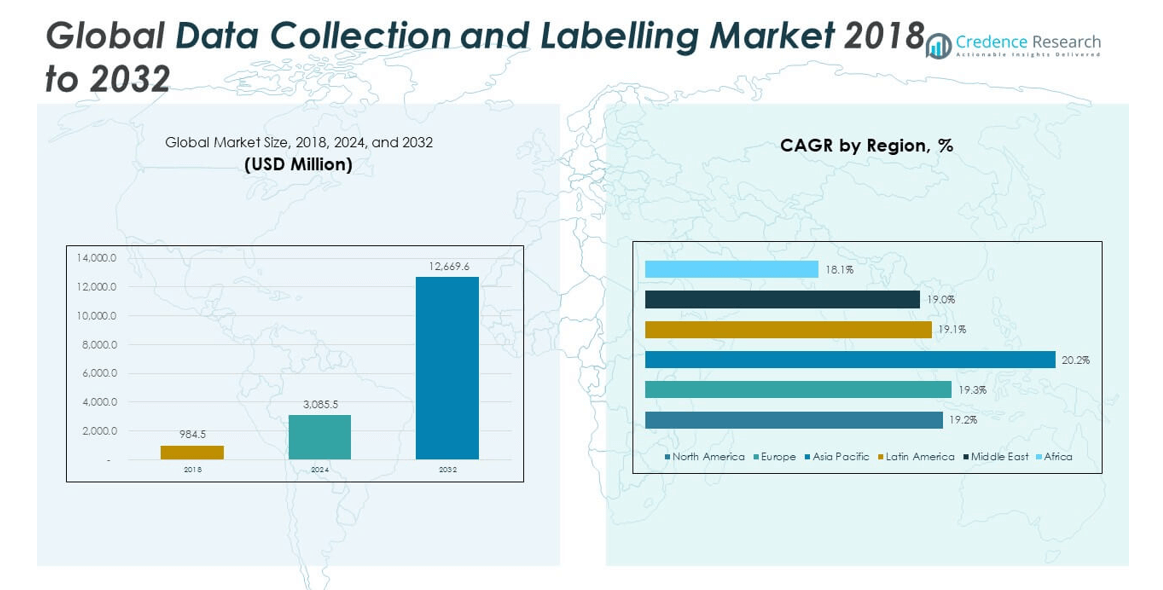
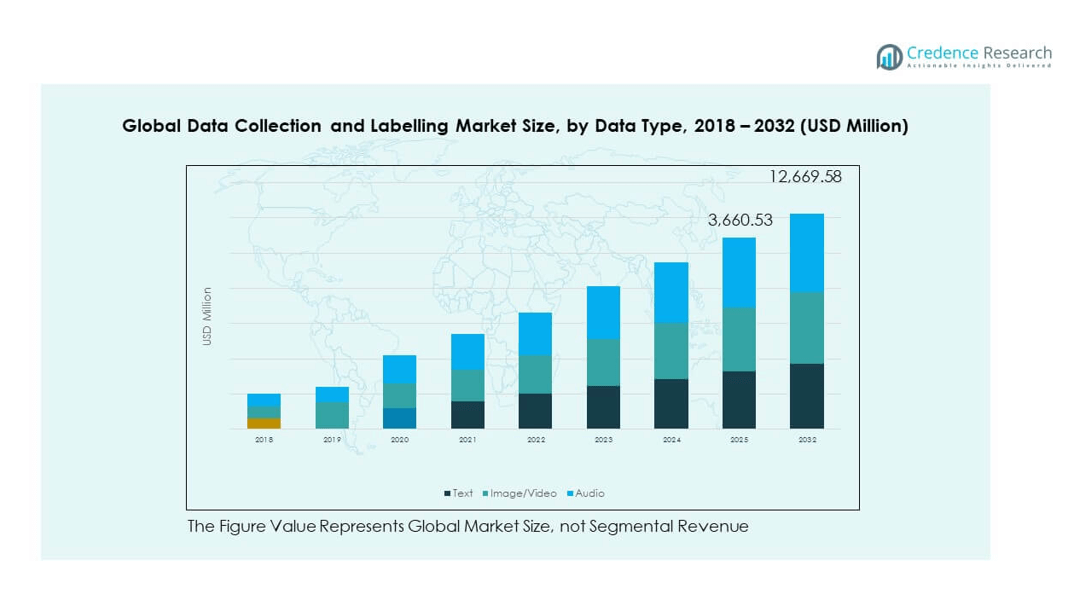
The Global Data Collection and Labeling Market size was valued at USD 984.5 million in 2018 to USD 3,085.5 million in 2024 and is anticipated to reach USD 12,669.6 million by 2032, at a CAGR of 19.41% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Collection and Labeling Market Size 2024 | USD 3,085.5 million |
| Data Collection and Labeling Market, CAGR | 19.41% |
| Data Collection and Labeling Market Size 2032 | USD 12,669.6 million |
The market is experiencing significant growth due to the rising adoption of artificial intelligence, machine learning, and big data analytics across industries. Organizations increasingly require high-quality, accurately labelled datasets to train algorithms, improve model performance, and enhance decision-making processes. Expansion in autonomous vehicles, healthcare diagnostics, retail analytics, and smart devices further fuels demand for reliable Data Collection and Labeling services. The surge in digital transformation initiatives across both developed and emerging economies is accelerating this momentum.
North America holds a leading position in the market due to its advanced AI ecosystem, robust technological infrastructure, and strong presence of key market players. Europe follows closely, driven by stringent data quality standards and growing AI integration in automotive and healthcare sectors. The Asia Pacific region is emerging rapidly, supported by rising investments in AI start-ups, government-backed digital initiatives, and expanding e-commerce operations. Countries like China and India are witnessing accelerated adoption, while the Middle East and Africa are showing gradual but steady market penetration.
Market Insights:
- The Global Data Collection and Labeling Market was valued at USD 3,085.5 million in 2024 and is projected to reach USD 12,669.6 million by 2032, growing at a CAGR of 19.41%.
- Increasing adoption of AI and ML across industries is driving demand for high-quality labelled datasets.
- Autonomous vehicle development is boosting requirements for image, video, and sensor data annotation.
- Data privacy regulations and compliance complexities are restraining market growth in certain regions.
- North America leads the market with strong AI infrastructure and high adoption across sectors.
- Europe benefits from robust regulatory frameworks and advanced integration in healthcare and automotive industries.
- Asia Pacific is the fastest-growing region, supported by government-backed AI initiatives and expanding e-commerce.
Market Drivers
Expanding Integration of Artificial Intelligence and Machine Learning Across Industries
The Global Data Collection and Labeling Market is witnessing strong growth due to the widespread adoption of artificial intelligence (AI) and machine learning (ML) across multiple industries. It is essential for AI and ML models to process large volumes of high-quality labelled data to deliver accurate predictions and outcomes. Businesses in healthcare, automotive, finance, and retail are investing heavily in structured datasets to train algorithms effectively. Autonomous vehicles rely on image, video, and sensor data labelling to improve navigation and safety features. In healthcare, annotated medical images and patient data enable precision diagnostics and treatment planning. The surge in big data analytics requires reliable datasets to generate actionable insights. Companies are prioritizing data accuracy and standardization to maintain model efficiency and compliance with regulations.
- For example, Scale AI has provided data annotation support for autonomous vehicle projects, including work on Waymo’s datasets to improve navigation algorithms and safety features. iMerit delivers medical image annotation services for hospital networks, supporting AI-powered precision diagnostics in radiology.
Rising Demand for High-Quality Training Data in Autonomous Systems
Autonomous technologies, including self-driving cars, drones, and robotics, are driving demand in the Global Data Collection and Labeling Market. It is vital for these systems to process vast datasets that include images, videos, lidar scans, and real-time sensor inputs. Data labelling plays a key role in enabling object detection, path prediction, and decision-making capabilities. Automotive leaders are partnering with data service providers to ensure AI models operate in diverse weather and traffic conditions. Robotics in manufacturing requires annotated data to enhance precision and safety in complex environments. Smart transportation systems depend on labelled data for improved traffic management and predictive maintenance. The expanding use of intelligent automation in both industrial and consumer sectors continues to boost market growth.
- For instance, Tesla leverages data from its global fleet, which has logged over 482 million kilometers using the Full Self-Driving (FSD) system, to train and refine its autonomous driving capabilities. Onboard cameras capture high-resolution video and image inputs at rates of up to 50 Hz, generating vast volumes of real-world data. This information is uploaded to Tesla’s servers, where it is processed to improve neural network accuracy, optimize perception models, and enhance decision-making for complex driving scenarios.
Accelerating Adoption of Data-Driven Decision-Making in Enterprises
Enterprises are increasingly relying on structured datasets for strategic decision-making, fueling the Global Data Collection and Labeling Market. It is necessary for organizations to harness reliable data to forecast trends, optimize operations, and enhance customer engagement. Retailers utilize labelled purchase data to develop personalized marketing campaigns and improve inventory planning. Financial institutions apply labelled transaction records for fraud detection and risk assessment. In manufacturing, annotated production data improves quality control and predictive maintenance. Cloud-based platforms have simplified large-scale data processing and storage, enabling faster deployment of AI-powered analytics. The demand for accurate data annotation services grows as more industries embed AI-driven insights into their operations.
Expanding Role of Digital Transformation and IoT in Data Generation
The rapid growth of digital transformation and Internet of Things (IoT) devices is a key driver for the Global Data Collection and Labeling Market. It is estimated that billions of connected devices generate massive streams of raw data that require structured labelling for effective utilization. Smart cities rely on labelled data from sensors to manage utilities, traffic, and public safety efficiently. In logistics, IoT-enabled asset tracking systems use annotated datasets to optimize routes and reduce delays. Wearable devices produce health and activity data that is labelled for preventive care analytics. E-commerce platforms depend on labelled customer interaction data to refine product recommendations. The expansion of IoT ecosystems across industrial, commercial, and consumer sectors is significantly increasing the volume of data that requires accurate labelling.
Market Trends
Growing Use of Synthetic Data for Enhanced Model Training
The Global Data Collection and Labeling Market is experiencing a shift toward the use of synthetic data to supplement real-world datasets. It is becoming increasingly valuable for training AI models where real data is scarce or privacy-sensitive. Synthetic datasets enable safe experimentation without exposing confidential information. Industries such as healthcare and autonomous driving benefit from this approach by simulating rare scenarios for robust model training. Advanced generative AI tools produce realistic images, text, and sensor data that can be annotated for various applications. This trend reduces dependency on costly manual data collection processes. Businesses are integrating synthetic datasets alongside traditional labelling to achieve higher accuracy and scalability in AI models.
- For example, Waymo has driven over 20 billion miles in simulation, constructing virtual scenarios to test challenging situations that would be difficult or unsafe to replicate in the real world. These simulations include “fuzzing” techniques to subtly modify environments and generate rare or hazardous events that enrich training data.
Increasing Demand for Multi-Modal Data Annotation Services
The rising complexity of AI applications is creating demand for multi-modal data annotation in the Global Data Collection and Labeling Market. It is essential for models to process and correlate different data formats, including images, audio, video, text, and sensor inputs. Autonomous vehicles require synchronized labelling of camera feeds, radar scans, and GPS data for accurate navigation. Virtual assistants depend on combining voice recognition with contextual visual data for improved responses. E-commerce platforms leverage multi-modal datasets to enhance visual search and recommendation systems. This approach allows AI to understand and interpret cross-referenced information in real time. The integration of multi-modal labelling is enhancing model intelligence and expanding its applicability across industries.
Expansion of Cloud-Based Data Labelling Platforms
Cloud-based platforms are emerging as a transformative trend in the Global Data Collection and Labeling Market. It is enabling enterprises to scale their data annotation processes with greater speed and efficiency. Cloud solutions provide secure collaboration environments where geographically dispersed teams can work on datasets simultaneously. AI-driven automation integrated into cloud systems accelerates the annotation process while reducing errors. This model supports continuous updates, making it ideal for projects requiring frequent retraining of AI models. Industries benefit from lower infrastructure costs and faster project turnaround times. The flexibility of cloud-based platforms is fostering widespread adoption across sectors seeking agile data processing solutions.
- For example, Labelbox offers a cloud-based data annotation platform that supports large-scale AI data pipeline workflows, enabling distributed teams to collaborate on labelling projects in real time across multiple industries.
Adoption of Advanced Quality Control Mechanisms in Data Annotation
Quality assurance is becoming a strategic focus in the Global Data Collection and Labeling Market as organizations demand precise and consistent datasets. It is prompting service providers to deploy advanced quality control measures such as consensus-based labelling, automated validation tools, and expert review cycles. Industries with high compliance requirements, such as healthcare and finance, are prioritizing error-free data annotation to avoid regulatory risks. AI-assisted quality monitoring tools can detect inconsistencies and flag anomalies in real time. This trend ensures that datasets meet the accuracy thresholds required for mission-critical AI applications. Continuous improvement in quality control is enhancing trust and reliability in labelled datasets across the market.
Market Challenges Analysis
Managing Data Privacy and Compliance Across Diverse Jurisdictions
The Global Data Collection and Labeling Market faces significant challenges in ensuring compliance with varying data protection regulations worldwide. It is critical for organizations to navigate complex legal frameworks, such as GDPR in Europe, CCPA in the U.S., and evolving privacy laws in Asia-Pacific. Collecting and labelling personal or sensitive information requires stringent security measures and ethical practices. Any breach or misuse can lead to legal penalties and reputational damage. Cross-border data transfers present additional compliance complexities, demanding strict adherence to encryption and anonymization protocols. Balancing data utility with privacy preservation remains a major operational challenge for market participants.
Addressing Labour-Intensive Processes and Rising Operational Costs
High-quality data labelling often relies on extensive human input, creating cost and scalability challenges for the Global Data Collection and Labeling Market. It is resource-intensive to manually annotate large datasets, especially for complex image, video, or medical data. While automation tools are evolving, they still require human oversight for nuanced tasks that machines struggle to interpret accurately. Fluctuating demand in AI projects can strain staffing and training resources. Maintaining consistent accuracy across large annotation teams is difficult without robust quality control frameworks. These operational pressures can slow project timelines and increase overall service costs for enterprises.
Market Opportunities
Leveraging Emerging Markets for AI-Driven Data Services
Emerging economies are creating new growth avenues for the Global Data Collection and Labeling Market as digital transformation accelerates. It is providing opportunities for service providers to tap into expanding AI adoption in sectors like e-commerce, healthcare, and transportation. Government initiatives in countries such as India, Brazil, and Indonesia are promoting AI research and innovation. Local talent pools and lower operational costs make these regions attractive for setting up data labelling operations. Partnering with regional tech firms can enhance market reach and localization capabilities. The growing number of start-ups in these economies is further expanding the demand for labelled datasets.
Expanding Opportunities in Specialized Industry Applications
Industry-specific AI applications are opening lucrative opportunities for the Global Data Collection and Labeling Market. It is witnessing increased demand from niche sectors such as precision agriculture, environmental monitoring, and industrial automation. In agriculture, annotated drone imagery supports crop health analysis and yield prediction. Environmental agencies require labelled satellite images for tracking deforestation and climate change impacts. Industrial IoT platforms rely on annotated sensor data for predictive maintenance and process optimization. These specialized use cases offer high-value contracts for service providers capable of delivering domain-specific labelling expertise.
Market Segmentation Analysis:
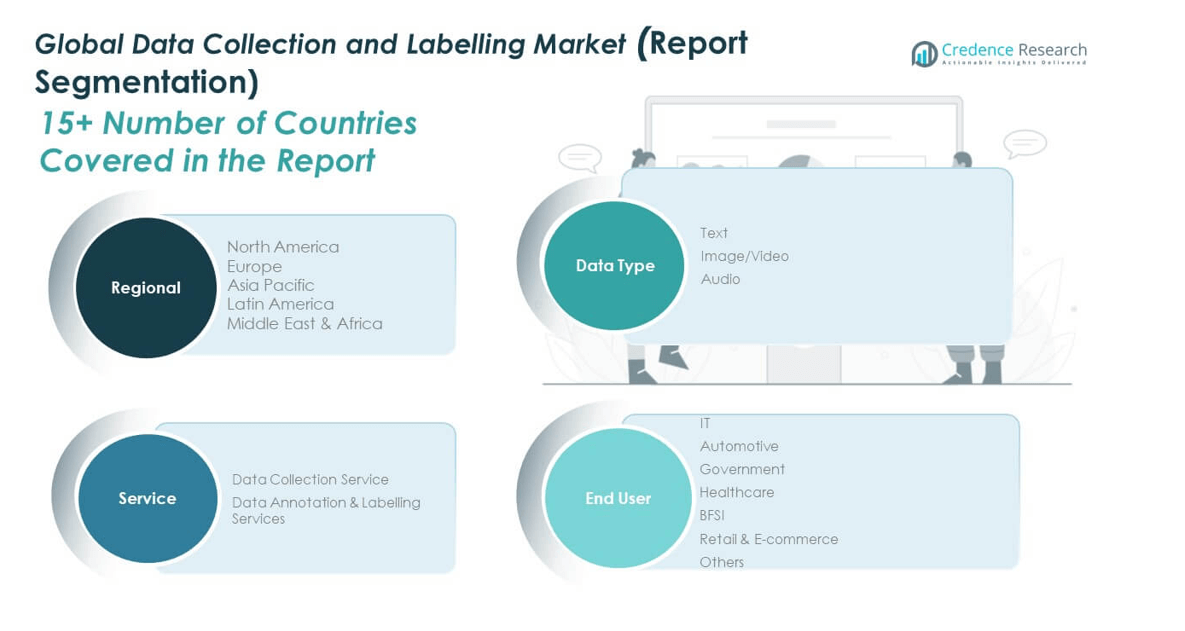
The Global Data Collection and Labeling Market is segmented
By data type into text, image/video, and audio. Text data remains a core category due to its extensive use in natural language processing, sentiment analysis, and document classification. Image and video data is experiencing strong growth with the rising demand for computer vision applications in autonomous vehicles, surveillance, and retail analytics. Audio data is gaining traction in voice recognition, virtual assistants, and transcription services, supported by advancements in speech-to-text technologies. Each data type plays a vital role in enabling AI systems to interpret and respond accurately across multiple use cases.
By service, the market is divided into data collection services and data annotation & labelling services. Data collection services focus on sourcing structured and unstructured datasets from varied environments, ensuring diversity and relevance for AI model training. Data annotation and labelling services provide the critical step of tagging and categorizing this data to enhance its usability for machine learning algorithms. Both services are integral to delivering reliable datasets that meet industry-specific requirements and accuracy standards.
- For example, Appen operates a global workforce of over 1 million contributors across more than 170 countries, collecting and annotating text, image, audio, and video data to support AI development for major technology clients, including Microsoft.
By end user, the market includes IT, automotive, government, healthcare, BFSI, retail & e-commerce, and others. The IT sector drives demand for large-scale labelled datasets to support AI and analytics solutions. Automotive applications, particularly in autonomous driving, require high-precision labelled sensor and visual data. Government agencies use labelled datasets for security, surveillance, and administrative automation. Healthcare leverages annotated medical images for diagnostics, while BFSI applies data labelling in fraud detection and risk modelling. Retail & e-commerce uses labelled consumer data for personalization and product recommendation systems.
- For example, JPMorgan Chase employs AI-driven systems that analyze transaction data in real time to detect and prevent fraud. These systems examine millions of daily transactions, applying behavioral analytics and anomaly detection to flag suspicious activity swiftly.
Segmentation:
By Data Type
- Text
- Image/Video
- Audio
By Service
- Data Collection Service
- Data Annotation & Labelling Services
By End User
- IT
- Automotive
- Government
- Healthcare
- BFSI
- Retail & E-commerce
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Regional Analysis:
North America
The North America Global Data Collection and Labeling Market size was valued at USD 252.72 million in 2018 to USD 783.19 million in 2024 and is anticipated to reach USD 3,167.39 million by 2032, at a CAGR of 19.2% during the forecast period. It accounts for 25.38% of the 2024 global market share. The region maintains a leading position due to its advanced AI infrastructure, strong investment in machine learning projects, and high adoption rates across industries. The presence of major technology companies accelerates innovation in data collection and annotation solutions. The automotive sector, driven by autonomous vehicle development, remains a significant contributor to demand. Healthcare organizations utilize annotated datasets for medical imaging, diagnostics, and predictive analytics. BFSI institutions rely on labelled data for fraud detection and regulatory compliance. The robust start-up ecosystem and government funding programs further enhance the market's competitive strength.
Europe
The Europe Global Data Collection and Labeling Market size was valued at USD 330.39 million in 2018 to USD 1,028.09 million in 2024 and is anticipated to reach USD 4,180.96 million by 2032, at a CAGR of 19.3% during the forecast period. It holds 33.33% of the 2024 global market share. Strong regulatory frameworks, including GDPR, drive demand for compliant and high-quality data labelling services. The automotive industry in Germany, France, and the UK invests heavily in AI-powered vision systems. Healthcare applications benefit from Europe’s emphasis on precision medicine and medical research. Retail and e-commerce sectors deploy labelled datasets for personalization and inventory optimization. Financial services companies utilize structured datasets for advanced analytics and risk modelling. Strategic collaborations between research institutions and private enterprises strengthen the innovation pipeline. Government-backed AI initiatives also contribute to market expansion.
Asia Pacific
The Asia Pacific Global Data Collection and Labeling Market size was valued at USD 221.02 million in 2018 to USD 722.05 million in 2024 and is anticipated to reach USD 3,125.58 million by 2032, at a CAGR of 20.2% during the forecast period. It captures 23.40% of the 2024 global market share. Rapid digitalization, expanding e-commerce operations, and significant AI investments fuel regional growth. China, Japan, and India lead adoption across automotive, healthcare, and IT industries. Governments are funding AI innovation, fostering local data labelling enterprises. The gaming and entertainment sectors generate rising demand for annotated visual and audio datasets. Outsourcing capabilities in countries such as India and the Philippines make the region a cost-effective hub for data services. Increasing smartphone penetration and IoT adoption generate vast volumes of data requiring annotation. The competitive landscape is diverse, ranging from global providers to emerging regional specialists.
Latin America
The Latin America Global Data Collection and Labeling Market size was valued at USD 100.52 million in 2018 to USD 310.00 million in 2024 and is anticipated to reach USD 1,245.42 million by 2032, at a CAGR of 19.1% during the forecast period. It accounts for 10.05% of the 2024 global market share. The market is gaining momentum with the rise of AI applications in retail, financial services, and logistics. Brazil and Mexico are leading adoption, supported by growing tech start-ups and innovation hubs. Retail and e-commerce companies leverage labelled consumer data for targeted marketing. The automotive sector invests in AI-driven quality control and predictive maintenance systems. Healthcare systems use annotated medical data for diagnostics and telemedicine platforms. The region benefits from a skilled workforce and competitive outsourcing costs. Increasing collaboration with North American technology companies is accelerating capability development.
Middle East
The Middle East Global Data Collection and Labeling Market size was valued at USD 56.90 million in 2018 to USD 174.64 million in 2024 and is anticipated to reach USD 696.83 million by 2032, at a CAGR of 19.0% during the forecast period. It represents 5.66% of the 2024 global market share. The region is witnessing increased adoption of AI in sectors such as oil and gas, smart cities, and public administration. The UAE and Saudi Arabia are at the forefront, implementing national AI strategies. Retail and financial services sectors utilize labelled datasets for customer engagement and fraud prevention. Healthcare providers adopt annotated imaging data to improve diagnostics. Smart city projects generate demand for real-time labelled sensor and video data. Partnerships with global technology firms are enhancing local expertise. Investments in AI-focused education and training programs are building a skilled workforce for data services.
Africa
The Africa Global Data Collection and Labeling Market size was valued at USD 22.94 million in 2018 to USD 67.53 million in 2024 and is anticipated to reach USD 253.39 million by 2032, at a CAGR of 18.1% during the forecast period. It holds 2.19% of the 2024 global market share. The market is at an early growth stage but shows potential with rising digital adoption and AI-focused initiatives. South Africa leads the region, followed by Nigeria and Kenya, in implementing AI for finance, healthcare, and agriculture. E-commerce platforms are leveraging labelled datasets for customer personalization. Agricultural applications use annotated drone and satellite imagery for crop monitoring. Healthcare organizations integrate labelled medical data for telemedicine services. Limited infrastructure and high operational costs present challenges. International partnerships and donor-backed technology projects are playing a key role in market development.
Key Player Analysis:
- Scale AI
- Reality AI
- Labelbox, Inc.
- Dobility Inc.
- Telcus International
- Globalme Localization Inc.
- Trilldata Technologies PVT LTD.
- Appen Limited
- iMerit
- SuperAnnotate
- Other Key Players
Competitive Analysis:
The Global Data Collection and Labeling Market is highly competitive, with a mix of established technology firms, specialized service providers, and emerging start-ups. It is driven by continuous innovation in AI-powered annotation tools, automation capabilities, and quality control processes. Key players such as Scale AI, Appen Limited, Labelbox, iMerit, and SuperAnnotate are expanding service portfolios to cater to diverse industry needs, including automotive, healthcare, and retail. Strategic alliances, mergers, and acquisitions are common to strengthen geographic presence and technological expertise. Companies focus on domain-specific labelling solutions to enhance value propositions and secure long-term contracts with enterprise clients. Investment in scalable cloud-based platforms and AI-assisted workflows remains a critical growth strategy.
Recent Developments:
- In June 2025, TELUS Corporation announced a proposal to acquire all outstanding shares of TELUS Digital at a 15% premium over the previous day's closing price. This acquisition, if finalized, will drive further operational integration between TELUS and its digital unit, enabling greater transformation and efficiency across sectors such as telecommunications, health, agriculture, and consumer goods.
- In June 2025, Scale AI attracted a $14.3 billion investment from Meta, with Meta acquiring a 49% stake in Scale AI. As part of this agreement, Scale AI’s CEO Alexandr Wang is joining Meta to lead its new Superintelligence lab, while Scale’s chief strategy officer, Jason Droege, steps in as interim CEO. The partnership is aimed at enhancing Meta’s AI capabilities and advancing joint data-generation projects for artificial intelligence models.
- In June 2024, iMerit also released a 3D Multi-Sensor Fusion Tool that enables the precise annotation of Lidar, radar, and camera data for multi-modal AI applications such as autonomous vehicles. iMerit continues to expand its ecosystem, partnering with industry leaders like Labelbox and AWS to offer scalable annotation services, and recently inaugurated an Automotive AI Center of Excellence in Coimbatore in June 2025.
- In April 2025, Telus International (TELUS Digital Experience) announced a strategic collaboration with Zendesk to integrate TELUS’ global customer experience (CX) talent and generative AI platform Fuel iX™ into Zendesk’s CRM and call-center-as-a-service solutions.
Market Concentration & Characteristics:
The Global Data Collection and Labeling Market exhibits moderate to high concentration, with a few dominant players holding significant market share alongside numerous regional specialists. It is characterized by high entry barriers due to the technical expertise, infrastructure, and quality standards required for competitive service delivery. Demand is fueled by the integration of AI across industries, creating opportunities for both large-scale providers and niche firms offering specialized data annotation. Continuous innovation, compliance with data privacy regulations, and adaptability to evolving AI models define market success. Strategic differentiation often stems from domain expertise, automation efficiency, and the ability to handle large, complex datasets with accuracy.
Report Coverage:
The research report offers an in-depth analysis based on Data Type, Service and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of AI and machine learning adoption will increase demand for high-quality labelled datasets across industries.
- Growth in autonomous vehicle development will boost requirements for image, video, and sensor data annotation.
- Rising healthcare digitization will drive usage of annotated medical data for diagnostics and treatment planning.
- Advancements in cloud-based platforms will enable scalable, faster, and cost-efficient labelling processes.
- Increased integration of multi-modal data annotation will enhance AI model accuracy and versatility.
- Strategic collaborations between global and regional players will accelerate service innovation and market reach.
- Adoption of synthetic data generation will complement real-world datasets for model training.
- Expansion of AI applications in retail and e-commerce will heighten demand for personalized data labelling.
- Growing compliance needs will push service providers to strengthen privacy and data governance frameworks.
- Emerging economies will present new outsourcing and growth opportunities for service providers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Integration of AI and ML Across Industries
The widespread adoption of artificial intelligence and machine learning in sectors such as healthcare, automotive, finance, and retail is driving the need for large volumes of high-quality labelled data to train and optimize algorithms, directly fueling demand for data collection and labeling services.
Rising Demand for High-Quality Training Data in Autonomous Systems
Growth in autonomous vehicles, drones, and robotics requires extensive image, video, and sensor data annotation to enable object detection, navigation, and decision-making, making precise data labeling essential for safe and effective deployment.
Accelerating Adoption of Data-Driven Decision-Making in Enterprises
Organizations across industries are increasingly leveraging structured and annotated datasets to forecast trends, optimize operations, and enhance customer engagement, which boosts the need for reliable data collection and labeling solutions.
Expanding Role of Digital Transformation and IoT in Data Generation
The proliferation of IoT devices and digital transformation initiatives is generating massive streams of raw data that require structured labeling for effective use in smart cities, logistics, healthcare, and e-commerce, expanding the market for annotation services.
Adoption of Advanced Quality Control and Compliance Mechanisms
Stringent data privacy regulations and the need for error-free, compliant datasets - especially in regulated industries like healthcare and finance - are driving investment in advanced quality control and secure data labeling processes, increasing market demand for specialized providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Data Collection and Labelling Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Data Collection and Labelling Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Global Data Collection and Labelling Market?
Who are the leading companies in the Global Data Collection and Labelling Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Data Collection Service
- 1.2.2 Data Annotation & Labelling Services
- 1.3 By End User
- 1.3.1 IT
- 1.3.2 Automotive
- 1.3.3 Government
- 1.3.4 Healthcare
- 1.3.5 BFSI
- 1.3.6 Retail & E-commerce
- 1.3.7 Others
- 1.4 By Data Type
- 1.4.1 Text
- 1.4.2 Image/Video
- 1.4.3 Audio
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,085.5 million → 2032: USD 12,669.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Collection and Labeling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Collection and Labeling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Collection and Labeling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Collection and Labeling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Collection and Labeling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Collection and Labeling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Collection and Labeling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Collection and Labeling Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,085.5 million → 2032: USD 12,669.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Collection and Labeling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Data Collection Service
- 12.3.7.2 Data Annotation & Labelling Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IT
- 12.4.7.2 Automotive
- 12.4.7.3 Government
- 12.4.7.4 Healthcare
- 12.4.7.5 BFSI
- 12.4.7.6 Retail & E-commerce
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Data Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Text
- 12.5.7.2 Image/Video
- 12.5.7.3 Audio
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Collection and Labeling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Collection and Labeling Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Collection and Labeling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Collection and Labeling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Scale AI
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Appen Limited
- 18.4 Labelbox, Inc.
- 18.5 iMerit
- 18.6 SuperAnnotate
- 18.7 Telus International
- 18.8 Reality AI
- 18.9 Dobility Inc.
- 18.10 Globalme Localization Inc.
- 18.11 Trilldata Technologies PVT LTD.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

