
Dental CAD/CAM Market Overview:
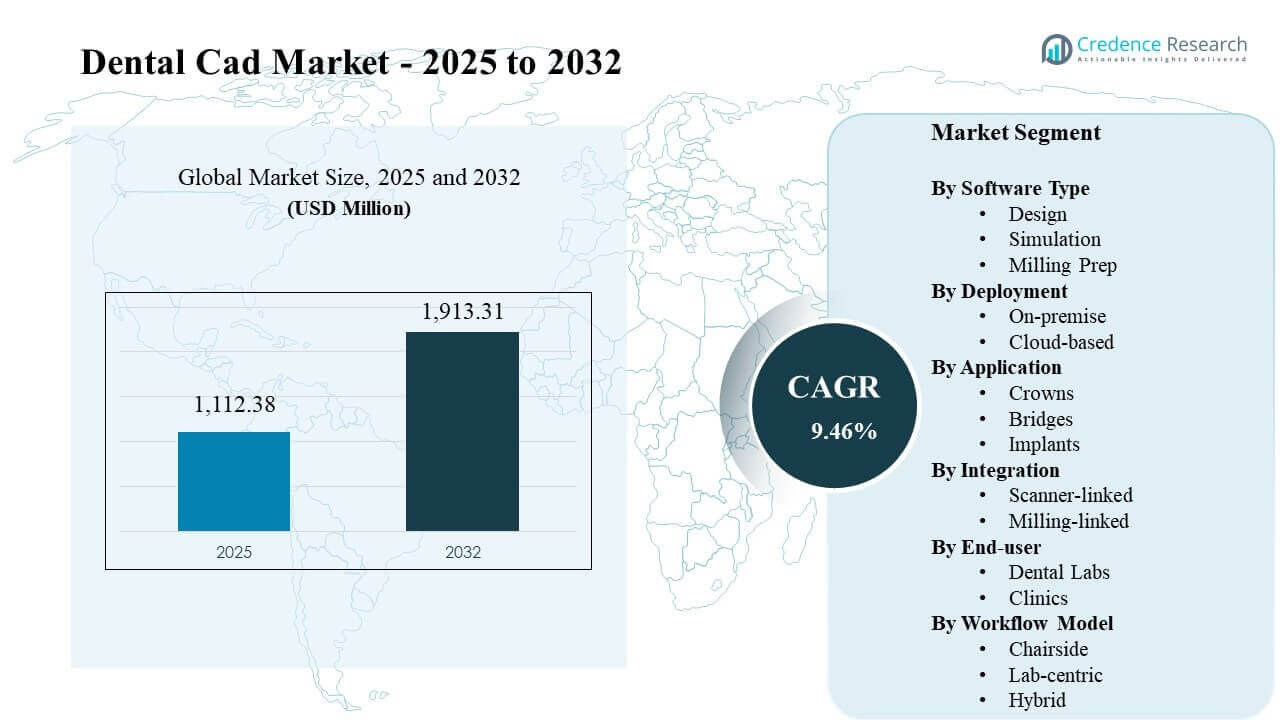
The global Dental CAD/CAM Market size was estimated at USD 1,112.38 million in 2025 and is expected to reach USD 1,913.31 million by 2032, growing at a CAGR of 9.46% from 2025 to 2032. Growth is primarily driven by faster adoption of end-to-end digital dentistry workflows that reduce turnaround time and improve restoration consistency across clinics and labs. Dental service organizations and multi-site lab networks are accelerating standardization of scan-to-design-to-fabrication processes, supporting recurring software usage and upgrades. North America remains the largest contributor as practices continue investing in chairside and lab-based digital systems.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Dental CAD/CAM Market Size 2025 | USD 1,112.38 million |
| Dental CAD/CAM Market, CAGR | 9.46% |
| Dental CAD/CAM Market Size 2032 | USD 1,913.31 million |
Key Market Trends & Insights
- The Dental CAD/CAM Market is projected to expand from USD 1,112.38 million in 2025 to USD 1,913.31 million by 2032 at a 9.46% CAGR (2025–2032).
- North America accounted for 40.90% of 2025 revenue, supported by high penetration of digital restorative workflows.
- Europe represented 31.80% of 2025 revenue, reflecting strong lab capabilities and steady clinic digitization.
- Asia Pacific captured 19.60% of 2025 revenue, supported by expanding private dental care and rising digital dentistry adoption.
- Dental Labs led the end-user mix with a 53.40% share in 2025, reinforcing the role of centralized design throughput in market demand.
Segment Analysis
Dental CAD/CAM demand is strongly tied to productivity, repeatability, and collaboration across clinics and labs. Design-centric workflows remain the core value proposition because restorative and implant cases rely on accurate margins, contacts, occlusion, and library-based components. Vendors are prioritizing usability improvements and guided workflows to help reduce case setup time and limit remakes, especially as more clinics adopt digital impressions and outsource fabrication.
Deployment preferences are evolving as distributed teams collaborate across locations and require consistent version control. Cloud-based enablement supports centralized updates and remote case management, which can be attractive for multi-site providers and labs that coordinate with multiple clinics. At the same time, many production environments continue to value predictable performance and local control, keeping on-premise installations relevant for certain high-throughput operations.
Integration choices typically follow how organizations standardize scan capture and fabrication. Scanner-linked ecosystems simplify the scan-to-design handoff and reduce file management complexity, especially for clinic-driven cases. Milling-linked integration is pulled by the need to align restoration geometry with machine constraints, materials, and toolpaths, helping reduce finishing labor and chairside adjustment time.
By Software Type Insights
Design software remains the anchor of dental CAD/CAM usage because restoration accuracy depends on repeatable margin detection, contact management, and occlusal control. Libraries and guided workflows improve technician productivity and support consistent outputs across teams. Simulation capabilities are gaining importance where implant and occlusal planning requires more advanced visualization and functional checks. Milling preparation features benefit from tighter alignment with CAM constraints, helping reduce rework and improve first-pass success.
By Deployment Insights
On-premise deployment continues to appeal to production-heavy environments that value predictable performance, local control, and continuity during connectivity disruptions. Cloud-based deployment is increasingly attractive for organizations that need remote collaboration, rapid updates, and simplified IT administration across multiple sites. Licensing flexibility and access control matter as labs and clinics scale. Security, governance, and integration with existing practice and lab systems remain key decision factors for deployment selection.
By Application Insights
Crowns represent the most standardized CAD/CAM workflow in everyday restorative dentistry, supported by mature libraries and predictable design steps. Bridges add complexity around multi-unit contacts and anatomical constraints, increasing the value of automation and guided design. Implants drive demand for planning tools, component libraries, and anatomy-aware workflows that improve accuracy and reduce chairside adjustment. Application growth is reinforced by patient expectations for faster turnaround times and improved aesthetics.
By Integration Insights
Scanner-linked integration supports streamlined case intake by reducing manual file handling and minimizing scan-to-design friction. This approach also helps clinics and labs maintain consistent data formats and reduces training burden across teams. Milling-linked integration strengthens manufacturing consistency by aligning design decisions with machine and material constraints earlier in the workflow. Open interoperability remains important for labs that operate mixed fleets and serve multiple clinic ecosystems.
By End-user Insights
Dental Labs accounted for the largest share of 53.40% in 2025. Dental labs lead because centralized design teams can process higher case volumes, apply standardized quality controls, and manage complex multi-unit and esthetic cases. Dental labs also benefit from module-based scaling, allowing adoption of specialized design tools as demand grows. Dental clinics increasingly adopt CAD/CAM capabilities for speed and patient experience, but many clinics still rely on labs for fabrication efficiency and complex case handling.
By Workflow Model Insights
Lab-centric accounted for the largest share of 52.60% in 2025. Lab-centric workflows lead because labs can batch production, maintain specialized expertise, and optimize design-to-fabrication handoffs for consistent outcomes. Lab-centric models also fit multi-clinic networks that outsource fabrication while keeping clinical capture digital. Chairside workflows are expanding where same-day dentistry is a priority and integrated ecosystems simplify training. Hybrid workflows are rising as clinics digitize capture and planning while leveraging labs for fabrication and finishing.
Dental CAD/CAM Market Drivers
Digital restorative adoption accelerates software utilization
Growth is supported by broader adoption of digital impressions and standardized restorative workflows across clinics and lab networks. Dental CAD/CAM software reduces manual design steps, improves repeatability, and helps teams manage more cases with fewer remakes. Design libraries and guided workflows shorten onboarding time for new technicians and support consistent outcomes. Integration across scanning, design, and fabrication reduces case friction and speeds turnaround, reinforcing recurring software demand across high-volume environments.
Demand for faster turnaround and patient experience improvements
Same-day and short-cycle dentistry models prioritize fast design and fabrication paths, increasing reliance on efficient CAD/CAM workflows. Dental CAD/CAM supports predictable design steps for crowns and other restorations, improving delivery speed and reducing chairside adjustments. Faster turnaround improves patient satisfaction and supports higher chair utilization for clinics. For lab partners, faster case throughput strengthens service-level performance and encourages investment in advanced modules and workflow optimization.
- For instance, Dentsply Sirona reports that CEREC Primemill can dry-mill a zirconia crown in about 5 minutes, while CEREC SpeedFire can sinter selected restorations in around 14 minutes, enabling same-day restorative workflows.
Expansion of implant and complex case workflows
Implant restorations and complex cases raise design complexity, increasing the value of specialized CAD/CAM tools and component libraries. Guided workflows reduce error rates and help teams maintain consistent fits across components and materials. As implant procedures expand, demand grows for planning-friendly design tools that support anatomy-aware decisions and predictable restoration outcomes. Complex case requirements also favor labs with specialized teams, strengthening lab-centric CAD/CAM demand.
- For instance, 3Shape states that Implant Studio works with implant libraries from more than 100 manufacturers, allowing clinicians and labs to plan implant positions and design surgical guides within one connected digital workflow.
Integration and interoperability shape purchasing decisions
Organizations increasingly select software based on ecosystem fit, including scanner compatibility, fabrication support, and file-handling simplicity. Scanner-linked workflows reduce operational complexity for clinics and improve collaboration with labs. Milling-linked integration supports manufacturing quality by aligning geometry with machine constraints and materials. Interoperability reduces vendor lock-in risk for labs running mixed fleets. These factors encourage upgrades and module adoption as ecosystems mature.
Dental CAD/CAM Market Challenges
Dental CAD/CAM adoption faces workflow and training barriers when clinics and labs shift from conventional processes to digital production. Skills gaps can slow onboarding and reduce early productivity, especially for complex design modules. Integration complexity across scanners, materials, mills, and printers can introduce compatibility issues and create process variability. Data management, governance, and IT support requirements can also challenge smaller providers without dedicated technical resources.
- For instance, Dentsply Sirona states that its Primescan platform can capture an entire upper jaw in well under 30 seconds and a full jaw in less than 1 minute while generating more than 1 million 3D points per second, illustrating how advanced digital systems can deliver high throughput but still require strong operator training and disciplined workflow control to achieve consistent outcomes.
Pricing sensitivity and procurement fragmentation can constrain upgrades, particularly for smaller clinics and independent labs. Software licensing complexity and module-based add-ons may increase total cost perceptions if outcomes are not clearly measured. Change management remains a recurring obstacle when teams must alter long-standing processes and quality checks. Inconsistent digital inputs from different scanners and operators can also drive remakes, limiting realized efficiency gains.
Dental CAD/CAM Market Trends and Opportunities
AI-assisted design and automation are becoming more visible across dental CAD/CAM workflows, targeting faster case setup and improved consistency. Automation opportunities are strongest in repetitive restorative tasks where guided steps reduce variability. Vendors are also improving user experience to shorten training time and boost productivity for new users. As automation improves, organizations can scale case volumes without proportionally increasing design staffing, strengthening the return on workflow standardization.
- For instance, 3Shape reports that in a documented case study, a clinician used 3Shape Automate and Dental System to design and order 6 crowns in only 5 minutes, with the full prepare-design-print-place workflow completed in just over 2 hours, illustrating how AI-supported automation can compress repetitive restorative design time while supporting higher case throughput.
Cloud-enabled collaboration is expanding as clinics and labs operate multi-site networks and require centralized updates and access control. Cloud workflows can support remote case review, faster handoffs, and standardized design protocols across teams. Hybrid IT strategies are creating opportunities for flexible licensing and deployment options that match different operating environments. Vendors that simplify integrations and support mixed ecosystems can capture share as labs diversify equipment and materials.
Regional Insights
North America
North America accounted for 40.90% of 2025 revenue, supported by high adoption of digital restorative workflows and strong purchasing power across clinics and lab networks. Dental service organizations encourage standardized scan-to-design protocols that increase CAD/CAM utilization. A mature ecosystem of scanners, mills, materials, and trained technicians supports faster rollouts of new modules. Vendor competition is intense, pushing usability improvements and stronger integrations that reduce remakes and improve throughput.
Europe
Europe represented 31.80% of 2025 revenue, reflecting a robust dental lab base and steady clinic digitization. Labs play a central role in complex restorative and esthetic cases, sustaining demand for advanced design tools and workflow modules. Cross-border production and multi-country lab operations increase the need for consistent software standards and version control. Procurement decisions often emphasize reliability, interoperability, and training support to maintain predictable outcomes across diverse equipment fleets.
Asia Pacific
Asia Pacific held 19.60% of 2025 revenue, supported by expanding private dental care, rising digital dentistry penetration, and growing lab capacity. Urban clinic networks are adopting digital impression workflows that increase CAD/CAM case flow to labs. Competitive differentiation in premium restorative services supports investment in modern design tools and faster turnaround models. Vendor strategies that prioritize training, localized workflows, and scalable deployment can accelerate adoption across varied provider maturity levels.
Latin America
Latin America captured 4.90% of 2025 revenue, with growth tied to modernization of private clinics and gradual upgrades in lab production capabilities. Adoption often starts with scan capture and outsourced design or fabrication, supporting lab-centric CAD/CAM demand. Budget constraints can slow upgrades, increasing interest in modular adoption and phased digitization plans. Strong distributor networks, training availability, and reliable service support remain important to build confidence in digital workflows.
Middle East & Africa
Middle East & Africa represented 2.80% of 2025 revenue, supported by investments in premium dental services in major cities and expanding private care networks. Adoption frequently prioritizes workflows that improve turnaround and aesthetics for restorative cases. Training, service support, and ecosystem compatibility influence purchasing decisions, especially where mixed equipment fleets are common. Partnerships with lab networks and digital dentistry education initiatives can accelerate uptake over the forecast period.
Competitive Landscape
Competition in the Dental CAD/CAM Market is defined by workflow breadth, usability, and integration across scanning and fabrication ecosystems. Vendors differentiate through library depth, guided workflows, automation, and support for complex restorative and implant use cases. Interoperability and partner ecosystems matter for labs serving multiple clinic platforms, while end-to-end suites can appeal to clinics seeking simplified procurement and training. Upgrades and module expansion are common strategies to deepen customer retention and increase recurring revenue.
Dentsply Sirona often competes through integrated digital dentistry offerings that align clinical capture, design workflows, and fabrication pathways. A suite-oriented strategy can reduce integration friction for clinics prioritizing standardized operations and predictable case delivery. Training and service support influence adoption outcomes because workflow change management is a core barrier for many practices. Product ecosystem alignment and compatibility with lab partners remain important for scaling utilization across networks.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Dentsply Sirona
- 3Shape
- ExoCAD/CAM
- Planmeca
- Straumann
- Ivoclar
- Amann Girrbach
- Dental Wings
- Carestream Dental
- Zirkonzahn
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Benco Dental and Dentsply Sirona expanded their partnership, with Benco set to offer Dentsply Sirona’s broader digital technology portfolio in the U.S., including the CEREC system, CEREC blocks, Primescan and Primescan 2 intraoral scanners, and extraoral imaging systems such as Axeos and Orthophos.
- In October 2025, Planmeca entered a new partnership with The Aspen Group to expand the use of advanced digital imaging technologies across Aspen Dental locations in the United States, with the goal of improving diagnostic precision, clinical workflow, and patient experience.
- In March 2025, Mikrona Group AG acquired Dental Axess AG in Switzerland, a move aimed at strengthening Mikrona’s position in digital dentistry through Dental Axess’ portfolio of CAD/CAM/CAM products, intraoral scanners, 3D printers, X-ray devices, and software solutions.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1,112.38 million |
| Revenue forecast in 2032 | USD 1,913.31 million |
| Growth rate (CAGR) | 9.46% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Software Type Outlook: Design, Simulation, Milling Prep; By Deployment Outlook: On-premise, Cloud-based; By Application Outlook: Crowns, Bridges, Implants; By Integration Outlook: Scanner-linked, Milling-linked; By End-user Outlook: Dental Labs, Clinics; By Workflow Model Outlook: Chairside, Lab-centric, Hybrid |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Dentsply Sirona, 3Shape, ExoCAD/CAM, Planmeca, Straumann, Ivoclar, Amann Girrbach, Dental Wings, Carestream Dental, Zirkonzahn |
| No. of Pages | 326 |
Segmentation
By Software Type
- Design
- Simulation
- Milling Prep
By Deployment
- On-premise
- Cloud-based
By Application
- Crowns
- Bridges
- Implants
By Integration
- Scanner-linked
- Milling-linked
By End-user
- Dental Labs
- Clinics
By Workflow Model
- Chairside
- Lab-centric
- Hybrid
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Accelerated adoption of digital restorative workflows
Dental clinics and labs are increasingly implementing end-to-end digital workflows, reducing turnaround times and improving restoration consistency, which drives recurring software usage and upgrades.
Demand for faster turnaround and improved patient experience
Same-day and short-cycle dentistry models are boosting reliance on efficient CAD/CAM workflows, enabling clinics and labs to deliver restorations more quickly and enhance patient satisfaction.
Expansion of implant and complex case workflows
The growing complexity of implant and multi-unit restorative cases increases the need for advanced CAD/CAM tools, guided workflows, and component libraries, supporting higher adoption among labs and clinics.
Integration and interoperability requirements
Purchasing decisions are increasingly influenced by the need for seamless integration with scanners, mills, and other digital equipment, as well as interoperability across mixed-fleet environments, encouraging upgrades and module adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and forecasted size of the Dental CAD/CAM Market?
What is the CAGR for the Dental CAD/CAM Market during 2025–2032?
What is the largest end-user segment in the Dental CAD/CAM Market?
What factors are driving growth in the Dental CAD/CAM Market?
Which companies are profiled in the Dental CAD/CAM Market report?
Which region leads the Dental CAD/CAM Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Dental Labs
- 1.2.2 Clinics
- 1.3 By Deployment
- 1.3.1 On-premise
- 1.3.2 Cloud-based
- 1.4 By Application
- 1.4.1 Crowns
- 1.4.2 Bridges
- 1.4.3 Implants
- 1.5 By Software Type
- 1.5.1 Design
- 1.5.2 Simulation
- 1.5.3 Milling Prep
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1,112.38 million → 2032: USD 1,913.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dental CAD/CAM Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dental CAD/CAM Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dental CAD/CAM Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dental CAD/CAM Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dental CAD/CAM Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dental CAD/CAM Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dental CAD/CAM Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dental CAD/CAM Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1,112.38 million → 2032: USD 1,913.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dental CAD/CAM Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dental Labs
- 12.3.7.2 Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-premise
- 12.4.7.2 Cloud-based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Crowns
- 12.5.7.2 Bridges
- 12.5.7.3 Implants
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Software Type - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Design
- 12.6.7.2 Simulation
- 12.6.7.3 Milling Prep
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dental CAD/CAM End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dental CAD/CAM Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dental CAD/CAM Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dental CAD/CAM Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dentsply Sirona
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3Shape
- 18.4 ExoCAD/CAM
- 18.5 Planmeca
- 18.6 Straumann
- 18.7 Ivoclar
- 18.8 Amann Girrbach
- 18.9 Dental Wings
- 18.10 Carestream Dental
- 18.11 Zirkonzahn
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

