
Diaphragm Pump Market Overview:
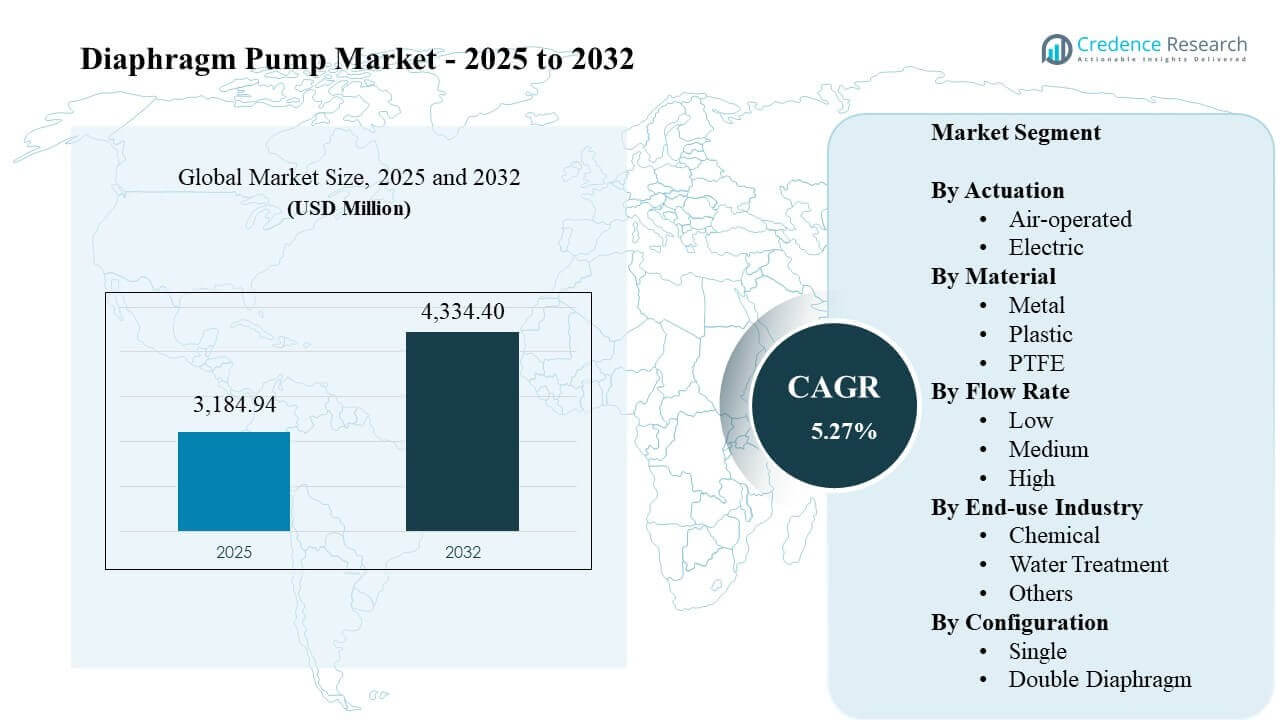
The global Diaphragm Pump Market size was estimated at USD 3,184.94 million in 2025 and is expected to reach USD 4,334.40 million by 2032, growing at a CAGR of 5.27% from 2025 to 2032. Growth is supported by rising demand for leak-free, chemically compatible fluid transfer across industrial processes where safety, uptime, and regulatory compliance shape equipment selection. Asia Pacific demand momentum is reinforced by expanding industrial capacity and wastewater investments, alongside wider adoption of diaphragm pumps in dosing, transfer, and slurry-handling workflows.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Diaphragm Pump Market Size 2025 | USD 3,184.94 million |
| Diaphragm Pump Market, CAGR | 5.27% |
| Diaphragm Pump Market Size 2032 | USD 4,334.40 million |
Key Market Trends & Insights
- The Diaphragm Pump Market is projected to add USD 1,149.46 million from 2025 to 2032 as adoption expands in process industries.
- Asia Pacific accounted for 33% revenue share in 2025, reflecting strong manufacturing and infrastructure-linked demand.
- North America contributed 31% revenue share in 2025, supported by chemical processing, industrial upgrades, and water treatment reliability requirements.
- Air-operated diaphragm pumps held 49% share in 2025, supported by suitability for hazardous environments and robust solids handling.
- Double diaphragm configurations represented 58% share in 2025, driven by steadier flow delivery and higher-duty transfer requirements.
Segment Analysis
Diaphragm pump purchasing decisions prioritize fluid compatibility, containment, and operational continuity across dosing, transfer, and sludge-handling use cases. End users select diaphragm pump configurations based on media aggressiveness, solids content, and the need for leak-free performance in regulated environments. Air-operated designs remain a common choice in plants where explosive atmospheres or utility constraints limit electrical deployment near the pump. Electric diaphragm pumps gain traction in automation-heavy sites that value repeatable control, monitoring, and integration into digital maintenance workflows.
Application demand is closely tied to chemical processing and water treatment operating models. Water treatment workflows favor diaphragm pumps for chemical dosing, sludge transfer, and reliable handling of abrasive media under intermittent duty cycles. Chemical operations emphasize corrosion resistance and safer handling of hazardous fluids, which strengthens demand for compatible wetted materials and proven sealing performance. Configuration choices often shift toward double diaphragm designs when facilities require steadier throughput and reduced pulsation under continuous operating schedules.
By Actuation Insights
Air-operated accounted for the largest share of 49% in 2025. Air-operated diaphragm pumps remain preferred in hazardous locations because air drive reduces electrical risk at the point of use and supports safe transfer of volatile fluids. Air-operated diaphragm pumps also perform well with viscous, abrasive, and solids-laden media, which aligns with sludge, slurry, and chemical transfer tasks. Maintenance workflows benefit from simple mechanical architecture and field serviceability across industrial sites.
By Material Insights
Material selection in the Diaphragm Pump Market is driven by chemical compatibility, corrosion resistance, temperature tolerance, and total cost of ownership. PTFE-wetted components and linings are favored in aggressive chemical duty because PTFE reduces attack risks and supports longer service intervals. Plastics are selected where corrosion resistance and weight advantages matter in water treatment and light chemical service. Metals remain important in high-pressure, high-temperature, or mechanically demanding applications where robustness and lifecycle reliability are prioritized.
By Flow Rate Insights
Flow-rate requirements shape diaphragm pump selection based on process duty, media properties, and control expectations. Low and medium flow applications commonly include chemical dosing, transfer between tanks, and metering tasks where stable delivery and containment are valued. High flow use cases appear in bulk transfer and industrial handling, where system design must balance pulsation control and energy efficiency. Flow-rate alignment with media viscosity and solids content remains critical because mismatch can increase wear and reduce uptime.
By End-use Industry Insights
Water Treatment accounted for the largest share of 22% in 2025. Water treatment demand is supported by municipal and industrial wastewater requirements, where diaphragm pumps perform dosing, sludge transfer, and handling of chemically treated water. Leak-free performance supports compliance and reduces environmental risk in treatment operations. Chemical end use also sustains demand because corrosive media handling requires compatible materials and dependable containment. Broader industrial use cases contribute steady volume through general fluid transfer and process support applications.
By Configuration Insights
Double Diaphragm accounted for the largest share of 58% in 2025. Double diaphragm configurations are widely used because double diaphragm operation supports steadier discharge and improved suitability for continuous duty applications. Process plants value reduced pulsation and more consistent throughput when transferring chemicals, slurries, or viscous fluids. Double diaphragm adoption is also supported by reliability in harsh environments and flexible installation across industrial layouts. Single diaphragm designs remain relevant in lighter duty and cost-sensitive deployments where throughput requirements are lower.
Diaphragm Pump Market Drivers
Expansion of wastewater treatment and dosing applications
Growth in municipal and industrial wastewater capacity supports sustained demand for diaphragm pumps used in dosing, sludge transfer, and chemical handling. Water utilities and industrial operators prioritize leak-free pumping to reduce compliance risk and protect worker safety. Diaphragm pump designs tolerate abrasive media and intermittent duty cycles that are common in treatment workflows. Investment in treatment upgrades and stricter discharge norms increase demand for reliable chemical metering and transfer systems.
- For instance, Blue-White reported that SUEZ Water South Jersey deployed its CHEM-FEED MD3 dual-diaphragm dosing pump for high-pressure alum injection, achieving a 2000:1 turndown ratio, 380 strokes per minute, and 50% higher energy efficiency than similar units, while sending exact flow-rate data to SCADA through the Sonic-Pro MS6 sensor and eliminating tube replacement in that application.
Higher safety requirements in hazardous and corrosive fluid handling
Chemical processing and adjacent industries require secure handling of hazardous, corrosive, and volatile fluids, which supports diaphragm pump adoption. Diaphragm pump architectures reduce leakage risk compared with alternatives used in certain duty points. Air-operated diaphragm pumps are favored in explosive atmospheres where electrical limitations exist near the pump location. Safety-driven procurement also elevates attention on compatible wetted materials and reliable sealing performance.
- For instance, ARO states that its metallic air-operated diaphragm pumps are certified for ATEX Zone 0 for gases and Zone 20 for dusts, with selected models available from 1/2-inch to 3-inch port sizes, flow rates from 45 lpm to 1,041 lpm, and discharge pressure up to 8.3 bar for high-risk hazardous applications.
Industrial process reliability and uptime optimization
Industrial sites focus on reducing unplanned downtime and improving plant reliability, which increases demand for pumps that handle challenging media consistently. Diaphragm pumps are selected for viscous, solids-containing, and shear-sensitive fluids where stable operation is required. Double diaphragm configurations help meet throughput stability needs in continuous transfer tasks. Maintenance planning and availability of service parts also influence brand selection, supporting suppliers with strong channel and service coverage.
Automation and electrification in industrial pumping
Automation strategies across process industries increase adoption of electric diaphragm pumps where precise control, monitoring, and integration are priorities. Electric actuation supports repeatable dosing and easier integration into plant control systems. Energy efficiency focus also encourages evaluation of electric alternatives in place of compressed-air-driven operation for suitable use cases. Digital maintenance practices increase interest in pumps designed for diagnostics, scheduled service, and predictable operating performance.
Diaphragm Pump Market Challenges
Compressed air availability and operating cost remain constraints for air-operated diaphragm pumps in plants where air generation is energy intensive or capacity is limited. Air system quality issues can impact diaphragm pump performance and maintenance frequency, increasing lifecycle cost concerns. Material compatibility challenges persist in aggressive chemical duty because improper selection can accelerate diaphragm wear and reduce uptime. Procurement teams also face trade-offs between upfront cost and durability, especially in price-sensitive industrial accounts.
- For instance, Wilden reports that its Pro-Flo SHIFT air distribution system can reduce air consumption by up to 60% while delivering flow rates up to 34% greater than other AODD pump models.
Pulsation management and flow stability requirements can increase system complexity in applications that demand smooth delivery. Facilities may require dampeners, controls, or system tuning, which can raise total installed cost and extend commissioning time. Competitive pressure from alternative pump technologies can influence diaphragm pump adoption in high-flow duties where centrifugal systems may offer advantages depending on media characteristics. Service coverage, spare parts availability, and training also affect supplier selection across distributed industrial footprints.
Diaphragm Pump Market Trends and Opportunities
Electrification and smarter control capabilities are shaping product strategies as more sites seek automated dosing and monitoring. Electric diaphragm pump adoption benefits from integration into plant controls and maintenance programs that emphasize predictability and reduced energy waste. Suppliers that provide configurable controls, diagnostics, and service support can strengthen long-term account retention. Growth is also supported by customers standardizing pump fleets across facilities to simplify training, spares, and compliance documentation.
Water infrastructure modernization creates opportunities for diaphragm pump suppliers focused on dosing, sludge management, and chemical handling reliability. Industrial expansion in emerging markets supports new installations across chemicals, general manufacturing, and utilities. Materials innovation remains an opportunity area because improved elastomers and PTFE-related solutions can extend service life in aggressive fluids. Channel expansion and localized service networks also improve competitiveness in regions with rising industrial activity and dispersed end users.
- For instance, Milton Roy reports that its redesigned mROY metering pump features a hydraulically balanced diaphragm with a 96,000-hour design life, while supporting flow rates from 0.8 l/h to 299 l/h and turndown ratios up to 100:1, underscoring how durability-focused diaphragm engineering can improve reliability in demanding chemical and water treatment applications.
Regional Insights
North America
North America held 31% share in 2025, supported by demand from chemical processing, industrial maintenance cycles, and compliance-driven fluid handling. Water and wastewater facilities also contribute steady demand for dosing and sludge transfer applications where leak-free pumping is prioritized. Industrial customers in North America often emphasize lifecycle cost, service availability, and safety performance. Supplier differentiation in North America commonly centers on reliability, spare parts access, and support for regulated environments.
Europe
Europe represented 24% share in 2025, supported by process industry operations and environmental compliance focus across water treatment and industrial plants. European buyers often prioritize energy performance, safety standards, and equipment reliability in corrosive or hazardous duty applications. Water treatment upgrades and industrial efficiency programs support demand for diaphragm pumps in dosing and transfer roles. Competitive positioning in Europe benefits from strong distributor networks and application engineering support for specialized use cases.
Asia Pacific
Asia Pacific led with 33% share in 2025 as manufacturing expansion and infrastructure spending increased demand for industrial pumping solutions. Rapid growth in wastewater treatment capacity supports diaphragm pump demand in dosing and sludge handling across municipal and industrial projects. Chemical and general manufacturing activities also support demand for corrosion-resistant, leak-free fluid transfer systems. Supplier strategies in Asia Pacific often emphasize localized production, service reach, and value-based product tiers for diverse end-user requirements.
Latin America
Latin America held 7% share in 2025, supported by selective industrial activity, mining-related process demand, and ongoing water treatment investments. Industrial operators prioritize robust designs that tolerate variable operating conditions and maintenance constraints. Wastewater and industrial dosing projects create recurring demand for diaphragm pumps in chemical feed and transfer roles. Supplier competitiveness in Latin America improves with strong distributor presence, spare parts availability, and training support for maintenance teams.
Middle East & Africa
Middle East and Africa captured 5% share in 2025, supported by chemical processing, desalination-adjacent workflows, and industrial projects in key hubs. Oil and gas and related industrial activity create demand for leak-free transfer in hazardous environments. Water treatment and industrial reuse initiatives also contribute to dosing and transfer demand. Suppliers that provide application engineering, corrosion-compatible materials, and reliable service coverage are better positioned to win project-led demand across the region.
Competitive Landscape
Competition in the Diaphragm Pump Market is defined by application fit, reliability, and total cost of ownership across chemical, water treatment, and industrial fluid-handling use cases. Suppliers differentiate through wetted-material portfolios, diaphragm durability, and service coverage that supports uptime in harsh environments. Product strategies increasingly align with automation needs, energy efficiency expectations, and easier maintenance. Channel strength and installed-base support also shape share retention in distributed industrial end markets.
Grundfos positions diaphragm pump and broader pumping offerings around reliability, energy performance, and lifecycle service support across industrial and water-related end users. Grundfos benefits from strong engineering capabilities that support application matching and system design guidance. Service reach and a broad product portfolio help Grundfos compete in accounts seeking standardization across multiple sites. Product quality and support infrastructure remain key factors influencing repeat procurement.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2025, Dover Corporation acquired Cryogenic Machinery Corp. (Cryo-Mach), and the business was added to Dover’s PSG unit within its Pumps & Process Solutions segment to expand Dover’s presence in the cryogenic pump market.
- In April 2025, Graco Inc. announced enhancements to its QUANTM electric double diaphragm pump line, adding 480V input compatibility and XTREME TORQUE motor technology to improve efficiency, reduce pump size and weight, and simplify maintenance.
- In September 2025, ARO introduced the EVO 210 electric double diaphragm pump for transfer and batching applications, expanding its diaphragm pump portfolio with an energy-efficient electric option designed to improve reliability and reduce maintenance time.
- In September 2024, IDEX Corporation completed its acquisition of Mott Corporation, a move that expanded IDEX’s applied material science and flow-control capabilities across high-value end markets connected to its broader pump and process businesses.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 3,184.94 million |
| Revenue forecast in 2032 | USD 4,334.40 million |
| Growth rate (CAGR) | 5.27% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Actuation, By Material, By Flow Rate, By End-use Industry, By Configuration |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Grundfos, Xylem, Verder, Flowserve, IDEX, Graco, KNF, TAPFLO, Ingersoll Rand, SPX Flow |
| No. of Pages | 328 |
Segmentation
By Actuation
- Air-operated
- Electric
By Material
- Metal
- Plastic
- PTFE
By Flow Rate
- Low
- Medium
- High
By End-use Industry
- Chemical
- Water Treatment
- Others
By Configuration
- Single
- Double Diaphragm
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of wastewater treatment and dosing applications
Growing municipal and industrial wastewater treatment capacity is driving demand for diaphragm pumps, which are essential for chemical dosing, sludge transfer, and handling abrasive media. Leak-free operation and compliance with stricter discharge norms make diaphragm pumps a preferred choice in these applications.
Higher safety requirements in hazardous and corrosive fluid handling
Industries such as chemical processing require secure handling of hazardous, corrosive, and volatile fluids. Diaphragm pumps, especially air-operated models, are favored for their leak-free performance and suitability for explosive or regulated environments, supporting safer operations.
Industrial process reliability and uptime optimization
Manufacturers and process industries are prioritizing equipment that minimizes downtime and ensures consistent operation with challenging media. Diaphragm pumps are selected for their ability to handle viscous, solids-laden, and shear-sensitive fluids, with double diaphragm configurations offering steadier throughput.
Automation and electrification in industrial pumping
The shift toward automation and digital maintenance in industrial facilities is increasing adoption of electric diaphragm pumps, which offer precise control, integration with plant systems, and improved energy efficiency compared to air-operated alternatives.
Material innovation and compatibility
Advancements in wetted materials such as PTFE and specialized elastomers are extending diaphragm pump service life in aggressive chemical environments. This supports broader adoption in industries where chemical compatibility and reduced maintenance are critical.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Diaphragm Pump Market?
What is the CAGR for the Diaphragm Pump Market during 2025–2032?
What is the largest segment in the Diaphragm Pump Market?
What factors are driving growth in the Diaphragm Pump Market?
Which companies are leading participants in the Diaphragm Pump Market?
Which region leads the Diaphragm Pump Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Metal
- 1.2.2 Plastic
- 1.2.3 PTFE
- 1.3 By Actuation
- 1.3.1 Air-operated
- 1.3.2 Electric
- 1.4 By Configuration
- 1.4.1 Single
- 1.4.2 Double Diaphragm
- 1.5 By End-use Industry
- 1.5.1 Chemical
- 1.5.2 Water Treatment
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3,184.94 million → 2032: USD 4,334.40 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Diaphragm Pumps Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Diaphragm Pumps Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Diaphragm Pumps Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Diaphragm Pumps Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Diaphragm Pumps Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Diaphragm Pumps Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Diaphragm Pumps Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Diaphragm Pumps Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3,184.94 million → 2032: USD 4,334.40 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Diaphragm Pumps Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metal
- 12.3.7.2 Plastic
- 12.3.7.3 PTFE
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Actuation - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Air-operated
- 12.4.7.2 Electric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Configuration - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single
- 12.5.7.2 Double Diaphragm
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-use Industry - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Chemical
- 12.6.7.2 Water Treatment
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Diaphragm Pumps End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Diaphragm Pumps Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Diaphragm Pumps Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Diaphragm Pumps Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Grundfos
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Xylem
- 18.4 Verder
- 18.5 Flowserve
- 18.6 IDEX
- 18.7 Graco
- 18.8 KNF
- 18.9 TAPFLO
- 18.10 Ingersoll Rand
- 18.11 SPX Flow
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

