
Market Overview:
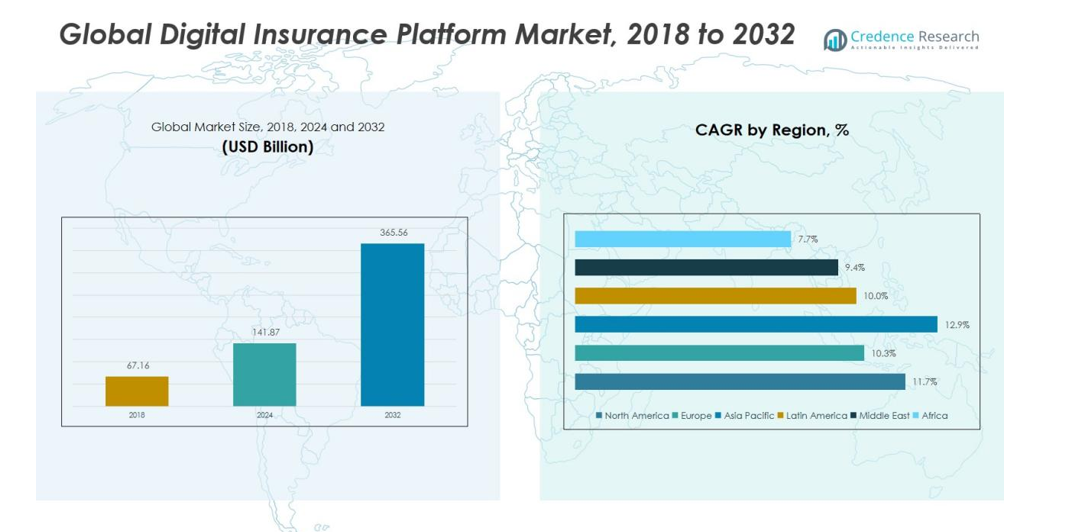
The Global Digital Insurance Platform Market size was valued at USD 67.16 million in 2018 to USD 141.87 million in 2024 and is anticipated to reach USD 365.56 million by 2032, at a CAGR of 11.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Insurance Platform Market Size 2024 | USD 141.87 million |
| Digital Insurance Platform Market, CAGR | 11.70% |
| Digital Insurance Platform Market Size 2032 | USD 365.56 million |
Key growth drivers include the adoption of cloud-based platforms, use of artificial intelligence and data analytics for underwriting and claims automation, and the growing need for regulatory compliance and digital reporting. The market also benefits from rising investments in insurtech startups and partnerships between traditional insurers and technology providers.
Regionally, North America holds the largest market share due to advanced IT infrastructure and early technology adoption by insurers. Europe follows with strong digital transformation initiatives and regulatory support for transparent insurance operations. The Asia Pacific region is expected to witness the fastest growth, driven by increasing insurance penetration, rapid smartphone adoption, and supportive government initiatives in countries such as India, China, and Japan.
Market Insights:
- The Global Digital Insurance Platform Market was valued at USD 67.16 million in 2018, reached USD 141.87 million in 2024, and is projected to reach USD 365.56 million by 2032, growing at a CAGR of 11.70% during the forecast period.
- North America holds 37% of the market share, driven by advanced IT infrastructure and early adoption of AI, IoT, and cloud technologies by insurers. Europe follows with 21% share, supported by strong regulatory frameworks and modernization of legacy systems.
- Asia Pacific accounts for 30% share and is the fastest-growing region, fueled by digital transformation, rising smartphone usage, and government-backed insurance inclusion programs in China, India, and Japan.
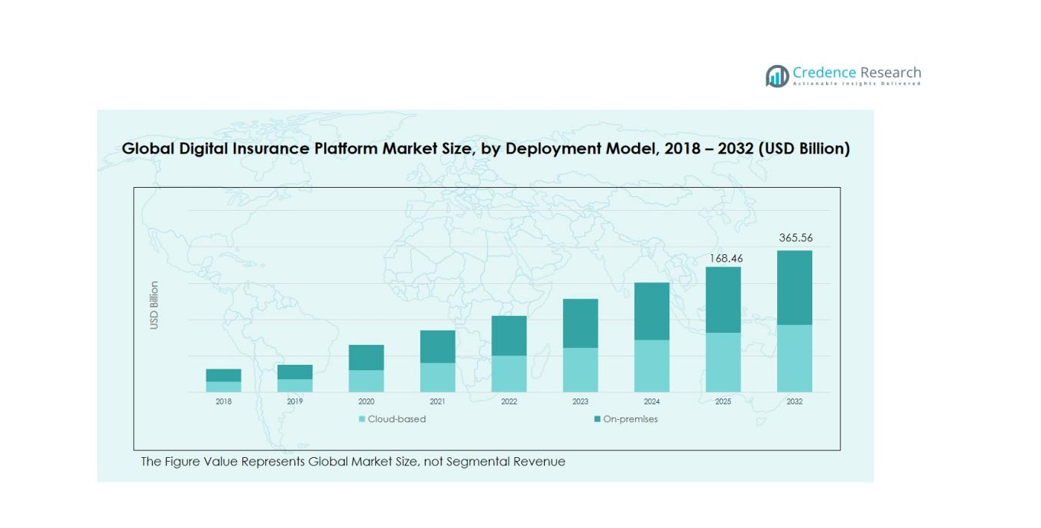
- By deployment model, the cloud-based segment dominates with over 65% share, offering scalability, cost reduction, and real-time access advantages over on-premises models.
- By business type, property and casualty insurance leads with 48% share due to growing demand for automated underwriting, personalized risk assessment, and integration of predictive analytics in claims management.
Market Drivers:
Rising Adoption of Cloud-Based Infrastructure and Advanced Technologies
The Global Digital Insurance Platform Market is expanding due to the widespread integration of cloud computing, AI, and big data analytics. Insurers are deploying scalable, cloud-based systems to reduce operational costs and improve flexibility. It enables seamless integration of third-party applications, accelerates claims processing, and enhances data-driven decision-making. The shift toward real-time analytics and machine learning supports faster underwriting and risk assessment, improving accuracy and profitability for insurers.
- For instance, Cytora, a risk digitization platform, joined Google Cloud Marketplace to automate risk processing across insurance workflows, processing multiple document types across over 140 languages and enabling insurers to separate premium growth from expense growth while gaining control over unstructured risk submission data across diverse formats.
Growing Demand for Enhanced Customer Experience and Personalization
Insurers are prioritizing customer-centric models to deliver personalized insurance products and responsive digital experiences. The market benefits from the rising use of chatbots, virtual assistants, and mobile apps that improve accessibility and service speed. It allows policyholders to manage claims, renewals, and premium payments through self-service platforms. Increasing consumer expectations for transparency and convenience are compelling insurers to invest in user-friendly digital ecosystems.
- For instance, Lemonade's AI-powered claims bot, AI Jim, processes insurance claims in just 2 seconds by assessing claims, cross-referencing policies, running anti-fraud algorithms, and approving payments-demonstrating how automated digital assistants can deliver instantaneous service while handling nearly 50% of all claims through artificial intelligence.
Rising Regulatory Compliance and Risk Management Needs
The growing complexity of insurance regulations across regions drives the adoption of digital platforms that ensure compliance and transparency. The Global Digital Insurance Platform Market gains traction as companies deploy automated tools for data tracking, reporting, and governance. It helps insurers adhere to regional data protection laws and maintain audit-ready records. Enhanced visibility and traceability of transactions strengthen trust among regulators and customers.
Expansion of Insurtech Collaborations and Ecosystem Partnerships
Insurtech startups are playing a pivotal role in reshaping the insurance landscape through technological innovation. The market benefits from collaborations between traditional insurers and technology providers to accelerate digital transformation. It enables the development of advanced underwriting models, predictive analytics, and connected policy ecosystems. Strategic partnerships also help insurers diversify offerings and reach new customer segments across digital channels.
Market Trends:
Integration of Artificial Intelligence, IoT, and Predictive Analytics in Insurance Operations
The Global Digital Insurance Platform Market is witnessing strong adoption of artificial intelligence, Internet of Things (IoT), and predictive analytics to transform core insurance processes. Insurers use AI-driven tools for claims automation, fraud detection, and customer risk profiling. It supports faster decision-making and reduces manual intervention across policy lifecycle management. Predictive analytics helps forecast claim probabilities, optimize pricing models, and improve underwriting accuracy. IoT-enabled devices such as telematics and smart wearables provide real-time data, allowing insurers to design dynamic, usage-based policies. These technologies enhance efficiency, accuracy, and personalization, creating significant competitive advantages for digital-first insurers.
- For instance, Aviva has deployed over 80 AI models in its claims operations, achieving £60 million ($82 million USD) in cost savings within its motor claims division while reducing claims settlement cycles and enabling 40,000 hours of workforce upskilling across the organization.
Shift Toward Ecosystem-Based Platforms and Embedded Insurance Solutions
The market is shifting from standalone systems to ecosystem-based digital platforms that integrate multiple insurance and non-insurance services. The Global Digital Insurance Platform Market is evolving toward embedded insurance models where coverage is seamlessly offered within retail, travel, or fintech transactions. It enables insurers to reach customers at the point of need, improving convenience and conversion rates. Digital ecosystems supported by APIs and open banking frameworks foster interoperability across partners and channels. Growing partnerships between insurers, fintechs, and technology firms are accelerating this trend. It promotes continuous engagement, drives cross-selling opportunities, and supports the transition toward real-time, personalized insurance experiences.
- For instance, Cover Genius partnered with Uber to offer drivers embedded income protection in Brazil, with premium costs calculated per kilometer driven and achieving a Net Promoter Score of +65 through its award-winning claims servicing.
Market Challenges Analysis:
Data Security Concerns and Regulatory Complexities Restraining Digital Transformation
The Global Digital Insurance Platform Market faces challenges related to data privacy, cybersecurity, and complex regulatory frameworks. Insurers handle vast amounts of sensitive customer data, making them targets for cyberattacks and breaches. It must ensure strong encryption, secure APIs, and compliance with data protection laws such as GDPR and HIPAA. Varying regional regulations increase compliance costs and hinder uniform platform deployment. Legacy infrastructure in many insurance firms also limits the integration of modern security frameworks. These concerns slow digital adoption and increase operational risks for insurers.
High Implementation Costs and Skill Gaps Limiting Market Growth
The transition to digital insurance platforms requires significant investment in infrastructure, cloud migration, and advanced analytics tools. The Global Digital Insurance Platform Market is challenged by high upfront costs that discourage smaller insurers from adopting new systems. It also faces a shortage of skilled professionals who can manage AI, data science, and cybersecurity functions. Integration with legacy systems often leads to technical disruptions and longer deployment cycles. Limited awareness of digital solutions in emerging economies further constrains adoption. These factors collectively restrict the market’s scalability and speed of transformation.
Market Opportunities:
Expansion of Digital Ecosystems and Untapped Markets in Emerging Economies
The Global Digital Insurance Platform Market offers strong potential in emerging economies with low insurance penetration and rapid digital adoption. Countries in Asia Pacific, Latin America, and Africa are witnessing growth in smartphone usage and internet access, creating demand for online policy distribution. It allows insurers to reach first-time customers through digital channels and microinsurance products. Government initiatives promoting financial inclusion further enhance adoption opportunities. Partnerships with fintech firms and telecom operators are expected to accelerate customer acquisition and improve access to affordable insurance solutions. These factors make emerging markets a key growth frontier for digital insurers.
Advancement of Embedded and On-Demand Insurance Models
Insurers are embracing embedded and on-demand insurance models to align with shifting consumer behavior. The Global Digital Insurance Platform Market benefits from the integration of insurance offerings into e-commerce, travel, and fintech ecosystems. It enables customers to purchase contextual coverage instantly during digital transactions. Real-time data analytics and automation simplify policy issuance and claims handling, enhancing customer experience. Growing demand for flexible, usage-based coverage options supports innovation in pay-per-use models. These developments open new revenue streams and strengthen insurer competitiveness in a dynamic digital environment.
Market Segmentation Analysis:
By Deployment Model
The Global Digital Insurance Platform Market is segmented into cloud-based and on-premises models. Cloud-based platforms dominate due to their scalability, cost efficiency, and faster deployment. It allows insurers to streamline data storage and enable real-time access across multiple locations. On-premises solutions remain relevant among large enterprises focused on higher data control and security compliance. Growing preference for hybrid models further supports flexible infrastructure adoption.
- For Instance, Allianz Direct utilized Rockset's cloud-native real-time analytics platform to integrate over 800 pricing factors into its pricing engine. This implementation, including self-service data product development, reduced model tuning cycles from weeks to 1–2 days.
By Application
The market covers applications such as underwriting, claims management, policy management, customer relationship management, and fraud detection. Claims management holds a major share driven by automation and AI integration for faster settlements. It supports real-time verification and enhances customer satisfaction through digital claim processing. Policy management and CRM modules are gaining traction for improving transparency and client engagement. Rising fraud incidents in digital insurance transactions are fueling investment in predictive fraud detection systems.
- For Instance, Allianz UK's use of AI-driven tools contributed to detecting over 15,800 instances of insurance fraud, preventing losses worth £92.6 million
By Business Type
The Global Digital Insurance Platform Market includes property and casualty, life and health, and specialty insurance segments. Property and casualty insurance dominates due to strong demand for personalized policies and efficient risk assessment tools. It benefits from IoT and AI integration for automated underwriting and real-time claims tracking. Life and health insurance is expanding with digital health data analytics and telemedicine support. Specialty insurance platforms are growing due to increasing coverage for niche sectors like cyber and travel insurance.
Segmentations:
By Deployment Model
- Cloud-Based
- On-Premises
By Application
- Underwriting
- Claims Management
- Policy Management
- Customer Relationship Management (CRM)
- Fraud Detection
By Business Type
- Property and Casualty Insurance
- Life and Health Insurance
- Specialty Insurance
By Organization Size
- Small and Medium-Sized Enterprises (SMEs)
- Large Enterprises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Digital Insurance Platform Market size was valued at USD 29.78 billion in 2018 to USD 62.27 billion in 2024 and is anticipated to reach USD 160.89 billion by 2032, at a CAGR of 11.7% during the forecast period. The region holds 37% of the Global Digital Insurance Platform Market share. Strong adoption of advanced technologies such as AI, IoT, and cloud infrastructure supports market expansion. It benefits from the presence of leading insurers and technology providers investing in automation and customer analytics. The United States dominates the region with a mature insurance ecosystem and focus on digital transformation. Canada and Mexico are recording steady progress supported by insurtech partnerships and mobile-based insurance distribution. Continuous investment in predictive analytics and automation reinforces the region’s leadership.
Europe
The Europe Digital Insurance Platform Market size was valued at USD 11.78 billion in 2018 to USD 23.42 billion in 2024 and is anticipated to reach USD 54.51 billion by 2032, at a CAGR of 10.3% during the forecast period. The region holds 21% of the Global Digital Insurance Platform Market share. It is driven by strong regulatory frameworks, increased cloud adoption, and innovation across the insurance ecosystem. The UK, Germany, and France lead through investments in AI-based underwriting and data-driven claims management. It benefits from modernization of legacy systems to improve compliance with data protection laws. Expanding collaboration between insurers and startups is strengthening the region’s digital infrastructure. These efforts are enhancing transparency and operational agility across European insurers.
Asia Pacific
The Asia Pacific Digital Insurance Platform Market size was valued at USD 19.71 billion in 2018 to USD 43.92 billion in 2024 and is anticipated to reach USD 123.28 billion by 2032, at a CAGR of 12.9% during the forecast period. The region contributes 30% of the Global Digital Insurance Platform Market share, making it the fastest-growing regional market. Rapid digital transformation, rising smartphone penetration, and favorable regulatory initiatives drive growth. China, India, and Japan are key contributors with strong adoption of mobile-first insurance solutions. It is supported by fintech collaborations that enhance affordability and accessibility of insurance products. Expanding middle-class income and growing health awareness increase demand for personalized policies. Investments in cloud technology and AI-based automation strengthen the region’s growth outlook.
Latin America
The Latin America Digital Insurance Platform Market size was valued at USD 3.17 billion in 2018 to USD 6.62 billion in 2024 and is anticipated to reach USD 15.09 billion by 2032, at a CAGR of 10.0% during the forecast period. The region holds 7% of the Global Digital Insurance Platform Market share. Growth is driven by digital initiatives promoting financial inclusion and policy accessibility. Brazil leads the region with widespread use of mobile insurance and online claims processing. Mexico and Argentina are improving digital adoption through cloud deployment and analytics integration. It is experiencing transformation through modernization of insurance regulation and automation adoption. Increasing demand for real-time claims and personalized products is further stimulating digital platform investments.
Middle East
The Middle East Digital Insurance Platform Market size was valued at USD 1.90 billion in 2018 to USD 3.66 billion in 2024 and is anticipated to reach USD 7.98 billion by 2032, at a CAGR of 9.4% during the forecast period. The region holds 4% of the Global Digital Insurance Platform Market share. Market growth is supported by national digitalization programs and smart government initiatives. GCC countries are driving demand through AI-enabled insurance tools and real-time data platforms. Israel’s expanding insurtech ecosystem contributes to regional innovation and product diversity. It is focusing on automating underwriting and claims processes to enhance efficiency. Increasing collaboration between insurers and technology firms is supporting market maturity across the Middle East.
Africa
The Africa Digital Insurance Platform Market size was valued at USD 0.82 billion in 2018 to USD 1.97 billion in 2024 and is anticipated to reach USD 3.81 billion by 2032, at a CAGR of 7.7% during the forecast period. The region holds 2% of the Global Digital Insurance Platform Market share. Market growth is supported by mobile insurance adoption and expanding financial inclusion programs. It benefits from strategic partnerships between telecom operators and insurers to deliver affordable microinsurance products. South Africa leads with advanced digital infrastructure and regulatory maturity. Nigeria, Kenya, and Egypt are strengthening their presence through fintech innovation and mobile payment integration. Growing smartphone usage and improved internet connectivity are expected to unlock new digital insurance opportunities across the region.
Key Player Analysis:
- IBM Corporation
- Guidewire Software
- Microsoft Corporation
- Duck Creek Technologies
- Oracle Corporation
- SAP SE
- Next Insurance
Competitive Analysis:
The Global Digital Insurance Platform Market is highly competitive, driven by technological innovation and strategic partnerships among major players. Key companies include IBM Corporation, Guidewire Software, Microsoft Corporation, Duck Creek Technologies, Oracle Corporation, SAP SE, and Next Insurance. It is characterized by continuous advancements in cloud computing, artificial intelligence, and data analytics aimed at improving operational efficiency and customer engagement. Companies are focusing on expanding product portfolios, developing customizable platforms, and strengthening global presence through collaborations and acquisitions. Cloud-based deployment and automation capabilities are central to competitive differentiation, with vendors emphasizing integration flexibility and cybersecurity compliance. The growing demand for end-to-end digital solutions and analytics-driven insights continues to shape the competition landscape, favoring firms with strong R&D capabilities and established client networks.
Recent Developments:
- In October 2025, IBM launched the IBM Digital Asset Haven platform for secure digital asset management in financial institutions, governments, and corporations.
- In October 2025, Oracle launched Oracle AI Factory, a new suite of customer and partner services designed to accelerate enterprise AI projects for global clients.
Report Coverage:
The research report offers an in-depth analysis based on Deployment Model, Application, Business Type, Organization Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Digital Insurance Platform Market will experience accelerated growth driven by rapid cloud adoption and advanced analytics integration.
- AI-driven automation will enhance underwriting accuracy, claims processing speed, and fraud detection efficiency.
- Insurers will prioritize customer-centric platforms offering personalized policy recommendations and real-time support.
- The rise of embedded insurance models will create new revenue channels across e-commerce, travel, and fintech sectors.
- Blockchain adoption will strengthen data transparency, reduce fraud risks, and improve contract management.
- Strategic collaborations between insurers and insurtech startups will fuel technological innovation and market expansion.
- Low-code and no-code platforms will enable faster deployment of customized insurance solutions.
- Cybersecurity and compliance technologies will gain importance to safeguard sensitive policyholder data.
- Emerging economies will witness strong growth supported by digital inclusion and mobile-first insurance initiatives.
- Sustainability-driven insurance products leveraging digital ecosystems will become a key competitive advantage.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Cloud-Based Infrastructure and Advanced Technologies
Insurers are increasingly deploying scalable, cloud-based digital insurance platforms to reduce operational costs, improve flexibility, and enable seamless integration of third-party applications. The integration of AI and big data analytics accelerates claims processing, enhances underwriting accuracy, and supports real-time decision-making.
Growing Demand for Enhanced Customer Experience and Personalization
Digital insurance platforms enable insurers to deliver personalized products and responsive digital experiences through chatbots, mobile apps, and self-service portals. This shift meets rising consumer expectations for transparency, convenience, and instant service, driving further investment in digital ecosystems.
Rising Regulatory Compliance and Risk Management Needs
The complexity of insurance regulations across regions is pushing insurers to adopt digital platforms that automate compliance, data tracking, and reporting. These platforms help maintain audit-ready records, adhere to data protection laws, and provide transparency, which strengthens trust with regulators and customers.
Expansion of Insurtech Collaborations and Ecosystem Partnerships
Collaborations between traditional insurers and insurtech startups are accelerating digital transformation by enabling the development of advanced underwriting models, predictive analytics, and connected policy ecosystems. These partnerships help insurers diversify offerings and reach new customer segments through digital channels.
Integration of Artificial Intelligence, IoT, and Predictive Analytics
The adoption of AI, IoT, and predictive analytics is transforming core insurance processes such as claims automation, fraud detection, and risk profiling. These technologies improve operational efficiency, enable dynamic pricing, and support the creation of usage-based and embedded insurance products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Digital Insurance Platform Market?
At what Compound Annual Growth Rate is the Global Digital Insurance Platform Market projected to grow between 2024 and 2032?
What factors are driving the growth of the Digital Insurance Platform Market?
What are some challenges faced by the Digital Insurance Platform Market?
Who are the major players in the Digital Insurance Platform Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Underwriting
- 1.2.2 Claims Management
- 1.2.3 Policy Management
- 1.2.4 Customer Relationship Management (CRM)
- 1.2.5 Fraud Detection
- 1.3 By Business Type
- 1.3.1 Property and Casualty Insurance
- 1.3.2 Life and Health Insurance
- 1.3.3 Specialty Insurance
- 1.4 By Deployment Model
- 1.4.1 Cloud-Based
- 1.4.2 On-Premises
- 1.5 By Organization Size
- 1.5.1 Small and Medium-Sized Enterprises (SMEs)
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 141.87 million → 2032: USD 365.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Insurance Platform Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Insurance Platform Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Digital Insurance Platform Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Digital Insurance Platform Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Insurance Platform Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Insurance Platform Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Insurance Platform Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Insurance Platform Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 141.87 million → 2032: USD 365.56 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Insurance Platform Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Base-Year Market Share, 2018
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Underwriting
- 12.3.6.2 Claims Management
- 12.3.6.3 Policy Management
- 12.3.6.4 Customer Relationship Management (CRM)
- 12.3.6.5 Fraud Detection
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Business Type - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Base-Year Market Share, 2018
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Property and Casualty Insurance
- 12.4.6.2 Life and Health Insurance
- 12.4.6.3 Specialty Insurance
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Model - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Base-Year Market Share, 2018
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud-Based
- 12.5.6.2 On-Premises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Base-Year Market Share, 2018
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small and Medium-Sized Enterprises (SMEs)
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Insurance Platform End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Digital Insurance Platform Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Digital Insurance Platform Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2018-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Digital Insurance Platform Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Guidewire Software
- 18.4 Microsoft Corporation
- 18.5 Duck Creek Technologies
- 18.6 Oracle Corporation
- 18.7 SAP SE
- 18.8 Next Insurance
- 18.9 Majesco
- 18.10 Sapiens International Corporation
- 18.11 Tata Consultancy Services
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

