
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Neuro Biomarkers Market Size 2024 | USD 706.96 million |
| Digital Neuro Biomarkers Market, CAGR | 24.2% |
| Digital Neuro Biomarkers Market Size 2032 | USD 4002.83 million |
Market Overview
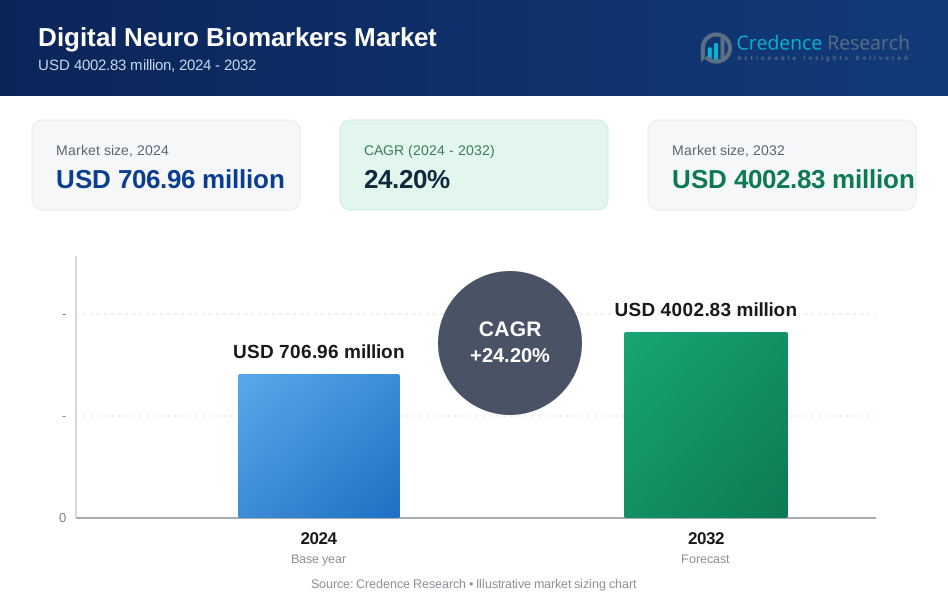
The digital neuro biomarkers market is projected to grow from USD 706.96 million in 2024 to USD 4002.83 million by 2032, with a compound annual growth rate (CAGR) of 24.2%.
The growth of the digital neuro biomarkers market is driven by increasing prevalence of neurological disorders, including Parkinson’s disease and multiple sclerosis, which necessitate more precise and timely diagnostic tools. Advances in wearable technologies, mobile health applications, and artificial intelligence are enabling the real-time assessment of neurological functions, improving disease monitoring and management. Pharmaceutical companies and research organizations are increasingly adopting digital biomarkers to enhance clinical trial efficiency and drug development. Collaborations between MedTech firms and healthcare providers are fostering innovation in remote monitoring and digital health platforms, further supporting market expansion. Additionally, growing awareness about the benefits of personalized medicine and the rising demand for non-invasive, patient-centered solutions are accelerating the adoption of digital neuro biomarkers. Key players are investing in research and development to introduce advanced, AI-powered diagnostic tools, contributing to the market's steady growth and adoption across clinical and research settings.
The digital neuro biomarkers market exhibits significant geographical variation, with North America holding the largest market share in 2024, driven by advanced healthcare infrastructure and high R&D investments. Europe follows closely, with key players in the UK, Germany, and France driving market growth through government initiatives and strong healthcare systems. The Asia-Pacific region, including China, Japan, and India, is experiencing rapid growth due to expanding healthcare access and rising awareness of neurological diseases. The Rest of the World, comprising Latin America, the Middle East, and Africa, is seeing steady growth, although infrastructure challenges may slow adoption. Leading players such as Altoida Inc., Koneksa, Biogen Inc., Roche, and Merck KGaA are contributing significantly to market dynamics across these regions, driving innovations and enhancing market penetration.
Market Insights
- The digital neuro biomarkers market is projected to grow from USD 706.96 million in 2024 to USD 4002.83 million by 2032, with a CAGR of 24.2%.
- Increasing prevalence of neurological disorders, including Parkinson’s and multiple sclerosis, is driving the demand for precise diagnostic tools and real-time disease monitoring.
- Advancements in wearable technologies, mobile health apps, and artificial intelligence are enhancing the accuracy and efficiency of digital biomarkers in disease management.
- Pharmaceutical companies and research organizations are increasingly adopting digital biomarkers to improve clinical trial efficiency and drug development.
- Growing awareness about personalized medicine and non-invasive, patient-centered solutions is accelerating the adoption of digital neuro biomarkers.
- North America holds the largest market share in 2024, with advanced healthcare infrastructure, high R&D investment, and a large patient base.
- Europe follows closely with a strong healthcare system and government initiatives promoting digital health technologies, while Asia-Pacific is experiencing rapid growth due to expanding healthcare access and awareness.
Market Drivers
Growing Prevalence of Neurological Disorders
The increasing global prevalence of neurological disorders such as Parkinson’s disease, Alzheimer’s disease, and multiple sclerosis is a significant driver for the digital neuro biomarkers market. These conditions require continuous monitoring and early detection for effective management, which is where digital neuro biomarkers provide an essential solution. For instance, Linus Health shared results from studies validating their AI-enhanced digital cognitive assessment technology, proving its accuracy in detecting mild cognitive impairment and dementia compared to traditional methods. These tools offer precise, real-time insights into disease progression, enabling timely interventions and personalized treatment strategies. As the number of individuals affected by neurological diseases continues to rise, the demand for advanced diagnostic solutions like digital neuro biomarkers is expected to grow.
Technological Advancements in Diagnostic Tools
Technological advancements in wearable devices, mobile health apps, and AI-based analytics are revolutionizing the digital neuro biomarkers market. For Instance, Revibe Technologies' wearable reminder system has demonstrated a 40% improvement in attention span and on-task behavior among children with ADHD. These innovations allow for continuous, non-invasive monitoring of patients, making it easier to track neurological health outside of clinical settings. The integration of artificial intelligence enhances the accuracy and efficiency of digital biomarkers, improving the interpretation of data collected from patients. As these technologies evolve, they offer more reliable and precise methods for assessing neurological functions, thereby fueling the market's growth.
Demand for Remote Patient Monitoring
The growing emphasis on remote patient monitoring is another key driver in the digital neuro biomarkers market. With healthcare systems increasingly focused on patient-centered care, digital neuro biomarkers provide a means for clinicians to monitor patients remotely, reducing the need for frequent in-person visits. This trend has been accelerated by the COVID-19 pandemic, which highlighted the necessity of digital health solutions. Remote monitoring enables healthcare providers to assess neurological conditions regularly, ensuring timely interventions and more effective management of chronic diseases.
Investment in Research and Development
Pharmaceutical companies, medical device manufacturers, and research institutions are investing heavily in the development of digital neuro biomarkers. These investments are focused on creating more sophisticated and precise tools for diagnosing and monitoring neurological diseases. The rising interest in personalized medicine, which aims to tailor treatments to individual patient needs, is also contributing to the demand for digital biomarkers. As these innovations continue to emerge, the market is likely to see enhanced product offerings and broader adoption in clinical settings.
Market Trends
Integration of AI and Machine Learning
One of the most prominent trends in the digital neuro biomarkers market is the increasing integration of artificial intelligence (AI) and machine learning (ML) technologies. These advanced tools are enhancing the analysis of large datasets generated from digital biomarkers, enabling more accurate predictions and early detection of neurological diseases. For instance, Roche has demonstrated that AI-driven digital biomarkers can reduce sample sizes in clinical trials by 70%, significantly improving efficiency. AI-driven platforms are being used to automate the interpretation of complex neurological data, improving the efficiency of clinical trials and personalized treatment approaches. This integration is revolutionizing the way healthcare providers diagnose and monitor patients with neurodegenerative disorders.
Expansion of Wearable and Mobile Health Technologies
Wearable devices and mobile health applications are becoming integral to the digital neuro biomarkers landscape. These technologies allow for continuous, real-time monitoring of patients' neurological functions, providing valuable insights into disease progression and response to treatment. The portability and convenience of these devices enable patients to track their symptoms outside of clinical settings, making healthcare more accessible. The growing demand for non-invasive, user-friendly devices is driving further innovation in this segment, with new products constantly being developed to meet evolving patient and provider needs.
Increasing Focus on Personalized Medicine
The shift towards personalized medicine is a key trend shaping the digital neuro biomarkers market. Digital biomarkers are playing a crucial role in tailoring treatment plans to individual patients by providing detailed insights into their unique neurological conditions. This personalized approach is improving treatment outcomes and reducing healthcare costs by enabling more targeted therapies and interventions. As the healthcare industry continues to embrace precision medicine, the demand for digital biomarkers that offer specific, patient-centric insights is expected to rise significantly.
Collaboration Between Tech and Healthcare Companies
Collaboration between technology firms and healthcare organizations is becoming increasingly common, driving innovation in digital neuro biomarkers. Partnerships between MedTech companies, pharmaceutical firms, and research institutions are accelerating the development of advanced diagnostic tools and platforms. For instance, NeuroSense Therapeutics Ltd. and NeuraLight collaborated to enhance the development of digital biomarkers for identifying and tracking neurological diseases, such as amyotrophic lateral sclerosis (ALS). These collaborations are fostering the creation of comprehensive, integrated solutions that combine cutting-edge technologies with clinical expertise, supporting the broader adoption of digital biomarkers in healthcare.
Market Challenges Analysis
Data Privacy and Security Concerns
One of the significant challenges in the digital neuro biomarkers market is the issue of data privacy and security. As digital biomarkers rely on continuous monitoring and the collection of sensitive patient data, there is an inherent risk of data breaches or unauthorized access. Ensuring the confidentiality and protection of this data is critical, as healthcare providers and patients are increasingly concerned about the security of personal health information. Strict regulations, such as the Health Insurance Portability and Accountability Act (HIPAA) in the United States, require companies to implement robust security measures. However, the evolving nature of digital health technologies often outpaces regulatory frameworks, leading to uncertainty about compliance and data protection practices. For instance, Roche's digital biomarker platform, developed in collaboration with the Michael J. Fox Foundation, allows patients to carry mobile phones with them to collect data on Parkinson's disease symptoms. This challenge presents barriers to the widespread adoption of digital neuro biomarkers, as patients and healthcare providers may hesitate to embrace these technologies without clear guarantees regarding data safety. Additionally, any security breaches or mishandling of patient data could result in reputational damage and legal ramifications, further discouraging innovation in the market.
Integration with Existing Healthcare Systems
Another key challenge in the digital neuro biomarkers market is the integration of new digital health technologies into existing healthcare systems. Many healthcare institutions still rely on traditional diagnostic methods and are often slow to adopt innovative technologies due to budget constraints, lack of infrastructure, and resistance to change. The seamless integration of digital neuro biomarkers into existing workflows and electronic health records (EHR) systems can be complex and resource-intensive, requiring significant technical expertise and collaboration between technology providers and healthcare organizations. Additionally, healthcare professionals need to be adequately trained to interpret and utilize the data generated by digital biomarkers, which may require substantial investment in training and education. This slow adoption and integration process can limit the effectiveness and reach of digital neuro biomarkers, hindering their potential to transform neurological disease management. Furthermore, inconsistent interoperability across platforms can impede data sharing and collaboration between institutions, slowing the widespread use of these technologies.
Market Opportunities
The digital neuro biomarkers market presents significant growth opportunities driven by the increasing demand for personalized healthcare solutions and early-stage disease detection. As the healthcare industry shifts toward precision medicine, digital neuro biomarkers play a pivotal role in tailoring treatment plans specific to individual patients. This growing focus on personalized care is leading to higher adoption of digital biomarkers that offer insights into neurological health, allowing for targeted therapies that improve patient outcomes. Additionally, as the global prevalence of neurological disorders continues to rise, the need for advanced diagnostic tools and continuous monitoring becomes more critical. Digital neuro biomarkers can address these needs by providing real-time data and enabling early intervention, thereby presenting substantial growth potential for companies in this sector.
Another key opportunity lies in the expanding applications of digital neuro biomarkers within clinical trials and drug development processes. Pharmaceutical companies are increasingly turning to digital biomarkers to streamline the clinical trial process, improve patient selection, and reduce the time and cost associated with bringing new drugs to market. The ability to remotely monitor patients' neurological conditions through digital biomarkers allows for more frequent and accurate assessments, enhancing the efficiency of clinical trials. Moreover, as regulatory agencies become more open to incorporating digital health solutions into drug approval processes, there is growing potential for digital biomarkers to be integrated into mainstream healthcare practices. These opportunities position the digital neuro biomarkers market for significant growth, with the promise of improving the management of neurological diseases and accelerating the development of innovative treatments.
Market Segmentation Analysis:
By Type
The digital neuro biomarkers market is segmented based on type into imaging biomarkers, genetic biomarkers, and electrophysiological biomarkers. Imaging biomarkers dominate the market, providing detailed insights into brain activity through advanced imaging technologies. Genetic biomarkers are also gaining traction, offering genetic insights for disease prediction, while electrophysiological biomarkers are increasingly used for monitoring neural activity and brain functions.
By Clinical Practice
In clinical practice, digital neuro biomarkers are applied in neurology, psychiatry, and cognitive health. Neurology holds the largest share due to the growing need for precise monitoring of conditions like Parkinson’s and Alzheimer's disease. Psychiatric applications are also expanding, with digital biomarkers being used for diagnosing and managing mood and behavioral disorders, while cognitive health applications focus on early detection and intervention for cognitive decline.
By End Use
The market is segmented by end use into hospitals, research institutes, and diagnostic centers. Hospitals are the largest end-user segment, adopting digital neuro biomarkers to improve patient monitoring and diagnosis. Research institutes leverage these technologies for drug development and clinical trials, while diagnostic centers focus on offering advanced diagnostic services to support early-stage disease detection.
Segments:
Based on Type
- Wearable
- Mobile-Based Applications
- Sensors
- Others
Based on Clinical Practice
- Diagnostic Digital Neuro Biomarker
- Monitoring Digital Neuro Biomarkers
- Predictive and Prognostic Digital Neuro Biomarkers
Based on End-use
- Healthcare Companies
- Healthcare Providers
- Payers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America is the largest regional market for digital neuro biomarkers, accounting for a significant share in 2024. The region's dominance is primarily due to the advanced healthcare infrastructure, widespread adoption of digital health technologies, and high levels of investment in research and development. The United States, in particular, leads in the integration of digital biomarkers into clinical practice and clinical trials, driven by an aging population and the rising prevalence of neurological disorders such as Alzheimer's and Parkinson's diseases. Additionally, the presence of major players in the MedTech and pharmaceutical industries further strengthens the market position. North America is expected to maintain its leading market share due to continuous advancements in digital health technologies and favorable regulatory frameworks, projected to hold 45% of the global market share in 2024.
Europe
Europe holds a substantial market share in 2024, driven by increasing adoption of digital neuro biomarkers in clinical research and diagnostic settings. Countries like Germany, the UK, and France are at the forefront of integrating these technologies into healthcare systems. The region benefits from strong healthcare infrastructure, government initiatives promoting digital health, and significant investments in medical research. The rising burden of neurological disorders in Europe, particularly among the elderly population, has led to a higher demand for non-invasive diagnostic tools. Europe is expected to capture 30% of the global market share in 2024, with continuous innovation and collaborations between healthcare providers and technology companies.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the digital neuro biomarkers market, projected to account for 15% of the global market share in 2024. This growth is fueled by an increasing healthcare expenditure, rising awareness about neurological diseases, and the expanding healthcare infrastructure in countries like China, Japan, and India. The region is also seeing a surge in research and development activities, with several healthcare providers and tech companies focusing on improving the diagnosis and treatment of neurological disorders. The adoption of wearable health devices and mobile health applications is accelerating the use of digital neuro biomarkers in clinical practice, particularly in urban areas.
Rest of the World
The Rest of the World (RoW) region, which includes Latin America, the Middle East, and Africa, is gradually emerging as a growing market for digital neuro biomarkers. In 2024, this region is expected to hold 10% of the global market share. The increasing prevalence of neurological disorders, improving healthcare access, and investments in medical technologies are contributing to the market's growth. However, limited healthcare infrastructure and economic challenges in certain regions may slow the adoption of advanced digital biomarkers in these areas. Despite these challenges, the market is anticipated to grow steadily, driven by rising demand for innovative healthcare solutions.
Key Player Analysis
- NeuraLight
- NeuraMetrix
- Enrolmmun
- Qiagen
- Koneksa
- Linus Health
- Thermo Fisher Scientific
- Neurotrack Technologies, Inc.
- Altoida Inc.
- RCSI
- Biogen Inc.
- Merck KGaA
Competitive Analysis
The digital neuro biomarkers market is highly competitive, with leading players like Altoida Inc., Koneksa, Biogen Inc., Roche (Navify), NeuraMetrix, Merck KGaA, Linus Health, Neurotrack Technologies, Inc., Huma, NeuraLight, RCSI, Qiagen, ADx NeuroSciences NV, Enrolmmun, and Thermo Fisher Scientific. These companies are at the forefront of innovation, developing advanced technologies and solutions to improve the diagnosis, monitoring, and treatment of neurological diseases. The market is characterized by strong investments in research and development, strategic partnerships, and collaborations. For instance, companies like Biogen and Koneksa are leveraging digital biomarkers to enhance clinical trials and drug development processes, while others such as Altoida and NeuraMetrix are focusing on wearable devices and AI-powered diagnostics. Moreover, players are increasingly adopting personalized medicine approaches to cater to the growing demand for precision healthcare. Despite the competition, the ongoing advancements in AI, machine learning, and wearable technologies are driving market growth and fostering a dynamic competitive environment.
Recent Developments
- In February 2023, ActiGraph and uMotif formed a partnership to deliver patient-centric solutions for clinical research. This collaboration integrates ActiGraph’s wearable technology with uMotif’s patient engagement platform.
- In March 2023, Koneksa expanded its partnership with SSI Strategy to promote the broader adoption of its in-house digital biomarker solutions for clinical trials, with SSI poised to support this increased demand.
- In March 2024, Merck joined the LEARNS study, an observational initiative focused on using digital biomarkers to assess and predict the progression of Parkinson's disease. By partnering with Koneksa, the study’s lead organization, Merck gained access to real-time data throughout the trial.
- In April 2024 , Indivi, a MedTech company based in Basel, Switzerland, announced a collaboration with Biogen to advance digital health technologies and develop digital biomarkers for Parkinson’s disease. Biogen licensed its smartphone-based Konectom platform, which enables remote neurological assessments, to Indivi for more precise disease monitoring.
- In May 2024, RCSI (Royal College of Surgeons in Ireland), in collaboration with Head Diagnostics, launched a new study aimed at enhancing the assessment and monitoring of multiple sclerosis (MS) using advanced diagnostic techniques. The research leverages innovative technologies to improve the accuracy of MS management, allowing for more precise monitoring and personalized treatment.
Market Concentration & Characteristics
The digital neuro biomarkers market is moderately concentrated, with a few key players holding significant market share while also witnessing the entry of new innovators and startups. Major companies like Biogen, Roche, and Merck KGaA dominate the landscape, leveraging substantial investments in research and development to drive innovation. These industry leaders are focused on integrating cutting-edge technologies, such as artificial intelligence and wearable devices, into their offerings to enhance diagnostic precision and disease management. Additionally, partnerships and collaborations between MedTech firms, healthcare providers, and research organizations play a crucial role in advancing market development. The market is characterized by a strong emphasis on personalized medicine and non-invasive solutions, with a growing demand for remote patient monitoring tools. While large players continue to lead, the market's evolving nature fosters a dynamic environment where new entrants are contributing to the diversification of available digital neuro biomarkers solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Clinical Practice, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The digital neuro biomarkers market is expected to see continued growth as demand for personalized and precision medicine increases.
- Advancements in artificial intelligence and machine learning will significantly enhance the accuracy of digital neuro biomarkers in diagnosing neurological disorders.
- The integration of wearable devices and mobile health apps will become more widespread, enabling continuous and non-invasive monitoring of neurological functions.
- Digital biomarkers will play an increasingly vital role in clinical trials, improving the efficiency of drug development and patient recruitment.
- Partnerships between pharmaceutical companies, tech firms, and healthcare providers will drive innovation in digital neuro biomarkers solutions.
- The adoption of remote patient monitoring technologies will expand, offering more accessible healthcare and improving patient outcomes.
- Regulatory bodies will likely develop clearer guidelines for digital health technologies, fostering more widespread adoption.
- Market expansion will be driven by growing awareness of neurological diseases and the need for early diagnosis and timely interventions.
- Emerging markets, particularly in Asia-Pacific and Latin America, will see a rise in the use of digital neuro biomarkers due to improved healthcare infrastructure.
- Research and development investments will continue to focus on creating more sophisticated, AI-powered diagnostic tools for neurological conditions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Digital Neuro Biomarkers Market?
What factors are driving the growth of the Digital Neuro Biomarkers Market?
What are some challenges faced by the Digital Neuro Biomarkers Market?
Who are the major players in the Digital Neuro Biomarkers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Neuro Biomarkers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Neuro Biomarkers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 706.96 million → 2032: USD 4002.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Neuro Biomarkers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Neuro Biomarkers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Neuro Biomarkers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Neuro Biomarkers Market Drivers
- 3.3 Digital Neuro Biomarkers Market Restraints & Challenges
- 3.4 Digital Neuro Biomarkers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Neuro Biomarkers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Neuro Biomarkers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Neuro Biomarkers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Neuro Biomarkers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Digital Neuro Biomarkers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Digital Neuro Biomarkers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Neuro Biomarkers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Neuro Biomarkers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Digital Neuro Biomarkers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Neuro Biomarkers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Digital Neuro Biomarkers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Neuro Biomarkers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Digital Neuro Biomarkers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Neuro Biomarkers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Neuro Biomarkers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Neuro Biomarkers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Neuro Biomarkers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Neuro Biomarkers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Neuro Biomarkers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
