
Market Overview:
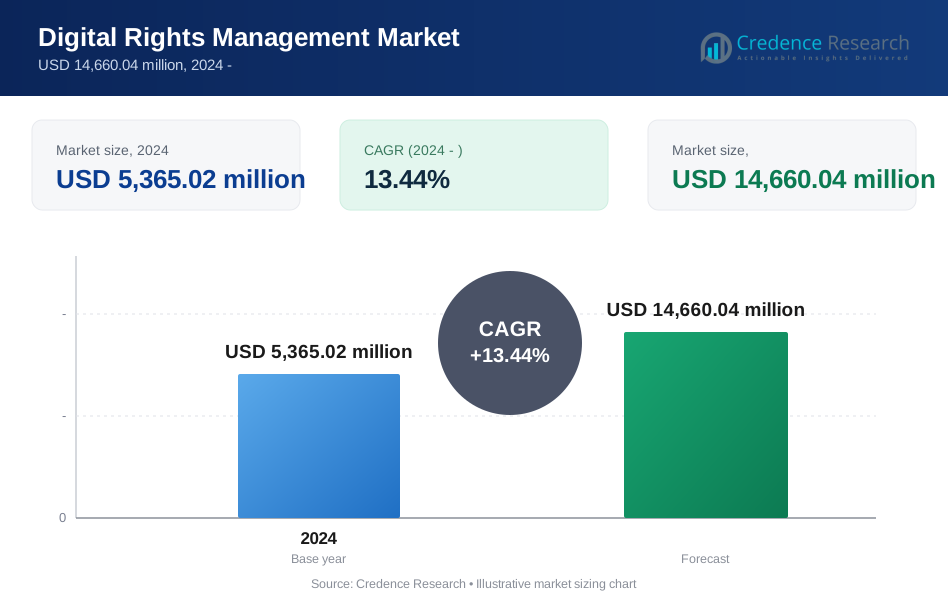
Digital Rights Management market size was valued at USD 3,560.00 million in 2018, reached USD 5,365.02 million in 2024, and is anticipated to reach USD 14,660.04 million by 2032, at a CAGR of 13.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Rights Management Market Size 2024 | USD 5,365.02 million |
| Digital Rights Management Market, CAGR | 13.44% |
| Digital Rights Management Market Size 2032 | USD 14,660.04 million |
The Digital Rights Management (DRM) market is led by major technology firms such as Adobe Systems Inc., Microsoft Corporation, Apple Inc., Google LLC, IBM Corporation, Oracle Corporation, and Sony Corporation, along with specialized vendors like Irdeto, Verimatrix, and Seclore. These companies maintain a competitive edge through robust product portfolios, global distribution networks, and strategic investments in cloud and AI-driven DRM solutions. North America emerges as the leading region in the global DRM market, holding a dominant 35.3% market share in 2024. This leadership is attributed to the region’s advanced digital infrastructure, strong regulatory framework, and high adoption of digital content across media, education, and enterprise sectors. The presence of key market players and early technology adoption further reinforces North America’s position as the most influential market for DRM solutions.

Market Insights
- The Digital Rights Management (DRM) market was valued at USD 3,560.00 million in 2018, reached USD 5,365.02 million in 2024, and is projected to hit USD 14,660.04 million by 2032, growing at a CAGR of 13.44% during the forecast period.
- Market growth is driven by rising digital content consumption, increasing piracy threats, and growing regulatory compliance needs across sectors such as media, education, and enterprise IT.
- Key trends include the integration of DRM with cloud-based platforms, rising adoption in non-traditional sectors like healthcare and legal, and the shift toward AI-powered content protection tools.
- The market is highly competitive with major players like Adobe, Microsoft, Apple, and Google leading innovation, while niche providers offer tailored, industry-specific solutions.
- North America led the market in 2024 with a 35.3% share, followed by Europe at 27.4% and Asia Pacific at 25.2%; the solution segment held the dominant share among components.
Market Segmentation Analysis:
By Component
The Digital Rights Management (DRM) market is segmented into Solution and Services, with the Solution segment accounting for the largest market share in 2024. This dominance is primarily driven by the rising demand for robust content protection tools across media, software, and enterprise content workflows. Solutions provide advanced encryption, licensing, and access control features that help organizations safeguard intellectual property and prevent piracy. Although Services, including Consulting, Integration, and Operation & Maintenance, are witnessing steady growth due to increasing implementation complexity, the Solution segment remains the core focus for most DRM deployments due to its direct role in content protection.
- For instance, Microsoft Azure Rights Management supports over 2.5 billion documents under protection, offering enterprise-scale encryption and access controls for data across Office 365 and Azure environments.
By Application
Video Content emerged as the dominant application segment in the DRM market, capturing the largest market share in 2024. The proliferation of streaming platforms, online education, and on-demand entertainment services has significantly fueled demand for video protection solutions. DRM technologies ensure secure distribution and control of high-value video content across devices and platforms. While Audio Content and Software & Games also contribute significantly to market growth, the need for dynamic watermarking, adaptive encryption, and playback restrictions in video streaming continues to drive higher adoption rates. Other applications, including eBooks and document protection, are expected to see moderate growth due to rising corporate and educational digitalization.
- For instance, Google’s Widevine DRM is embedded in over 5 billion devices globally, enabling encrypted video streaming for platforms like Netflix and Disney+.
By Deployment
The Cloud deployment segment leads the market with a considerable share in 2024, driven by its scalability, cost-efficiency, and ease of integration across various digital ecosystems. Organizations increasingly favor cloud-based DRM solutions to support remote access, reduce infrastructure costs, and enable real-time content protection updates. On-Premise deployment, while still relevant in industries with stringent regulatory or data privacy requirements, has seen a gradual decline in preference due to higher upfront costs and limited flexibility. The growing shift towards digital-first business models and content distribution is expected to reinforce the dominance of cloud-based DRM solutions in the forecast period.
Market Overview
Surge in Digital Content Consumption
The rapid increase in digital content consumption across platforms—particularly video streaming, eBooks, and online music—is a major growth driver for the Digital Rights Management (DRM) market. As consumers shift toward digital-first entertainment and information sources, content creators and distributors prioritize the protection of intellectual property. This trend is particularly evident in sectors like media and publishing, where unauthorized content access and piracy pose serious revenue threats. DRM solutions help mitigate these risks by enforcing access controls, licensing frameworks, and usage restrictions, thereby securing digital assets in a growing global content ecosystem.
- For instance, Apple’s FairPlay DRM encrypts and protects millions of tracks and videos delivered through the iTunes Store and Apple TV+, with FairPlay integrated into over 1.5 billion active Apple devices worldwide.
Regulatory Compliance and Data Security Requirements
The implementation of global data protection laws such as GDPR, HIPAA, and copyright regulations has heightened the demand for DRM solutions. Organizations across industries are adopting DRM tools to ensure compliance with legal requirements related to data privacy, intellectual property, and user rights. In particular, sectors such as healthcare, finance, and legal services are increasingly deploying DRM to manage document security, audit trails, and secure file sharing. These compliance pressures drive sustained investment in DRM technology to meet evolving regulatory standards and protect sensitive content in both internal and customer-facing systems.
- For instance, Seclore’s Enterprise DRM secures over 2 billion documents annually for compliance in sectors like BFSI and government across more than 1,000 enterprise deployments.
Proliferation of BYOD and Remote Work Models
The widespread adoption of Bring Your Own Device (BYOD) policies and remote work environments has increased the risk of data leakage and unauthorized content access. As enterprise content moves beyond traditional firewalls, DRM solutions offer critical tools for securing documents, presentations, and proprietary software across diverse endpoints. The ability to control content usage based on identity, device, and location is particularly valuable in hybrid workplaces. Organizations are adopting DRM to enable secure collaboration while protecting intellectual property, making it a key enabler of digital workplace transformation and operational agility.
Key Trends & Opportunities
Integration with Cloud-Based Content Management Systems
The integration of DRM with cloud-based content management systems (CMS) is an emerging trend offering scalability, real-time content tracking, and centralized control. Organizations are leveraging this synergy to enhance content security across distributed teams and digital distribution channels. Cloud-native DRM solutions facilitate seamless protection of video, audio, and documents without impacting accessibility. As more enterprises migrate to cloud-based collaboration platforms, the demand for integrated DRM functionality presents significant growth opportunities for solution providers aiming to offer unified and adaptable digital security frameworks.
- For instance, Adobe Experience Manager integrates Adobe Primetime DRM to protect video assets and supports over 7 billion DRM license requests annually from streaming and broadcast media clients.
Expansion into Non-Traditional Sectors
DRM adoption is expanding beyond traditional media and entertainment sectors into education, healthcare, and legal domains. These industries increasingly rely on digital content such as training modules, patient records, and confidential legal documents that require secure access and sharing. Educational institutions, for example, are utilizing DRM to prevent unauthorized distribution of online courses and examination materials. This diversification presents opportunities for vendors to tailor DRM offerings to meet sector-specific requirements, thereby broadening the addressable market and driving innovation in specialized DRM capabilities.
- For instance, Locklizard DRM protects over 25 million confidential documents annually in sectors including education, legal, and corporate training, offering print control, dynamic watermarking, and offline access controls.
Key Challenges
Complex Integration and High Implementation Costs
Despite its benefits, DRM solutions often involve complex integration with existing IT systems, particularly in large enterprises with diverse digital infrastructures. The initial setup, licensing models, and need for customization can lead to high implementation costs. These challenges are more pronounced for small and medium-sized enterprises with limited IT budgets. The perceived cost-to-value imbalance may deter potential adopters, slowing down market penetration and requiring vendors to offer flexible, scalable solutions with simplified deployment options to appeal to a broader audience.
User Resistance and Impact on Experience
End-users often resist DRM implementations due to the restrictions imposed on content access, usage, and sharing. In some cases, DRM can disrupt user experience by requiring frequent authentication, limiting device compatibility, or reducing functionality—especially in consumer-facing applications like streaming services or eBooks. This friction can lead to dissatisfaction and hinder content adoption. Striking a balance between security and user convenience remains a critical challenge for vendors, pushing them to innovate DRM technologies that are both robust and minimally intrusive.
Evolving Piracy Techniques and Cyber Threats
As DRM technologies advance, so do the techniques employed by pirates and cybercriminals to bypass them. From screen recording tools to DRM circumvention software, malicious actors continually find ways to access and distribute protected content illegally. Keeping up with these rapid developments requires significant investment in R&D and continuous system upgrades, posing a major challenge to maintaining long-term DRM effectiveness and reliability.
Regional Analysis
North America
North America dominated the Digital Rights Management (DRM) market in 2024 with the highest market share of approximately 35.3%, valued at USD 1,891.67 million, up from USD 1,270.92 million in 2018. The region is projected to reach USD 5,161.83 million by 2032, registering a strong CAGR of 13.4%. This growth is driven by advanced technological adoption, widespread digital content consumption, and a strong regulatory framework supporting data protection. The presence of key market players and a mature digital infrastructure further accelerates DRM adoption, particularly across the media, IT, and education sectors, reinforcing the region’s leadership in the global market.
Europe
Europe accounted for 27.4% of the global DRM market share in 2024, reaching USD 1,471.48 million, compared to USD 1,012.82 million in 2018. It is forecasted to grow to USD 3,815.32 million by 2032, at a CAGR of 12.7%. The market expansion in Europe is primarily driven by strict regulatory compliance, including GDPR, which compels enterprises to secure sensitive content and data. The increasing adoption of DRM in publishing, legal, and healthcare sectors also supports growth. European organizations are prioritizing secure content distribution and copyright protection, contributing to steady demand for both cloud and on-premise DRM solutions.
Asia Pacific
Asia Pacific is the fastest-growing region in the DRM market, with a projected CAGR of 14.8% and a 2024 market share of 25.2%, valued at USD 1,352.23 million, up from USD 858.67 million in 2018. The market is expected to grow significantly, reaching USD 4,082.83 million by 2032. This rapid expansion is fueled by digital transformation across emerging economies like China, India, and Southeast Asia. Increasing mobile and internet penetration, rising content creation, and expanding e-learning platforms are driving the adoption of DRM technologies. The growing demand for software and media protection in entertainment and education continues to boost regional growth.
Latin America
Latin America held a 6.1% market share in the global DRM market in 2024, reaching USD 325.07 million, up from USD 217.87 million in 2018. The market is projected to reach USD 821.99 million by 2032, growing at a CAGR of 12.4%. The region’s DRM adoption is driven by increasing digital content usage, expansion of the streaming industry, and the rising need to combat intellectual property theft. Countries like Brazil and Mexico are witnessing a surge in digital media and enterprise content management, encouraging businesses to invest in DRM solutions for secure content delivery and data privacy compliance.
Middle East
In 2024, the Middle East accounted for 3.3% of the global DRM market, valued at USD 178.08 million, up from USD 126.74 million in 2018. It is expected to reach USD 435.48 million by 2032, registering a CAGR of 11.9%. The regional market growth is supported by expanding digital infrastructure, government-led digital transformation initiatives, and rising demand for secure digital distribution in sectors such as media and finance. While still developing compared to Western markets, the region shows strong potential as organizations increasingly prioritize data protection, copyright enforcement, and compliance with digital content regulations.
Africa
Africa represented a 2.7% share of the global DRM market in 2024, with a market size of USD 146.49 million, growing from USD 72.98 million in 2018. The region is forecasted to reach USD 342.59 million by 2032, with a CAGR of 10.8%. DRM adoption in Africa is gradually increasing due to expanding internet access, growth in mobile content consumption, and the emergence of local streaming and educational platforms. However, infrastructure limitations and budget constraints remain challenges. Despite slower uptake compared to other regions, ongoing digitalization and rising awareness around content protection are expected to drive moderate market growth.

Market Segmentations:
By Component
- Solution
- Services
- Consulting
- Integration
- Operation & Maintenance
By Application
- Audio Content
- Images
- Video Content
- Confidential Documents, Spreadsheets, Presentations
- Software & Games
- eBooks
- Other Applications
By Deployment
- On-Premise
- Cloud
By Organization Size
- Small and Medium Enterprises
- Large Enterprises
By Verticals
- BFSI
- Education & Training / Research & Publications
- Media & Entertainment
- IT & ITeS
- Healthcare
- Legal
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Digital Rights Management (DRM) market is characterized by the presence of several global technology leaders and specialized solution providers. Key players such as Adobe Systems Inc., Microsoft Corporation, Apple Inc., Google LLC, and IBM Corporation dominate the market through comprehensive product portfolios, strong brand equity, and extensive customer bases. These companies focus on continuous innovation, strategic partnerships, and acquisitions to strengthen their DRM offerings and expand their global footprint. In addition to tech giants, niche players like Irdeto, Verimatrix, Seclore, and Vitrium Systems play a vital role by offering industry-specific and highly customizable DRM solutions. The market is witnessing increased investment in cloud-based and AI-integrated DRM tools, driven by the demand for scalable, real-time content protection. As competition intensifies, vendors are prioritizing user experience, compliance capabilities, and seamless integration with enterprise ecosystems to differentiate themselves. Overall, the landscape is dynamic, with innovation and security emerging as key competitive parameters.
Key Player Analysis
- Adobe Systems Inc.
- Apple Inc.
- Microsoft Corporation
- Google LLC
- Oracle Corporation
- IBM Corporation
- Sony Corporation
- Irdeto
- OpenText Corporation
- Kudelski Group
- VeriSign Inc.
- Vitrium Systems
- NextLabs Inc.
- Verimatrix
- Seclore
- Digify
Recent Developments
- In April 2025, Microsoft enhanced DRM licensing for PC games in the Microsoft Store, introducing a layered security approach. This includes game-initiated license checks and recommendations for anti-tamper mechanisms, aiming to prevent unauthorized access and fake licenses.
- In March 2025, Adobe Experience Manager (AEM) received updates focusing on asset rights management, specifically enhancing DRM with license enforcement. Users must now accept license agreements before downloading DRM-protected assets, with new storage for license data to improve compliance workflows. This ensures proper usage and adherence to licensing terms for protected assets within AEM.
- In January 2025, Oracle released Critical Patch Updates (CPUs) that addressed several vulnerabilities across various product families, including their Data Relationship Management (DRM) suite, by mitigating issues related to remote access and permission management within Oracle Enterprise Manager and related systems.
- In January 2025, Apple continues to strengthen FairPlay DRM, focusing on enhanced content protection for music, video streaming, and offline playback across its devices. The system now features hardware-level DRM for robust protection and expanded real-time key management for AirPlay and device-to-device content transfer.
Market Concentration & Characteristics
The Digital Rights Management Market displays a moderately concentrated structure, dominated by a mix of global technology giants and specialized solution providers. Leading companies such as Adobe, Microsoft, Apple, and Google hold significant market shares due to their strong product portfolios, global reach, and integration capabilities across devices and platforms. It exhibits characteristics of a mature but evolving industry, with vendors competing on the basis of content security, scalability, and ease of integration. The market favors innovation, especially in cloud-based and AI-driven solutions, as enterprises seek flexible and robust digital asset protection. It caters to a wide range of industries, including media, software, education, legal, and healthcare, reflecting its versatility and growing importance. Companies focus on compliance, user access control, and real-time protection to meet diverse client needs. The presence of niche players such as Verimatrix, Irdeto, and Seclore enhances the competitive environment by offering targeted solutions tailored to specific industry challenges.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Deployment, Organization Size, Verticals and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily driven by the increasing need to secure digital content across multiple platforms.
- Cloud-based DRM solutions will gain stronger adoption due to their flexibility, scalability, and lower deployment costs.
- Integration of AI and machine learning will enhance real-time content monitoring and threat detection capabilities.
- Video content protection will remain a key focus area due to the expansion of streaming services and online learning platforms.
- Enterprises will prioritize DRM tools that offer seamless integration with content management and collaboration platforms.
- Demand from non-traditional sectors such as healthcare, education, and legal will expand the addressable market.
- The shift to remote work and hybrid models will increase the need for secure file sharing and access control solutions.
- DRM providers will focus on improving user experience while maintaining high security standards.
- Regulatory compliance will drive adoption, especially in regions with strict data privacy laws.
- Emerging markets in Asia Pacific and Latin America will present significant growth opportunities for vendors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Digital Rights Management (DRM) market?
What are the key drivers of growth in the DRM market?
How are innovations like blockchain affecting the DRM market?
Which regions are leading the DRM market?
Why is the DRM market important for businesses?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Rights Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Rights Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 5,365.02 million → forecast year: USD 14,660.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Rights Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Rights Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Rights Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Rights Management Market Drivers
- 3.3 Digital Rights Management Market Restraints & Challenges
- 3.4 Digital Rights Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Rights Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Rights Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Rights Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Rights Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Digital Rights Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Digital Rights Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Rights Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Rights Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Digital Rights Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Rights Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Digital Rights Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Rights Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Digital Rights Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Rights Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Rights Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Rights Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Rights Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Rights Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Rights Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
