
Market Overview:
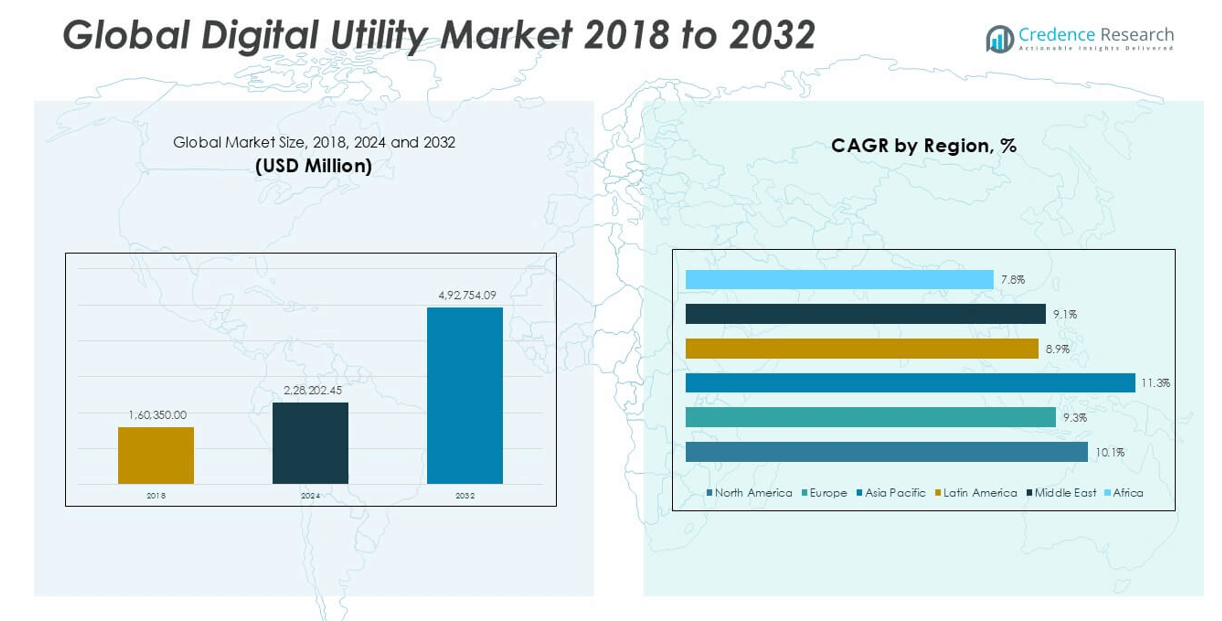
The Digital Utility market size was valued at USD 160,350.00 million in 2018, increased to USD 228,202.45 million in 2024, and is anticipated to reach USD 492,754.09 million by 2032, at a CAGR of 10.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Utility Market Size 2024 | USD 228,202.45 million |
| Digital Utility Market, CAGR | 10.13% |
| Digital Utility Market Size 2032 | USD 492,754.09 million |
The Digital Utility market is dominated by leading players such as ABB, Siemens, Schneider Electric, Microsoft, Oracle, IBM, SAP SE, Cisco Systems, Accenture, and Honeywell International Inc. These companies are at the forefront of driving innovation through AI, IoT integration, cloud platforms, and smart grid technologies. Their strategic partnerships, R&D investments, and focus on grid modernization have significantly influenced the market landscape. Regionally, North America leads the market with a 34% share in 2024, followed closely by Asia Pacific at 28.7%. Both regions benefit from strong infrastructure, regulatory support, and increasing investments in digital transformation.
Market Insights
- The Digital Utility market was valued at USD 228,202.45 million in 2024 and is projected to reach USD 492,754.09 million by 2032, growing at a CAGR of 10.13% during the forecast period.
- Rising demand for smart grid infrastructure, renewable energy integration, and real-time energy monitoring systems are key drivers accelerating digital transformation across utilities.
- Increasing adoption of cloud-based platforms and consumer-centric services are prominent trends, enabling greater efficiency and flexibility in utility operations.
- The market is competitive, with major players including ABB, Siemens, Schneider Electric, Microsoft, IBM, and Oracle focusing on AI, IoT, and data analytics to expand their global presence.
- North America holds the largest regional share at 34%, followed by Asia Pacific at 28.7%; segment-wise, Integrated Solutions lead the technology segment with over 60% share, while Transmission & Distribution dominates the network segment with around 45% share in 2024.
Market Segmentation Analysis:
By Technology
In the Digital Utility market, the Integrated Solutions segment holds the dominant market share, accounting for over 60% in 2024. This dominance is driven by the increasing demand for real-time data analytics, end-to-end smart grid solutions, and cloud-based platforms that optimize utility operations. Integrated solutions enable utilities to streamline asset management, enhance customer engagement, and improve energy distribution efficiency. Additionally, the growing adoption of AI and IoT technologies in utility infrastructure supports the segment’s growth, as utilities increasingly shift from traditional hardware models to more adaptive and scalable digital ecosystems.
- For instance, Siemens implemented its SICAM A8000 remote terminal units across 1,400 transformer stations in Germany, enabling real-time data collection and grid automation for enhanced stability and efficiency.
By Network
The Transmission & Distribution segment leads the market among network segments, contributing more than 45% of the total market share in 2024. This growth is primarily driven by the global push toward smart grid modernization and the integration of renewable energy sources. Utilities are investing heavily in digital tools for real-time monitoring, predictive maintenance, and fault detection across transmission lines. The segment benefits from government mandates for grid reliability and efficiency improvements. Additionally, the increasing frequency of power outages and the need for automated grid management further fuel the demand for digital solutions in transmission and distribution operations.
- For instance, ABB deployed its Ability™ Smart Sensor technology to monitor over 2,000 distribution transformers in Italy, enabling condition-based maintenance and reducing fault response times by up to 60 minutes.
Market Overview
Growing Demand for Smart Grid Infrastructure
The increasing need for grid modernization is a significant driver of the digital utility market. Utilities are rapidly adopting smart grid technologies to improve energy efficiency, reduce transmission losses, and ensure grid reliability. Advanced metering infrastructure (AMI), intelligent control systems, and predictive maintenance tools are in high demand as they support real-time data analysis and automation. Government initiatives and funding for smart grid development further accelerate adoption, especially in developed economies. These systems enable a more responsive and resilient grid, aligning with broader sustainability and energy transition goals.
- For instance, Landis+Gyr delivered over 14 million smart electricity meters to Tokyo Electric Power Company, supporting Japan’s nationwide smart grid development.
Rising Integration of Renewable Energy Sources
The global shift toward renewable energy sources such as solar, wind, and hydroelectric power has increased the complexity of grid operations, necessitating the adoption of digital utility solutions. Integrated digital platforms help utilities manage variable energy inputs and ensure stable power delivery. Energy storage systems, demand response technologies, and digital forecasting tools are essential in managing decentralized energy generation. As countries enforce stricter emission targets, utilities are compelled to upgrade infrastructure with digital tools to efficiently balance traditional and renewable power, boosting the digital utility market growth.
- For instance, GE Vernova deployed its GridOS software suite to support integration of over 3,000 megawatts of distributed renewable resources into California’s electric grid.
Increasing Adoption of IoT and AI Technologies
The proliferation of Internet of Things (IoT) devices and artificial intelligence (AI) is transforming utility operations. IoT-enabled sensors and smart meters provide real-time insights into energy consumption, equipment performance, and system anomalies. AI-driven analytics support predictive maintenance, energy forecasting, and automated decision-making. These technologies enhance operational efficiency, reduce downtime, and optimize resource utilization. With utilities under pressure to reduce costs and improve service reliability, the integration of IoT and AI solutions is becoming a strategic priority, contributing significantly to market expansion.
Key Trends & Opportunities
Shift Toward Cloud-Based Utility Platforms
An increasing number of utility providers are transitioning to cloud-based platforms to improve flexibility, scalability, and cost-efficiency. Cloud computing enables utilities to manage large volumes of data generated from smart meters, IoT devices, and customer portals more effectively. These platforms support real-time analytics, remote monitoring, and integrated services. The trend is especially prominent among small and mid-sized utilities looking to modernize without heavy infrastructure investments. Cloud adoption also opens opportunities for third-party software vendors and platform providers to enter the market with innovative, subscription-based digital utility solutions.
- For instance, Microsoft Azure IoT powers over 1.2 million connected utility assets globally, supporting remote diagnostics and predictive grid analytics.
Growing Focus on Consumer-Centric Digital Services
Utilities are embracing digital transformation to enhance customer engagement and satisfaction. The deployment of mobile apps, personalized billing platforms, and interactive dashboards empowers consumers with greater control over their energy usage. Demand for transparent energy pricing, usage analytics, and real-time notifications has created a need for advanced digital interfaces. This shift toward consumer-centric services not only boosts operational efficiency but also opens new revenue streams through value-added offerings. The trend reflects a broader movement toward customer empowerment in the energy sector and represents a major opportunity for digital innovation.
- For instance, Schneider Electric’s EcoStruxure™ platform helped over 1 million residential users in France monitor and optimize energy usage through mobile-enabled smart meter data.
Key Challenges
High Initial Capital Investment
One of the primary challenges in the digital utility market is the significant upfront investment required for digital transformation. Implementing smart grids, IoT networks, AI-based systems, and cloud infrastructure demands substantial financial resources, which can be a barrier for many utility companies, especially in emerging economies. The long payback period and uncertainty over return on investment may delay decision-making. Moreover, legacy systems require costly upgrades or replacements to integrate with modern platforms, adding to the overall expenditure burden for utility firms.
Cybersecurity and Data Privacy Concerns
As utilities become more digitized and data-driven, the risk of cyberattacks increases. Smart grids, cloud platforms, and connected devices are vulnerable to hacking, data breaches, and unauthorized access. These threats can disrupt operations, compromise customer data, and damage trust. The lack of standardized cybersecurity protocols across regions further complicates protection efforts. Addressing these concerns requires continuous investment in security infrastructure, staff training, and compliance with regulatory frameworks efforts that add complexity and cost to digital utility deployments.
Integration Challenges with Legacy Infrastructure
Utilities operating with aging infrastructure face technical difficulties in integrating modern digital systems with legacy equipment. Many existing grid assets lack the compatibility and connectivity required for seamless digital adoption. As a result, integration may necessitate expensive retrofitting or replacement of components. Additionally, workforce skill gaps in handling advanced digital tools can slow down implementation. These integration hurdles pose a challenge to achieving full-scale digital transformation, particularly in regions where utility systems are outdated or under-resourced.
Regional Analysis
North America
North America dominated the global digital utility market in 2024 with a market value of USD 77,724.39 million, rising from USD 55,320.75 million in 2018 and projected to reach USD 167,586.55 million by 2032, registering a CAGR of 10.1%. The region held approximately 34% of the global market share in 2024, driven by early adoption of smart grid technologies, strong regulatory support, and significant investment in utility digitalization. The U.S. remains the key contributor due to its advanced infrastructure and integration of AI and IoT in grid operations, enhancing operational efficiency and customer engagement.
Europe
Europe accounted for around 24.5% of the global digital utility market share in 2024, with a market size of USD 55,766.44 million, up from USD 40,825.11 million in 2018, and is expected to reach USD 113,507.22 million by 2032 at a CAGR of 9.3%. The region's growth is supported by strong environmental regulations, increasing renewable energy integration, and widespread deployment of smart meters and digital platforms. Countries like Germany, the UK, and France are at the forefront of this transformation, focusing on energy efficiency, demand-side management, and digital consumer interfaces to align with EU climate targets.
Asia Pacific
Asia Pacific emerged as the fastest-growing regional market with a CAGR of 11.3%, reaching USD 65,504.55 million in 2024 from USD 44,288.67 million in 2018 and projected to hit USD 154,478.80 million by 2032. The region captured approximately 28.7% of the global digital utility market share in 2024. Rapid urbanization, increasing energy demand, and government investments in smart grid infrastructure are key growth enablers. China, India, and Japan are major contributors, investing heavily in digital platforms, automation, and AI to modernize utility systems and support large-scale renewable integration into national grids.
Latin America
Latin America's digital utility market reached USD 11,864.24 million in 2024, up from USD 8,434.41 million in 2018, and is forecasted to grow to USD 23,391.03 million by 2032, registering a CAGR of 8.9%. The region held a 5.2% share of the global market in 2024. The growth is supported by increasing government initiatives to reduce transmission losses, upgrade aging infrastructure, and implement smart metering programs. Brazil and Mexico lead regional adoption, focusing on enhancing grid reliability and integrating distributed energy resources through digital platforms to ensure long-term energy sustainability and customer satisfaction.
Middle East
The Middle East digital utility market stood at USD 10,564.29 million in 2024, up from USD 7,809.05 million in 2018, and is projected to reach USD 21,092.59 million by 2032, growing at a CAGR of 9.1%. The region accounted for 4.6% of the global market share in 2024. Driven by the need to diversify energy sources and improve grid efficiency, countries like the UAE and Saudi Arabia are investing in digital transformation. These efforts are aligned with national visions such as Saudi Vision 2030, focusing on smart infrastructure, renewable integration, and enhanced consumer energy management.Africa
Africa held the smallest share of the global digital utility market at 3% in 2024, with a value of USD 6,778.54 million, growing from USD 3,672.02 million in 2018 and projected to reach USD 12,697.90 million by 2032 at a CAGR of 7.8%. The market is expanding gradually due to rising electricity access programs, investments in off-grid and mini-grid solutions, and donor-backed smart grid initiatives. Countries like South Africa, Kenya, and Nigeria are beginning to adopt digital technologies to manage energy distribution, reduce outages, and expand reach in underserved rural areas, despite challenges with infrastructure and funding.
Market Segmentations:
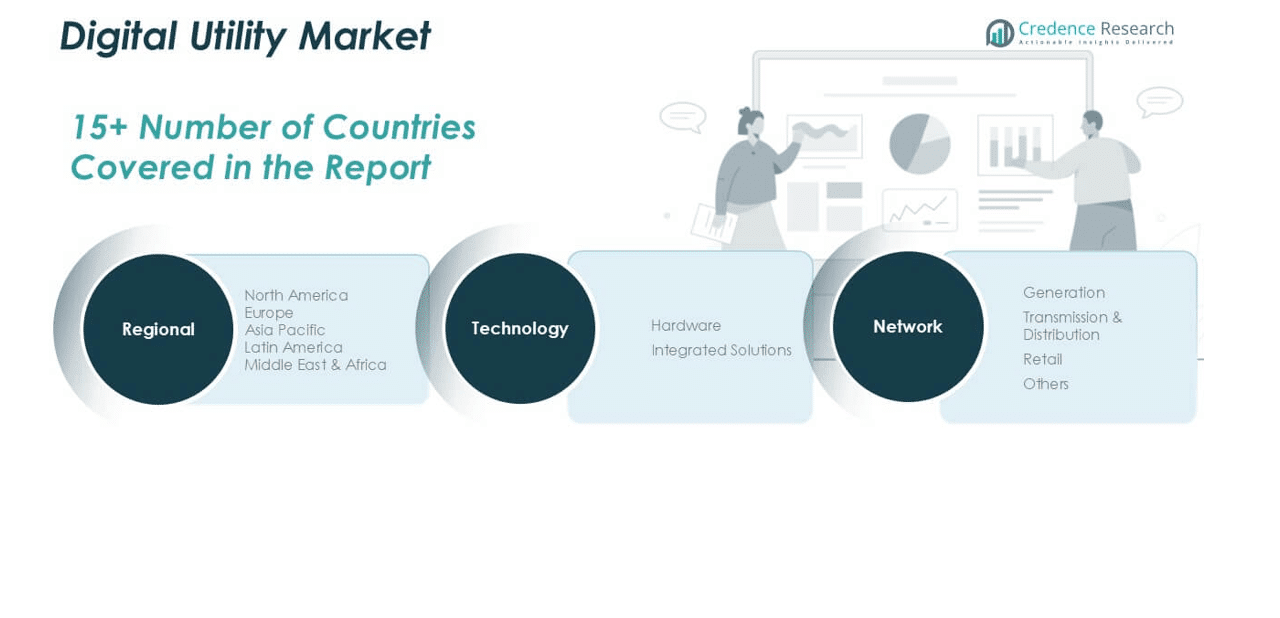
By Technology
- Hardware
- Integrated Solutions
By Network
- Generation
- Transmission & Distribution
- Retail
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the digital utility market is characterized by the presence of several global technology and industrial leaders, each aiming to strengthen their market position through strategic collaborations, product innovations, and digital transformation initiatives. Key players such as ABB, Siemens, Schneider Electric, Microsoft, Oracle, and IBM are actively investing in smart grid technologies, cloud platforms, and AI-driven analytics to offer comprehensive digital utility solutions. These companies are focused on enhancing energy efficiency, grid reliability, and customer engagement for utility providers. Strategic partnerships between software firms and utility operators have become increasingly common, enabling end-to-end digital solutions that integrate IT and operational technologies. Additionally, firms like SAP SE, Cisco Systems, and Accenture are leveraging their expertise in enterprise software and consulting services to support digital transitions across the utility sector. The market remains highly competitive, with firms continuously enhancing their offerings to cater to growing global demand for intelligent, resilient, and sustainable utility infrastructure.
Key Player Analysis
- ABB
- Accenture
- Cisco Systems, Inc.
- Honeywell International Inc.
- International Business Machines Corporation
- Microsoft
- Oracle
- SAP SE
- Schneider Electric
- Siemens
Recent Developments
- In July 2025, IBM launched Power11 servers, a major upgrade supporting AI, hybrid cloud, and high-resiliency digital utility workloads on-premises or in cloud, aiming to bolster performance and scalability for utility sector digital transformation.
- In June 2025 ABB, in partnership with Applied Digital, launched a groundbreaking power infrastructure solution tailored for AI-ready data centers at a 400 MW campus in North Dakota. Central to this is ABB's HiPerGuard Medium Voltage Static UPS, boosting grid reliability, scalability, and energy efficiency essential for the next wave of AI-powered digital utilities.
- In June 2025, Accenture restructured its business into an integrated “Reinvention Services” unit to better embed AI and data into digital utility solutions, aiming to accelerate the adoption of trusted, AI-powered services sector-wide.
- In June 2025, Cisco unveiled innovations in AI-ready, secure data center networks and campus architectures, simplifying infrastructure scaling for utilities integrating AI and IoT. These include centralized management, new AI-optimized networking devices, and advanced security features for digital grid environments.
- In June 2025, Honeywell expanded its Digital Prime ecosystem to support utilities’ transition from automation to full autonomy using new AI-enabled digital suites.
Market Concentration & Characteristics
The Digital Utility Market exhibits a moderately concentrated structure, with a mix of global technology leaders and specialized solution providers holding significant shares. It features a blend of industrial giants like Siemens, ABB, Schneider Electric, and Microsoft that offer end-to-end digital utility solutions, alongside niche players focusing on specific segments such as grid automation or analytics. It is characterized by high capital intensity, long project cycles, and strong dependency on regulatory frameworks and infrastructure readiness. The market reflects a high degree of technological integration, with AI, IoT, and cloud computing central to product offerings. Vendor differentiation depends on platform scalability, cybersecurity capabilities, and interoperability with existing utility infrastructure. Partnerships between IT firms and utility operators shape the competitive landscape, enabling cross-industry innovation. It demands deep industry expertise and proven track records due to the complexity of deployment and operational risk. Buyers prioritize reliability, technical support, and long-term service contracts when selecting vendors.
Report Coverage
The research report offers an in-depth analysis based on Technology, Network and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand due to rising investments in smart grid modernization.
- Utility providers will adopt AI and IoT to improve operational efficiency and real-time decision-making.
- Integrated solutions will dominate, offering scalable platforms for grid management and customer engagement.
- Cloud-based utility platforms will gain traction among small and mid-sized operators.
- Demand for cybersecurity solutions will increase to protect digital infrastructure and customer data.
- Renewable energy integration will drive adoption of digital tools for load balancing and forecasting.
- Governments will support digital utility rollouts through policy incentives and infrastructure funding.
- Advanced metering infrastructure will become standard across major utility networks.
- Companies will form more strategic partnerships to deliver comprehensive digital solutions.
- Asia Pacific will emerge as the fastest-growing region, driven by urbanization and energy demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Smart Grid Modernization
Utilities are investing in advanced metering infrastructure, intelligent control systems, and predictive maintenance tools to improve grid reliability, reduce transmission losses, and enhance energy efficiency. Government initiatives and funding for smart grid development are accelerating adoption, especially in developed economies.
Integration of Renewable Energy
The increasing share of solar, wind, and other renewables in the energy mix is driving demand for digital utility solutions that can manage variable energy inputs, enable real-time balancing, and support distributed generation. Digital platforms and forecasting tools are essential for stable and efficient grid operations as renewable integration rises.
Adoption of IoT and AI Technologies
Utilities are leveraging IoT-enabled sensors, smart meters, and AI-driven analytics for real-time monitoring, predictive maintenance, and automated decision-making. These technologies improve operational efficiency, reduce downtime, and optimize resource utilization, making digital transformation a strategic priority.
Shift to Cloud-Based Utility Platforms
Cloud computing enables utilities to manage large volumes of data, support remote monitoring, and deliver integrated services with greater flexibility and scalability. This trend is particularly strong among small and mid-sized utilities seeking to modernize without heavy infrastructure investments.
Focus on Consumer-Centric Digital Services
Utilities are deploying mobile apps, personalized billing, and interactive dashboards to enhance customer engagement and satisfaction. The demand for transparent pricing, usage analytics, and real-time notifications is driving the adoption of advanced digital interfaces and value-added services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Digital Utility Market?
What are the main drivers of growth in the Digital Utility Market?
How are technological advancements impacting the Digital Utility Market?
Which regions are leading the Digital Utility Market?
Why are utilities investing in digital infrastructure?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Network
- 1.2.1 Generation
- 1.2.2 Transmission & Distribution
- 1.2.3 Retail
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 Hardware
- 1.3.2 Integrated Solutions
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 228,202.45 million → 2032: USD 492,754.09 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Utility Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Utility Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Utility Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Utility Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Utility Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Utility Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Utility Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Utility Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 228,202.45 million → 2032: USD 492,754.09 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Utility Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Network - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Generation
- 12.3.7.2 Transmission & Distribution
- 12.3.7.3 Retail
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Integrated Solutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Utility Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Digital Utility Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Digital Utility Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 ABB
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Siemens
- 17.4 Schneider Electric
- 17.5 Microsoft
- 17.6 Oracle
- 17.7 IBM
- 17.8 SAP SE
- 17.9 Cisco Systems
- 17.10 Accenture
- 17.11 Honeywell International Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

