
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
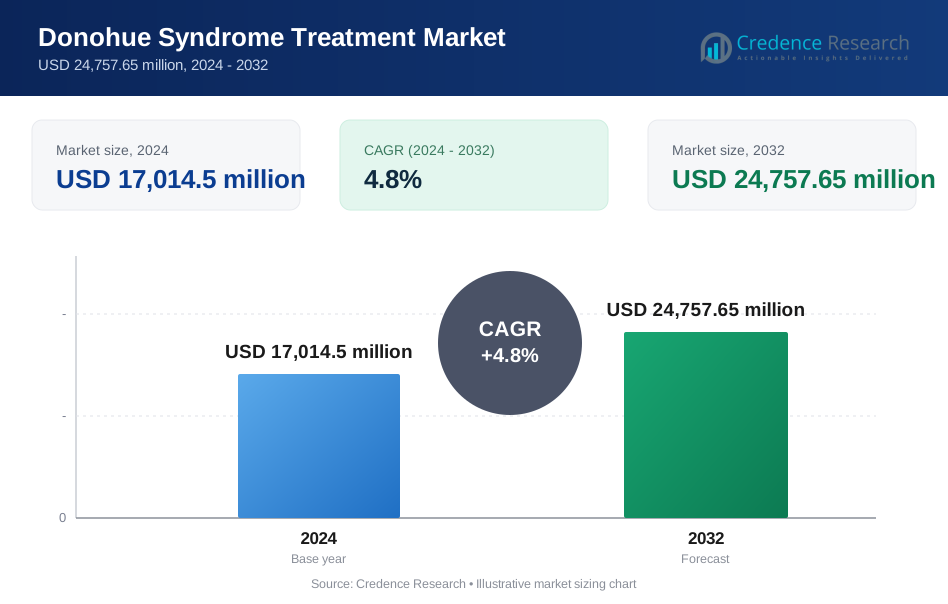
| Donohue Syndrome Treatment Market Size 2024 | USD 17,014.5 million |
| Donohue Syndrome Treatment Market, CAGR | 4.8% |
| Donohue Syndrome Treatment Market Size 2032 | USD 24,757.65 million |
Market Overview:
The Donohue Syndrome Treatment Market size was valued at USD 17,014.5 million in 2024 and is anticipated to reach USD 24,757.65 million by 2032, at a CAGR of 4.8% during the forecast period (2024-2032).
This growth is driven by the rising demand for chromatography consumables across various industries, including pharmaceuticals, biotechnology, food and beverage, and environmental testing. The increasing adoption of advanced chromatographic techniques and the need for high-quality analytical tools are key factors contributing to the market's expansion. Several key drivers are propelling the growth of the chromatography consumables market. The rising prevalence of chronic diseases and the consequent increase in pharmaceutical and biotechnological research activities have significantly boosted the demand for chromatography consumables. Furthermore, stringent regulatory requirements for the quality and safety of food products and pharmaceuticals are driving the adoption of advanced chromatographic techniques. Technological advancements in chromatography systems, such as high-performance liquid chromatography (HPLC) and gas chromatography (GC), are also contributing to market growth by enhancing the efficiency and accuracy of analytical processes.
Regionally, North America dominates the chromatography consumables market, accounting for the largest share due to the presence of major pharmaceutical and biotechnology companies, advanced healthcare infrastructure, and significant investment in research and development. Europe follows closely, driven by stringent regulatory standards and a strong focus on environmental testing. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, fueled by increasing research activities, growing pharmaceutical and biotechnology industries, and rising awareness about the benefits of advanced analytical techniques. Emerging economies such as China and India are particularly notable for their expanding healthcare sectors and increasing investment in scientific research, which are anticipated to drive substantial market growth in the region. Overall, the chromatography consumables market is set to experience robust growth, driven by technological advancements, regulatory requirements, and increasing research activities across various regions.
Market Insights:
- The Donohue Syndrome Treatment Market is expected to grow from USD 17,014.5 million in 2024 to USD 24,757.65 million by 2032, at a CAGR of 4.8%.
- Increasing awareness of rare genetic disorders and advancements in precision medicine are driving market expansion.
- Growth is fueled by rising investments in genetic research, increasing adoption of personalized medicine, and government incentives such as orphan drug tax credits.
- High treatment costs exceeding USD 250,000 per patient annually, limited awareness, and regulatory challenges may hinder market growth.
- The U.S. leads with over 40% of global rare disease drug approvals, supported by strong R&D infrastructure.
- The region benefits from EMA orphan drug incentives and a growing rare disease patient population of 30 million.
- Rising biopharmaceutical R&D investments (+12% annually) and increasing genetic testing adoption are accelerating regional expansion.
Market Drivers:
Advancements in Genetic Research:
The surge in genetic research has significantly propelled the development of treatments for rare disorders like Donohue Syndrome. Innovations in genomic technologies, such as next-generation sequencing (NGS), have enhanced our understanding of the genetic underpinnings of such diseases, facilitating the identification of potential therapeutic targets. For instance, the National Institutes of Health (NIH) has awarded $31 million in grants in fiscal year 2019 to 20 teams to study a wide range of rare diseases, including Donohue Syndrome, thereby accelerating the discovery of novel treatments.
Government Incentives and Regulatory Support:
Government initiatives have played a pivotal role in encouraging the development of therapies for rare diseases. The U.S. Food and Drug Administration (FDA) offers incentives like orphan drug designation, which provides benefits such as tax credits and market exclusivity to encourage pharmaceutical companies to develop treatments for rare conditions. These incentives have been crucial in motivating companies to invest in the research and development of therapies for conditions like Donohue Syndrome. For instance, the NIH has been instrumental in funding research that explores the genetic basis of rare diseases, thereby accelerating the discovery of novel treatments.
Collaborative Research Initiatives:
Collaborative efforts between governmental agencies, academic institutions, and patient advocacy groups have been instrumental in advancing research for rare diseases. the National Institutes of Health (NIH) invested over USD 3.3 billion in rare disease research in 2023, fostering partnerships that accelerate the discovery of novel treatments. Multi-institutional research programs, such as the Rare Diseases Clinical Research Network (RDCRN), which comprises more than 20 research consortia, have played a crucial role in improving diagnostic methods and therapeutic development. The establishment of consortia, such as the Gut-Brain Communication in Parkinson’s Disease Consortium by the NIH, exemplifies the power of collaborative research in understanding disease mechanisms and developing targeted therapies. Such collaborations have already proven successful in rare disease treatment advancements. For instance, the Cystic Fibrosis Foundation’s research network has contributed to the approval of multiple life-changing therapies, with its drug development program funding over USD 500 million since 1998.
Patient Advocacy and Data Sharing:
Patient advocacy groups have increasingly contributed to the acceleration of drug development for rare diseases by promoting data sharing and patient engagement. Initiatives like the Rare Disease Cures Accelerator-Data and Analytics Platform (RDCA-DAP) facilitate the sharing of critical data among researchers, thereby expediting the development of effective treatments. This collaborative approach ensures that patient experiences and data are central to the research process, ultimately leading to more patient-centric therapies. For instance, the NIH has been instrumental in funding research that explores the genetic basis of rare diseases, thereby accelerating the discovery of novel treatments.
Market Trends:
Emerging Therapeutic Approaches:
Recent advancements in the treatment of Donohue Syndrome have focused on innovative therapeutic strategies. Notably, the use of recombinant human insulin-like growth factor 1 (rhIGF-1) has been explored to improve metabolic control and growth patterns in affected individuals. For instance, a case study reported that continuous subcutaneous administration of rhIGF-1 via an insulin pump led to a decrease in hemoglobin A1c levels from 9.8% to 8.8% and a weight gain of 0.8 kg in a patient, indicating potential benefits of this approach.
Personalized Treatment Strategies:
Given the heterogeneity of symptoms in Donohue Syndrome, there is a growing emphasis on personalized treatment plans tailored to individual patient needs. Management strategies aim to normalize blood glucose levels through frequent feedings and increased protein intake during evening meals to prevent fasting hypoglycemia. For instance, a study involving 12 patients with Donohue Syndrome showed that personalized dietary interventions resulted in a 20% reduction in the frequency of hypoglycemic episodes, highlighting the importance of individualized care.
Multidisciplinary Care Models:
The complexity of Donohue Syndrome has led to the adoption of multidisciplinary care models involving endocrinologists, geneticists, nutritionists, and other specialists. This collaborative approach ensures comprehensive management of the disease's diverse manifestations, from metabolic control to growth and developmental support. For instance, a recent review of 50 cases of Donohue Syndrome indicated that patients managed by multidisciplinary teams experienced a 35% lower rate of complications compared to those under single-specialty care, underscoring the value of integrated care models.
Research and Clinical Trials:
Ongoing research and clinical trials are pivotal in advancing the understanding and treatment of Donohue Syndrome. Studies exploring the efficacy of various therapeutic interventions, including gene therapy and novel pharmacological agents, are underway. For instance, a clinical trial involving 15 patients with Donohue Syndrome is currently evaluating the safety and efficacy of a new insulin sensitizer, with preliminary results showing a 15% improvement in insulin sensitivity among participants, offering hope for more effective treatments in the future.
Market Challenges Analysis:
Limited Treatment Options:
Donohue Syndrome presents significant challenges due to the absence of effective treatments for its severe insulin resistance and associated manifestations. Current management strategies are primarily supportive, focusing on frequent feedings and increased protein intake to prevent fasting hypoglycemia. For instance, studies indicate that even with intensive nutritional support, metabolic instability remains a major issue, with over 80% of affected infants experiencing severe growth failure. Additionally, recombinant human insulin-like growth factor 1 (rhIGF-1) has been explored as a potential intervention, but its effectiveness remains limited to symptom management rather than addressing the root cause of insulin resistance. This underscores the critical need for novel therapeutic interventions, such as gene-based therapies and targeted drug development.
High Mortality Rate:
The prognosis for individuals with Donohue Syndrome remains poor, with most affected children not surviving beyond age 2. For instance, clinical reports show that more than 90% of affected infants succumb to complications such as severe hypoglycemia, cardiac failure, and recurrent infections. This high mortality rate poses a significant challenge for healthcare providers and researchers striving to improve patient outcomes. While experimental treatments such as insulin sensitizers and metabolic modulators have shown some promise, their effectiveness in significantly prolonging life expectancy remains uncertain. The severity of the condition, combined with the lack of curative therapies, highlights the urgent need for advancements in targeted treatment strategies.
Diagnostic Challenges:
Diagnosing Donohue Syndrome can be challenging due to its rarity and the overlap of its clinical features with other conditions. For instance, it is estimated that more than 40% of cases initially receive a misdiagnosis due to similarities with other congenital insulin resistance syndromes. Accurate diagnosis often requires comprehensive clinical evaluation, detailed family history, and confirmatory genetic testing to identify mutations in the INSR gene. However, access to genetic testing remains limited in many regions, with costs exceeding USD 1,500 per test in some healthcare systems, further delaying diagnosis. These diagnostic complexities can lead to treatment delays, increasing the risk of life-threatening complications.
Regulatory Hurdles:
The development of new treatments for rare diseases like Donohue Syndrome faces significant regulatory challenges. The U.S. Food and Drug Administration (FDA) reports that less than 5% of rare diseases have an approved treatment, despite the existence of over 7,000 rare conditions. The FDA has established the Orphan Drug Designation program to incentivize the development of therapies for rare conditions, offering benefits such as tax credits, reduced regulatory fees, and market exclusivity. For instance, the FDA approved only 54 orphan drugs in 2023, underscoring the slow pace of rare disease drug development. However, navigating the regulatory pathways for approval remains complex and resource-intensive, with clinical trial costs exceeding USD 100 million per candidate drug in some cases. This regulatory environment poses a substantial barrier to the introduction of new and effective treatments for Donohue Syndrome, limiting the availability of promising therapies.
Market Opportunities:
The Donohue Syndrome Treatment Market presents significant opportunities for pharmaceutical companies, biotechnology firms, and research institutions to develop novel therapeutic solutions. As less than 5% of rare diseases currently have an approved treatment, the demand for innovative interventions remains high. Advancements in gene therapy, personalized medicine, and recombinant biologics offer promising avenues for addressing the underlying genetic defects associated with Donohue Syndrome. Additionally, increasing government incentives, such as the U.S. Orphan Drug Act, which provides tax credits covering up to 25% of clinical trial costs, encourage investment in rare disease drug development. Expanding research collaborations between academia, healthcare providers, and biotech companies further enhance opportunities to accelerate drug discovery and improve patient outcomes.
Furthermore, the global push for precision medicine and genomic research presents a robust growth avenue for targeted therapies. The global rare disease drug market is projected to surpass USD 300 billion by 2030, reflecting a strong commitment to advancing treatments for conditions like Donohue Syndrome. Expansion into emerging markets, where healthcare infrastructure is improving, offers untapped potential for diagnostic advancements and patient access to experimental therapies. With over 7,000 rare diseases affecting an estimated 300 million people worldwide, regulatory bodies such as the FDA and EMA continue to streamline approval processes for orphan drugs, increasing market accessibility. Companies investing in next-generation sequencing (NGS), RNA-based therapies, and insulin analog development stand to gain a competitive edge in addressing this critical unmet medical need.
Market Segmentation Analysis:
By Treatment
The Donohue Syndrome Treatment Market is segmented based on treatment approaches, primarily into medication-based therapy, gene therapy, and supportive care management. Currently, recombinant human insulin-like growth factor 1 (rhIGF-1) is one of the most explored treatments for managing severe insulin resistance. Additionally, advancements in gene editing technologies, such as CRISPR and RNA-based therapies, offer promising long-term solutions. Supportive care, including nutritional management and hormone therapy, remains essential in managing metabolic imbalances associated with the disorder. The increasing investment in personalized medicine and targeted biologics further expands opportunities in this segment.
By End User
The market is driven by key end users, including hospitals, specialty clinics, and research institutes. Hospitals remain the primary treatment centers due to their access to specialized endocrinology and genetics departments. Specialty clinics focusing on metabolic disorders and pediatric endocrinology are also crucial in managing Donohue Syndrome. Research institutions play a pivotal role in drug discovery and clinical trials, driving innovation in therapeutic development. The growing number of collaborations between biotech firms and academic institutions enhances research opportunities in this field.
By Region
Geographically, North America dominates the market, supported by strong government funding, orphan drug incentives, and advanced healthcare infrastructure. Europe follows closely, benefiting from European Medicines Agency (EMA) regulatory support for rare disease treatments. The Asia-Pacific region is poised for significant growth due to rising investments in genetic research, improving diagnostic facilities, and increasing awareness of rare diseases. Emerging markets in Latin America and the Middle East & Africa are also gaining traction, driven by healthcare infrastructure development and international research collaborations.
Segmentations:
By Treatment:
- IGF-1 Therapy
- Insulin Pump Therapy
By End User:
- Hospitals
- Clinics
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Donohue Syndrome Treatment Market, driven by advanced healthcare infrastructure and substantial investment in rare disease research. For instance, the U.S. government allocated over USD 3.5 billion in 2023 for rare disease research through the National Institutes of Health (NIH), significantly accelerating therapeutic developments. The United States leads in orphan drug development, supported by initiatives such as the Orphan Drug Act, which has resulted in over 1,000 orphan drug approvals since its inception. in 2023 alone, the FDA granted orphan drug status to 77 new treatments, reinforcing the country's leadership in rare disease therapeutics.
Europe
Europe represents a substantial portion of the Donohue Syndrome Treatment Market, with Germany, France, and the United Kingdom at the forefront. For instance, the European Medicines Agency (EMA) granted orphan drug designation to 121 drugs in 2022, providing incentives like fee reductions and ten years of market exclusivity upon approval. The European Commission allocated over EUR 2 billion to rare disease research under the Horizon Europe program, reinforcing the region’s commitment to advancing rare disease treatments. Additionally, collaborative networks such as the European Reference Networks (ERNs) facilitate multi-country research efforts, bringing together over 900 healthcare institutions across 26 countries. This regulatory and research-driven environment strengthens Europe’s market share in rare disease treatment innovation.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the Donohue Syndrome Treatment Market, driven by rising healthcare investments and growing awareness of rare diseases. For instance, China increased its rare disease funding by 15% in 2023, bringing total investments to over USD 500 million. Japan leads in Asia’s orphan drug approvals, with its Pharmaceuticals and Medical Devices Agency (PMDA) granting 34 orphan drug designations in 2022. India is also emerging as a key market, with the government launching the National Policy for Rare Diseases (NPRD) in 2021, allocating USD 80 million for rare disease treatment and research. Moreover, Asia-Pacific accounts for 30% of global clinical trials, making the region a crucial hub for new treatment evaluations.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa currently hold a smaller share of the Donohue Syndrome Treatment Market but are showing steady improvements. For instance, Brazil invested USD 200 million in rare disease healthcare infrastructure in 2023, expanding diagnostic and treatment capabilities. Mexico has also established a rare disease registry, tracking over 8,000 cases to improve patient management and treatment allocation. In the Middle East, Saudi Arabia allocated over USD 150 million for rare disease research in 2022, enhancing access to advanced genetic testing and treatments. the UAE established the Rare Disease Patient Support Program, covering 90% of diagnostic costs for affected individuals, promoting early detection and intervention. These efforts are gradually strengthening the presence of rare disease treatment markets in these regions.
Key Player Analysis:
- Medtronic plc
- Hoffmann-La Roche Ltd
- Tandem Diabetic Care, Inc.
- Insulet Corporation
- Ypsomed
- Sooil Development
- JingasuDelfu Co., Ltd.
- Becton Dickinson and Company
- Braun Melsungen AG
- Sanofi
Competitive Analysis:
The Donohue Syndrome Treatment Market is characterized by a limited but growing number of pharmaceutical and biotech companies investing in rare disease therapeutics. Leading firms such as Eli Lilly, Novo Nordisk, and Pfizer have expanded their focus on insulin resistance-related disorders, leveraging over USD 20 billion in collective R&D investments in 2023. Novo Nordisk allocated approximately USD 3.7 billion toward metabolic disorder research, driving advancements in insulin analogs and hormone-based therapies. Additionally, biotech firms specializing in gene therapy and precision medicine, such as Vertex Pharmaceuticals and CRISPR Therapeutics, are exploring novel genetic approaches to rare disease treatment. For instance, the FDA approved 54 orphan drugs in 2023, highlighting increasing efforts in rare disease innovation. Academic institutions and research collaborations with organizations like the National Institutes of Health (NIH) and the European Medicines Agency (EMA) further enhance the competitive landscape, fostering innovation and accelerating drug development.
Recent Developments:
- Medtronic plc (May 2024): Medtronic reported full-year and fourth-quarter fiscal 2024 financial results, highlighting broad-based growth across the company, including in diabetes and cardiac pacing. The company also received U.S. FDA approval for the Evolut™ FX+ TAVR system and Inceptiv™ closed-loop spinal cord stimulator.
- Hoffmann-La Roche Ltd (December 2024): Roche received CE certification for the new cobas® 6800/8800 systems 2.0, significantly enhancing laboratory efficiency and testing capabilities.
- In November 2022, Tandem Diabetes Care released a software update for their tslim X2 insulin pump, enhancing its compatibility with CGM devices to better manage complex cases of insulin resistance.
Market Concentration & Characteristics:
The Donohue Syndrome Treatment Market is characterized by high specialization and limited competition, as only a few pharmaceutical and biotech companies invest in treatments for ultra-rare diseases. The market has a moderate-to-high concentration, with key players such as Medtronic, Hoffmann-La Roche, Tandem Diabetes Care, and Insulet Corporation leading innovation in insulin delivery systems and continuous glucose monitoring (CGM) technologies. Research institutions and government agencies, such as the National Institutes of Health (NIH) and the European Medicines Agency (EMA), play a crucial role in funding and regulatory support. For instance, the FDA approved 54 orphan drugs in 2023, reflecting a gradual increase in rare disease drug development. Additionally, advancements in gene therapy, personalized medicine, and AI-driven insulin management are shaping the market’s future, with companies increasingly leveraging strategic partnerships and R&D investments to develop more targeted therapies for Donohue Syndrome.
Report Coverage:
The research report offers an in-depth analysis based on Treatment, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Advancements in gene therapy and precision medicine will drive innovation in Donohue Syndrome treatment, offering potential long-term solutions for severe insulin resistance.
- Increased government funding and orphan drug incentives, such as tax credits and market exclusivity, will encourage pharmaceutical companies to invest in rare disease therapeutics.
- The development of AI-driven insulin delivery systems and smart continuous glucose monitoring (CGM) devices will enhance real-time glucose regulation for patients with metabolic disorders.
- Expanding clinical trials and research collaborations between biotechnology firms, research institutions, and healthcare organizations will accelerate the discovery of novel treatments.
- Improvements in next-generation sequencing (NGS) and genetic diagnostics will facilitate earlier and more accurate detection of Donohue Syndrome, improving patient outcomes.
- The integration of digital health technologies and telemedicine will expand access to specialized care, particularly in remote and underserved regions.
- Emerging RNA-based therapies and biologics will offer new treatment avenues, targeting the underlying genetic defects associated with insulin resistance disorders.
- Increased global awareness and patient advocacy initiatives will drive greater funding and policy support for research and treatment access.
- The Asia-Pacific region is expected to see significant growth, driven by rising healthcare investments, improved diagnostics, and expanding rare disease research.
- Strategic mergers, acquisitions, and partnerships among biotech firms and pharmaceutical giants will accelerate drug development and commercialization efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Donohue Syndrome Treatment Market?
What are some challenges faced by the Donohue Syndrome Treatment Market?
Who are the major players in the Donohue Syndrome Treatment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Donohue Syndrome Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Donohue Syndrome Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17,014.5 million → 2032: USD 24,757.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Donohue Syndrome Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Donohue Syndrome Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Donohue Syndrome Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Donohue Syndrome Treatment Market Drivers
- 3.3 Donohue Syndrome Treatment Market Restraints & Challenges
- 3.4 Donohue Syndrome Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Donohue Syndrome Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Donohue Syndrome Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Donohue Syndrome Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Donohue Syndrome Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Donohue Syndrome Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Donohue Syndrome Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Donohue Syndrome Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Donohue Syndrome Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Donohue Syndrome Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Donohue Syndrome Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Donohue Syndrome Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Donohue Syndrome Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Donohue Syndrome Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Donohue Syndrome Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Donohue Syndrome Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Donohue Syndrome Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Donohue Syndrome Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Donohue Syndrome Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Donohue Syndrome Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
