
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Drone Logistics and Transportation Market Size 2024 | USD 1574.66 Million |
| Drone Logistics and Transportation Market, CAGR | 36% |
| Drone Logistics and Transportation Market Size 2032 | USD 18428.84 Million |
Market Overview:
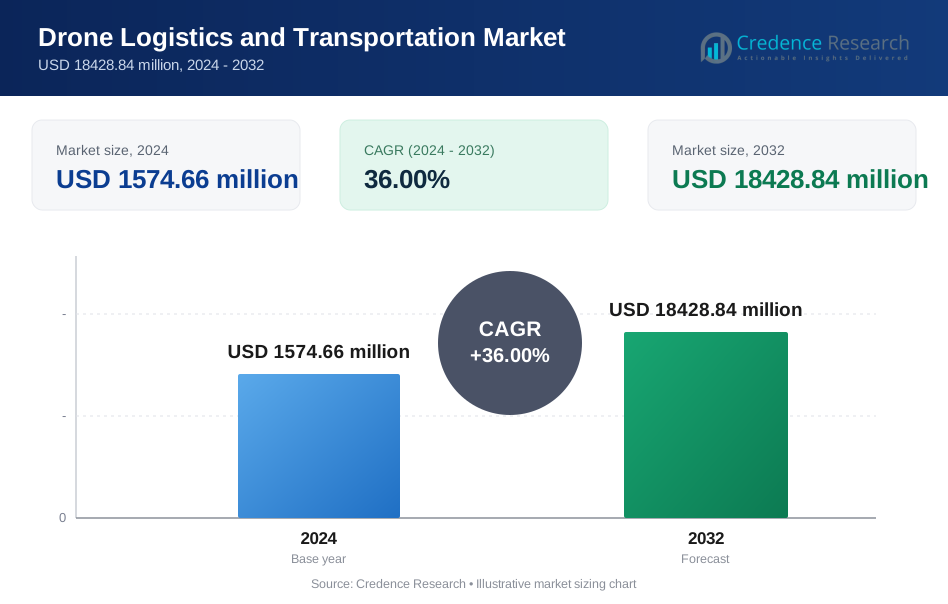
The Drone Logistics and Transportation Market size was valued at USD 1574.66 million in 2024 and is anticipated to reach USD 18428.84 million by 2032, at a CAGR of 36% during the forecast period (2024-2032).
The key drivers of the Drone Logistics & Transportation market include advancements in drone technology, such as improved battery life, payload capacity, and autonomous navigation systems, which are making drones more capable of carrying out long-distance deliveries. As drones become more reliable and versatile, they are expected to address the logistical challenges of last-mile delivery more efficiently. The need for faster, contactless, and cost-effective delivery solutions in urban and remote areas further accelerates the adoption of drones. Additionally, the growing focus on reducing carbon footprints and enhancing sustainability in logistics is driving companies to explore green alternatives, with drones offering a more eco-friendly option compared to traditional delivery vehicles. Drones not only reduce greenhouse gas emissions but also help alleviate road congestion in urban environments. Regulatory support and infrastructure development are also contributing to the market's growth, as governments and industry stakeholders create frameworks to ensure safe integration of drones into national airspaces, ensuring consistent safety standards across regions.
Regionally, North America holds the largest share of the Drone Logistics & Transportation market, driven by early adoption of drone technologies, significant investments in R&D, and the presence of key players like Amazon and UPS. The region’s strong regulatory framework and support for innovation have enabled rapid deployment of drone solutions for logistics. Europe and Asia Pacific are also witnessing rapid growth, with countries such as the UK, Germany, and China actively integrating drone solutions into their logistics networks. The growing investment in infrastructure for drone operations and supportive government policies in these regions further facilitate market expansion. The expanding e-commerce industry and increasing demand for innovative delivery methods are expected to fuel further market expansion across these regions, especially in addressing the challenges posed by densely populated areas and difficult terrains.
Market Insights:
- The Drone Logistics & Transportation market was valued at USD 66 million in 2024 and is projected to reach USD 18428.84 million by 2032. The market is expected to grow at a CAGR of 36% during the forecast period from 2024 to 2032.
- Advancements in drone technology, including better battery life, payload capacity, and autonomous navigation systems, are key drivers of market growth.
- Drones are increasingly used to address logistical challenges, particularly in last-mile delivery, reducing operational costs and delivery times.
- Environmental sustainability is a major factor driving the adoption of drones, as they offer an eco-friendly alternative to fuel-powered delivery vehicles.
- Regulatory support and infrastructure development, including air traffic management systems, are contributing to the market's growth by ensuring safe drone integration.
- North America holds the largest market share (40%), driven by early adoption, strong regulatory frameworks, and significant investments in R&D.
Market Drivers:
Advancements in Drone Technology
Recent advancements in drone technology have played a pivotal role in driving the growth of the Drone Logistics & Transportation market. Innovations such as enhanced battery life, greater payload capacity, and improved autonomous navigation systems are expanding the capabilities of drones, enabling them to carry out longer-distance deliveries and carry heavier cargo. These technological improvements have enhanced the reliability, efficiency, and scalability of drones, making them a more viable option for logistics and transportation companies. With drones becoming more capable of handling complex deliveries, they are increasingly seen as a solution to address the logistical challenges of the modern supply chain, particularly in urban and hard-to-reach locations.
Demand for Faster and Cost-Effective Delivery Solutions
The growing demand for faster, cost-effective, and contactless delivery solutions is another key driver of the market. For instance, Skye Air in Bengaluru has introduced a drone delivery service capable of completing deliveries in just seven minutes by bypassing traffic through invisible air corridors. As e-commerce continues to expand globally, customers expect shorter delivery times and more convenient options. Traditional delivery methods are often slow and inefficient, particularly in dense urban areas or remote locations. Drones provide an innovative solution by enabling faster and more direct deliveries. With the ability to bypass road traffic and take the most efficient routes, drones reduce delivery times significantly. Moreover, drones can operate at a lower cost compared to traditional vehicles, making them an attractive option for companies seeking to optimize their delivery networks while reducing operational expenses.
Environmental Sustainability and Reduced Carbon Footprints
With growing environmental concerns, sustainability has become a major consideration in logistics and transportation. Drones offer a more eco-friendly alternative to traditional delivery methods, which often rely on fuel-powered vehicles that contribute to air pollution and carbon emissions. For example, Aerialoop’s drone-based logistics network avoids traffic congestion to significantly cut delivery times and reduce urban freight emissions by 97% compared to gas-powered vehicles, promoting cleaner air and a more sustainable urban environment. Drones are electrically powered, reducing the overall carbon footprint of delivery operations. As governments and companies alike focus on reducing emissions and meeting sustainability goals, the adoption of drones presents an opportunity to reduce the environmental impact of logistics activities. This growing emphasis on sustainability is expected to accelerate the demand for drone-based solutions, as companies strive to align their operations with green initiatives and carbon reduction targets.
Regulatory Support and Infrastructure Development
The development of regulatory frameworks and the expansion of supporting infrastructure are essential drivers of the Drone Logistics & Transportation market. Governments across various regions are actively working on policies and regulations to ensure the safe integration of drones into national airspaces. These regulations are vital for ensuring that drones can operate safely in busy skies while avoiding potential conflicts with manned aircraft. Moreover, the establishment of designated drone corridors and air traffic management systems further supports the growth of this market. As governments collaborate with industry stakeholders to create a conducive regulatory environment, the market is witnessing increased investment in infrastructure that facilitates the deployment of drones for logistics purposes. The combination of regulatory support and the development of critical infrastructure is expected to pave the way for widespread drone adoption in the logistics industry.
Market Trends:
Increased Investment in Drone Technology
A significant trend in the Drone Logistics & Transportation market is the growing investment in drone technology. Both private and public sectors are channeling substantial funds into research and development to improve drone performance and expand operational capabilities. Key focus areas include enhancing battery life, extending flight range, increasing payload capacity, and developing more sophisticated autonomous navigation systems. This investment is not only enhancing the reliability of drones but also improving their potential to handle more complex logistics tasks, such as last-mile delivery in urban environments and remote regions. These advancements are pushing the boundaries of what drones can accomplish, making them an increasingly integral part of logistics networks.
Adoption of Drones in E-Commerce
The rise of e-commerce has significantly accelerated the adoption of drones for logistics and transportation. For instance, Amazon Prime Air has successfully implemented drone delivery services, offering same-day delivery options in select regions. Major e-commerce players like Amazon and Walmart are leading the way, integrating drones into their delivery systems to meet the growing demand for faster, more efficient delivery options. Drones are particularly beneficial for last-mile delivery, where they reduce delivery times, lower costs, and provide contactless service. The ability to offer rapid deliveries, particularly in densely populated or hard-to-reach areas, has made drones an essential tool for e-commerce companies looking to improve customer satisfaction and stay competitive in the marketplace.
Focus on Sustainability
Sustainability remains a critical trend within the Drone Logistics & Transportation market. With increasing pressure to reduce carbon footprints, drones provide an eco-friendly solution to traditional delivery methods, which are often reliant on fuel-powered vehicles. For example, Zipline, known for its drone-based medical supply deliveries in Rwanda and Ghana, has significantly reduced reliance on fuel-powered vehicles by utilizing electric drones. The use of electric-powered drones reduces emissions, making them an attractive option for companies and governments committed to meeting sustainability targets. As the demand for green logistics solutions grows, drones are positioned as a viable alternative to reduce the environmental impact of transportation, contributing to the ongoing shift towards greener business practices.
Regulatory Developments
Regulatory advancements are another key trend shaping the market. Governments worldwide are working on creating frameworks that allow for the safe and efficient integration of drones into national airspaces. In addition to airspace management, regulations are being developed to address safety, privacy, and operational standards. As regulatory environments evolve and infrastructure to support drone operations is built, the logistics industry is witnessing the gradual but steady adoption of drone technology, which is enabling drones to play an increasingly central role in the transportation sector.
Market Challenges Analysis:
Regulatory and Safety Concerns
One of the primary challenges in the Drone Logistics & Transportation market is navigating the complex regulatory landscape. For instance, India has introduced the Drone Rules 2021, which significantly simplified drone operations by reducing permissions and creating green zones for drones to operate freely. While governments are developing frameworks for drone operations, regulations vary significantly across regions, which creates inconsistencies in implementation and operational standards. The lack of global standardization can hinder the seamless integration of drones into logistics networks, particularly in cross-border operations. Moreover, regulatory delays and restrictions on drone flight zones often cause operational setbacks, limiting the scalability of drone services. Additionally, ensuring airspace safety remains a key challenge, as drones must be integrated with manned aircraft systems to avoid collisions. The establishment of safe, designated drone corridors and robust air traffic management systems is essential but requires considerable investment and coordination, which can slow the pace of adoption.
Technological and Infrastructure Limitations
Despite advancements in drone technology, limitations still exist that hinder the widespread adoption of drones in logistics. Battery life, payload capacity, and flight range remain constraints, particularly for long-distance deliveries and larger cargo. Drones are still developing the necessary technology to carry heavier loads over greater distances without frequent recharging or maintenance. In addition, weather conditions such as strong winds and poor visibility can further limit drone operations, creating logistical challenges. Furthermore, the lack of comprehensive infrastructure to support drone operations, such as charging stations and drone ports, poses a significant challenge. The development of this infrastructure requires substantial investment, which may be a barrier for smaller companies or regions with limited resources. These technological and infrastructure gaps need to be addressed to enable the scalable deployment of drones in logistics.
Market Opportunities:
The Drone Logistics & Transportation market presents significant opportunities driven by the increasing demand for faster, more efficient, and cost-effective delivery solutions. As e-commerce continues to grow, the need for rapid last-mile delivery is more critical than ever. Drones offer an innovative way to address this challenge by enabling quick, direct deliveries in densely populated urban areas as well as remote or hard-to-reach locations. The potential for drones to transform logistics is further enhanced by advancements in drone technology, which are improving their range, payload capacity, and autonomous capabilities. This positions drones as a valuable asset for industries such as retail, healthcare, and manufacturing, where timely deliveries are essential. Additionally, the cost-saving potential of drones-through reduced fuel consumption and labor costs-creates an appealing proposition for companies seeking to optimize their logistics operations.
Another major opportunity lies in the growing emphasis on sustainability within the logistics and transportation sectors. As governments and corporations worldwide seek to reduce carbon footprints, drones offer an eco-friendly alternative to traditional delivery vehicles. Since drones are typically powered by electricity, they produce fewer emissions and are less reliant on fossil fuels compared to conventional trucks or vans. This environmental benefit is especially attractive to companies aiming to meet sustainability targets and regulatory requirements. Furthermore, as regulatory frameworks for drone operations evolve, more regions will open up for drone deliveries, expanding the market's reach and enabling broader adoption across various sectors. The combination of technological advancements, sustainability trends, and expanding regulatory support presents a promising future for the Drone Logistics & Transportation market.
Market Segmentation Analysis:
By Drone Type
The Drone Logistics & Transportation market is segmented by drone type into fixed-wing drones, rotary-wing drones, and hybrid drones. Fixed-wing drones are ideal for long-distance deliveries due to their ability to cover large areas with high efficiency. Rotary-wing drones, on the other hand, offer greater maneuverability and are typically used for short-range deliveries, especially for last-mile logistics in urban areas. Hybrid drones combine the features of both fixed and rotary wings, making them versatile for various operational environments. The demand for rotary-wing drones is currently higher due to their flexibility and suitability for urban logistics and short-distance deliveries.
By Operation Type
The market is also segmented by operation type into manual, autonomous, and semi-autonomous drones. Autonomous drones, which can operate independently without human intervention, are gaining traction due to their efficiency and ability to perform complex tasks in logistics operations. Semi-autonomous drones require limited human oversight, while manual drones are still used in specific scenarios but are expected to decrease as autonomous systems become more reliable and prevalent in the industry.
By Application
The Drone Logistics & Transportation market is further segmented by application into e-commerce, healthcare, agriculture, and others. E-commerce and healthcare are the largest application segments, with drones being increasingly used for last-mile deliveries and medical supplies. Drones also play a significant role in agricultural logistics by delivering seeds, pesticides, and fertilizers to remote areas, contributing to the growth of the agricultural sector.
Segmentations:
By Drone Type- Fixed-Wing Drones
- Rotary-Wing Drones
- Hybrid Drones
- Manual Drones
- Autonomous Drones
- Semi-Autonomous Drones
- E-commerce
- Healthcare
- Agriculture
- Military & Defense
- Industrial
- Retail
- Pharmaceuticals
- Logistics Service Providers
- Government & Military
- Healthcare Institutions
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the global Drone Logistics & Transportation market, with a 40% market share. This dominance is due to the early adoption of drone technology and the involvement of major industry players such as Amazon and UPS, who are advancing drone-based delivery systems. The United States has made considerable progress in integrating drones into commercial logistics, supported by a robust regulatory framework, with the Federal Aviation Administration (FAA) playing a vital role in establishing safety guidelines. These regulations facilitate smooth drone operations in the national airspace, contributing to widespread adoption. Additionally, North America benefits from significant investments in research and development (R&D), particularly in enhancing drone capabilities such as autonomous flight systems and longer battery life. As e-commerce continues to expand, drones are expected to play an increasingly vital role in last-mile deliveries, ensuring that North America remains a leader in the market.
Europe
Europe holds the second-largest share of the market at 30%, driven by rapid adoption of drone technology in logistics. Key players like DHL and UPS have been testing and deploying drones for delivery services, and the European Union has proactively developed regulations to enable safe drone operations. Countries such as the UK, Germany, and France are at the forefront of integrating drones into logistics infrastructures. The use of drones in healthcare logistics, especially for remote or rural deliveries, is also gaining traction. Europe's commitment to sustainability and reducing emissions makes drones an attractive alternative to traditional delivery vehicles, further fueling adoption. As regulations evolve and the demand for innovative logistics solutions increases, Europe is well-positioned for continued growth in the drone logistics market.
Asia Pacific
The Asia Pacific region, with a market share of 25%, is experiencing rapid growth in the drone logistics sector. Countries like China, Japan, and India are heavily investing in drone technology to address urban and rural delivery challenges. China has emerged as a leader in drone development, with companies like DJI leading the way in manufacturing commercial drones. E-commerce giants like Alibaba and JD.com are integrating drones into their delivery networks, particularly for last-mile deliveries in remote regions. The rapid urbanization in Asia, along with a growing demand for faster and cost-effective delivery solutions, presents substantial opportunities for drone adoption. Additionally, government initiatives are supporting the development of drone infrastructure, setting the stage for continued market expansion as regulatory frameworks evolve.
Key Player Analysis:
- Wing Aviation
- Matternet
- Hardis Group
- Volansi
- Amazon
- DHL
- InDro Robotics
- Flirtey
- Drone Delivery Canada
- Gather
- Swellgarfo
- Zipline
- Skycart
- Aerodyne Group
- UPS
Competitive Analysis:
The Drone Logistics & Transportation market is highly competitive, with several key players leading the development and deployment of drone-based delivery solutions. Major companies like Amazon, UPS, and DHL have been pioneers in integrating drones into their logistics operations, with significant investments in drone technology and infrastructure. Amazon, through its Prime Air service, aims to revolutionize last-mile delivery by using drones to provide rapid, cost-effective service. UPS and DHL have also launched pilot projects focusing on drone deliveries, particularly for healthcare and e-commerce applications.
In addition to these global players, emerging companies like Zipline and Wing are gaining traction by providing drone delivery services in specific regions, such as Africa and Australia, focusing on sectors like healthcare and urgent supply chain needs. As drone technology continues to evolve, competition will intensify, with companies striving to enhance operational efficiency, extend coverage, and address regulatory challenges to maintain market leadership.
Recent Developments:
- In June 2024, Blue Dart, South Asia’s leading courier and express package distribution company, has partnered with Skye Air, a pioneer in drone technology in India, to launch drone delivery services.
- In January 2024, Draganfly Inc., a prominent provider of drone solutions, entered into a strategic partnership with Mass General Brigham. The collaboration aims to introduce Draganfly's advanced drone delivery services for Mass General Brigham's Home Hospital initiative.
- In May 2023, The US Marine Corps (USMC) allocated over USD 13 million to procure 41 tactical resupply unmanned aircraft systems (TRUAS). This investment is part of the USMC’s strategy to enhance its logistics capabilities through unmanned aerial deliveries. The TRUAS, designed to carry payloads of up to 150 pounds over a distance of nine miles, feature secure payload containerization and are expected to achieve initial operational capacity soon.
Market Concentration & Characteristics:
The Drone Logistics & Transportation market exhibits a moderate to high level of concentration, with a few key players dominating the landscape while numerous emerging companies contribute to market innovation. Major industry leaders such as Amazon, UPS, and DHL have established a significant presence, leveraging their extensive logistics networks and technological expertise to drive the adoption of drone-based delivery solutions. These companies are investing heavily in research and development to enhance drone capabilities, including autonomous systems and extended flight ranges. Additionally, several startups and regional players are entering the market, focusing on niche segments such as healthcare deliveries, rural logistics, and regulatory compliance. The market is characterized by rapid technological advancements, intense competition, and an evolving regulatory environment, which requires players to stay agile in adapting to new policies and consumer demands. As drone technology matures, the market is expected to experience further consolidation and strategic partnerships among key players.
Report Coverage:
The research report offers an in-depth analysis based on drone type, operation type, application, end-use and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Drone Logistics & Transportation market is expected to see continued technological advancements, improving the efficiency, payload capacity, and autonomy of drones.
- Regulatory frameworks will evolve, allowing for safer and more widespread drone operations across global airspaces.
- Increased investment in drone infrastructure, including charging stations and drone ports, will support market growth.
- E-commerce giants will increasingly integrate drones into their last-mile delivery networks to meet growing consumer demands for faster, more reliable services.
- Drones will play a significant role in healthcare logistics, enabling rapid and contactless delivery of medical supplies and equipment, particularly in remote areas.
- The shift toward sustainability will drive the adoption of drones, as they provide a more eco-friendly alternative to traditional fuel-powered delivery vehicles.
- With urbanization on the rise, drones will become essential for overcoming logistical challenges in congested urban environments.
- The development of hybrid drones, capable of both long-range and short-range operations, will expand drone applications in diverse industries.
- The agriculture sector will increasingly rely on drones for tasks such as delivering pesticides, fertilizers, and seeds, improving crop management.
- Strategic partnerships between logistics companies and drone manufacturers will accelerate the deployment of drone delivery systems worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Drone Technology
Improvements in battery life, payload capacity, and autonomous navigation systems are making drones more capable and reliable for logistics, enabling longer-distance deliveries and heavier cargo transport.
Demand for Faster and Cost-Effective Delivery Solutions
The need for rapid, contactless, and affordable delivery - especially for last-mile logistics in urban and remote areas - is pushing companies to adopt drones, which can bypass road congestion and reduce operational costs.
Environmental Sustainability and Reduced Carbon Footprints
Drones, being electrically powered, offer a greener alternative to traditional fuel-based delivery vehicles, helping companies and governments meet sustainability goals and reduce urban emissions.
Regulatory Support and Infrastructure Development
Evolving regulatory frameworks and investments in drone infrastructure, such as air traffic management systems and designated drone corridors, are enabling safer and more widespread integration of drones into logistics networks.
Growth of E-Commerce and Urbanization
The expansion of e-commerce and increasing urban density are driving the need for innovative delivery methods, with drones providing efficient solutions for timely deliveries in congested or hard-to-reach locations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Drone Logistics & Transportation market?
What are the key drivers of the Drone Logistics & Transportation market?
Which region holds the largest market share for Drone Logistics & Transportation?
What is the role of drones in addressing environmental concerns?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Retail
- 1.2.2 Pharmaceuticals
- 1.2.3 Logistics Service Providers
- 1.2.4 Government & Military
- 1.2.5 Healthcare Institutions
- 1.3 By Drone Type
- 1.3.1 Fixed-Wing Drones
- 1.3.2 Rotary-Wing Drones
- 1.3.3 Hybrid Drones
- 1.4 By Application
- 1.4.1 E-commerce
- 1.4.2 Healthcare
- 1.4.3 Agriculture
- 1.4.4 Military & Defense
- 1.4.5 Industrial
- 1.5 By Operation Type
- 1.5.1 Manual Drones
- 1.5.2 Autonomous Drones
- 1.5.3 Semi-Autonomous Drones
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1574.66 million → 2032: USD 18428.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drone Logistics and Transportation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drone Logistics and Transportation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drone Logistics and Transportation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drone Logistics and Transportation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drone Logistics and Transportation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drone Logistics and Transportation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drone Logistics and Transportation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drone Logistics and Transportation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1574.66 million → 2032: USD 18428.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drone Logistics and Transportation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Retail
- 12.3.7.2 Pharmaceuticals
- 12.3.7.3 Logistics Service Providers
- 12.3.7.4 Government & Military
- 12.3.7.5 Healthcare Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drone Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed-Wing Drones
- 12.4.7.2 Rotary-Wing Drones
- 12.4.7.3 Hybrid Drones
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 E-commerce
- 12.5.7.2 Healthcare
- 12.5.7.3 Agriculture
- 12.5.7.4 Military & Defense
- 12.5.7.5 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Operation Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Manual Drones
- 12.6.7.2 Autonomous Drones
- 12.6.7.3 Semi-Autonomous Drones
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drone Logistics and Transportation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drone Logistics and Transportation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drone Logistics and Transportation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drone Logistics and Transportation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 UPS
- 18.4 DHL
- 18.5 Zipline
- 18.6 Wing Aviation
- 18.7 Matternet
- 18.8 Volansi
- 18.9 Drone Delivery Canada
- 18.10 Flirtey
- 18.11 Aerodyne Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

