
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| E-Sports and Game Streaming Market Size 2024 | USD 2604.6 million |
| E-Sports and Game Streaming Market, CAGR | 12.4% |
| E-Sports and Game Streaming MarketSize 2032 | USD 6635.4 million |
Market Overview:
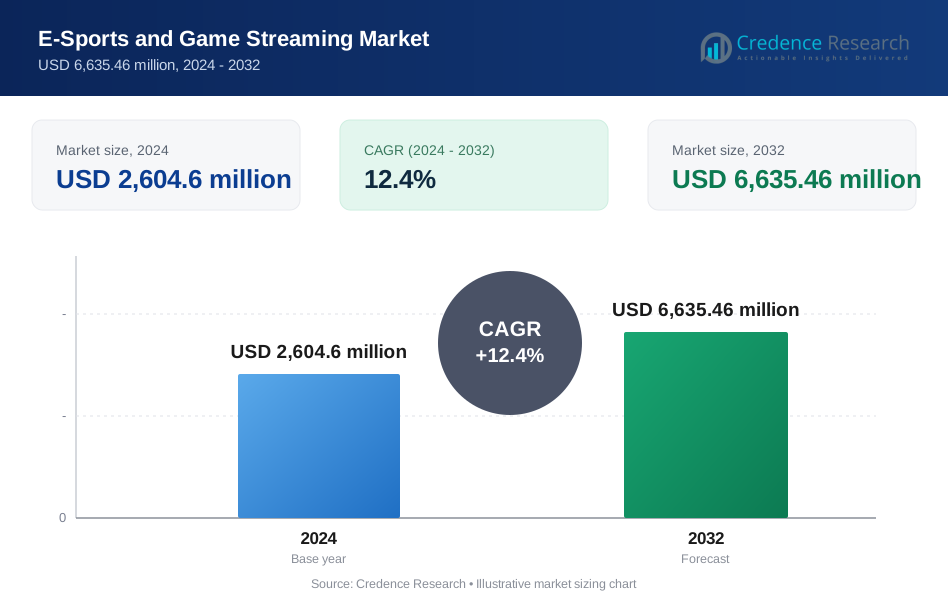
The E-Sports and Game Streaming Market is projected to grow from USD 2604.6 million in 2024 to an estimated USD 6635.4 million by 2032, with a compound annual growth rate (CAGR) of 12.4% from 2024 to 2032.
Several key factors are fueling the growth of the e-sports and game streaming market. The widespread availability of high-speed internet and the increasing penetration of smartphones have made gaming and streaming more accessible to a broader audience. Platforms like Twitch, YouTube Gaming, and Facebook Gaming have revolutionized content consumption by offering interactive and engaging experiences. Additionally, the surge in mobile gaming, particularly in emerging markets, has contributed significantly to market expansion. The integration of advanced technologies, such as augmented reality (AR) and virtual reality (VR), is enhancing user engagement, while the growing investment from sponsors and advertisers is providing substantial revenue streams for content creators and organizations.
Regionally, Asia Pacific dominates the e-sports and game streaming market, driven by a large and engaged gaming population, supportive government policies, and significant investments in infrastructure. Countries like China, South Korea, and Japan are at the forefront, with China recognizing e-sports as an official sport and South Korea hosting numerous international tournaments. North America follows closely, with the United States leading in terms of revenue generation and technological advancements. Europe is also witnessing substantial growth, attributed to increasing viewership and the establishment of professional leagues. Emerging markets in Latin America and the Middle East & Africa are gradually gaining traction, supported by improving internet infrastructure and a growing youth demographic interested in gaming and streaming activities.
Market Insights:
- The E-Sports and Game Streaming market is projected to grow from USD 2,604.6 million in 2024 to USD 6,635.4 million by 2032, at a CAGR of 12.4%, driven by rising global interest in digital entertainment.
- High-speed internet access and smartphone penetration are expanding participation in streaming and competitive gaming, especially in Asia Pacific and Latin America.
- Platforms like Twitch, YouTube Gaming, and Facebook Gaming have transformed viewer interaction by enabling real-time engagement and creator-driven content ecosystems.
- Competitive gaming tournaments with large prize pools and global fanbases are attracting substantial brand sponsorships and advertising revenue.
- AR, VR, and AI are being integrated to enhance content delivery, drive viewer retention, and differentiate streaming platforms in a competitive environment.
- Monetization challenges persist for smaller creators due to unequal revenue distribution, platform dependence, and audience fragmentation.
- Asia Pacific leads the market with a 40% share, followed by North America and Europe, while emerging regions like Latin America and the Middle East show rapid adoption potential.
Report Scope
This report segments the E-Sports and Game Streaming Market as follows: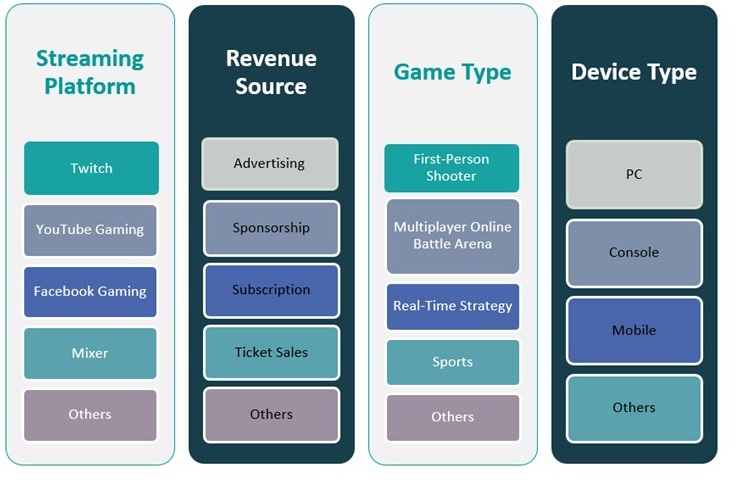
Market Drivers:
Surging Popularity of Competitive Gaming Drives Viewer Engagement and Revenue Potential
The E-Sports and Game Streaming Market is thriving due to the explosive growth in competitive gaming viewership. Audiences across age groups are increasingly drawn to professional e-sports tournaments, fostering a community-driven ecosystem around gaming culture. High-profile tournaments like League of Legends World Championship and The International attract millions of viewers and offer prize pools exceeding tens of millions of dollars. These events not only generate substantial revenue through sponsorships and advertising but also encourage participation at amateur levels. Live streaming platforms such as Twitch and YouTube Gaming enable real-time interaction between streamers and fans, enhancing engagement. The rise in viewership has incentivized brands to invest in the space, further strengthening the commercial viability of this sector.
- For instance, Riot Games reported that the 2023 League of Legends World Championship Finals reached a peak viewership of 6.4 million concurrent viewers globally, according to Esports Charts.
Expansion of High-Speed Internet and Mobile Penetration Enables Market Accessibility Across Demographics
Widespread access to high-speed internet and smartphones has opened up the E-Sports and Game Streaming Market to a global audience. Regions with previously low digital engagement are now contributing significantly to online traffic and content consumption. Improved infrastructure allows seamless game streaming and low-latency multiplayer experiences, making participation and viewership more enjoyable. Mobile gaming, in particular, has gained popularity in Asia Pacific and Latin America, creating a broader user base for streaming content. Affordable devices and increased mobile data coverage make it easier for new users to access competitive games and follow streamers. This accessibility expands the market’s demographic reach and attracts developers and content creators to tap into emerging economies.
Growing Investments from Advertisers, Sponsors, and Game Publishers Accelerate Commercialization
The commercialization of the E-Sports and Game Streaming Market is accelerating due to robust investments from global brands, sponsors, and gaming companies. Leading brands recognize the marketing potential of this market and actively pursue collaborations with top influencers and gaming tournaments. Sponsorship deals, product placements, and branded in-game content contribute significantly to revenue generation. Game publishers also benefit from increased visibility and extended game lifecycles through streamers who demonstrate gameplay and build loyal communities. It provides a direct marketing channel that influences purchasing behavior and boosts user retention. Strategic partnerships between streaming platforms and game developers further enhance monetization opportunities across the value chain.
- For example, in 2023, Mastercard renewed its global sponsorship agreement with Riot Games, extending its multi-year partnership for League of Legends e-sports events.
Adoption of Emerging Technologies Enhances Viewer Experience and Platform Differentiation
The E-Sports and Game Streaming Market is adopting advanced technologies to deliver immersive and personalized experiences. Augmented reality (AR), virtual reality (VR), and artificial intelligence (AI) are transforming how audiences interact with content. VR headsets enable fans to attend virtual arenas, while AI-driven recommendations improve content discovery and viewer retention. Real-time analytics provide streamers and platforms with insights to optimize performance and tailor content. Technology adoption also enhances security, reduces latency, and improves video quality across devices. These innovations differentiate platforms in a competitive landscape and elevate the overall user experience.
Market Trends:
Integration of Artificial Intelligence and Data Analytics is Reshaping Content Personalization and Monetization
The E-Sports and Game Streaming Market is witnessing a strong shift toward the use of artificial intelligence (AI) and data analytics to personalize user experiences. Platforms deploy AI to recommend content based on user preferences, viewing history, and engagement behavior. It enables streamers and content creators to analyze audience metrics and adapt their strategies in real time. Brands use analytics to optimize ad placements and measure return on investment across campaigns. This data-driven approach improves monetization, strengthens audience retention, and increases platform stickiness. AI tools also assist in moderating chatrooms and identifying potential risks to maintain a safe and engaging environment.
- For instance, Twitch uses AI to recommend streams based on user preferences and viewing history, while also providing streamers with real-time audience metrics to adapt content strategies.
Rise of Cross-Platform and Cloud Gaming is Driving a More Connected and Scalable Ecosystem
Cross-platform compatibility and cloud gaming are redefining how users access and participate in the E-Sports and Game Streaming Market. Gamers now engage across devices without traditional hardware constraints, creating a more connected ecosystem. Cloud gaming allows access to high-performance games on low-spec devices, removing barriers for new users. Streaming platforms benefit from increased traffic and engagement as content becomes more accessible. Game developers design titles to support multiple platforms from launch, ensuring broader reach and higher competitive participation. It creates new content opportunities for streamers while boosting inclusivity across markets with varying digital infrastructure.
Expansion of Exclusive Streaming Partnerships is Reshaping Platform Competition and Creator Loyalty
The E-Sports and Game Streaming Market is being influenced by a surge in exclusive streaming agreements between platforms and top-tier content creators. Platforms secure contracts with high-profile streamers to attract dedicated fan bases and increase daily active users. These deals include guaranteed revenue, performance-based incentives, and promotional support, creating a competitive advantage. Content creators benefit from increased visibility and platform-backed tools that enhance audience engagement. Viewers follow favorite streamers across platforms, shifting traffic and driving subscription revenues. It intensifies rivalry among streaming services, prompting them to innovate in content offerings and user interface enhancements.
- For example, Microsoft’s Xbox Cloud Gaming (formerly xCloud) allows users to stream games across smartphones, tablets, and PCs without the need for high-end hardware.
Growth of Virtual Events and Digital Fan Engagement is Changing How Audiences Interact with E-Sports
Virtual tournaments and interactive experiences are reshaping fan engagement in the E-Sports and Game Streaming Market. With audiences unable to attend in-person events consistently, platforms have enhanced digital interactions through virtual meetups, chat-integrated polling, and digital merchandise. Gamified viewing features like prediction challenges and reward points incentivize longer watch times. Tournament organizers integrate real-time commentary, multilingual streams, and behind-the-scenes content to enrich the viewer experience. It allows fans worldwide to participate actively regardless of location or time zone. This trend creates new revenue streams and deepens the emotional connection between audiences and e-sports brands.
Market Challenges Analysis:
Monetization Limitations and Revenue Fragmentation Create Growth Uncertainty for Emerging Creators
The E-Sports and Game Streaming Market faces significant challenges related to sustainable monetization and equitable revenue distribution. While top streamers and large organizations attract major sponsorships and advertising income, smaller creators often struggle to secure financial support. It limits content diversity and discourages new entrants from pursuing long-term engagement. Advertising models remain platform-dependent, with limited revenue-sharing flexibility for creators across different geographies. Subscription fatigue also affects consumer willingness to support multiple streamers or platforms. The growing number of content providers further dilutes viewership, making it harder for emerging talent to establish visibility and consistent income streams.
- For example, YouTube Gaming’s Partner Program only allows channels with at least 1,000 subscribers and 4,000 watch hours to monetize, leaving many small creators without access to ad revenue.
Cybersecurity Risks and Regulatory Complexities Undermine Platform Trust and Global Scalability
Cybersecurity vulnerabilities and inconsistent regulations present operational hurdles for the E-Sports and Game Streaming Market. Live-streamed content is vulnerable to unauthorized access, stream hijacking, and data breaches, which can damage platform credibility. It places pressure on service providers to invest in robust security infrastructure and real-time threat detection. Regulatory frameworks vary widely across regions, complicating cross-border content delivery and monetization. Compliance with data privacy laws such as GDPR and content moderation policies demands significant resources. Content platforms must also address challenges around age-appropriate engagement and digital well-being, especially for younger audiences frequently involved in e-sports and gaming content.
Market Opportunities:
The E-Sports and Game Streaming Market holds significant growth opportunities in emerging regions such as Southeast Asia, Latin America, and the Middle East. Rising internet penetration and growing smartphone adoption in these areas are enabling broader participation in streaming and competitive gaming. Local language content and culturally tailored experiences can help platforms engage new audiences. Governments in several countries are also supporting digital infrastructure and youth development in e-sports. It encourages both domestic content creation and international investment. Expanding into these regions allows platforms to diversify revenue sources and build loyal viewer communities.
Adopting immersive technologies such as augmented reality, virtual reality, and haptic feedback systems presents new engagement models in the E-Sports and Game Streaming Market. These innovations enhance how viewers interact with games and streamers, turning passive audiences into active participants. It creates new avenues for monetization through premium features, virtual goods, and interactive events. Brands can also explore product placement within virtual environments, blending advertising with entertainment. The integration of immersive tech elevates the viewing experience and strengthens platform differentiation. It helps retain users in a highly competitive digital media landscape.
Market Segmentation Analysis:
The E-Sports and Game Streaming Market is segmented by streaming platform, revenue source, game type, and device type.
By Streaming platforms, Twitch leads in global engagement, followed by YouTube Gaming and Facebook Gaming, while Mixer and other platforms cater to niche audiences. It reflects a growing preference for live, interactive content.
By revenue source, advertising remains the dominant stream, supported by strong viewer metrics and targeted campaigns. Sponsorship contributes significantly through tournament funding and brand collaborations. Subscription models drive platform loyalty, while ticket sales and other sources such as merchandise sales offer incremental revenue opportunities.
By game type, First-Person Shooter (FPS) and Multiplayer Online Battle Arena (MOBA) games generate the highest viewership due to competitive formats and fan engagement. Real-Time Strategy (RTS) and Sports games retain a dedicated following, while other genres expand the viewer base with diverse content.
By device type, mobile dominates in emerging markets due to accessibility and cost-efficiency. PC remains the preferred choice for high-performance gaming, while consoles offer seamless integration with streaming services. Others include smart TVs and tablets, which enhance cross-device viewing flexibility.
Segmentation:
By Streaming Platform
- Twitch
- YouTube Gaming
- Facebook Gaming
- Mixer
- Others
By Revenue Source
- Advertising
- Sponsorship
- Subscription
- Ticket Sales
- Others
By Game Type
- First-Person Shooter (FPS)
- Multiplayer Online Battle Arena (MOBA)
- Real-Time Strategy (RTS)
- Sports
- Others
By Device Type
- PC
- Console
- Mobile
- Others
Regional Analysis:
Asia Pacific Leads Global Growth with Expanding Mobile Gaming Ecosystem Asia Pacific holds the largest share of the E-Sports and Game Streaming Market, accounting for approximately 40% of global revenue. China, South Korea, and Japan anchor this dominance through a combination of massive user bases, government support, and advanced digital infrastructure. China leads in both viewership and platform development, while South Korea maintains its global influence through competitive leagues and talent cultivation. Japan’s console legacy continues to evolve with localized streaming content and partnerships. Mobile gaming plays a pivotal role, particularly in Southeast Asia, where affordable smartphones and data plans have accelerated adoption. India’s market is also expanding rapidly, driven by a young demographic and rising internet penetration. It positions Asia Pacific as the fastest-growing region in the global landscape.
North America Maintains Stronghold with Established Infrastructure and Premium Content North America contributes approximately 35% of the global E-Sports and Game Streaming Market revenue, underpinned by a mature ecosystem of professional leagues, exclusive content deals, and high consumer spending. The United States leads the region with established franchises, robust sponsorship networks, and technological innovation. Major publishers and streaming platforms headquartered in the U.S. drive content creation and distribution. Canada also contributes significantly through talent development and supportive policies. The region's advanced infrastructure and high disposable incomes support sustained growth and innovation. It continues to be a critical contributor to the industry's revenue.
Europe, Latin America, and Middle East & Africa Exhibit Emerging Potential Amid Infrastructure Improvements Europe holds a significant share of the E-Sports and Game Streaming Market, with countries like Germany, the United Kingdom, and Sweden leading in terms of viewership and infrastructure. The region benefits from a diverse range of gaming interests and a strong emphasis on community-driven content. Latin America, accounting for approximately 2.5% of global revenue, is experiencing rapid growth, particularly in Brazil and Mexico, driven by increasing internet penetration and a growing youth demographic. The Middle East and Africa, while currently holding a smaller market share, are witnessing gradual growth supported by improving internet infrastructure and a rising interest in gaming and streaming activities. It reflects a dynamic and varied landscape across these regions.
Key Player Analysis:
- com, Inc.
- Douyu TV (Tencent Holdings Limited)
- YouTube Gaming
- Facebook Gaming
- Twitch
Competitive Analysis:
The E-Sports and Game Streaming Market remains highly competitive, led by dominant players like Twitch (Amazon), YouTube Gaming (Google), and Facebook Gaming (Meta). These platforms compete through exclusive partnerships, real-time engagement features, and creator-centric tools. Twitch holds a strong position in North America, while YouTube Gaming expands its global influence with integrated video services and mobile reach. Facebook Gaming focuses on community interaction and regional expansion, especially in emerging markets. Chinese platforms like Douyu TV and Huya, backed by Tencent, command significant viewership in Asia. Game publishers such as Riot Games and Activision Blizzard further strengthen the ecosystem by producing competitive titles optimized for streaming. It encourages strategic collaborations between developers and platforms to drive user retention and engagement. Market leadership depends on technology innovation, content diversity, and the ability to monetize large, loyal audiences at scale. Competitive intensity continues to increase with rising investments and new market entrants.
Recent Developments:
- In July 2024, Amazon was announced as the Official Ecommerce Partner for the Esports World Cup (EWC). As part of this partnership, Amazon launched the Esports World Cup Hub, a dedicated online platform for fans in the Middle East and North Africa (MENA) region. This hub integrates live esports broadcasts-featuring the official EWC Twitch stream-with exclusive shopping deals on gaming devices and accessories, bringing together online retail and live streaming for the first time in this region.
- In late 2024, Douyu reinforced its position in the competitive Chinese esports streaming market by launching a series of self-produced esports events. These events not only spanned popular and niche games but also introduced a cross-platform cooperation model, notably through the "Delta Force: Xtreme" Tigerfish Bounty Cup, co-organized with Huya. This innovative approach integrated resources and audiences from both platforms, enhancing user engagement and setting a new industry benchmark for cross-platform collaboration.
Market Concentration & Characteristics:
The E-Sports and Game Streaming Market displays moderate to high market concentration, with a few dominant platforms controlling a large share of global traffic and revenue. Twitch, YouTube Gaming, and Huya lead the market through scale, exclusive content, and advanced engagement tools. It features strong network effects, where larger audiences attract top content creators and sponsors. The market is highly dynamic, shaped by rapid technology adoption, changing viewer preferences, and regional content demands. User loyalty often depends on creator relationships and platform experience. Entry barriers remain high due to infrastructure costs and the need for continuous innovation. Market consolidation through acquisitions and partnerships continues to influence competitive positioning.
Report Coverage:
The research report offers an in-depth analysis based on Streaming Platform, Revenue Source, Game Type and Device Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Viewer numbers will continue to rise, driven by growing internet access and mobile gaming adoption in emerging markets.
- Streaming platforms will invest in immersive technologies like AR and VR to enhance audience interaction.
- Sponsorship and advertising revenue will increase as brands prioritize digital engagement and influencer marketing.
- Exclusive content deals and creator partnerships will intensify competition among streaming platforms.
- Game publishers will expand in-house streaming capabilities to retain audience control and monetize directly.
- AI-driven personalization will shape content recommendations and viewer retention strategies.
- Regional platforms will gain traction by offering localized content and language-specific streams.
- Cloud gaming integration will expand access to high-performance games, drawing new users to live streams.
- Regulatory oversight on digital content and data privacy will shape platform operations and monetization models.
- Strategic acquisitions and cross-industry collaborations will define market consolidation and global expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surging Popularity of Competitive Gaming
The explosive growth in e-sports tournaments and professional gaming leagues is attracting millions of viewers globally, driving engagement and creating lucrative opportunities for sponsorship and advertising revenue.
Expansion of High-Speed Internet and Mobile Penetration
Widespread access to high-speed internet and affordable smartphones is making game streaming and e-sports accessible to broader demographics, especially in emerging markets, significantly expanding the user base.
Growing Investments from Advertisers, Sponsors, and Game Publishers
Major brands and game publishers are increasing investments in sponsorships, exclusive content, and influencer partnerships, accelerating the commercialization and monetization of streaming platforms and tournaments.
Adoption of Emerging Technologies
Integration of AR, VR, and AI is enhancing user engagement and content personalization, differentiating platforms and improving the overall viewer experience, which attracts and retains larger audiences.
Rise of Cross-Platform and Cloud Gaming
Cross-platform compatibility and cloud gaming are reducing hardware barriers, enabling more users to participate in streaming and e-sports activities across devices, thus broadening market reach and engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the E-Sports and Games Streaming Market?
What factors are driving the growth of the E-Sports and Games Streaming Market?
What are the key segments within the E-Sports and Games Streaming Market?
What are some challenges faced by the E-Sports and Games Streaming Market?
Who are the major players in the E-Sports and Games Streaming Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Game Type
- 1.2.1 First-Person Shooter (FPS)
- 1.2.2 Multiplayer Online Battle Arena (MOBA)
- 1.2.3 Real-Time Strategy (RTS)
- 1.2.4 Sports
- 1.2.5 Others
- 1.3 By Device Type
- 1.3.1 PC
- 1.3.2 Console
- 1.3.3 Mobile
- 1.3.4 Others
- 1.4 By Revenue Source
- 1.4.1 Advertising
- 1.4.2 Sponsorship
- 1.4.3 Subscription
- 1.4.4 Ticket Sales
- 1.4.5 Others
- 1.5 By Streaming Platform
- 1.5.1 Twitch
- 1.5.2 YouTube Gaming
- 1.5.3 Facebook Gaming
- 1.5.4 Mixer
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,604.6 million → 2032: USD 6,635.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global E-Sports and Game Streaming Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global E-Sports and Game Streaming Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global E-Sports and Game Streaming Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global E-Sports and Game Streaming Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global E-Sports and Game Streaming Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global E-Sports and Game Streaming Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global E-Sports and Game Streaming Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global E-Sports and Game Streaming Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,604.6 million → 2032: USD 6,635.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global E-Sports and Game Streaming Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Game Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 First-Person Shooter (FPS)
- 12.3.7.2 Multiplayer Online Battle Arena (MOBA)
- 12.3.7.3 Real-Time Strategy (RTS)
- 12.3.7.4 Sports
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Device Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 PC
- 12.4.7.2 Console
- 12.4.7.3 Mobile
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Revenue Source - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Advertising
- 12.5.7.2 Sponsorship
- 12.5.7.3 Subscription
- 12.5.7.4 Ticket Sales
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Streaming Platform - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Twitch
- 12.6.7.2 YouTube Gaming
- 12.6.7.3 Facebook Gaming
- 12.6.7.4 Mixer
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global E-Sports and Game Streaming Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global E-Sports and Game Streaming Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global E-Sports and Game Streaming Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Twitch (Amazon.com, Inc.)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 YouTube Gaming (Google LLC)
- 17.4 Facebook Gaming (Meta Platforms, Inc.)
- 17.5 Douyu TV (Tencent Holdings Limited)
- 17.6 Huya Inc.
- 17.7 Riot Games, Inc.
- 17.8 Activision Blizzard, Inc.
- 17.9 Microsoft Corporation
- 17.10 Nimo TV
- 17.11 Garena
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

