
Market Overview
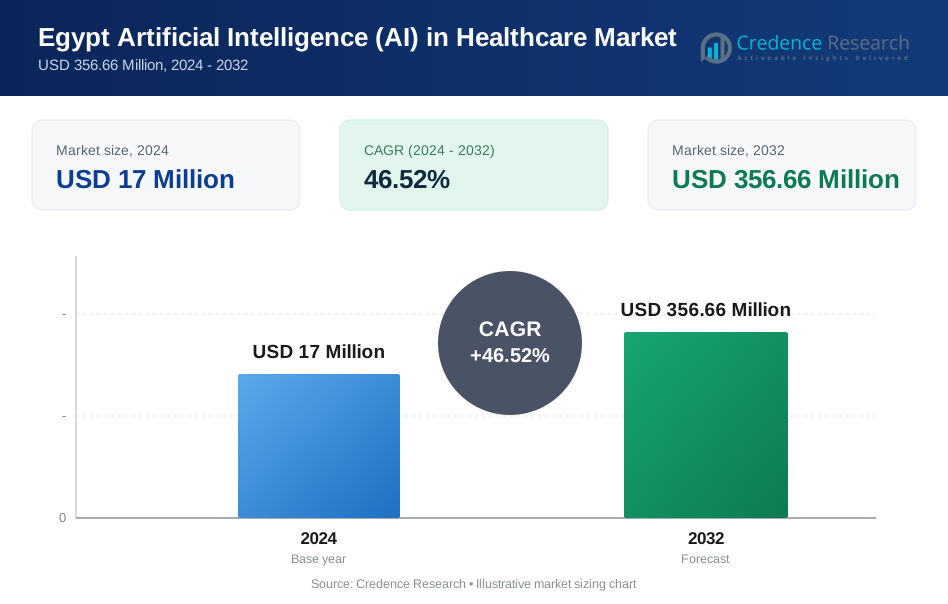
Egypt Artificial Intelligence (AI) in Healthcare Market was valued at USD 17 Million in 2024 and is projected to reach USD 356.66 Million by 2032, growing at a CAGR of 46.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Egypt Artificial Intelligence (AI) in Healthcare Market Size 2024 | USD 17 Million |
| Egypt Artificial Intelligence (AI) in Healthcare Market, CAGR | 46.52% |
| Egypt Artificial Intelligence (AI) in Healthcare Market Size 2032 | USD 356.66 Million |
Egypt Artificial Intelligence (AI) in Healthcare Market is led by a mix of established technology providers and innovative startups driving AI adoption across diagnostics, treatment planning, and patient monitoring. Key players, including InnoTech Medical Solutions, Medispec, Nile University’s Medical Image and Signal Processing (MISP) Lab, Faisal Misbah Mahmoud Radiology Center, BrainVISA Technologies, Scintilla for Medical Supplies, BMEYE, Crystal Technology, and NewTech Medical Devices, are actively investing in AI-enabled imaging, predictive analytics, and telemedicine solutions. Cairo dominates the market with a 38.4% share in 2024, supported by a concentration of hospitals, research institutes, and startups. Alexandria follows with 21.7% share, benefiting from growing private healthcare infrastructure and academic collaborations, while Giza contributes 15.3% share. Other regions collectively hold 24.6%, showing steady adoption driven by regional hospitals and government health initiatives. The competitive landscape emphasizes innovation, partnerships, and localized AI solutions tailored to Egypt’s healthcare needs.
Market Insights
- The Egypt Artificial Intelligence (AI) in Healthcare market was valued at USD 17 million in 2024 and is projected to reach USD 356.66 million by 2032, growing at a CAGR of 46.52%.
- Rising demand for accurate diagnostics, telemedicine, and personalized treatment is driving adoption of AI solutions across hospitals, diagnostic centers, and research institutes.
- Key trends include the integration of AI with wearable devices, IoT platforms, and cloud-based analytics, as well as the use of AI in drug discovery and predictive patient monitoring.
- Major players include InnoTech Medical Solutions, Medispec, Nile University’s MISP Lab, Faisal Misbah Mahmoud Radiology Center, BrainVISA Technologies, Scintilla for Medical Supplies, BMEYE, Crystal Technology, and NewTech Medical Devices, focusing on innovation, partnerships, and localized AI solutions.
- Cairo leads with 38.4% share, followed by Alexandria at 21.7%, Giza at 15.3%, and other regions collectively holding 24.6%, with diagnostics and hospitals & clinics segments dominating adoption.
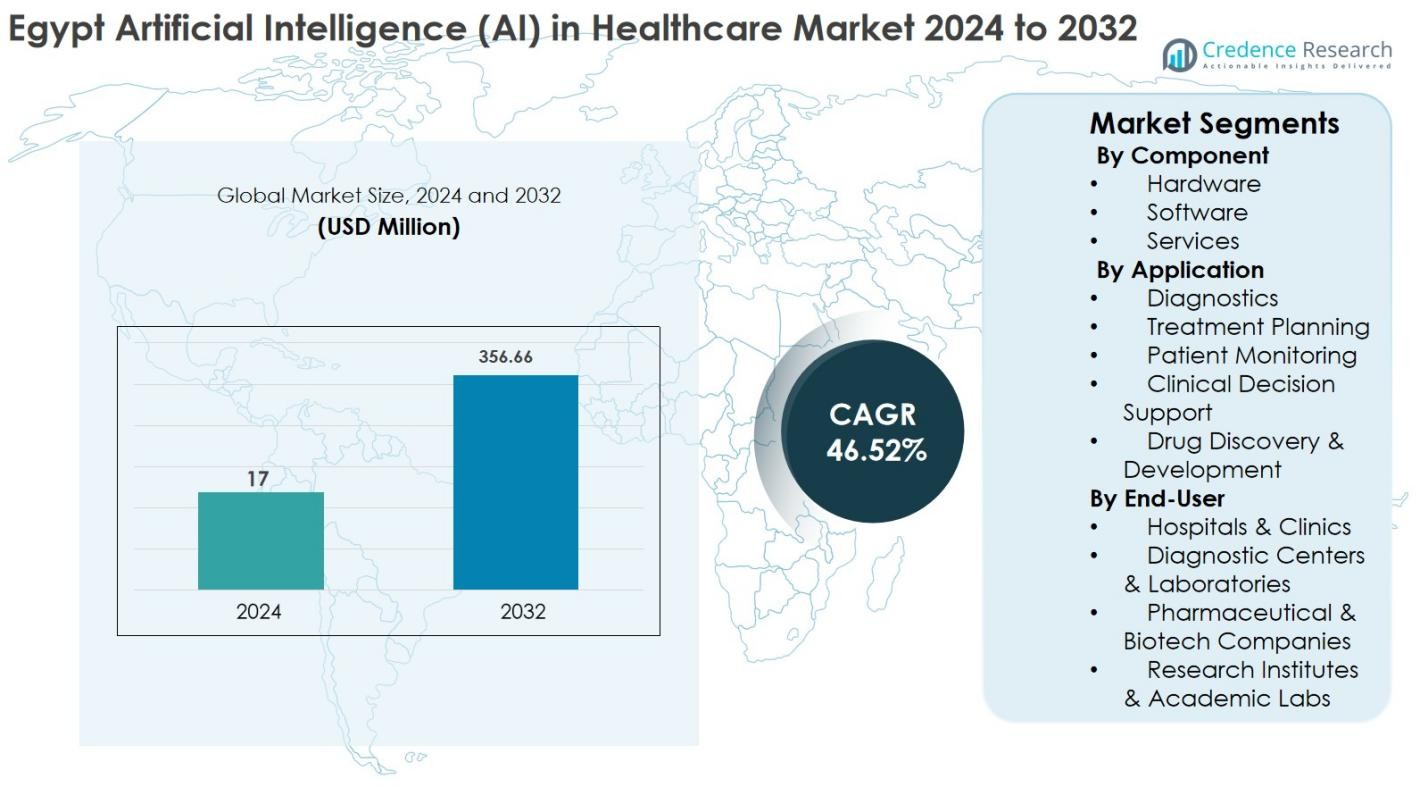 Market Segmentation Analysis:
By Component
The Hardware segment dominates the Egypt Artificial Intelligence (AI) in Healthcare market with a 41.8% share in 2024, driven by increasing adoption of AI-enabled imaging devices, diagnostic machines, and wearable medical devices. Hospitals and diagnostic centers are investing heavily in advanced hardware to enhance accuracy and reduce diagnostic time. The Software sub-segment is witnessing rapid growth due to AI-powered analytics, predictive modeling, and treatment planning platforms, while Services, including consulting, implementation, and maintenance, support efficient deployment and integration of AI solutions across healthcare facilities. Rising healthcare digitization continues to fuel overall segment growth.
- For instance, Siemens Healthineers introduced a suite of AI-powered imaging and diagnostic systems in Egypt, such as the photon-counting NAEOTOM Alpha.Prime CT scanner and AI-driven MOBILETT Elara Max mobile X-ray unit, designed to enhance imaging precision and streamline clinical workflows in hospitals and emergency departments.
By Application
In the application segment, Diagnostics holds the leading position with a 45.6% market share in 2024, primarily driven by AI-based imaging, radiology, and pathology tools that improve early disease detection. Treatment Planning and Patient Monitoring are experiencing strong growth as hospitals increasingly adopt personalized medicine and remote monitoring solutions. AI-powered Clinical Decision Support enhances physicians’ efficiency, while Drug Discovery & Development leverages machine learning to accelerate research. Key drivers include rising demand for accurate diagnostics, early intervention, and the integration of AI technologies in patient care workflows.
- For instance, Royal Philips launched the AI-enabled CT-5300 system, equipped with advanced AI reconstruction and smart workflow automation to increase diagnostic confidence and streamline image interpretation across a range of clinical indications.
By End-User
Among end-users, Hospitals & Clinics dominate with a 48.3% share in 2024, fueled by the need for advanced AI solutions to improve clinical outcomes and operational efficiency. Diagnostic Centers & Laboratories are rapidly adopting AI tools for imaging and lab analysis, while Pharmaceutical & Biotech Companies leverage AI for drug development and predictive modeling. Research Institutes & Academic Labs drive innovation and pilot AI applications in healthcare. Strong government initiatives, rising healthcare spending, and a focus on digital transformation continue to propel adoption across all end-user segments in Egypt.
Key Growth Drivers
Rising Demand for Accurate Diagnostics
The Egypt Artificial Intelligence (AI) in Healthcare market is primarily driven by the growing need for accurate and timely diagnostics. Hospitals and diagnostic centers increasingly rely on AI-enabled imaging devices, pathology tools, and predictive analytics to detect diseases early and reduce human error. This demand is fueled by the rising prevalence of chronic diseases, cancer, and cardiovascular conditions, which require precise and rapid assessment. AI integration enhances diagnostic efficiency, shortens patient waiting times, and supports personalized treatment planning. Additionally, government initiatives to modernize healthcare infrastructure and promote digital health adoption further accelerate the deployment of AI technologies. Investments in AI-powered diagnostic platforms by both public and private healthcare providers are creating significant growth opportunities, making early and precise disease detection a central growth driver in the market.
- For instance, Philips’ AI-enabled radiology and enterprise imaging solutions support automated workflow orchestration, lesion detection, and image quality enhancement, allowing clinicians to prioritize critical cases and reduce interpretation time in high-volume diagnostic centers.
Expansion of Telemedicine and Remote Patient Monitoring
The proliferation of telemedicine and remote patient monitoring solutions is a key growth driver for AI in Egypt’s healthcare sector. AI-powered tools enable continuous monitoring of vital signs, chronic disease management, and predictive alerts for critical conditions, reducing hospital readmissions and improving patient outcomes. The COVID-19 pandemic accelerated the adoption of remote healthcare solutions, highlighting the importance of AI-enabled platforms in ensuring uninterrupted care. Hospitals and clinics increasingly integrate AI into wearable devices, mobile applications, and cloud-based monitoring systems to deliver personalized and proactive care. This trend is supported by rising smartphone penetration, improved internet connectivity, and growing patient awareness, creating a conducive environment for the adoption of AI technologies. Consequently, the integration of AI in telemedicine and remote monitoring continues to expand the market significantly.
- For instance, Egypt’s Ministry of Health expanded telemedicine and digital health platforms under national health transformation programs, enabling remote consultations and AI-supported monitoring for chronic disease patients in underserved regions.
Increasing Investment in Healthcare Digitization
Significant investments in healthcare digitization are driving the Egypt AI in Healthcare market forward. Hospitals, clinics, and research institutes are deploying electronic health records (EHR), AI-powered analytics platforms, and digital imaging solutions to enhance operational efficiency and patient care. Private and public sector funding is being channeled toward AI research, pilot programs, and infrastructure upgrades to support predictive modeling, clinical decision support, and treatment optimization. Digital transformation initiatives are further accelerated by government policies encouraging technology adoption and the modernization of healthcare systems. The focus on integrating AI with cloud-based solutions, big data analytics, and IoT devices creates an ecosystem that enables advanced diagnostics, real-time monitoring, and personalized treatment, positioning AI as a pivotal component of Egypt’s healthcare evolution.
Key Trends & Opportunities
Adoption of AI in Drug Discovery and Personalized Medicine
A major trend in Egypt’s AI in Healthcare market is the adoption of AI for drug discovery and personalized medicine. Pharmaceutical companies and research institutes are leveraging AI algorithms to predict drug efficacy, optimize clinical trials, and identify patient-specific treatment regimens. This accelerates the drug development process and reduces costs while improving therapeutic outcomes. Personalized medicine applications use patient data, genomics, and predictive analytics to tailor treatments, enhancing patient satisfaction and clinical success rates. The increasing collaboration between AI startups, healthcare providers, and academic labs provides a strong opportunity for innovative solutions. As Egypt’s healthcare ecosystem embraces precision medicine, AI-driven drug discovery and personalized care represent significant growth avenues, fostering innovation and improved healthcare delivery.
- For instance, Insilico Medicine used its AI platform to identify a novel fibrosis drug candidate that advanced from target discovery to preclinical testing in under 18 months, demonstrating how AI can significantly compress traditional drug development cycles.
Integration of AI with Wearable and IoT Devices
The integration of AI with wearable devices and IoT platforms presents a promising opportunity in the Egypt healthcare market. AI-powered wearables monitor vital signs, track chronic conditions, and provide predictive health insights, enabling proactive interventions. IoT-enabled devices transmit real-time patient data to healthcare providers, improving remote monitoring and reducing hospital visits. Rising smartphone penetration, increasing health awareness, and the demand for preventive care support adoption. Additionally, integration with cloud computing and AI analytics allows scalable data-driven healthcare solutions. Hospitals, clinics, and research labs are increasingly investing in smart devices that offer actionable insights, making AI-enabled IoT and wearable technologies a key trend with high growth potential in Egypt’s healthcare landscape.
- For instance, Apple Watch’s FDA-cleared ECG and heart rhythm monitoring features use machine-learning algorithms to detect atrial fibrillation and irregular heart rhythms, supporting large-scale adoption of AI-driven preventive cardiac monitoring through consumer wearables.
Key Challenges
Data Privacy and Security Concerns
Data privacy and security remain significant challenges in Egypt’s AI in Healthcare market. The collection, storage, and analysis of sensitive patient data through AI platforms and cloud-based systems expose healthcare providers to potential breaches and unauthorized access. Strict regulatory compliance, patient confidentiality, and ethical concerns create barriers for AI deployment. Limited awareness among healthcare staff regarding cybersecurity protocols further exacerbates risks. Ensuring robust encryption, secure data sharing, and compliance with emerging local and international regulations requires substantial investment and technical expertise. These challenges can slow the adoption of AI technologies despite their clear benefits, making data privacy and cybersecurity critical obstacles to market growth.
High Implementation Costs and Technical Complexity
High implementation costs and technical complexity pose a major challenge for AI adoption in Egypt’s healthcare sector. Deploying AI solutions requires substantial investment in hardware, software, infrastructure, and staff training, which can be prohibitive for small clinics and diagnostic centers. The technical expertise needed to integrate AI with existing healthcare systems, manage algorithms, and maintain devices adds to operational challenges. Limited local expertise in AI development and healthcare technology can delay adoption and increase dependency on external vendors. These factors hinder scalability and slow down market penetration, especially in smaller or resource-constrained healthcare facilities, making cost and complexity a persistent barrier for AI growth.
Regional Analysis
Cairo
Cairo leads the Egypt Artificial Intelligence (AI) in Healthcare market with a 38.4% share in 2024, driven by its status as the country’s primary hub for healthcare services, research institutions, and technology adoption. Major hospitals, diagnostic centers, and AI-focused startups are concentrated here, accelerating the deployment of AI-enabled imaging, diagnostics, and patient monitoring solutions. Government initiatives supporting digital health, coupled with private sector investments, enhance accessibility and infrastructure for AI integration. The presence of academic and research institutes fosters innovation in AI applications, including predictive analytics and treatment planning, making Cairo the dominant region in the national AI healthcare landscape.
Alexandria
Alexandria accounts for 21.7% share of the Egypt AI in Healthcare market in 2024, benefiting from a growing network of hospitals, medical research centers, and private diagnostic facilities. The city is witnessing increasing adoption of AI-powered diagnostics, telemedicine, and patient monitoring platforms due to rising healthcare awareness and urbanization. Local investments in technology infrastructure and collaborations between academic institutions and healthcare providers support AI innovation. Rising chronic disease prevalence and demand for high-quality healthcare services drive AI integration, positioning Alexandria as a key secondary hub for AI applications in diagnostics, treatment planning, and remote patient care within Egypt.
Giza
Giza contributes a 15.3% share to the Egypt AI in Healthcare market in 2024, supported by its proximity to Cairo and expanding healthcare infrastructure. The region is witnessing gradual adoption of AI-enabled imaging systems, clinical decision support tools, and patient monitoring solutions across hospitals and diagnostic centers. Investment in digital health initiatives, training programs for medical professionals, and AI research collaborations encourage market growth. Rising urban population and increasing demand for accurate diagnostics and personalized treatment are fueling adoption. Giza is becoming a growing market for AI solutions, complementing Cairo’s dominance while providing access to innovative healthcare technologies in western Egypt.
Others
Other regions, including Luxor, Aswan, and Suez, collectively hold a 24.6% share of the Egypt AI in Healthcare market in 2024. These areas are experiencing steady adoption of AI-enabled diagnostics, remote monitoring, and telemedicine solutions, driven by regional hospitals, clinics, and government health initiatives. Investments in healthcare infrastructure, increasing digital literacy, and rising awareness of chronic diseases contribute to market growth. Although adoption rates are lower than in major urban centers, initiatives to expand AI capabilities and pilot projects in smaller cities are creating opportunities for growth, enabling broader access to advanced healthcare technologies across Egypt.
Market Segmentations:
By Component
- Hardware
- Software
- Services
By Application
- Diagnostics
- Treatment Planning
- Patient Monitoring
- Clinical Decision Support
- Drug Discovery & Development
By End-User
- Hospitals & Clinics
- Diagnostic Centers & Laboratories
- Pharmaceutical & Biotech Companies
- Research Institutes & Academic Labs
By Geography
- Cairo
- Alexandria
- Giza
- Others
Competitive Landscape
The Egypt Artificial Intelligence (AI) in Healthcare market is characterized by the presence of both established technology providers and innovative startups, fostering a dynamic competitive landscape. Key players such as InnoTech Medical Solutions, Medispec, Nile University’s Medical Image and Signal Processing (MISP) Lab, Faisal Misbah Mahmoud Radiology Center, BrainVISA Technologies, Scintilla for Medical Supplies, BMEYE, Crystal Technology, and NewTech Medical Devices are actively investing in AI-powered imaging, diagnostics, treatment planning, and patient monitoring solutions. Companies focus on strategic partnerships, technology collaborations, and pilot projects with hospitals, clinics, and research institutes to enhance market penetration. Product innovation, particularly in AI software platforms, wearable devices, and predictive analytics, remains a primary differentiator. Competitive strategies also emphasize local support, customization for regional healthcare needs, and training services. Rising adoption of AI across diagnostics, telemedicine, and personalized medicine drives companies to expand their presence, ensuring rapid innovation and positioning Egypt as a growing hub for AI-enabled healthcare solutions.
Key Player Analysis
- Crystal Technology
- BrainVISA Technologies
- Medispec
- One Way Forward
- InnoTech Medical Solutions
- Scintilla for Medical Supplies
- BMEYE
- Nile University’s Medical Image and Signal Processing (MISP) Lab
- NewTech Medical Devices
- Faisal Misbah Mahmoud Radiology Center
Recent Developments
- In December 2025, Egypt-based health-tech company Rology closed a significant growth funding round, attracting investment from global healthcare leaders such as the Philips Foundation, Johnson & Johnson Impact Ventures, Sanofi Global Health Unit’s Impact Fund, and MIT Solve Innovation Future to expand its AI-powered teleradiology platform across the Middle East and Africa, enhancing diagnostic capacity and regional presence.
- In November 2025, Rology won the $100,000 grand prize at Meta’s AMET AI Accelerator competition for its innovative AI-powered teleradiology platform, gaining mentorship and technical support from Meta to further enhance its technology and market reach.
- In July 2025, Telecom Egypt signed a Memorandum of Understanding (MoU) with KareXpert, a Reliance Jio-backed healthcare technology company, to launch a comprehensive AI-powered digital healthcare platform hosted on a national cloud in Egypt that integrates hospital management systems, unified electronic medical records (EMR), and revenue cycle management tools to improve hospital efficiency and digital service delivery.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI adoption in diagnostics and imaging is expected to expand rapidly across hospitals and clinics.
- Telemedicine and remote patient monitoring will increasingly integrate AI for proactive care.
- Personalized medicine and AI-driven treatment planning will see broader implementation.
- AI-powered predictive analytics will improve early disease detection and clinical decision-making.
- Integration of AI with wearable and IoT devices will enhance patient monitoring and preventive care.
- Pharmaceutical and biotech companies will increasingly leverage AI for drug discovery and development.
- Collaboration between AI startups, hospitals, and research institutes will drive innovation.
- Government initiatives and digital health policies will continue to support AI deployment.
- Investment in healthcare digitization and AI infrastructure will accelerate market growth.
- Regional adoption will expand beyond major cities, increasing access to AI healthcare solutions nationwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Egypt Artificial Intelligence (AI) in Healthcare market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Egypt Artificial Intelligence (AI) in Healthcare market projected to grow between 2024 and 2032?
Which Egypt Artificial Intelligence (AI) in Healthcare market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Egypt Artificial Intelligence (AI) in Healthcare market?
Who are the leading companies in the Egypt Artificial Intelligence (AI) in Healthcare market?
Which region commanded the largest share of the Egypt Artificial Intelligence (AI) in Healthcare market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17 Million → 2032: USD 356.66 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Egypt Artificial Intelligence (AI) in Healthcare Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Egypt Artificial Intelligence (AI) in Healthcare Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Egypt Artificial Intelligence (AI) in Healthcare Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Egypt Artificial Intelligence (AI) in Healthcare Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Egypt Artificial Intelligence (AI) in Healthcare Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Egypt Artificial Intelligence (AI) in Healthcare Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Egypt Artificial Intelligence (AI) in Healthcare Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Egypt Artificial Intelligence (AI) in Healthcare Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17 Million → 2032: USD 356.66 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Egypt Artificial Intelligence (AI) in Healthcare Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Egypt Artificial Intelligence (AI) in Healthcare Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Egypt Artificial Intelligence (AI) in Healthcare Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Egypt Artificial Intelligence (AI) in Healthcare Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
