
Sovereign Arabic models set local data demand
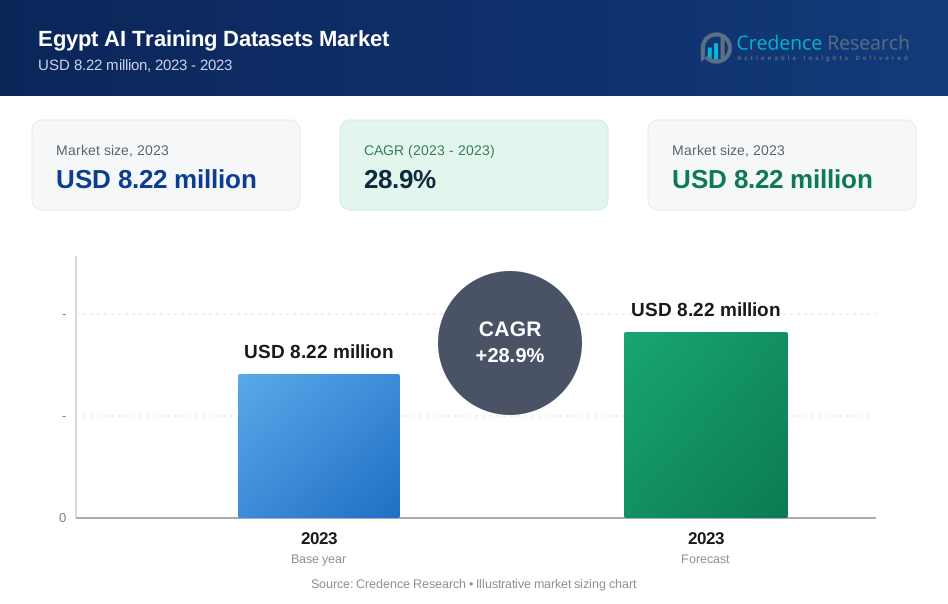
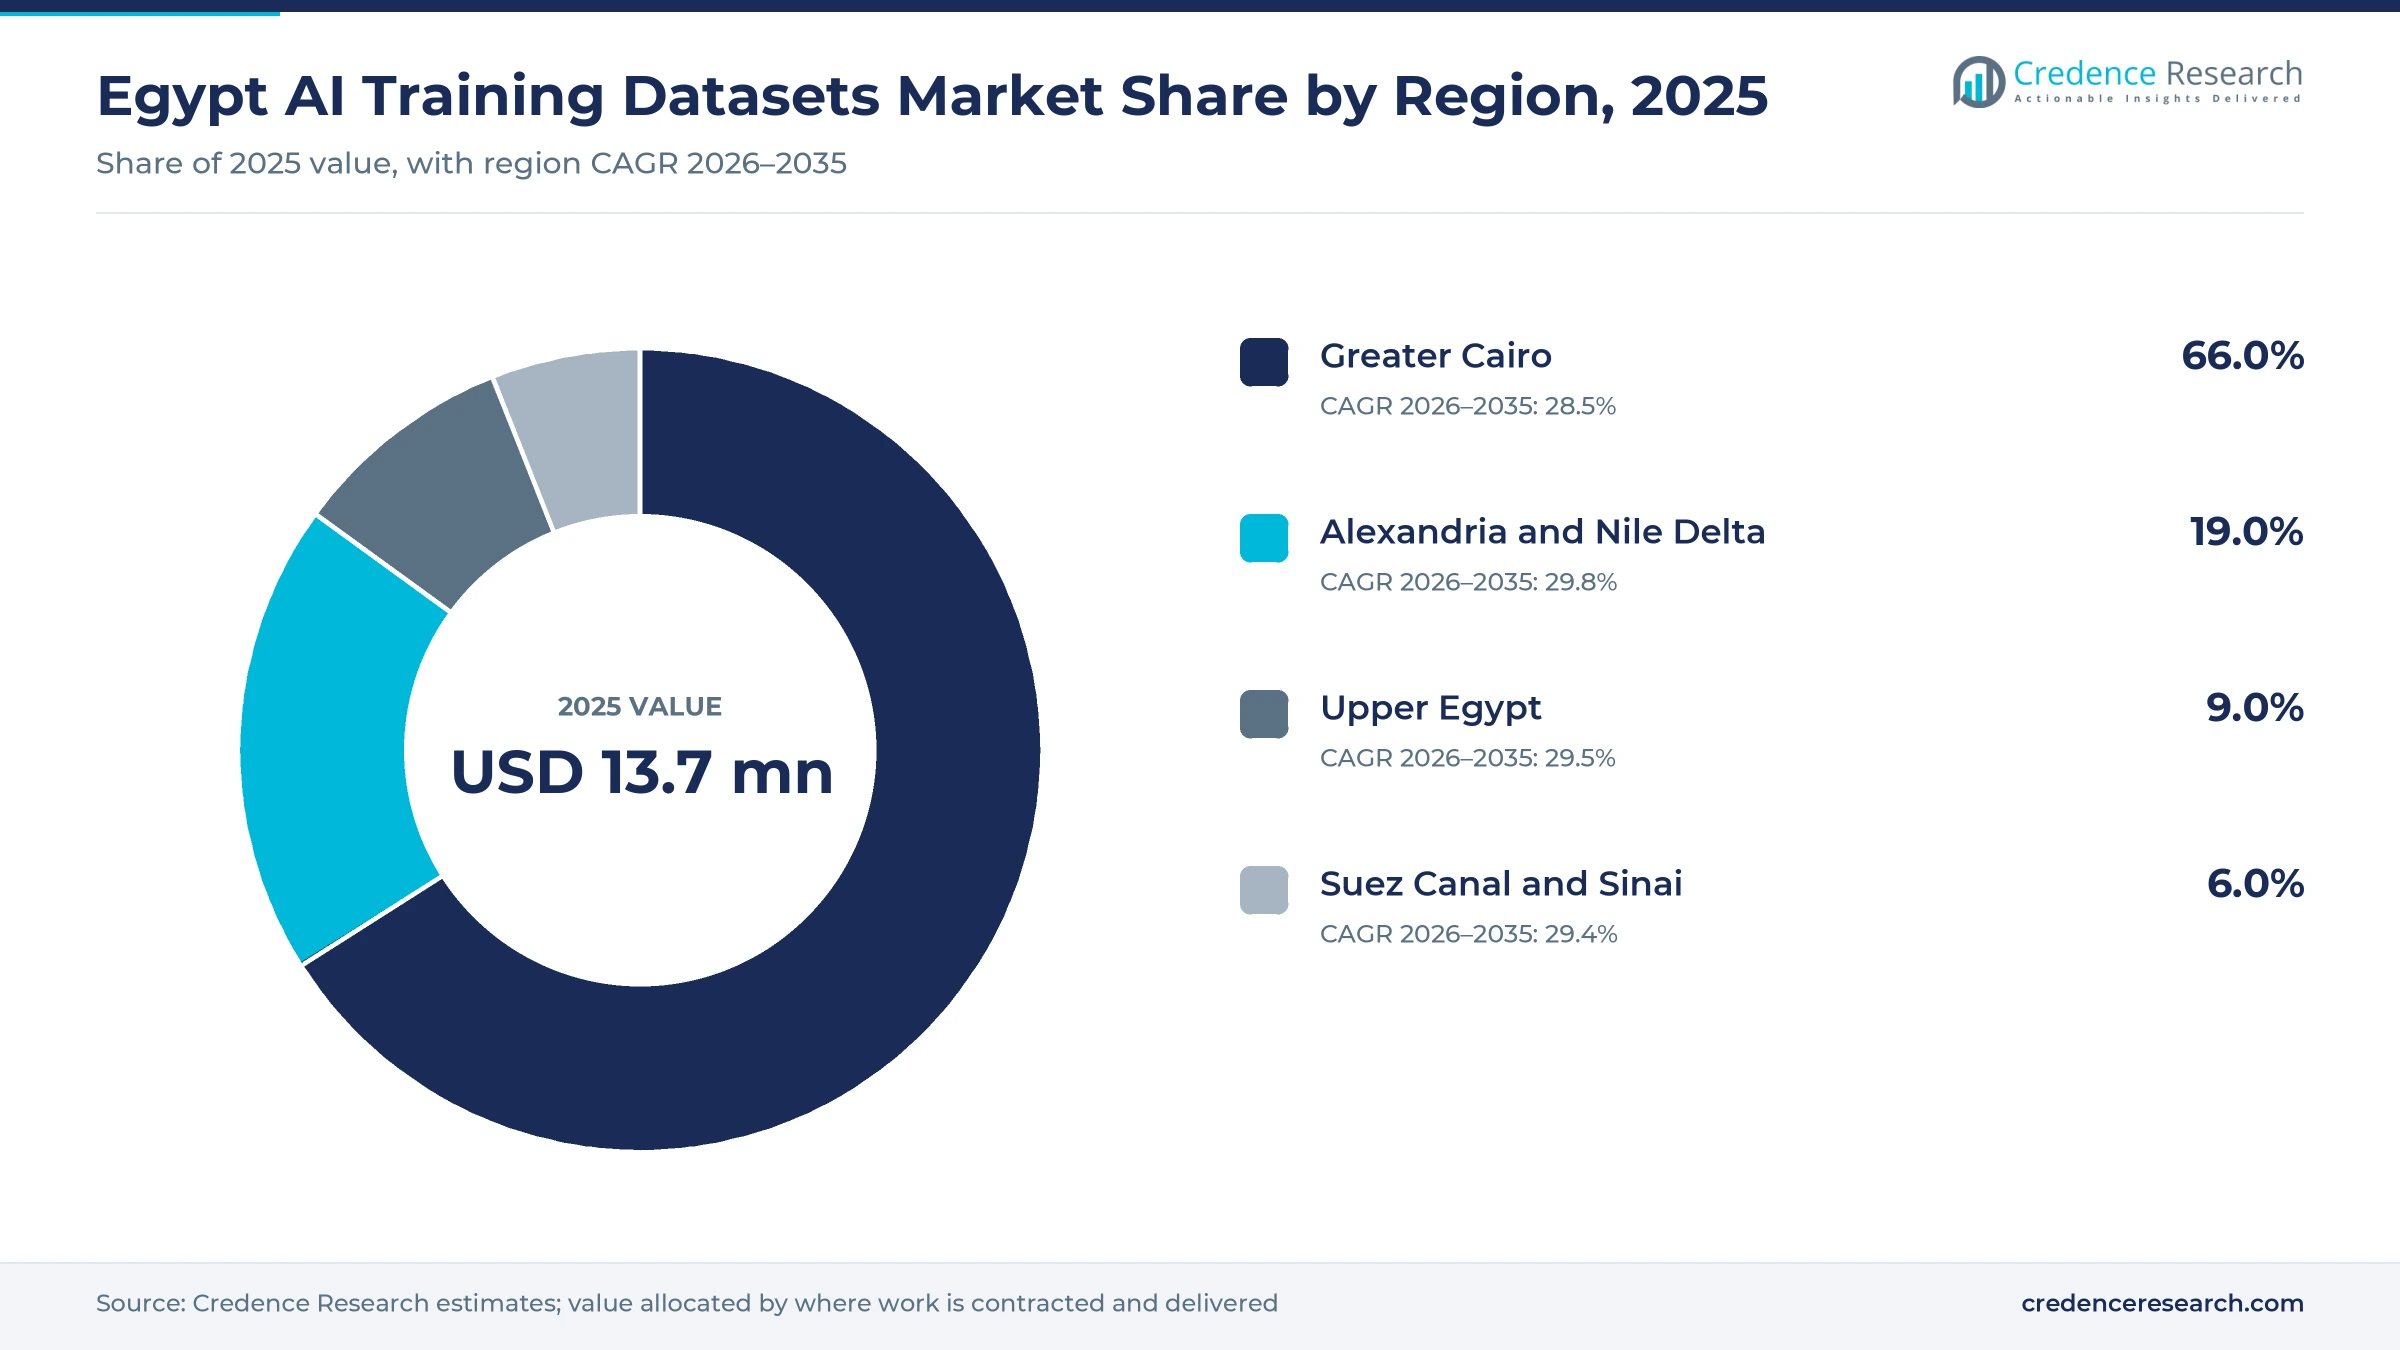
The Egypt AI training datasets market was valued at USD 13.7 million in 2025 and is projected to increase from USD 17.6 million in 2026 to USD 173.0 million by 2035, registering a CAGR of 28.90% during 2026–2035. Demand comes from the Ministry of Communications and Information Technology, which builds Arabic language models for public services, and from telecom operators, banks, fintech lenders and hospitals that train models on Egyptian text, speech and images. Greater Cairo held the largest regional share, 66.0% in 2025, because ministries, bank headquarters and most engineering centers sit in Cairo, Giza and Smart Village. Alexandria and Nile Delta is the fastest-growing region, as global delivery centers there add Arabic labeling teams. The executive regulations of the Personal Data Protection Law, issued in November 2025, now require a license before personal data is collected or sent abroad, which favors suppliers that can collect and store Egyptian data onshore.
Curated corpora, licensed data and labeling services make up the count
The market counts the value of training data that organizations in Egypt buy to build machine learning models. It covers licensed off-the-shelf datasets, custom collection of text, speech, images and video, annotation and transcription services, preference and evaluation data for language models, and synthetic data generated to stand in for scarce or sensitive records.
Annotation work that Egyptian delivery centers perform for foreign clients is excluded, as are labeling software licences sold without data and the cost of compute used for training. Value moves from crowds of native Egyptian Arabic speakers, delivery centers and data owners through dataset vendors and integrators to model builders in government, telecom, finance, health and engineering.
Egypt AI Training Datasets Market Insights
- The Egypt AI training datasets market rises from USD 13.7 million in 2025 to USD 173.0 million by 2035, a 28.90% CAGR during 2026–2035, as sovereign Arabic models and regulated buyers need local data.
- Greater Cairo held 66.0% of 2025 value, because ministries, bank headquarters and engineering centers in Cairo, Giza and Smart Village contract most data work.
- Text held 35.0% of 2025 value, since language model builders such as the Applied Innovation Center curate Egyptian and Arabic documents first.
- MCIT launched Karnak, a national Arabic large language model, at Ai Everything MEA Egypt in February 2026, and BelMasry speech engines followed in August 2026.
- Vodafone Business, Elsewedy Electric and Cassava plan an AI data center rising from 20 MW to 200 MW, which keeps training data and compute inside Egypt.
Text leads while Egyptian speech data grows fastest
Text corpora lead while Egyptian speech data grows fastest
Based on type, the market is categorized into text, audio, image, video and others (sensor and geo). Text led with 35.0% of 2025 value because large language models consume curated documents first, and the Applied Innovation Center built Karnak Chat on curated Egyptian and Arab data and documents, Mena Startup Digest reported. Audio grows fastest at 30.0% a year, as speech engines need recorded and transcribed dialect. A CrowdGen project for Appen posted in March 2026 recruits Egypt residents to record scripted Egyptian Arabic commands in sessions of 500 prompts.
On-premises delivery leads as onshore cloud grows faster
Based on deployment mode, the market is categorized into on-premises and cloud. On-Premises led with 55.0% of 2025 value because government bodies and banks keep raw personal data inside their own networks. Synapse Analytics, which raised a USD 13 million Series A in September 2026, installs its credit models inside client IT, including air-gapped networks, LaunchBase Africa reported. Cloud grows fastest at 29.8% a year, as the onshore AI hosting covered under trends lets buyers label and store Egyptian personal data in licensed local facilities instead of foreign regions.
Telecom buyers lead while healthcare data grows fastest
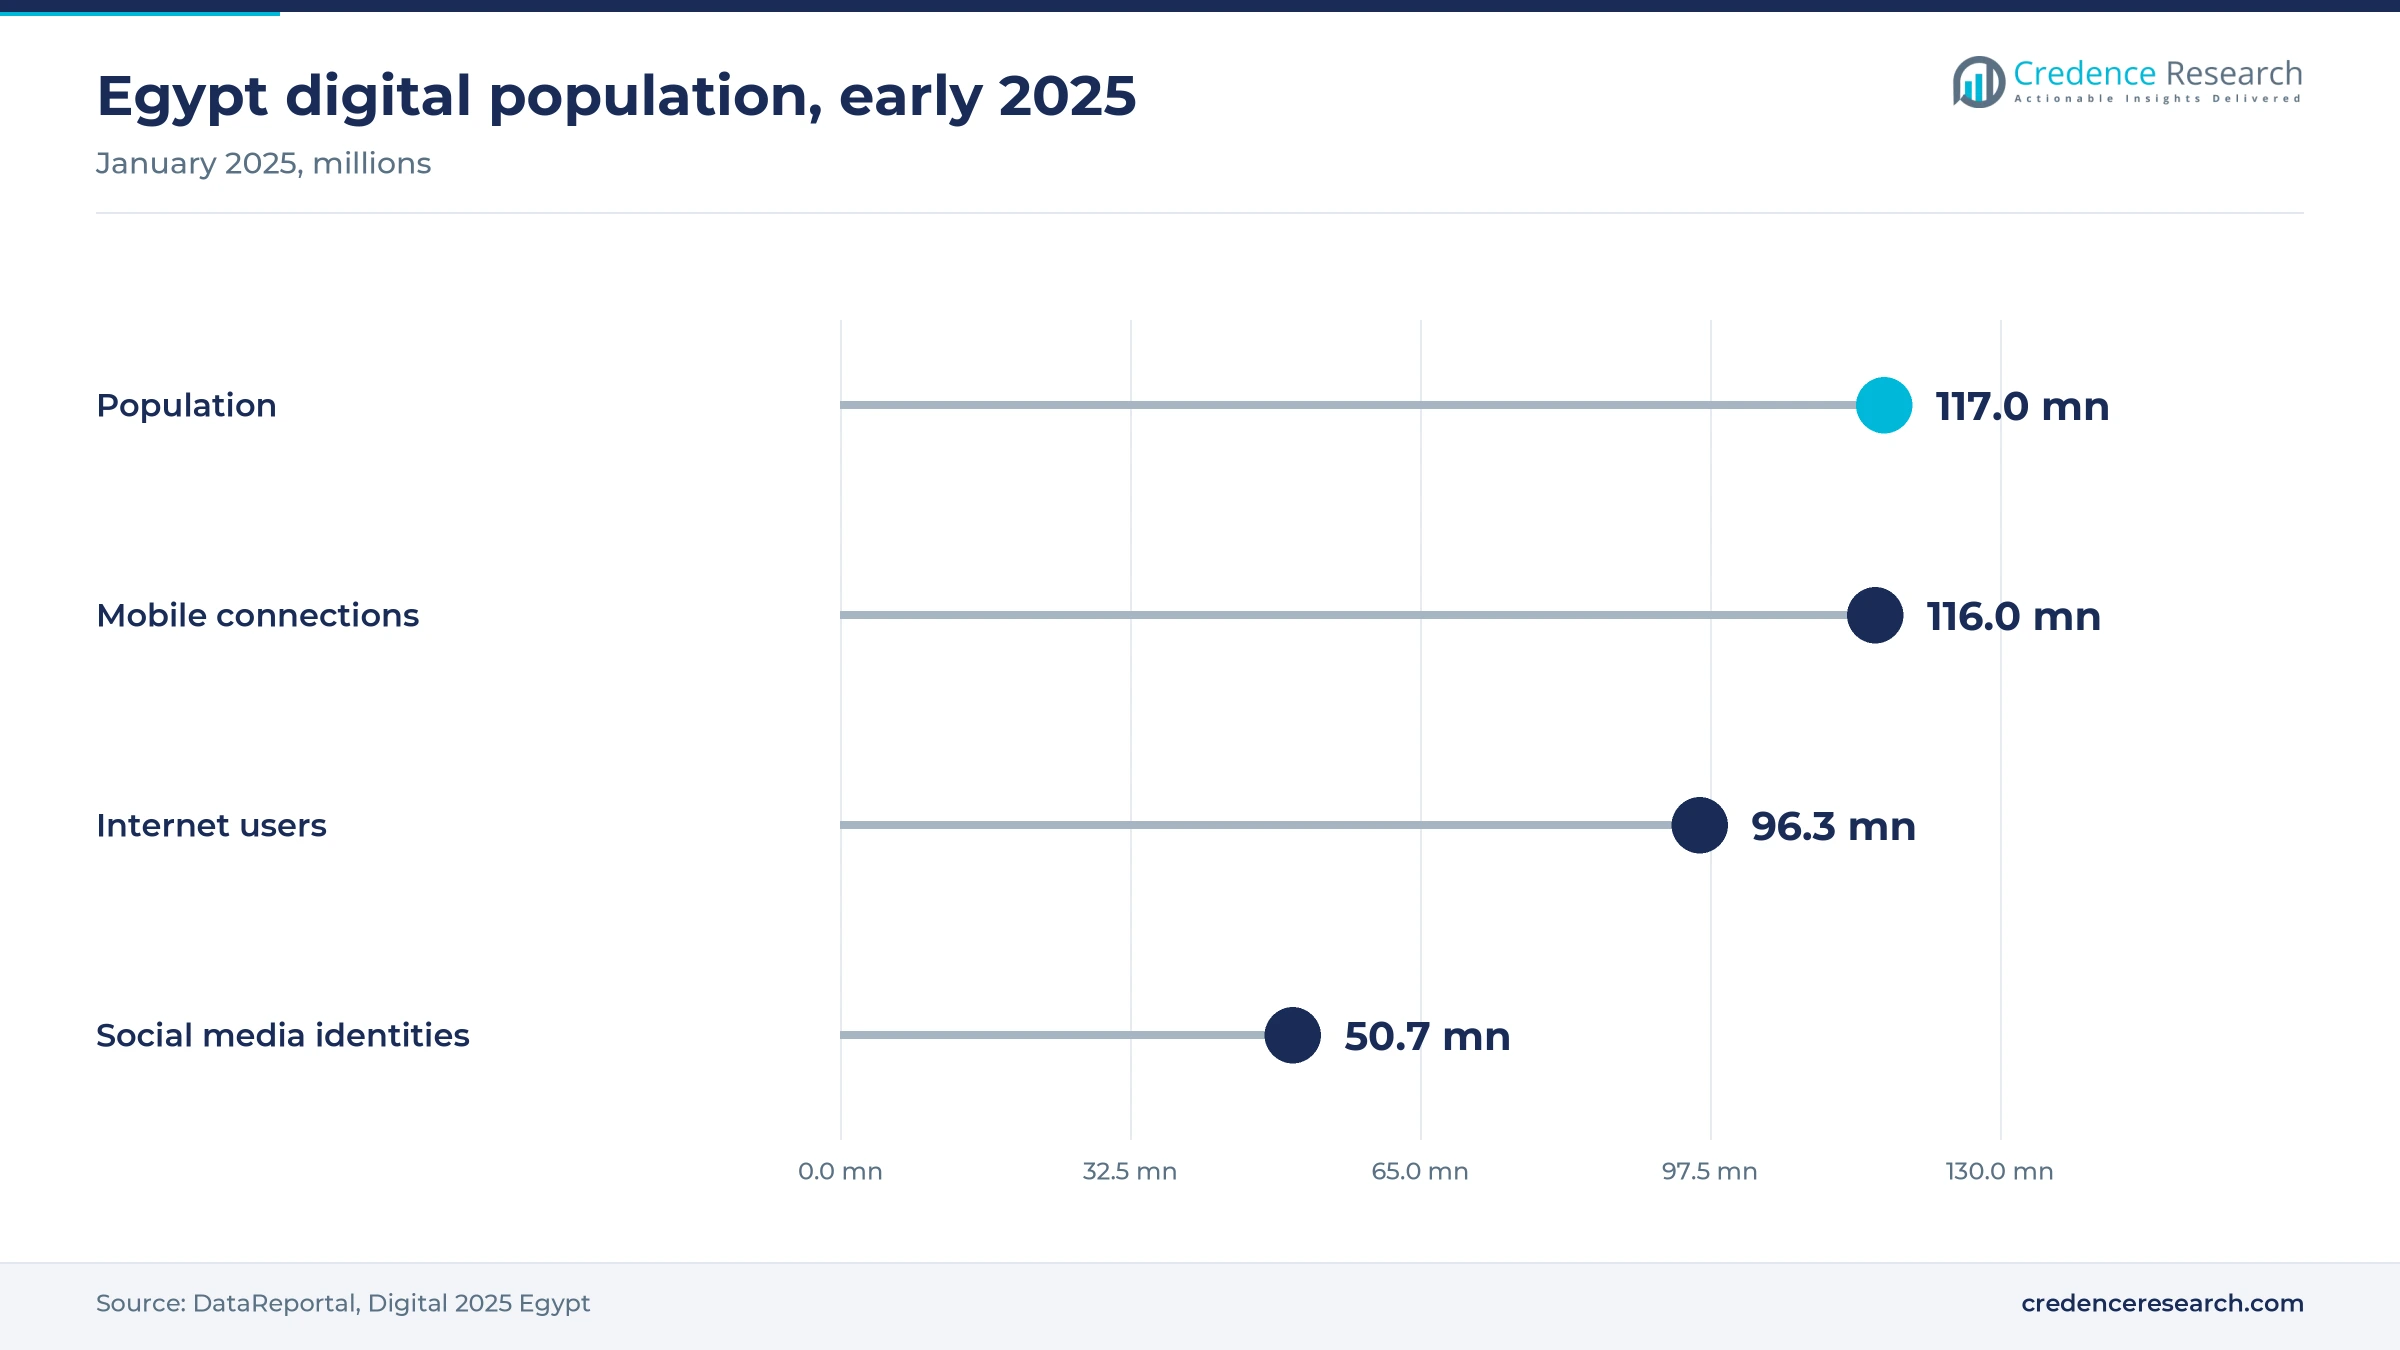
Based on end user, the market is categorized into IT and telecommunications, retail and consumer goods, healthcare, automotive, BFSI and others (government and manufacturing). IT and Telecommunications led with 27.0% of 2025 value because operators serve 116 million mobile connections, DataReportal counted in January 2025, and train models for call centers, churn and network faults. Healthcare grows fastest at 30.1% a year, as the Egypt Genome Project sequenced 1,024 citizens from 21 governorates and found more than 17 million previously undocumented variants, Ahram Online reported in April 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Text | 35.0% | Audio | 30.0% |
| By Deployment Mode | On-Premises | 55.0% | Cloud | 29.8% |
| By End User | IT and Telecommunications | 27.0% | Healthcare | 30.1% |
Labor rates and project scope set data prices
Training data in Egypt is priced per project, per labeled item or per hour of recorded and transcribed audio, and labor is the largest cost in custom work. Native-speaker crowds are paid per completed session only when quality review passes, which shifts rework cost onto contributors and keeps vendor margins steady. Licensing and transfer permits under the data protection law add a fixed cost that small projects absorb poorly. Suppliers with existing consented corpora earn the highest margins, because they resell the same data without new collection.
| Offer or input | Typical price or fee | Basis |
|---|---|---|
| Private sector minimum wage, floor for annotator pay | EGP 7,000 per month from March 2025 | National Wages Council, via Arab Finance, February 2025 |
| Scripted Egyptian Arabic speech collection | Paid per 500-prompt session; unpaid below 90% QA score | CrowdGen listing for Appen, March 2026 |
| Transcribed Egyptian dialect speech | USD 40 to USD 120 per hour of audio | Credence Research estimate from wage, QA and licensing inputs |
| Image bounding-box annotation in Egypt | USD 0.03 to USD 0.10 per box | Credence Research estimate from delivery center labor rates |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Arabic models, public data and health records add demand
Sovereign Arabic models need curated Egyptian corpora
State-backed language models create the largest single pull for curated Egyptian text and speech, because a model that serves citizens must handle colloquial Arabic, local law and public services that global models cover poorly. MCIT launched Karnak, which it calls the highest-ranking Arabic model in the 30 to 40 billion parameter class, on Feb. 11, 2026, ITIDA said, at an event with more than 350 AI enterprises and startups. The same launch added AcQua, which audits calls to the Digital Egypt call center, and Torgoman, a translation engine. BelMasry, released in August 2026, was trained on Egyptian and Arabic linguistic datasets. Suppliers of dialect speech, legal text and evaluation data gain most from these programs.
Strategy targets and open data widen the buyer base
National policy widens the number of organizations that buy training data, because it sets targets for AI firms and releases public records in usable form. The second National AI Strategy, covering 2025–2030, targets more than 250 AI-driven startups, 30,000 AI specialists and an ICT share of 7.7% of GDP by 2030, MEA Tech Watch reported. The Open Data Policy, approved by the National Council for Artificial Intelligence, entered into force in August 2025 and makes non-sensitive government data open by default in machine-readable formats. Open records lower collection cost for public-sector corpora, although health and identity data stay outside the policy and still need licensed collection. More AI startups and open public records turn into more annotation and evaluation contracts.
A connected population creates labeled data needs
Egypt's connected population produces the calls, chats, payments and images that operators and lenders now want to model, and each model needs local examples labeled by native speakers. Internet users reached 96.3 million, or 81.9% of the population, in January 2025, according to DataReportal. MEA Tech Watch reported 7.9 million new mobile internet users during 2025. Velents raised USD 1.5 million in October 2025 for Agent.sa, an Arabic voice and chat agent that speaks regional dialects for companies and government entities in Egypt and Saudi Arabia. Telecom operators, wallets and lenders are the first buyers of these labeled Egyptian sets in volume.
Health records and imaging programs open medical data
Healthcare is adding training data demand, because diagnostic models must be trained and validated on Egyptian patients before hospitals and regulators trust them. The Egypt Genome Project showed that European risk models flagged more than 83% of participants as high stroke risk, against an expected 10%, Ahram Online reported. Rology, an AI-assisted teleradiology platform working with more than 300 hospitals in more than 13 countries, closed a growth round in December 2025, AllAfrica reported. MCIT also offers engines for diabetic retinopathy and breast cancer detection with UNDP. Annotation by radiologists, consented imaging sets and healthcare diagnostics validation data gain from this shift.
Data moves onshore as delivery centers add labeling
Buyers shift data and compute onshore
Model builders are shifting toward in-country compute and storage to keep Egyptian personal data inside the country and to avoid cross-border licensing. Vodafone Business, Elsewedy Electric and Cassava Technologies plan an AI data center with 20 MW and about USD 200 million in its first phase, rising to 200 MW and USD 1 billion, W.Media reported in September 2026. Intro Group has signed supplier contracts for the 80 MW Kemet facility in the Suez Canal Economic Zone, with nearly USD 270 million for phase one. The 200 MW target is ten times the first phase, so onshore demand for prepared data should rise in steps. Onshore capacity favors suppliers that can deliver labeled data into local environments.
Outsourcing groups add AI data labeling in Cairo
Customer experience and outsourcing groups are shifting Egyptian seats toward AI data work, because Arabic-speaking agents can label, transcribe and rate model output with little retraining. Conectys opened Cairo operations in November 2025 with AI data labeling among its services, under an MoU with ITIDA. TP acquired Agents Only, a platform for expert annotators, in June 2025 to expand TP.ai Data Services under a EUR 100 million AI program. Konecta opened a generative AI center in New Cairo in July 2026 as part of a USD 100 million plan, with 800 specialists today and about 3,000 targeted by 2028. Because these seats already handle Arabic customer contacts, the shift adds labeling supply without new recruitment. Local buyers gain more onshore suppliers and shorter lead times.
Dialect voice services open room for speech data
Egyptian dialect speech data is the clearest opening for suppliers, because voice agents and call analytics fail when trained only on Modern Standard Arabic. Intella develops Arabic speech intelligence for financial services and telecom, NVIDIA noted in September 2026 after a Cairo reception for its startup program. BelMasry, which translates between Arabic and 50 foreign languages, combines speech-to-text, translation and text-to-speech and separates speakers in multi-party recordings, a feature that needs diarized training audio. Welocalize advertised remote work of 20 to 40 hours a week in February 2025 for annotators who match Arabizi to Egyptian Arabic words. Suppliers that hold consented, transcribed dialect audio can sell to banks, operators and government contact centers.
Engineering centers create demand for sensor data
Engineering centers in Cairo give image, video and sensor data suppliers a second opening, because driver assistance and lighting software must be trained and tested on labeled scenes. Valeo opened an AI Development Center at Smart Village in April 2026 with 35 engineers and plans more than 100, ITIDA said, and its Egyptian engineers number more than 3,000. Valeo Egypt delivers about four million R&D hours a year and nearly half of the group's software output. Capgemini announced an AI center of excellence in Cairo in April 2025. Suppliers of data labeling for lidar, camera and video can win these programs.
Licensing rules, currency and thin corpora raise costs
Licensing under the data protection law adds cost
Collecting Egyptian voices, faces and records now needs a license, which raises the cost and time of custom data projects. Ministerial Decree No. 816 of 2025, issued Nov. 1, 2025, requires controllers and processors to hold a license from the Personal Data Protection Center before processing and a separate permit for transfers abroad, Al Tamimi noted. Fees scale with records processed, so a 1 million-record collection costs more to license than a pilot. Foreign crowdsourcing platforms and small vendors without a local representative are most exposed once enforcement begins.
A weaker pound raises the price of imported data
Licences for global datasets, labeling platforms and cloud compute are usually priced in U.S. dollars, so local buyers pay more whenever the pound weakens. The pound fell from about EGP 47.9 per dollar in late February 2026 to about EGP 54.5 by April 5, 2026, Ahram Online reported, so a dollar-priced licence cost about 14% more in pounds. Startups and hospitals that budget in pounds are most exposed, and many delay custom collection or turn to smaller open datasets with weaker coverage of Egyptian dialect.
Thin public dialect corpora slow early projects
Public Egyptian Arabic datasets remain small, so startups must fund custom collection before they can train a usable model. A widely used Egyptian speech set derived from the MGB-3 challenge on Hugging Face holds about 1,160 clips of 3 to 30 seconds, under 10 hours of audio. The earlier Egyptian reference genome drew on just over 100 people, Ahram Online noted. Early-stage developers without funding for collection are most exposed, while state programs can build corpora themselves.
Competition for Arabic-speaking staff lifts labor costs
Annotation depends on educated Arabic speakers, and the same graduates are recruited by large delivery centers, which pushes up wages for labeling teams. Concentrix targets a 35,000-person Egyptian workforce by 2028, and TP plans 18,000 Egyptian jobs over three years, ITIDA said in August 2026. The private sector minimum wage also rose to EGP 7,000 a month from March 2025. Small labeling vendors that compete on price are most exposed to attrition.
Greater Cairo buys most as Alexandria adds delivery
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Greater Cairo | 9.0 | 66.0% | 28.5% |
| Alexandria and Nile Delta | 2.6 | 19.0% | 29.8% |
| Upper Egypt | 1.2 | 9.0% | 29.5% |
| Suez Canal and Sinai | 0.8 | 6.0% | 29.4% |
Greater Cairo leads through ministries and engineering hubs
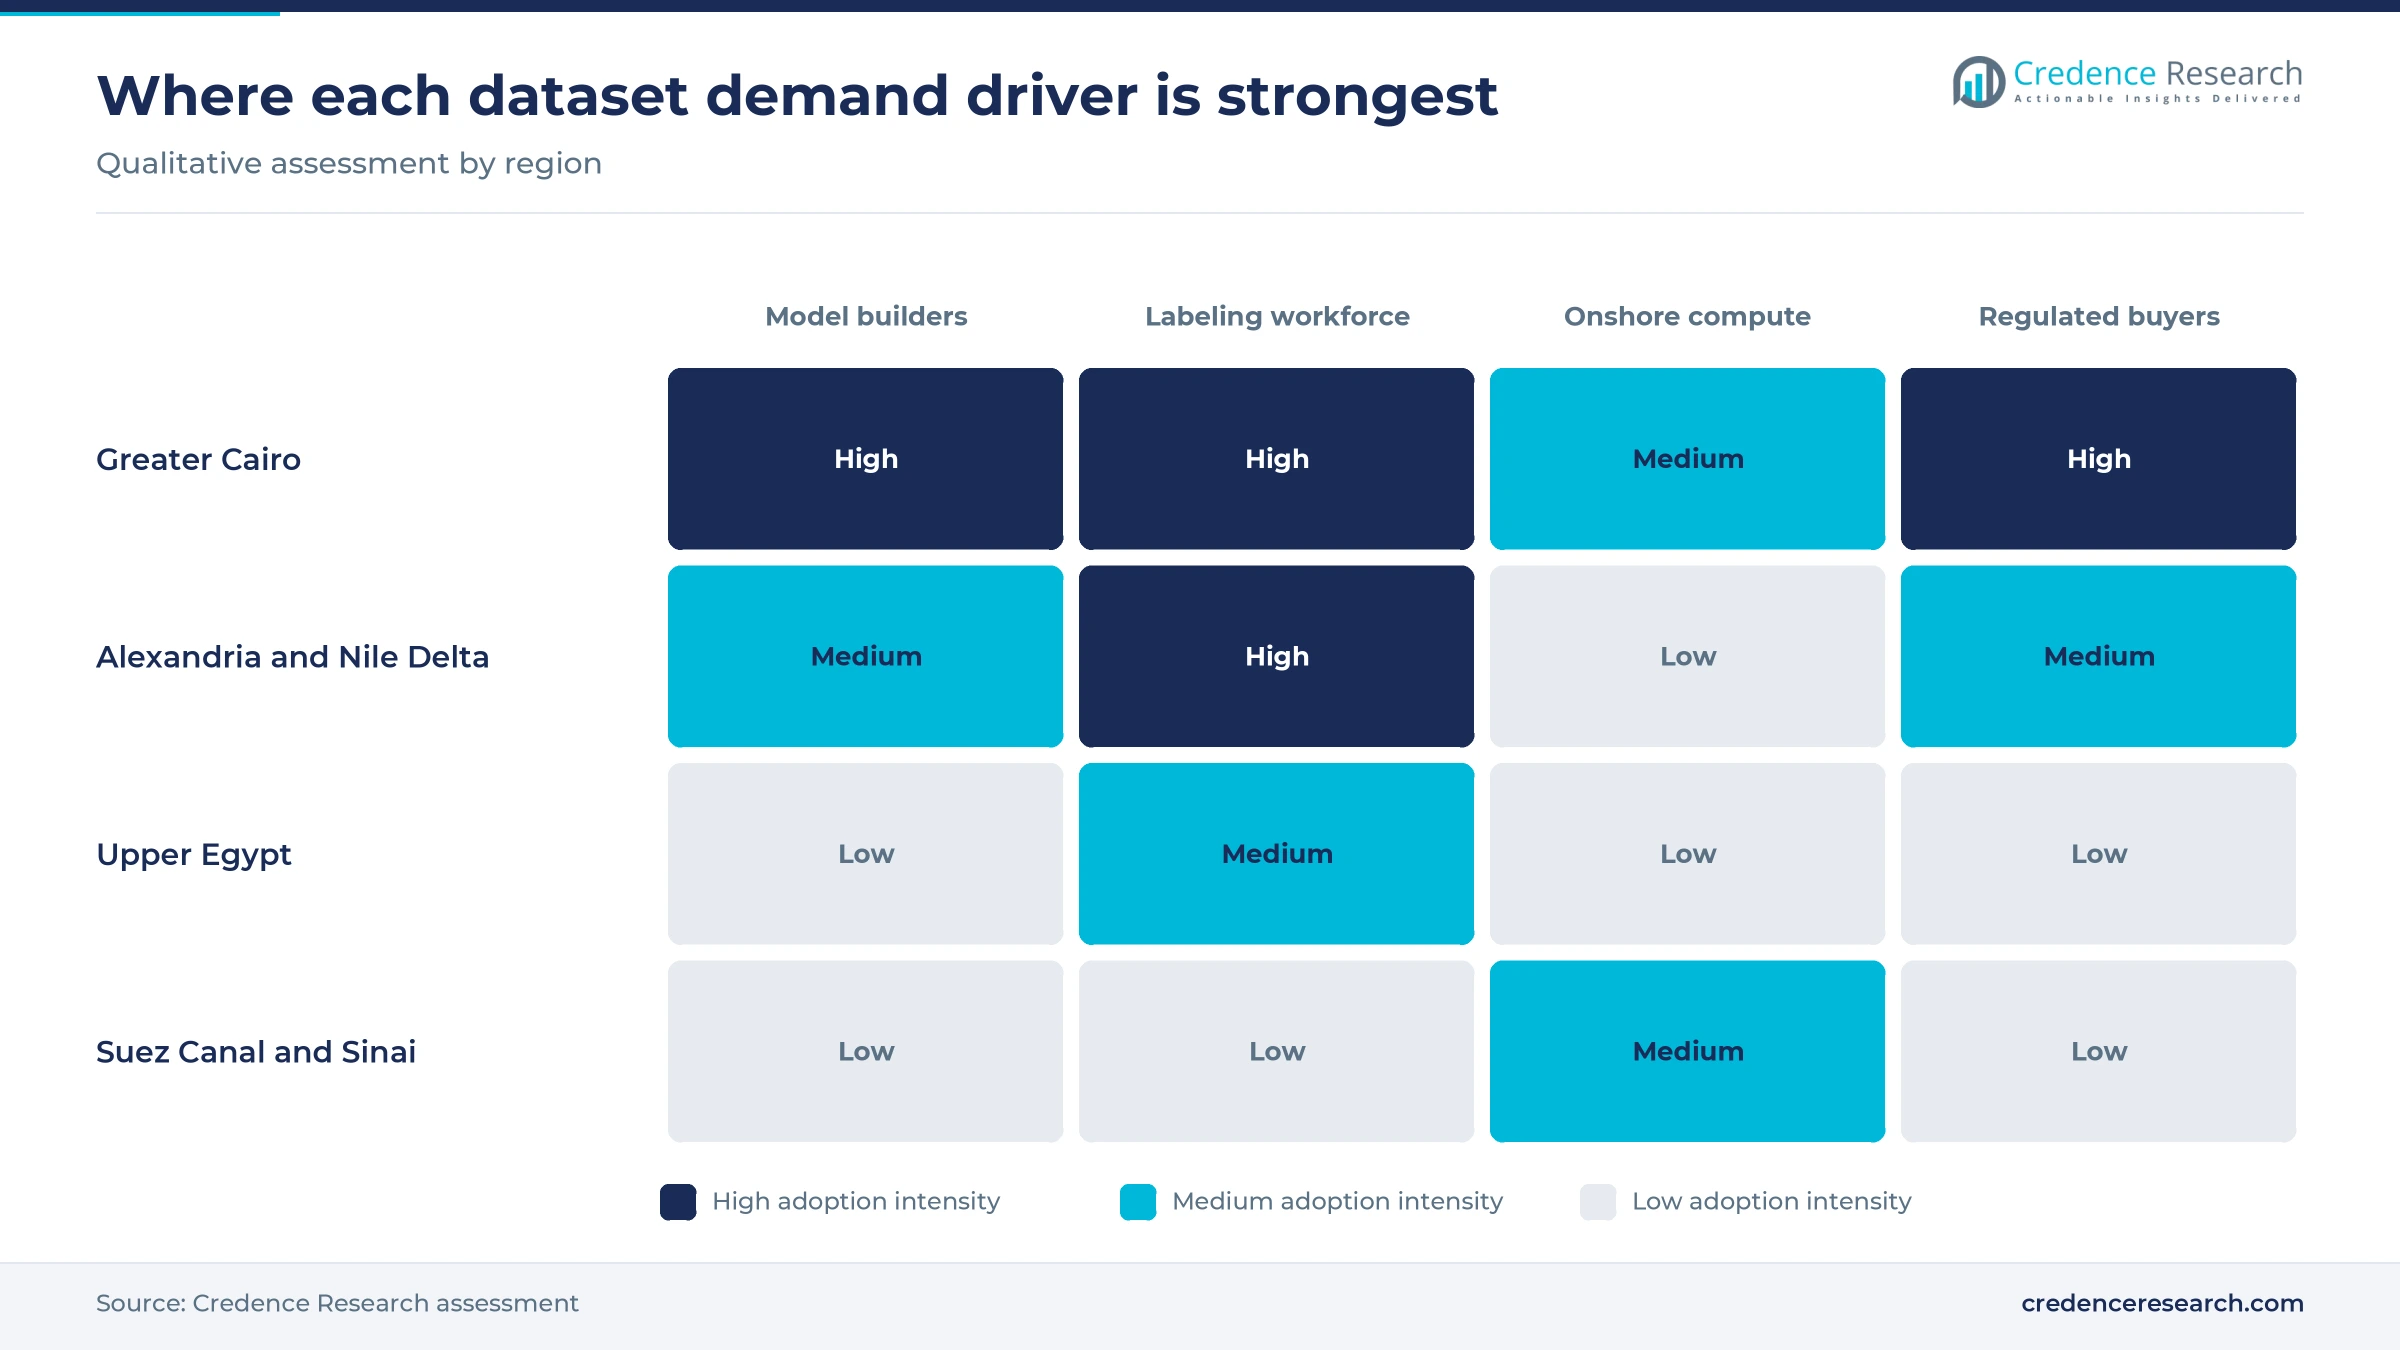
Greater Cairo held 66.0% of 2025 value and grows at 28.5% a year through 2035. The Applied Innovation Center, which builds Karnak and BelMasry, sits within MCIT in the capital region, and Smart Village hosts Valeo's new AI center. Konecta's generative AI center in New Cairo and Capgemini's Cairo center add buyers of evaluation and labeling work. Bank and operator headquarters in Cairo and Giza sign most dataset contracts, which keeps the region dominant even as delivery spreads.
Alexandria and the Nile Delta add labeling capacity
Alexandria and Nile Delta held 19.0% of 2025 value and is the fastest-growing region at 29.8% a year. TP runs four Alexandria delivery centers with more than 4,000 employees, VOIS employs 1,100 specialists there, and Sutherland has more than 6,000, ITIDA reported after a prime ministerial visit in August 2026. Concentrix, with 24,500 staff across 13 Egyptian centers, is embedding generative AI in its local operations, adding labeling supply for regional demand. This workforce gives local model builders labeling and transcription capacity outside the capital.
Upper Egypt grows from new technology parks
Upper Egypt held 9.0% of 2025 value and grows at 29.5% a year. An ITIDA job fair at the Beni Suef technology park in September 2025 drew more than 2,000 registrants for about 650 outsourcing and contact center jobs, which points to a labor pool for transcription work outside Cairo. Silicon Waha manages technology parks across these tier-2 cities, which give dataset suppliers lower-cost seats than Cairo. Credence Research expects transcription and data collection work to follow this cheaper labor pool.
Suez Canal and Sinai gain from data center projects
Suez Canal and Sinai held 6.0% of 2025 value and grows at 29.4% a year. The Kemet data center planned in the economic zone would add hosting close to subsea cable routes, and its first phase has completed engineering designs. Public sources reviewed do not show dataset purchases by industrial users in the zone, which is an evidence gap, so demand is assumed to follow the data center projects. Credence Research assesses local supplier presence as thin, so most work is contracted from Cairo, while data center storage capacity builds ahead of demand.
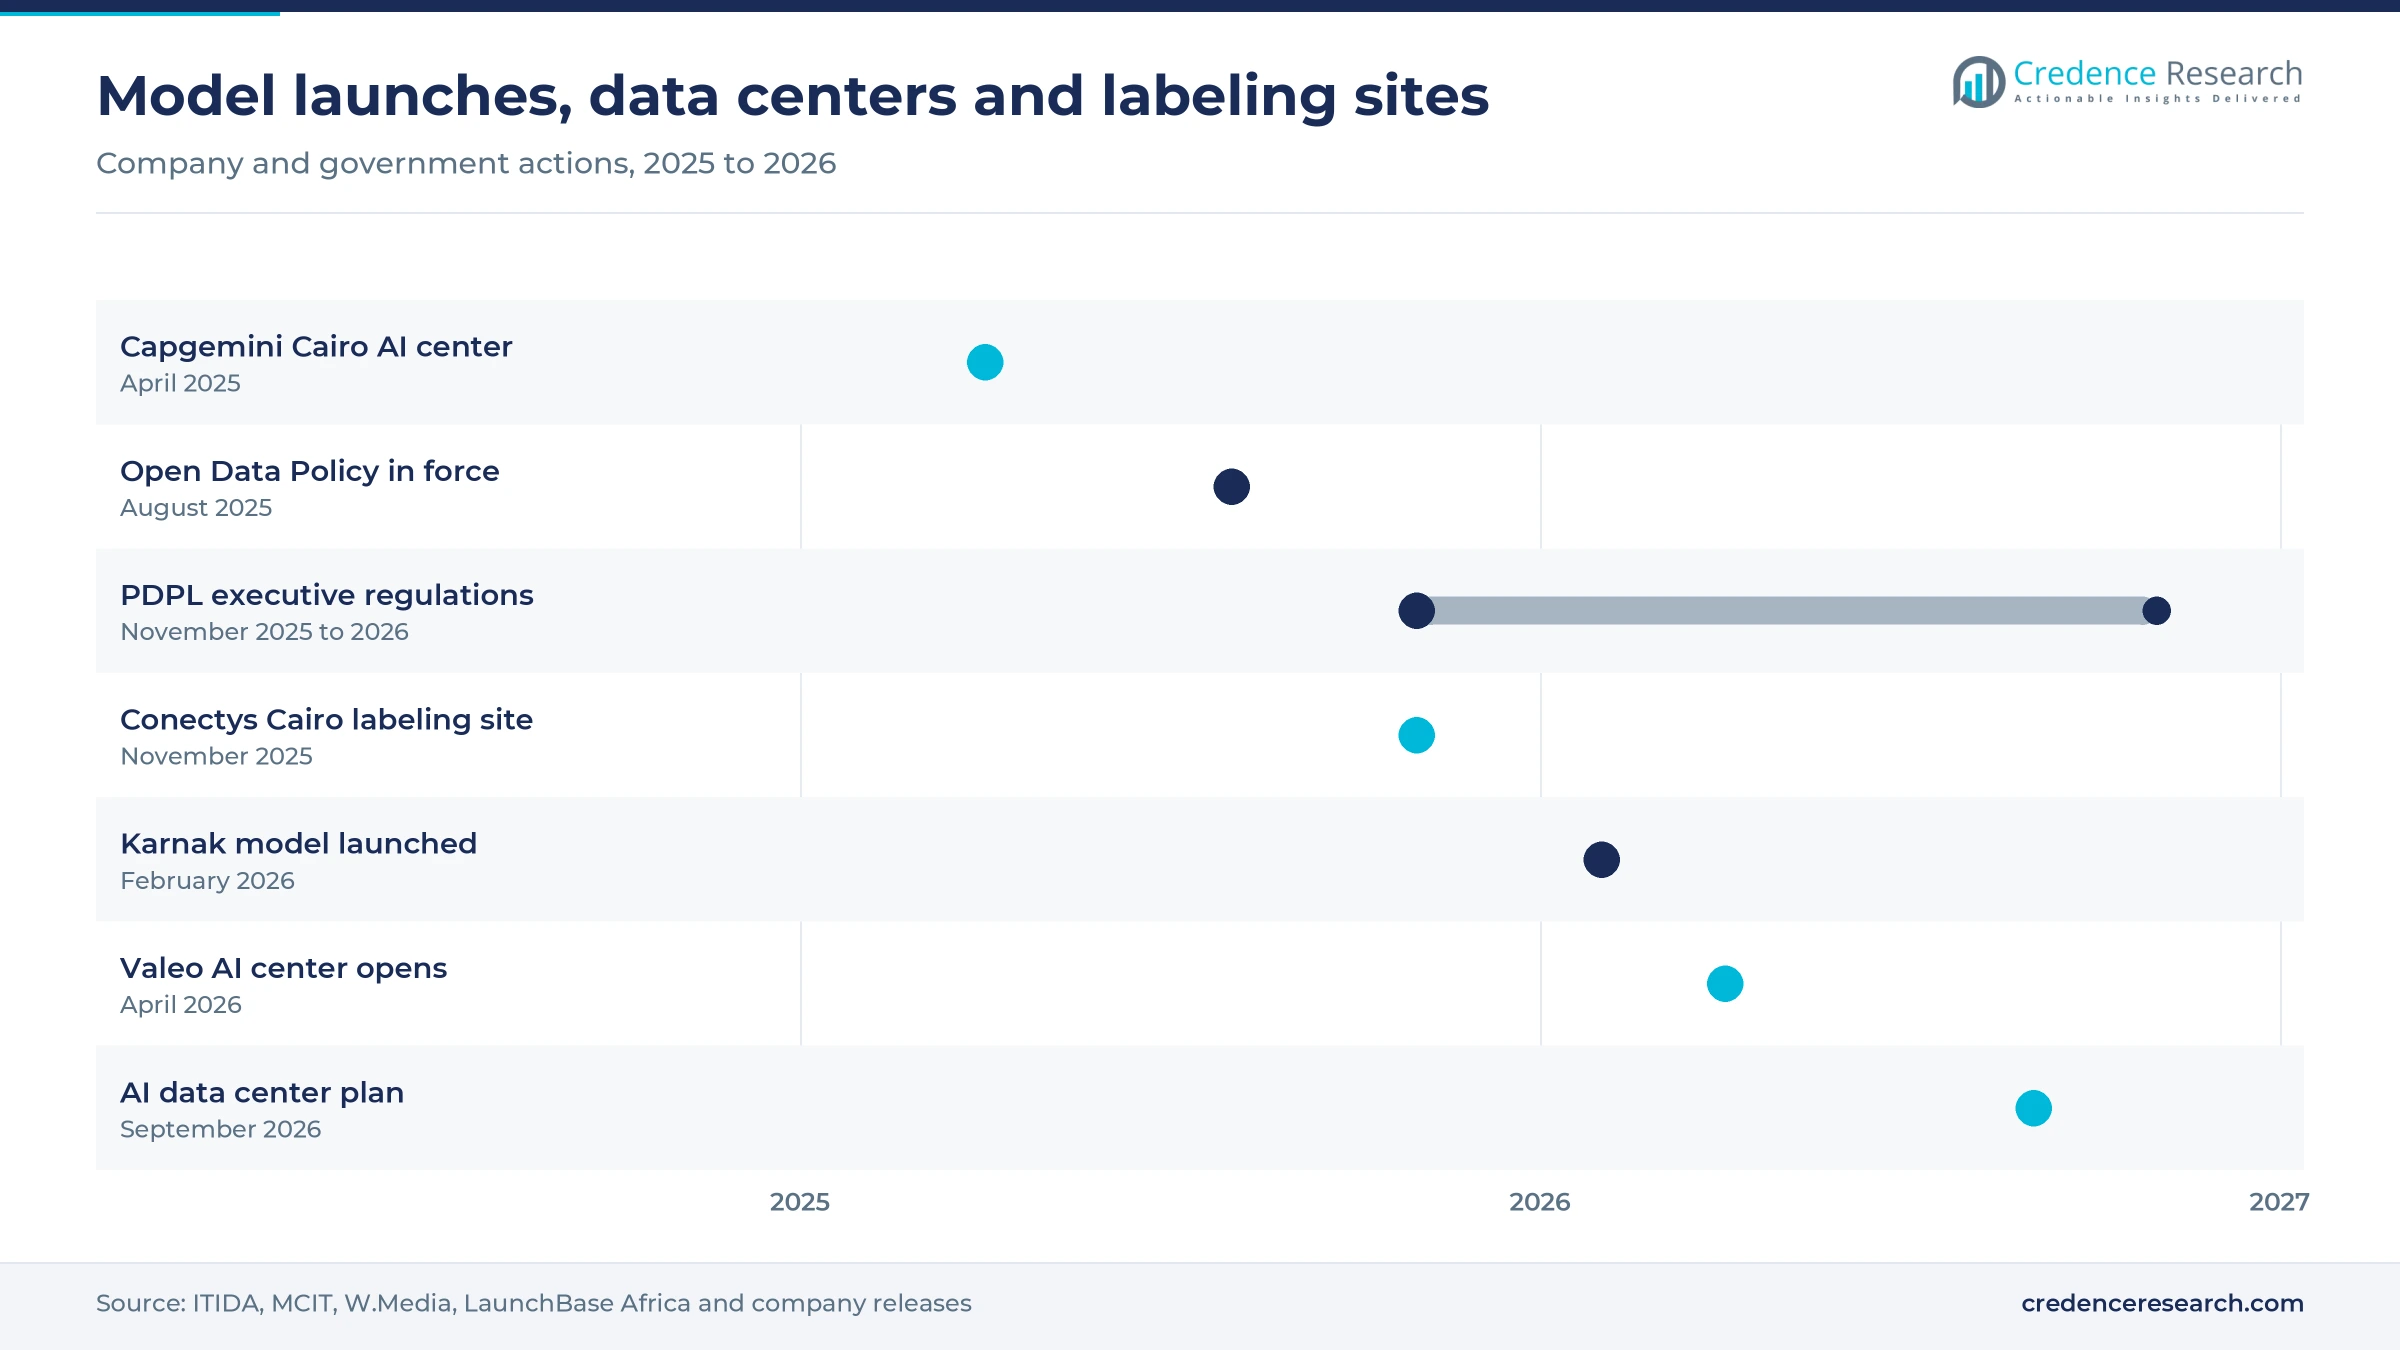
Model launches, data centers and labeling sites
| Development | Status and market relevance |
|---|---|
| In April 2025, Capgemini announced an AI center of excellence in Cairo for generative and agentic AI projects, with work starting in May 2025. | Announcement; implementation started, adding a buyer of evaluation data. |
| In November 2025, Egypt issued the executive regulations of the Personal Data Protection Law under Ministerial Decree No. 816 of 2025. | Regulation in force; a one-year compliance period runs to about November 2026. |
| In November 2025, Conectys opened Cairo operations offering AI data labeling, content moderation and customer care under an MoU with ITIDA. | Operational launch; adds an onshore labeling supplier. |
| In February 2026, MCIT launched Karnak, a national Arabic large language model, at Ai Everything MEA Egypt in Cairo. | Launch; a free Karnak version is offered to developers. |
| In September 2026, Vodafone Business, Elsewedy Electric and Cassava Technologies announced an AI data center starting at 20 MW. | Plan; the facility is not yet built and targets 200 MW at full buildout. |
Dialect speech, preference data and synthetic records
- Diarized dialect speech sets pair Egyptian Arabic audio with speaker turns and transcripts, which call analytics and multi-speaker transcription engines need.
- Preference and evaluation data rank model answers written by native speakers, which tunes Arabic language models toward local usage and legal accuracy.
- Synthetic records stand in for scarce or sensitive patient and payment data, and synthetic data generation reduces the number of real records that need a license.
- On-premises training pipelines let banks and agencies label and train inside their own networks, which keeps raw personal data out of foreign clouds.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Arabic crowds and onshore delivery decide positions
Competition in the Egypt AI training datasets market splits between data vendors and delivery operators. Appen, through its CrowdGen community, and Scale AI and Lionbridge sell collection, transcription and evaluation work with global crowds that include Egyptian Arabic speakers. TP, Conectys and Welocalize sell managed labeling from Egyptian seats or remote Egyptian annotators, and win on language coverage and quality control. Cloud labeling tools and compute sit outside this estimate, although their pricing caps what in-house teams pay for annotation. State programs at the Applied Innovation Center build their own corpora, which sets a quality benchmark for vendors. Appen and Welocalize recruit remote contributors inside Egypt, which lets them scale dialect projects without opening local offices. Buyers judge suppliers on dialect coverage, consent records and data residency.
How is the supply side organized?
The supply side serving Egyptian dataset buyers runs in three distinct tiers. Global data vendors such as Appen, Scale AI and Lionbridge reach Egyptian contributors through online crowds and sell finished datasets to local and foreign buyers. Outsourcing groups with Egyptian seats, including TP, Conectys and Welocalize, sell managed labeling and transcription. Buyers that staff cloud labeling tools with their own teams compete with these vendors for the same projects. Entry barriers sit in consented dialect corpora, quality control and, since the compliance period under Decree No. 816 ended in November 2026, data protection licenses, and margins are highest in licensed corpora and expert evaluation.
Dataset and annotation suppliers buyers shortlist in Egypt
| Company | Type | Role in the market |
|---|---|---|
| Appen Ltd. (CrowdGen) | Data vendor | Collects and transcribes Egyptian Arabic speech through its CrowdGen contributor community |
| TP (Teleperformance SE, TP.ai Data Services) | Delivery and data services | Sells AI data labeling and annotation, with about 26,800 staff in Egypt |
| Welocalize | Language data specialist | Hires Egyptian Arabic annotators for transliteration, rating and AI content evaluation |
| Conectys | Delivery and data services | Offers AI data labeling and content moderation from its Cairo site |
| Scale AI | Data vendor | Sells annotation, evaluation and preference data for language and vision models |
| Lionbridge | Language data specialist | Sells multilingual training data, transcription and model evaluation services |
Dialect speech will add more value than text
Credence Research's view is that Egyptian dialect speech, not text, will decide how much value the market adds by 2035. Text corpora lead today because language model programs curate documents first, yet text can be reused and partly synthesized once collected. Speech must be recorded, consented, diarized and transcribed for each new use, and the data protection license makes each project a regulated purchase. Suppliers that combine native-speaker crowds, onshore storage and licensed consent records should gain the most share.
Estimates rest on public, trade and company data
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The 2025 value brings the earlier Credence Research estimate for 2023 forward at its own growth rate and was checked against national output, model program and buyer counts. Market values come from the Credence Research model, and the regional, type, deployment and end user splits are Credence Research estimates informed by public data. Sources include the OECD Artificial Intelligence Review of Egypt, DataReportal indicators, ITIDA and MCIT releases, legal analysis of the data protection regulations, company announcements and Egyptian business publishers. No official statistic tracks dataset spending in Egypt, so the type split rests on program and company evidence. No published Egypt-specific estimate of training data spending could be opened, so the 2025 value carries a wider range than the segment splits. No interviews or surveys were used to build these estimates.
Onshore compute and licensing shape value to 2035
Credence Research expects Egypt dataset value to reach USD 173.0 million by 2035 as sovereign models, banks, operators and hospitals move from pilots to production. Alexandria and Nile Delta should keep the fastest pace, while Greater Cairo remains the largest source of value. Healthcare buyers grow at 30.1% a year during 2026–2035, ahead of telecom, as genomic and imaging programs need labeled Egyptian records. Licensing under Decree No. 816 should become routine by 2027, which would lower the fixed cost of each project and widen demand. The main risks are licensing delays and a weaker pound, while onshore AI compute offers the clearest upside.
Licensing and onshore compute set the range of outcomes
The range to 2035 depends mainly on how the data protection center applies licenses to collection and transfer, and on whether planned AI data centers reach operation on time. Sovereign model programs support every case, but their budgets decide how much curated data the state buys each year. Private demand from banks, operators and hospitals adds upside if dialect models prove their value in production.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 23.9% | USD 121.2 million | Licensing slows custom collection and AI data center projects slip beyond 2029 |
| Base | 28.90% | USD 173.0 million | Karnak and BelMasry keep expanding and the first 20 MW AI phase opens |
| Upside | 32.4% | USD 220.2 million | Banks, operators and hospitals put dialect and imaging models into production at scale |
Frequently Asked Questions
How big is the Egypt AI training datasets market?
Which data type leads in Egypt?
What categories make up the market?
How does the data protection law affect dataset projects?
Which region leads dataset demand?
How is Egypt training its AI and IT workforce?
What are the main challenges for dataset suppliers?
Who are the main companies in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Text
- 1.2.2 Image
- 1.2.3 Audio
- 1.2.4 Video
- 1.2.5 Others (Sensor and Geo)
- 1.3 By Deployment Mode
- 1.3.1 On-Premises
- 1.3.2 Cloud
- 1.4 By End User
- 1.4.1 IT and Telecommunications
- 1.4.2 BFSI
- 1.4.3 Others (Government and Manufacturing)
- 1.4.4 Healthcare
- 1.4.5 Retail and Consumer Goods
- 1.4.6 Automotive
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 13.7 million → 2035: USD 173.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Egypt AI Training Datasets Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Egypt AI Training Datasets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Egypt AI Training Datasets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Egypt AI Training Datasets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Egypt AI Training Datasets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Egypt AI Training Datasets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Egypt AI Training Datasets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Egypt AI Training Datasets Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 13.7 million → 2035: USD 173.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Egypt AI Training Datasets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Text
- 12.3.7.2 Image
- 12.3.7.3 Audio
- 12.3.7.4 Video
- 12.3.7.5 Others (Sensor and Geo)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premises
- 12.4.7.2 Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 IT and Telecommunications
- 12.5.7.2 BFSI
- 12.5.7.3 Others (Government and Manufacturing)
- 12.5.7.4 Healthcare
- 12.5.7.5 Retail and Consumer Goods
- 12.5.7.6 Automotive
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Egypt AI Training Datasets End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Egypt AI Training Datasets Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Egypt AI Training Datasets Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Egypt AI Training Datasets Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Appen Ltd. (CrowdGen)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 TP (Teleperformance SE, TP.ai Data Services)
- 18.4 Welocalize
- 18.5 Conectys
- 18.6 Scale AI
- 18.7 Lionbridge
- 18.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

