
Electric Vehicle Tires Market Overview:
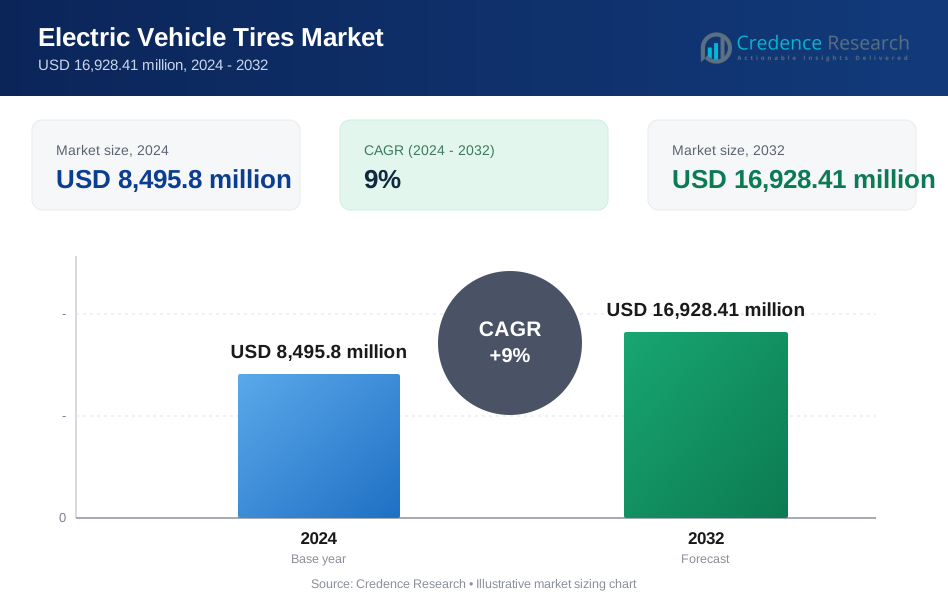
Electric Vehicle Tire Market size was valued USD 8495.8 million in 2024 and is anticipated to reach USD 16928.41 million by 2032, at a CAGR of 9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Vehicle Tires Market Size 2024 | USD 8495.8 million |
| Electric Vehicle Tires Market, CAGR | 9% |
| Electric Vehicle Tires Market Size 2032 | USD 16928.41 million |
Electric Vehicle Tires Market Insights
- Market growth is primarily driven by rising demand for EV-specific tires with low rolling resistance, higher load-bearing capacity, and enhanced durability, as battery weight and instant torque place greater performance demands on tire structures and compounds.
- Key market trends include increasing use of sustainable materials, silica-rich tread compounds, and noise-reduction technologies, while all-season and radial tires dominate the segment mix due to broad applicability and efficiency benefits.
- The competitive landscape is characterized by strong R&D intensity, OEM co-development programs, and investments in smart tire technologies, with manufacturers differentiating through performance optimization and sustainability credentials.
- Regionally, Asia-Pacific leads with an exact 42% market share, supported by large-scale EV manufacturing in China, Japan, and South Korea, while Europe and North America follow, driven by regulatory mandates and premium EV penetration.
Electric Vehicle Tires Market Segmentation Analysis:
By Tire Type
By tire type, all-season tires represent the dominant sub segment in the electric vehicle tire market, accounting for an estimated 44% market share. Their leadership is driven by year-round usability, reduced replacement frequency, and balanced performance across dry, wet, and mild winter conditions key priorities for EV owners focused on low total cost of ownership. All season compounds are increasingly optimized for low rolling resistance to extend driving range while maintaining load-bearing capacity for heavier EVs. Summer and winter tires follow in regions with extreme climates, while all-terrain and niche tires serve limited but growing crossover and utility EV applications.
- For instance, Hankook Tire and Technology Co., Ltd. has engineered its EV-focused all-season tires using advanced silica-rich tread compounds and optimized belt structures capable of supporting axle loads exceeding 800 kilograms per tire, while also incorporating tread block designs tested for durability beyond 50,000 kilometers under EV-specific torque conditions.
By Tire Construction
By tire construction, radial tires dominate the electric vehicle tire market with approximately 86% market share, supported by superior durability, heat dissipation, and energy efficiency compared with bias designs. Radial construction reduces rolling resistance and improves tread wear uniformity, directly contributing to extended battery range and lower operating costs. The flexible sidewall and stable tread footprint also enhance ride comfort and handling, aligning with EV performance expectations. Bias tires remain marginal, primarily used in specialized off-road or industrial EVs, where robustness outweighs efficiency considerations.
- For instance, Goodyear's SoundComfort Technology uses a polyurethane foam layer to reduce cabin noise by approximately 3 to 4 decibels, which the company states is up to a 50% reduction in perceived noise. A 50-decibel reduction is not physically possible for a tire modification.
By Technology
By technology, eco-friendly tires lead the segment with nearly 39% market share, driven by stringent emission regulations, sustainability targets, and OEM commitments to lower lifecycle carbon footprints. These tires use silica-rich compounds, recycled materials, and bio-based polymers to reduce rolling resistance and energy loss, directly improving EV efficiency. Noise reduction technologies, including foam inserts and optimized tread patterns, closely follow due to the heightened cabin noise sensitivity of EVs. Run-flat and self-sealing technologies remain secondary, favored mainly for premium and long-range electric vehicle models.
Key Growth Drivers
Rapid Growth in Electric Vehicle Production
The accelerating global production of electric vehicles remains a primary growth driver for the electric vehicle tire market. Rising EV adoption across passenger cars, commercial fleets, and two-wheelers directly increases demand for tires specifically engineered to handle higher vehicle weights, instant torque, and unique load distributions. OEMs increasingly specify EV-optimized tires during vehicle design to improve range, durability, and driving comfort. Expanding EV manufacturing capacity in Asia-Pacific, Europe, and North America further strengthens original equipment demand, while the growing installed EV base also drives steady replacement tire sales over the vehicle lifecycle.
- For instance, Yokohama Tire Corporation has developed its ADVAN and BluEarth EV tire lines to withstand electric motor torque levels above 700 newton-meters and support per-tire load capacities exceeding 750 kilograms, validated through durability testing cycles surpassing 60,000 kilometers under EV-specific operating conditions.
Focus on Energy Efficiency and Driving Range
Energy efficiency requirements strongly influence tire selection in electric vehicles, making low rolling resistance tires a critical growth factor. EV tires are designed with advanced tread compounds, optimized carcass structures, and lightweight materials to minimize energy losses and extend driving range per charge. Automakers and consumers increasingly prioritize range optimization, pushing tire manufacturers to innovate around silica-rich compounds and aerodynamic tread patterns. Regulatory pressure to improve vehicle efficiency and reduce lifecycle emissions further reinforces the adoption of specialized EV tires across both mass-market and premium vehicle segments.
- For instance, Toyo's premium all-season and performance lines, such as the Proxes ST III or Open Country series, are backed by treadwear warranties ranging from 40,000 to 65,000 miles (approx. 64,000 to 104,000 km), confirming durability well beyond the 60,000 km threshold.
Rising Demand for Noise Reduction and Ride Comfort
Electric vehicles operate with minimal powertrain noise, making road and tire noise more noticeable inside the cabin. This has intensified demand for EV tires with advanced noise reduction features such as optimized tread block designs, variable pitch sequencing, and sound-absorbing foam layers. Improved ride comfort and reduced vibration are now key purchase criteria for EV owners, especially in urban and premium vehicle segments. As consumer expectations for quiet, smooth mobility increase, tire manufacturers continue to invest in acoustic technologies that directly support market growth.
Key Trends & Opportunities
Integration of Eco-Friendly and Sustainable Materials
Sustainability is emerging as a major trend and opportunity in the electric vehicle tire market. Manufacturers are increasingly integrating bio-based polymers, recycled carbon black, and renewable fillers to reduce environmental impact without compromising performance. EV buyers are often environmentally conscious, creating strong alignment between electric mobility and sustainable tire solutions. This trend opens opportunities for differentiated product offerings, green branding, and compliance with tightening environmental regulations, particularly in Europe. Sustainable tire innovations also support circular economy initiatives through improved recyclability and extended tire life.
- For instance, Bridgestone Corporation has advanced its ENLITEN technology platform by incorporating recycled carbon black recovered through pyrolysis and plant-derived natural rubber alternatives, achieving material circularity rates exceeding 50 raw-material components per tire, while internal testing confirms weight reductions of up to 2 kilograms per tire and rolling-resistance improvements validated over endurance testing cycles beyond 80,000 kilometers without loss of wear performance.
Advancements in Smart and Connected Tire Technologies
The adoption of smart tire technologies presents a significant opportunity for the electric vehicle tire market. Embedded sensors capable of monitoring pressure, temperature, tread wear, and road conditions enable predictive maintenance and improved vehicle efficiency. These data-driven insights help optimize energy consumption, enhance safety, and reduce total cost of ownership for EV fleets and individual users. As electric vehicles increasingly integrate with digital vehicle platforms, smart EV tires align well with broader trends in connected mobility and software-defined vehicles.
- For instance, Kumho Tyre (Australia) Pty Ltd. supports Kumho Tire’s proprietary intelligent tire systems that integrate in-tire sensors capable of measuring internal pressure changes within 0.1 bar accuracy and temperature variations across a range up to 120 degrees Celsius, while transmitting data at intervals below 1 second to vehicle control units, validated through endurance testing exceeding 100,000 kilometers under EV-specific load and torque conditions.
Expansion of the EV Aftermarket Segment
Beyond OEM demand, the EV tire aftermarket is emerging as a strong growth opportunity. As early generations of electric vehicles age, replacement cycles are accelerating, increasing demand for EV-specific tires. Consumers are becoming more aware of the performance differences between conventional and EV-optimized tires, supporting premium aftermarket adoption. Expanding EV penetration in ride-hailing, logistics, and shared mobility fleets further strengthens replacement demand, creating long-term volume opportunities for tire manufacturers and distributors.
Key Challenges
Higher Development and Manufacturing Costs
Developing electric vehicle-specific tires involves higher R&D and production costs compared to conventional tires. Advanced materials, specialized compounds, reinforced structures, and noise-reduction technologies increase complexity and cost. These factors can limit price competitiveness, particularly in cost-sensitive markets and emerging economies. Balancing performance requirements with affordability remains a key challenge for manufacturers, especially as EV adoption expands beyond premium vehicle segments into mass-market categories.
Limited Consumer Awareness and Standardization
Despite growing EV adoption, consumer awareness of the importance of EV-specific tires remains uneven. Many users continue to replace tires with conventional alternatives, potentially compromising vehicle range, noise performance, and safety. Additionally, the lack of universal standards for EV tire labeling and performance benchmarks creates confusion in the market. Educating consumers, dealers, and fleet operators while working toward clearer performance standards is essential to unlock the full growth potential of the electric vehicle tire market.
Regional Analysis
North America
North America accounts for approximately 32% of the global electric vehicle tire market, driven by strong EV adoption in the United States and Canada, supportive government incentives, and stringent fuel-efficiency regulations. Automakers increasingly specify low rolling resistance and noise-optimized tires to enhance EV range and cabin comfort, directly supporting demand. The region benefits from advanced R&D capabilities, strong OEM–tire manufacturer collaborations, and a growing replacement market as the installed EV base expands. Rising penetration of electric SUVs and pickup trucks further accelerates demand for high-load, durable EV-specific tires tailored to higher torque requirements.
Europe
Europe holds around 28% of the electric vehicle tire market, supported by aggressive carbon-reduction targets, bans on internal combustion engine sales in several countries, and rapid electrification across passenger and commercial fleets. Germany, France, and the Nordic countries lead adoption, emphasizing premium, sustainable tire technologies. European demand strongly favors eco-friendly materials, low rolling resistance compounds, and advanced noise-reduction designs aligned with strict vehicle noise regulations. The presence of major automotive OEMs and tire manufacturers enables early integration of EV-optimized tires into new vehicle platforms, strengthening original equipment demand across the region.
Asia-Pacific
Asia-Pacific dominates the electric vehicle tire market with an estimated 34% share, led by China’s large-scale EV production and sales, followed by Japan, South Korea, and rapidly growing markets such as India. High EV manufacturing volumes, cost-competitive tire production, and strong government subsidies significantly support regional growth. Demand spans both mass-market passenger EVs and electric two-wheelers, creating large-volume opportunities. Local manufacturers focus on balancing affordability with performance, while premium EV segments increasingly adopt advanced tread designs and lightweight materials to improve efficiency and durability under high-torque conditions.
Latin America
Latin America represents about 4% of the electric vehicle tire market, reflecting an early but gradually expanding stage of EV adoption. Countries such as Brazil, Mexico, and Chile lead regional growth through pilot electrification programs, urban mobility initiatives, and increasing public charging infrastructure. Demand is primarily concentrated in fleet vehicles, electric buses, and compact passenger EVs, driving the need for durable and cost-effective tires. As EV penetration rises, replacement tire demand is expected to grow steadily, supported by improving regulatory frameworks and increasing awareness of total cost of ownership benefits.
Middle East & Africa
The Middle East & Africa region accounts for roughly 2% of the global electric vehicle tire market, with growth driven by sustainability initiatives, smart city projects, and gradual EV adoption in the Gulf Cooperation Council countries. The UAE and Saudi Arabia lead regional demand, supported by investments in charging infrastructure and electric public transport. Harsh climatic conditions increase demand for heat-resistant and high-durability EV tires. Although overall volumes remain limited, long-term growth potential exists as governments diversify transportation systems and encourage low-emission mobility solutions.
Electric Vehicle Tires Market Segmentations:
By Tire Type:
- Summer tires
- Winter tires
By Tire Construction:
- Radial
- Bias
By Technology:
- Run-flat technology
- Self-sealing tires
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the electric vehicle tire market players such as Hankook Tire and Technology Co., Ltd., The Goodyear Tire and Rubber Company, Yokohama Tire Corporation, Pirelli Tyre S.p.A, Toyo Engineering Corporation, Bridgestone Corporation, Kumho Tyre (Australia) Pty Ltd., Continental AG, Sumitomo Corporation. the electric vehicle tire market is shaped by rapid technological innovation, rising performance expectations, and increasing alignment with sustainability goals. Manufacturers compete by engineering EV-specific tires that address higher vehicle weight, instant torque delivery, and the need for extended driving range. Key areas of differentiation include ultra-low rolling resistance compounds, reinforced carcass structures for higher load indices, and advanced tread designs that reduce road noise to complement quiet electric drivetrains. Players also emphasize sustainable raw materials, recyclable components, and energy-efficient manufacturing to align with OEM decarbonization targets. Strong collaboration with electric vehicle manufacturers enables early-stage tire integration and platform-specific customization. Additionally, digital technologies such as smart tires, embedded sensors, and predictive wear analytics are gaining importance as automakers move toward connected and software-defined vehicles. Overall, competition increasingly centers on innovation depth, sustainability credentials, and the ability to scale EV-focused tire solutions globally.
Key Player Analysis
- Hankook Tire and Technology Co., Ltd.
- The Goodyear Tire and Rubber Company
- Yokohama Tire Corporation
- Pirelli Tyre S.p.A
- Toyo Engineering Corporation
- Bridgestone Corporation
- Kumho Tyre (Australia) Pty Ltd.
- Continental AG
- Sumitomo Corporation
- The Michelin Group
Recent Developments
- In August 2025, Nexen Tire launched the N'FERA Supreme EV ROOT, a tire for both Electric Vehicles (EVs) and Internal Combustion Engine (ICE) cars, showing a 20% lower rolling resistance and 13% better wet/dry handling in tests with a Kia EV6, offering efficiency for EVs and performance for all, using an 'EV ROOT' mark for such versatile products.
- In June 2025, Goodyear launched the Assurance MaxGuard SUV tire in India, specifically for the growing SUV market, including electric SUVs, focusing on strong durability (DuraGuard Tech, 2-ply), better wet grip (ActiveGrip Tech), comfort, and improved fuel efficiency (around 2% better due to low rolling resistance), making it a versatile, EV-ready choice for Indian roads.
- In March 2025, CEAT launched its new SportDrive luxury tyre range in India, featuring innovations like ZR-rated 21-inch tyres for ultra-high speeds, Run-Flat Tyres (RFTs) for enhanced safety, and CALM Technology (with foam inserts) to significantly reduce in-cabin noise, targeting high-end sedans and SUVs with competitive pricing and global tech.
Report Coverage
The research report offers an in-depth analysis based on Tire Type, Tire Construction, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Growth in Electric Vehicle Production
The surge in global electric vehicle manufacturing, especially in Asia-Pacific, Europe, and North America, is directly increasing demand for EV-specific tires that can handle higher weights, instant torque, and unique load distributions. OEMs are integrating EV-optimized tires at the design stage to improve range, durability, and comfort, fueling both original equipment and replacement tire sales.
Focus on Energy Efficiency and Driving Range
EV owners and automakers prioritize tires with low rolling resistance to maximize driving range per charge. Advanced tread compounds and lightweight materials are being developed to minimize energy loss, while regulatory pressure for improved vehicle efficiency further accelerates the adoption of specialized EV tires.
Rising Demand for Noise Reduction and Ride Comfort
With minimal powertrain noise in EVs, tire and road noise become more prominent, driving demand for tires with advanced noise reduction features such as optimized tread block designs and sound-absorbing foam layers. Enhanced ride comfort and reduced vibration are increasingly important for EV consumers, especially in urban and premium segments.
Integration of Eco-Friendly and Sustainable Materials
Manufacturers are incorporating bio-based polymers, recycled materials, and renewable fillers to meet sustainability targets and appeal to environmentally conscious EV buyers. This trend is reinforced by tightening environmental regulations and supports product differentiation and green branding.
Advancements in Smart and Connected Tire Technologies
The adoption of embedded sensors and smart tire technologies enables real-time monitoring of pressure, temperature, and tread wear, supporting predictive maintenance and improved vehicle efficiency. These innovations align with the broader trend toward connected and software-defined vehicles, enhancing safety and reducing total cost of ownership for EV fleets and individual users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electric Vehicle Tire Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Vehicle Tire Market projected to grow between 2024 and 2032?
Which Electric Vehicle Tire Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Vehicle Tire Market?
Who are the leading companies in the Electric Vehicle Tire Market?
Which region commanded the largest share of the Electric Vehicle Tire Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Tire Type
- 1.2.1 All-season tires
- 1.2.2 Summer tires
- 1.2.3 Winter tires
- 1.2.4 All-terrain tires
- 1.2.5 Performance tires
- 1.3 By Technology
- 1.3.1 Eco-friendly tires
- 1.3.2 Noise reduction technology
- 1.3.3 Run-flat technology
- 1.3.4 Self-sealing tires
- 1.3.5 Smart/connected tires
- 1.4 By Tire Construction
- 1.4.1 Radial
- 1.4.2 Bias
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,495.8 million → 2032: USD 16,928.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Vehicle Tires Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Vehicle Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Vehicle Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Vehicle Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Vehicle Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Vehicle Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Vehicle Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Vehicle Tires Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,495.8 million → 2032: USD 16,928.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Vehicle Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Tire Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 All-season tires
- 12.3.7.2 Summer tires
- 12.3.7.3 Winter tires
- 12.3.7.4 All-terrain tires
- 12.3.7.5 Performance tires
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Eco-friendly tires
- 12.4.7.2 Noise reduction technology
- 12.4.7.3 Run-flat technology
- 12.4.7.4 Self-sealing tires
- 12.4.7.5 Smart/connected tires
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Tire Construction - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Radial
- 12.5.7.2 Bias
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Vehicle Tires Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Vehicle Tires Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Vehicle Tires Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Hankook Tire and Technology Co., Ltd.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 The Goodyear Tire and Rubber Company
- 17.4 Yokohama Tire Corporation
- 17.5 Pirelli Tyre S.p.A
- 17.6 Toyo Engineering Corporation
- 17.7 Bridgestone Corporation
- 17.8 Kumho Tyre (Australia) Pty Ltd.
- 17.9 Continental AG
- 17.10 Sumitomo Corporation
- 17.11 The Michelin Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

