
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Embedded Motherboard Market Size 2024 | USD 3853.88 million |
| Embedded Motherboard Market , CAGR | 2.97% |
| Embedded Motherboard Market Size 2032 | USD 4870.62 million |
Market Overview:
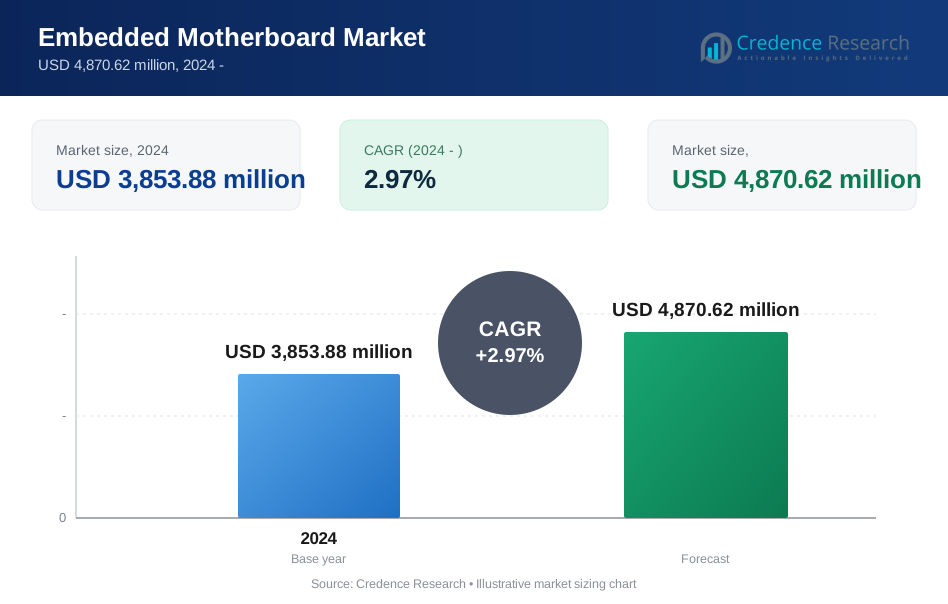
The Global Embedded Motherboard Market size was valued at USD 3853.88 million in 2024 and is anticipated to reach USD 4870.62 million by 2032, at a CAGR of 2.97% during the forecast period (2024-2032).
Several factors drive the embedded motherboard market, including the rise in automation and the need for more efficient, compact, and high-performance computing solutions. The increasing adoption of embedded motherboards in IoT devices, smart homes, and industrial automation systems is also contributing to the market's growth. The demand for embedded motherboards in robotics, manufacturing, and medical devices is further expanding their scope. Additionally, advancements in semiconductor technology are enabling the development of high-performance, low-power embedded motherboards that cater to a wide range of applications. The automotive sector's shift toward electric vehicles (EVs) and autonomous driving systems further boosts the demand for embedded solutions. Moreover, the growing trend of digitalization across industries is accelerating the deployment of embedded systems, thus driving the market. This is particularly evident in the rise of connected devices and the push for real-time data processing.
Regionally, North America dominates the embedded motherboard market, owing to the presence of key players and advancements in IoT and industrial automation technologies. The region's focus on smart manufacturing and the adoption of Industry 4.0 are also contributing to market growth. Additionally, the growing emphasis on 5G technology is expected to drive further demand for embedded motherboards in communication devices. Europe follows closely, driven by the expanding automotive and healthcare sectors. The region's initiatives in sustainable technologies and electric mobility also foster market expansion. Meanwhile, the Asia-Pacific region is expected to witness the highest growth during the forecast period, primarily due to the rapid industrialization, increasing adoption of IoT devices, and growing demand for embedded systems in emerging economies such as China and India. The region's cost-efficient manufacturing capabilities are also helping to make embedded systems more accessible.
Market Insights:
- The embedded motherboard market is expected to grow from USD 3,853.88 million in 2024 to USD 4,870.62 million by 2032, with a CAGR of 2.97% during the forecast period.
- The increasing adoption of IoT devices, smart homes, and industrial automation systems is contributing significantly to the market's growth.
- The rise in automation and industrial IoT adoption is driving demand for high-performance, compact, and energy-efficient embedded solutions across sectors.
- Advancements in semiconductor technology are enabling the development of low-power, high-performance embedded motherboards.
- The automotive sector’s transition to electric vehicles and autonomous driving is fueling the demand for embedded systems in EVs, sensors, and control systems.
- The global trend of digitalization and the increasing use of 5G technologies are expanding the market for embedded motherboards in connected devices and real-time data processing.
- North America holds the largest market share, while the Asia-Pacific region is expected to see the highest growth rate, driven by industrialization and IoT adoption.
Market Drivers:
Rise in Automation and Industrial IoT Adoption
The growing trend of automation across various industries is one of the primary drivers of the embedded motherboard market. Industries such as manufacturing, automotive, and healthcare are increasingly relying on embedded systems to optimize operations, improve efficiency, and reduce costs. Embedded motherboards are integral to the functioning of industrial automation systems, providing robust computing platforms for controlling machines, robots, and production lines. The integration of Industrial Internet of Things (IIoT) devices is also driving demand, as these devices require efficient and reliable embedded systems for real-time data processing, monitoring, and analysis. As automation continues to proliferate, the need for advanced embedded motherboards to power these systems will increase substantially.
Advancements in Semiconductor Technology
Semiconductor technology advancements are playing a significant role in the growth of the embedded motherboard market. As the demand for more compact, energy-efficient, and high-performance systems rises, manufacturers are developing semiconductors with improved processing power and lower energy consumption. For instance, companies like Black Semiconductor in Germany are leveraging graphene-based solutions to enhance connectivity and efficiency for applications such as autonomous driving and IoT systems. These innovations enable the production of embedded motherboards that can handle complex tasks with minimal power requirements, a crucial aspect for embedded applications in industries such as automotive, medical, and consumer electronics. The continued progress in semiconductor fabrication, including the use of advanced materials and smaller process nodes, is further driving the market as it allows for the development of high-performance embedded solutions at competitive prices.
Shift Toward Electric Vehicles and Autonomous Driving
The automotive sector’s transition toward electric vehicles (EVs) and the development of autonomous driving technologies is fueling demand for embedded motherboards. EVs rely heavily on embedded systems for battery management, powertrain control, and infotainment, while autonomous vehicles require powerful embedded solutions for real-time processing, sensors, and control systems. For instance, Magna International integrates AI-powered thermal sensors into autonomous driving systems to detect pedestrians using body heat. As automotive manufacturers strive for smarter, safer, and more efficient vehicles, the adoption of embedded motherboards in these applications is set to increase. Furthermore, with the rise of advanced driver-assistance systems (ADAS) and connected vehicle technology, the demand for embedded systems to support these innovations continues to grow.
Growing Trend of Digitalization and Connectivity
The global trend of digitalization is another key factor propelling the embedded motherboard market. As businesses and industries continue to adopt digital technologies, the demand for embedded systems to power connected devices and platforms has surged. From smart homes and wearable technology to healthcare devices and smart cities, embedded motherboards serve as the backbone for numerous applications that rely on constant connectivity. The rise of 5G technology further amplifies this demand, as faster, more reliable internet speeds enable more advanced IoT devices and connected systems. As more sectors embrace digital transformation, the need for embedded systems that offer high performance and connectivity will only intensify, driving market growth in the coming years.
Market Trends:
Smaller and Energy-Efficient Solutions
One of the significant trends in the embedded motherboard market is the growing demand for smaller, more energy-efficient solutions. As industries increasingly adopt IoT devices and automation technologies, the need for embedded motherboards that are both compact and capable of high performance has intensified. Manufacturers are focusing on creating systems that offer powerful processing capabilities while minimizing space and power consumption. This trend is particularly evident in sectors such as automotive, healthcare, and consumer electronics, where space constraints and energy efficiency are paramount. As a result, companies are developing embedded motherboards with advanced low-power semiconductors and smaller form factors to meet these demands.
Integration of AI and Machine Learning
Another key trend is the rising integration of artificial intelligence (AI) and machine learning (ML) capabilities into embedded systems. AI and ML are becoming essential for applications that require real-time data processing, predictive maintenance, and automation. For instance, Ford Motor Company has implemented neural networks to automate quality assurance, detect wrinkles in car seats, and support inventory and resource management in its supply chain. Embedded motherboards with built-in AI and ML features are increasingly being used in industries like manufacturing, healthcare, and transportation to enable smarter decision-making and enhanced operational efficiency. This trend is expected to accelerate as more industries adopt intelligent systems that can process vast amounts of data quickly and autonomously.
Expansion of 5G Technology
The expansion of 5G technology is also driving innovation in the embedded motherboard market. With the rollout of 5G networks worldwide, the demand for embedded systems that can support ultra-fast connectivity has surged. For instance, China Unicom has pioneered the deployment of the country's first city-wide RedCap network in Jinan, with the installation of 3,220 5G RedCap terminals for various applications in the power grid sector. Embedded motherboards are crucial for powering 5G-enabled devices, such as connected cars, smart cities, and industrial IoT applications. The higher bandwidth and lower latency offered by 5G networks require embedded motherboards that can handle the increased data traffic and provide seamless communication between devices, which is reshaping the market landscape.
Focus on Edge Computing
Lastly, the increasing focus on edge computing is another notable trend. As more businesses move toward decentralizing data processing to reduce latency and improve real-time analytics, embedded motherboards that support edge computing applications are gaining traction. These systems enable faster decision-making at the device level, reducing the reliance on centralized cloud infrastructures. This trend is particularly important for industries like healthcare, automotive, and industrial automation, where quick data processing is essential for mission-critical operations.
Market Challenges Analysis:
Technological Complexity and Integration
One of the primary challenges in the embedded motherboard market is the increasing complexity of technology integration. As industries adopt more advanced applications, embedded motherboards are required to support higher levels of performance, multiple connectivity options, and integration with other systems. For instance, Kontron has successfully integrated Intel’s 14th-gen processors into their motherboards, ensuring higher data transfer speeds and improved performance while maintaining energy efficiency and scalability for industries like automation and healthcare. However, the integration of diverse technologies such as AI, IoT, and 5G into embedded systems can be complex, requiring careful consideration of compatibility, power consumption, and heat dissipation. Manufacturers face the challenge of designing motherboards that meet the demands for speed, efficiency, and size while also maintaining reliability and ease of integration. This complexity often leads to higher development costs and longer time-to-market for new products, posing a significant barrier for companies looking to stay competitive. Moreover, as end-user requirements become more specialized, designing customizable solutions further adds to the challenge.
Supply Chain Disruptions and Component Shortages
Another significant challenge for the embedded motherboard market is the ongoing supply chain disruptions and component shortages. The global semiconductor shortage has affected various industries, including embedded systems, where a steady supply of high-quality components is essential for manufacturing motherboards. Shortages of critical components such as chips, resistors, and capacitors have led to delays in production and increased costs. Additionally, disruptions in global logistics and shipping have further exacerbated these challenges, making it difficult for manufacturers to meet demand. As embedded systems are used in a wide range of industries, from automotive to healthcare, supply chain vulnerabilities can significantly impact the ability to deliver timely and cost-effective solutions, thereby hindering market growth. This situation has pushed manufacturers to explore alternative supply sources, but shortages remain a persistent challenge.
Market Opportunities:
The embedded motherboard market offers significant growth opportunities driven by advancements in technology and the increasing demand for IoT, automation, and intelligent systems. As industries continue to embrace digital transformation, there is a growing need for embedded systems to power smart devices, connected networks, and automated processes. This provides an opportunity for manufacturers to develop high-performance, energy-efficient embedded motherboards that cater to specific industry requirements, such as in automotive, healthcare, and industrial automation. The rise of Industry 4.0 and smart manufacturing is creating new avenues for embedded systems that can support real-time data processing and improve operational efficiency. Additionally, the rapid adoption of IoT devices across various sectors, including agriculture, healthcare, and consumer electronics, presents a growing market for embedded motherboards capable of supporting these technologies.
Another key opportunity for the embedded motherboard market lies in the expansion of electric vehicles (EVs) and autonomous driving systems. As the automotive industry continues to shift towards electric mobility, the demand for embedded systems to support battery management, powertrain control, and connected vehicle technologies is expected to increase. Embedded motherboards are crucial in enabling the advanced functionalities required for EVs and autonomous vehicles, such as real-time data processing, sensor integration, and vehicle-to-infrastructure communication. Furthermore, the global rollout of 5G networks is creating new possibilities for embedded systems in applications that require ultra-fast, low-latency connectivity. As industries and consumers alike increasingly rely on these technologies, embedded motherboard manufacturers can capitalize on the demand for next-generation, high-performance solutions.
Market Segmentation Analysis:
By Types
The embedded motherboard market is segmented based on types, including single-board computers (SBCs), system-on-modules (SOMs), and embedded mini-ITX. SBCs dominate the market due to their compact size, ease of integration, and versatility in various applications, such as industrial automation and IoT devices. SOMs are gaining traction for their high modularity and adaptability, making them suitable for custom solutions across industries like automotive and medical. Embedded mini-ITX motherboards are used in applications requiring more processing power while maintaining a compact form factor, such as digital signage and gaming systems.
By Architecture
Embedded motherboards are further segmented by architecture, including x86, ARM, and RISC. x86-based embedded motherboards hold a significant market share due to their compatibility with a wide range of operating systems and software applications. ARM-based embedded systems are growing in popularity due to their lower power consumption, making them ideal for mobile and IoT applications. RISC architecture is used in high-performance systems requiring efficient computation, with applications in sectors like aerospace and defense.
By End-User
The embedded motherboard market serves multiple end-users, including automotive, healthcare, industrial automation, consumer electronics, and telecommunications. The automotive sector is experiencing strong growth due to the rise in electric vehicles and autonomous driving technologies. The industrial automation segment is another key driver, as businesses embrace IoT and smart manufacturing technologies. The healthcare sector’s demand for embedded systems is increasing, especially in medical devices and patient monitoring systems.
Segmentations:
- By Types:
- Single-Board Computers (SBCs)
- System-on-Modules (SOMs)
- Embedded Mini-ITX
- By Architecture:
- x86
- ARM
- RISC
- By End-User:
- Automotive
- Healthcare
- Industrial Automation
- Consumer Electronics
- Telecommunications
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
North America holds the largest market share in the embedded motherboard sector, with a share of 40%. The region’s dominance is attributed to the presence of leading manufacturers, technological advancements, and a strong focus on industrial automation and IoT. North America’s automotive industry is also a major contributor to the market growth, as embedded systems are crucial for electric vehicles (EVs), autonomous driving technologies, and advanced driver-assistance systems (ADAS). Furthermore, the increasing focus on smart cities and connected infrastructure is driving the demand for embedded solutions across sectors such as urban development and energy management. Additionally, the growing adoption of 5G technology and smart manufacturing solutions in the region is further boosting the demand for embedded motherboards. The U.S. is a central hub for technology innovation, with an emphasis on research and development, making it a key driver of market growth in North America.
Europe
Europe holds a significant market share of 30%, driven by the increasing use of embedded systems in sectors such as automotive, healthcare, and industrial automation. The automotive sector, in particular, is a major contributor to market growth, as Europe is home to some of the world’s largest automotive manufacturers, including those investing heavily in electric mobility and autonomous vehicle technologies. The region is also seeing a strong push for sustainable technologies, including energy-efficient embedded systems for renewable energy projects. Moreover, Europe’s strong focus on sustainability and the push for smarter, more connected cities are contributing to the increasing demand for embedded systems. The adoption of Industry 4.0 technologies and digital transformation in manufacturing further boosts market opportunities across the region. Additionally, the implementation of strict regulatory standards in various sectors is increasing the demand for reliable embedded systems.
Asia-Pacific (APAC)
Asia-Pacific (APAC) is expected to witness the highest growth rate during the forecast period, capturing a market share of 25%. The rapid industrialization in countries like China, India, and Japan is driving the demand for embedded systems across various applications, including automotive, consumer electronics, and industrial automation. APAC is also experiencing a strong rise in IoT devices and connected infrastructure, significantly driving embedded motherboard demand. The APAC region is home to several key manufacturers and a strong base for semiconductor production, which is critical for embedded motherboard development. Moreover, the region’s emerging economies are increasingly investing in digital transformation and smart city initiatives, creating new opportunities for embedded systems. Additionally, the growing adoption of IoT devices, 5G technology, and smart infrastructure in emerging economies is fueling the demand for embedded solutions. With the rise of digitalization in the region, APAC is set to be a major growth driver for the embedded motherboard market in the coming years.
Key Player Analysis:
- JWIPC Technology Co Ltd
- DFI Inc
- AAEON Technology Inc
- Winmate
- Darveen Co., Ltd
- GIGAIPC CO., Ltd
- Asus IoT
- Micro-Star International Co., Ltd
- ADLINK Technology Inc
- ASRock Inc
- Contec Co., Ltd
- MiTAC Holdings Corporation
- AEWIN Technologies Co., Ltd
- Kontron AG
- Gigabyte Technology
Competitive Analysis:
The embedded motherboard market is highly competitive, with key players constantly innovating to meet the evolving demands of industries such as automotive, healthcare, and industrial automation. Major companies in the market include Intel Corporation, Advantech Co., Ltd., Kontron, and ASRock Industrial, among others. These companies are focusing on developing high-performance, energy-efficient embedded systems that support advancements in IoT, AI, and 5G technologies. They are also investing heavily in R&D to improve semiconductor technologies and offer customizable solutions to cater to specific industry needs. Additionally, partnerships and collaborations are common strategies for companies to expand their product portfolios and gain access to new markets. The market is also characterized by a growing trend toward edge computing, driving the development of embedded motherboards that can support real-time data processing. As demand for smart, connected systems increases, the competition is expected to intensify, with a focus on innovation and customer-centric solutions.
Recent Developments:
- In February 2025, JWIPC Technology Co Ltd introduced the JEC-5310 embedded PC, powered by the Intel® Tiger Lake U SoC with a 15W TDP, designed for energy efficiency and high performance in industrial applications.
- In January 2024, DFI Inc participated in the Embedded Tech India Expo, showcasing rugged industrial-grade products, industrial motherboards, and embedded systems in collaboration with distribution partner Dynalog.
- In March 2025, DFI Inc announced its participation in Embedded World 2025, focusing on edge AI solutions for smart cities, industrial automation, intelligent transportation, and healthcare.
Market Concentration & Characteristics:
The embedded motherboard market exhibits a moderate level of concentration, with several key players commanding significant market share, including Intel Corporation, Advantech Co., Ltd., Kontron, ASRock Industrial, and ASUS. These companies lead the market through continuous innovation, offering a wide range of high-performance, customizable embedded solutions across various industries such as automotive, healthcare, industrial automation, and telecommunications. While the market is dominated by large corporations, numerous smaller, regional players contribute by focusing on niche segments and specialized applications. The competition is driven by advancements in technologies such as AI, IoT, and 5G, which push companies to develop energy-efficient, high-performance systems. As a result, product differentiation plays a significant role, with companies competing on factors such as innovation, quality, customization, and pricing. This dynamic market is expected to see increasing competition, as demand for embedded systems grows in response to the rising adoption of connected devices and smart technologies.
Report Coverage:
The research report offers an in-depth analysis based on Types, Architecture, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The embedded motherboard market is expected to witness significant growth driven by the increasing adoption of IoT, AI, and automation technologies across various industries.
- Demand for energy-efficient and compact embedded systems will continue to rise as industries look for high-performance solutions with low power consumption.
- The automotive sector, especially with the rise of electric vehicles and autonomous driving technologies, will remain a major driver for embedded systems.
- The integration of 5G technology will significantly enhance the demand for embedded motherboards, especially in smart cities, connected devices, and industrial applications.
- Advancements in semiconductor technology will enable the development of more powerful and efficient embedded motherboards, catering to a wide range of applications.
- The healthcare sector will increasingly rely on embedded systems for medical devices, patient monitoring systems, and healthcare automation.
- Regional markets, particularly in Asia-Pacific, will experience rapid growth due to industrialization and increased demand for embedded systems in emerging economies.
- Embedded systems will play a pivotal role in the growth of edge computing, reducing latency and enabling real-time data processing in industries like manufacturing and healthcare.
- Smaller companies and regional players will continue to innovate in niche applications, contributing to product diversity in the market.
- Competitive pressures will drive continuous technological advancements, pushing companies to offer highly customized and flexible embedded motherboard solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Embedded Motherboard Market?
What factors are driving the growth of the Embedded Motherboard Market?
What are the key segments within the Embedded Motherboard Market?
Who are the major players in the Embedded Motherboard Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Embedded Motherboard Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Embedded Motherboard Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 3,853.88 million → forecast year: USD 4,870.62 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Embedded Motherboard Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Embedded Motherboard Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Embedded Motherboard Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Embedded Motherboard Market Drivers
- 3.3 Embedded Motherboard Market Restraints & Challenges
- 3.4 Embedded Motherboard Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Embedded Motherboard Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Embedded Motherboard Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Embedded Motherboard category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Embedded Motherboard Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Embedded Motherboard Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Embedded Motherboard market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Embedded Motherboard Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Embedded Motherboard Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Embedded Motherboard Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Embedded Motherboard (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Embedded Motherboard Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Embedded Motherboard Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Embedded Motherboard Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Embedded Motherboard Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Embedded Motherboard Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Embedded Motherboard Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Embedded Motherboard Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Embedded Motherboard Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Embedded Motherboard Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
