
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Embedded Systems Market Size 2023 | USD 93881.5 million |
| Embedded Systems Market, CAGR | 6.1% |
| Embedded Systems Market Size 2032 | USD 150765.88 million |
Market Overview
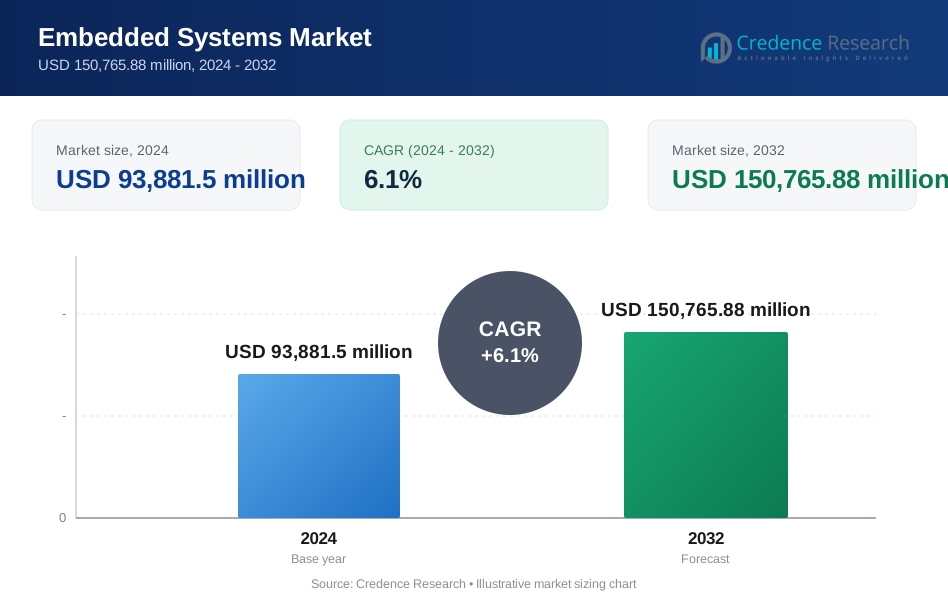
The Embedded System Market is projected to grow from USD 93881.5 million in 2024 to an estimated USD 150765.88 million by 2032, with a compound annual growth rate (CAGR) of 6.1% from 2024 to 2032.This growth is driven by the increasing integration of embedded systems across industries such as automotive, telecommunications, and consumer electronics.Key market drivers include the growing demand for real-time data processing in automotive and industrial applications, as well as advancements in technologies such as AI and IoT. The shift towards automation, especially in manufacturing and healthcare, fuels demand for embedded systems. Emerging trends such as 5G implementation, autonomous vehicles, and wearable technologies are expected to further boost market growth over the forecast period
Geographically, North America and Europe dominate the market due to high technology adoption rates and strong automotive and industrial sectors. Asia-Pacific is expected to witness the fastest growth, driven by rapid industrialization and increasing investments in consumer electronics and telecommunications. Key players in the global embedded systems market include Renesas Electronics, STMicroelectronics N.V., Infineon Technologies, Texas Instruments Inc., Qualcomm Incorporated, NXP Semiconductors, and Intel Corporation. These companies continuously innovate to maintain their competitive edge and expand their market presence.
Market Drivers
Rising Demand for IoT and Smart Devices
The rapid adoption of the Internet of Things (IoT) and the increasing demand for smart devices are significant drivers of the embedded systems market. IoT refers to the interconnected network of physical devices that collect and exchange data, allowing for automation, remote control, and real-time decision-making. Embedded systems serve as the backbone of IoT devices, enabling these devices to perform specific functions with efficiency and precision. For instance, the number of connected IoT devices is predicted to surpass 29 billion by 2030, nearly doubling from 2020. IoT is transforming industries such as healthcare, manufacturing, agriculture, and transportation, where smart devices are used to monitor, control, and optimize operations. In healthcare, for example, IoT-enabled medical devices like wearable health monitors and smart diagnostic tools rely heavily on embedded systems to provide accurate and real-time data. In healthcare, IoT-enabled medical devices like wearable health monitors provide continuous patient monitoring and real-time data collection. In the industrial sector, IoT-based sensors embedded in machinery help improve operational efficiency by enabling predictive maintenance and reducing downtime. In the industrial sector, IoT-based sensors embedded in machinery help improve operational efficiency by enabling predictive maintenance and reducing downtime.As the demand for IoT devices continues to grow, so does the need for advanced embedded systems that can support real-time data processing, low-power consumption, and seamless connectivity. This trend is expected to accelerate further with the rollout of 5G networks, which will enhance the capabilities of IoT devices and create new opportunities for the embedded systems market.
Advancements in Microprocessors and Microcontrollers
Technological advancements in microprocessors and microcontrollers are another critical driver of the embedded systems market. Microprocessors and microcontrollers form the core of embedded systems, enabling them to execute specific tasks efficiently. Over the years, significant improvements in the performance, power efficiency, and size of these components have expanded the application scope of embedded systems across various industries. One of the most notable advancements in this space is the development of multi-core processors, which allow embedded systems to handle complex tasks more efficiently. Multi-core processors provide the processing power required for applications such as autonomous vehicles, advanced driver assistance systems (ADAS), and industrial automation. The integration of artificial intelligence (AI) and machine learning (ML) capabilities into microprocessors and microcontrollers is also enhancing the functionality of embedded systems. AI-enabled embedded systems can process vast amounts of data in real-time, making them suitable for use in applications like predictive maintenance, robotics, and smart surveillance systems. As microprocessor and microcontroller technology continues to evolve, it will drive the demand for more sophisticated embedded systems that can meet the growing requirements of advanced applications.
Growing Automation in Industrial and Automotive Sectors
The increasing adoption of automation in the industrial and automotive sectors is a major driver of the embedded systems market. In the industrial sector, embedded systems are used in a wide range of applications, from factory automation and robotics to energy management and control systems. The growing focus on Industry 4.0, which emphasizes the use of smart technologies to optimize manufacturing processes, is driving the demand for embedded systems that can support real-time monitoring, data analysis, and decision-making. For instance, automated systems are expected to account for 25% of capital spending in the industrial sector over the next five years. Industrial automation relies on embedded systems to control and monitor machinery, ensure safety, and improve operational efficiency. For instance, embedded systems are used in programmable logic controllers (PLCs), human-machine interfaces (HMIs), and robotic controllers to automate repetitive tasks and reduce human intervention. As manufacturers seek to enhance productivity, reduce costs, and improve product quality, the demand for embedded systems in industrial automation is expected to rise. Similarly, in the automotive sector, the push towards automation and electrification is fueling the demand for embedded systems. Modern vehicles are equipped with a wide range of embedded systems that control everything from engine performance and safety features to infotainment and connectivity. In the automotive sector, advanced driver assistance systems (ADAS) and autonomous driving technologies rely on embedded systems to process data from multiple sensors and make real-time decisions. Advanced driver assistance systems (ADAS), autonomous driving technologies, and electric vehicle (EV) powertrain management are all dependent on sophisticated embedded systems. As the automotive industry continues to evolve, driven by the shift towards electric and autonomous vehicles, the embedded systems market will play a crucial role in supporting these innovations.
Increasing Focus on Energy Efficiency and Sustainability
As industries and consumers become more conscious of energy consumption and environmental sustainability, there is growing demand for energy-efficient embedded systems. Embedded systems are used in a variety of applications that require low power consumption, especially in battery-powered devices such as portable electronics, wearable devices, and remote sensors. The ability to design energy-efficient embedded systems is becoming increasingly important as manufacturers seek to reduce the environmental impact of their products and comply with regulatory standards. The shift towards renewable energy sources, such as solar and wind, also presents opportunities for the embedded systems market. Embedded systems play a key role in the management and optimization of renewable energy systems, enabling efficient energy generation, storage, and distribution. For example, embedded systems are used in solar inverters, smart grids, and energy storage systems to ensure optimal performance and reliability. Additionally, embedded systems are being used to develop energy-efficient solutions for smart buildings and smart cities, where they help monitor and control energy usage in real-time. These systems enable the integration of renewable energy sources, optimize energy consumption, and reduce waste, contributing to overall sustainability goals. The increasing focus on energy efficiency and sustainability will continue to drive the demand for advanced embedded systems in various sectors.
Market Trends
Growing Automation in Industrial and Automotive Sectors
The increasing adoption of automation in the industrial and automotive sectors is a major driver of the embedded systems market. In the industrial sector, embedded systems are used in a wide range of applications, from factory automation and robotics to energy management and control systems. The growing focus on Industry 4.0, which emphasizes the use of smart technologies to optimize manufacturing processes, is driving the demand for embedded systems that can support real-time monitoring, data analysis, and decision-making. For instance, automated systems are expected to account for 25% of capital spending in the industrial sector over the next five years. Industrial automation relies on embedded systems to control and monitor machinery, ensure safety, and improve operational efficiency. For instance, embedded systems are used in programmable logic controllers (PLCs), human-machine interfaces (HMIs), and robotic controllers to automate repetitive tasks and reduce human intervention. As manufacturers seek to enhance productivity, reduce costs, and improve product quality, the demand for embedded systems in industrial automation is expected to rise. Similarly, in the automotive sector, the push towards automation and electrification is fueling the demand for embedded systems. Modern vehicles are equipped with a wide range of embedded systems that control everything from engine performance and safety features to infotainment and connectivity. In the automotive sector, advanced driver assistance systems (ADAS) and autonomous driving technologies rely on embedded systems to process data from multiple sensors and make real-time decisions. Advanced driver assistance systems (ADAS), autonomous driving technologies, and electric vehicle (EV) powertrain management are all dependent on sophisticated embedded systems. As the automotive industry continues to evolve, driven by the shift towards electric and autonomous vehicles, the embedded systems market will play a crucial role in supporting these innovations.
Growing Adoption of Real-Time Operating Systems (RTOS)
Another significant trend in the embedded systems market is the growing adoption of real-time operating systems (RTOS). RTOS are crucial for embedded systems that require precise timing and reliable execution of tasks in real time. Sectors such as aerospace, automotive, telecommunications, and industrial automation are increasingly adopting RTOS due to their ability to handle time-sensitive applications where delays or system failures could lead to critical consequences. For instance, the telecommunications sector relies on RTOS for managing network infrastructure, ensuring seamless communication between over 10 billion connected devices. In the automotive industry, for example, RTOS are essential for embedded systems that control safety-critical functions such as airbags, braking systems, and electronic stability control. These systems must respond instantly to input signals, ensuring the safety and performance of vehicles. In the automotive industry, RTOS are essential for embedded systems that control safety-critical functions such as airbags, braking systems, and electronic stability control, with some systems requiring response times of less than 10 milliseconds. Similarly, in industrial automation, RTOS play a vital role in controlling robotic systems and machinery that require precise timing and synchronization to operate efficiently. The telecommunications sector also relies on RTOS for managing network infrastructure and ensuring seamless communication between devices. As the demand for real-time processing increases across industries, the adoption of RTOS in embedded systems is expected to grow, enabling more efficient, reliable, and responsive applications. This trend underscores the increasing complexity and sophistication of modern embedded systems as they become integral to mission-critical operations across diverse industries.
Market Restraints and Challenges
Complexity of Design and Development
One of the primary challenges faced by the Global Embedded Systems Market is the increasing complexity involved in designing and developing these systems. Embedded systems must meet stringent requirements for performance, efficiency, and reliability, particularly in industries such as automotive, aerospace, and healthcare, where safety and precision are critical. As embedded systems become more advanced, integrating multiple functionalities, such as artificial intelligence (AI), real-time data processing, and connectivity, into a compact and energy-efficient framework is becoming more difficult. The need for customized designs tailored to specific applications further adds to the complexity. Engineers must develop systems that balance power consumption, performance, and size while ensuring security and durability. Moreover, the growing demand for low-power, battery-operated devices poses additional challenges, requiring advanced hardware and software optimization. As a result, the increased complexity in design and development can lead to longer development cycles, higher costs, and potential delays in product launches, which may restrain market growth.
Security Concerns and Vulnerabilities
Another significant restraint in the embedded systems market is the growing concern over security vulnerabilities. As embedded systems become more interconnected through IoT and other smart technologies, they are increasingly exposed to cyber threats. Embedded systems often control critical infrastructure, industrial machinery, and medical devices, making them attractive targets for cyberattacks. Security breaches in these systems can lead to severe consequences, including system failures, data breaches, and compromised safety. The challenge lies in securing embedded systems without compromising performance or adding excessive costs. Many embedded systems have limited processing power and memory, making it difficult to implement robust security protocols. Furthermore, the lack of standardization in security measures across industries exacerbates the challenge. Companies must invest in secure hardware, encryption, and regular software updates to protect against evolving threats. The growing complexity of cyber threats and the challenges in securing embedded systems are significant barriers that could hinder market expansion if not adequately addressed.
Market Segmentation Analysis
By Component
The embedded systems market is driven by both hardware and software components, each playing a crucial role. The hardware segment, which includes microcontrollers, microprocessors, sensors, and integrated circuits (ICs), dominates the market due to the growing demand for high-performance systems that support real-time data processing and AI applications. Advancements in semiconductor technology have led to the development of more compact and energy-efficient hardware, further fueling this segment's growth. On the software side, operating systems, middleware, and application software are essential for managing hardware resources and enabling device communication. As AI, machine learning, and IoT become more integrated, software development is becoming increasingly complex. Real-time operating systems (RTOS), in particular, are gaining importance for their ability to handle time-sensitive tasks in critical applications like automotive and industrial automation.
By Type
Embedded systems can be categorized into four key types. Standalone embedded systems operate independently without relying on a host system and are commonly used in consumer electronics like calculators and washing machines, although their future growth may be limited by the rising demand for more sophisticated technologies. Real-time embedded systems, designed for time-sensitive applications, are rapidly gaining traction in safety-critical sectors such as automotive, industrial automation, and medical equipment, driven by the advancement of autonomous driving and industrial automation. Network embedded systems, essential for IoT and smart devices, enable communication between devices and are seeing significant growth with the expansion of IoT in healthcare, smart cities, and telecommunications. Mobile embedded systems, used in devices like smartphones and tablets, are experiencing continuous growth due to increasing connectivity needs and advancements in AI and IoT integration, making mobile systems more powerful and versatile.
Segments
Based on Component
- Hardware
- Software
Based on Type
- Standalone Embedded Systems
- Real-Time Embedded Systems
- Network Embedded Systems
- Mobile Embedded Systems
Based on Application
- Consumer Electronics
- Medical Equipment
- Industrial Automation
- Automotive Systems
- Aerospace & Defense Technologies
- Telecommunications
- Smart Devices
- Others
Based on Region
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis
North America (35%)
North America holds the largest share of the global embedded systems market, accounting for approximately 35% of the total market. The region’s dominance is driven by the presence of key players such as Intel Corporation, Texas Instruments, and Qualcomm, who are at the forefront of technological innovation. North America's strong position in the automotive, aerospace, and defense sectors fuels the demand for advanced embedded systems, particularly in applications such as autonomous driving and real-time data processing. The growing adoption of IoT, 5G technology, and AI in industries such as healthcare and industrial automation also plays a significant role in boosting the market in this region. Additionally, a well-established semiconductor industry and high R&D investments further bolster market growth.
Europe (25%)
Europe is the second-largest market, holding around 25% of the global market share. The region’s growth is driven by the strong automotive sector, with countries like Germany leading the way in the development of electric vehicles (EVs) and autonomous driving technologies. Europe is also a hub for industrial automation, particularly in countries like Germany, the UK, and France, where embedded systems are essential for optimizing production processes. The region has a growing demand for embedded systems in healthcare, aerospace, and telecommunications, with key players such as STMicroelectronics and Infineon Technologies driving innovation in these areas. The European Union’s focus on sustainability and energy-efficient systems is further propelling the market
Key players
- Renesas Electronics (Japan)
- STMicroelectronics N.V. (Switzerland)
- Infineon Technologies (Germany)
- Texas Instruments Inc. (U.S.)
- Qualcomm Incorporated (U.S.)
- NXP Semiconductors (Netherlands)
- Microchip Technology Inc. (U.S.)
- Analog Devices Inc. (U.S.)
- Intel Corporation (U.S.)
- Advanced Micro Devices, Inc. (U.S.)
Competitive Analysis
The Global Embedded Systems Market is highly competitive, with key players focusing on innovation, strategic acquisitions, and partnerships to strengthen their market positions. Companies like Renesas Electronics, STMicroelectronics, and Texas Instruments dominate the market due to their strong portfolios in microcontrollers, microprocessors, and sensors, which are critical components of embedded systems. Qualcomm and Intel lead in AI integration and real-time data processing capabilities, driving advancements in the automotive and telecommunications sectors. NXP Semiconductors and Infineon Technologies maintain a strong presence in automotive applications, particularly in electric vehicles and autonomous driving. In addition, companies like Microchip Technology, Analog Devices, and Advanced Micro Devices are focusing on energy-efficient embedded solutions to meet the rising demand in consumer electronics, industrial automation, and healthcare. The market is characterized by continuous R&D investment, which enables key players to enhance system performance and expand their presence across diverse industries.
Recent Developments
- In July 2022, Renesas Electronics Corporation completed the acquisition of Reality Analytics, Inc., a provider of embedded AI solutions.
- In September 2024, STMicroelectronics unveiled a new generation of silicon carbide power technology tailored for next-generation EV traction inverters.
- In October 2023, Infineon Technologies acquired GaN Systems, a global technology leader in the development of GaN-based solutions for power conversion.
- In March 2023, Texas Instruments introduced a new 32-bit general-purpose MCU portfolio based on the Arm Cortex-M0+ architecture.
- In April 2024, Qualcomm announced breakthrough Wi-Fi technology and introduced new AI-Ready IoT and Industrial Platforms at Embedded World 2024.
- In August 2023, NXP Semiconductors, along with other industry players, formed a new company to drive the adoption of RISC-V globally.
- In July 2023, Microchip Technology announced a multi-year initiative to invest approximately $300 million in expanding its operations in India.
- In June 2023, Analog Devices launched Apollo MxFE, a software-defined, direct RF-sampling platform.
- In February 2024, Intel launched the world’s first systems foundry designed for the AI era.
- In February 2024, AMD announced the launch of AMD Embedded+, a new architectural solution that combines AMD Ryzen Embedded processors with Versal adaptive SoCs.
Market Concentration and Characteristics
The Global Embedded Systems Market is moderately concentrated, with a few leading players such as Renesas Electronics, STMicroelectronics, Texas Instruments, and Intel Corporation commanding a significant share of the market. These companies have strong footholds due to their advanced technology offerings, extensive R&D capabilities, and established relationships across industries like automotive, consumer electronics, and industrial automation. The market is characterized by high innovation, driven by the integration of AI, IoT, and real-time processing capabilities into embedded systems. Additionally, the sector demands continuous technological advancements in hardware components and software solutions, with companies focusing on energy efficiency, miniaturization, and enhanced performance. Although the market is competitive, barriers to entry exist due to the complexity of product development and the need for significant capital investment in research and infrastructure.
Report Coverage
The research report offers an in-depth analysis based on Component, Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The integration of artificial intelligence (AI) and machine learning (ML) into embedded systems will continue to expand, enhancing automation and real-time decision-making across industries such as automotive, healthcare, and industrial automation.
- The proliferation of the Internet of Things (IoT) will drive the demand for embedded systems that enable smart devices and interconnected networks, particularly in consumer electronics, smart cities, and industrial automation.
- The global rollout of 5G networks will boost demand for high-speed, low-latency embedded systems, especially in telecommunications, autonomous vehicles, and smart infrastructure.
- The growing development of autonomous vehicles will create new opportunities for embedded systems in the automotive sector, with an increased focus on safety-critical applications and real-time processing.
- Energy efficiency will remain a critical focus for future embedded systems, particularly as industries seek to reduce power consumption and extend battery life in portable and IoT devices.
- Embedded systems will play an increasingly important role in smart healthcare devices, enabling advanced patient monitoring, diagnostics, and real-time data analysis, driven by the rising demand for personalized medical care.
- As embedded systems become more interconnected, ensuring robust cybersecurity will be crucial, with future systems incorporating advanced encryption and secure communication protocols to prevent data breaches.
- Continued advancements in semiconductor technology will lead to smaller, more efficient embedded systems, enabling their integration into compact devices such as wearables and medical implants.
- The adoption of Industry 4.0 technologies will fuel demand for embedded systems in factory automation, robotics, and industrial IoT, helping businesses improve efficiency and productivity.
- Asia-Pacific and Latin America are expected to witness rapid growth in the embedded systems market, driven by rising industrialization, increased investment in technology, and growing demand for consumer electronics and smart infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of IoT and Smart Devices
The proliferation of IoT and smart devices across industries such as healthcare, manufacturing, and consumer electronics is fueling demand for embedded systems that enable real-time data processing, automation, and connectivity.
Advancements in Microprocessors and Microcontrollers
Continuous improvements in microprocessor and microcontroller technology, including the integration of AI and multi-core architectures, are enabling more powerful and energy-efficient embedded systems for complex applications like autonomous vehicles and industrial automation.
Automation in Industrial and Automotive Sectors
The shift toward Industry 4.0 and the rise of autonomous and electric vehicles are driving the adoption of embedded systems for real-time monitoring, control, and safety-critical functions in factories and vehicles.
Focus on Energy Efficiency and Sustainability
Growing emphasis on reducing power consumption and supporting renewable energy systems is increasing the need for energy-efficient embedded solutions in applications such as smart grids, portable electronics, and smart buildings.
Adoption of Real-Time Operating Systems (RTOS)
The need for precise, reliable, and time-sensitive operations in sectors like automotive, aerospace, and telecommunications is accelerating the adoption of RTOS, which are essential for mission-critical embedded applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Embedded Systems Market in 2023,and what is the forecast for 2032?
What are the key drivers of growth in the Global Embedded SystemsMarket?
How does the integration of AI and ML impact the embedded systemsmarket?
What role do embedded systems play in the automotive sector?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Standalone Embedded Systems
- 1.2.2 Real-Time Embedded Systems
- 1.2.3 Network Embedded Systems
- 1.2.4 Mobile Embedded Systems
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.4 By Application
- 1.4.1 Consumer Electronics
- 1.4.2 Medical Equipment
- 1.4.3 Industrial Automation
- 1.4.4 Automotive Systems
- 1.4.5 Aerospace & Defense Technologies
- 1.4.6 Telecommunications
- 1.4.7 Smart Devices
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 93,881.5 million → 2032: USD 150,765.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Embedded Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Embedded Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Embedded Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Embedded Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Embedded Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Embedded Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Embedded Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Embedded Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 93,881.5 million → 2032: USD 150,765.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Embedded Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Standalone Embedded Systems
- 12.3.7.2 Real-Time Embedded Systems
- 12.3.7.3 Network Embedded Systems
- 12.3.7.4 Mobile Embedded Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Medical Equipment
- 12.5.7.3 Industrial Automation
- 12.5.7.4 Automotive Systems
- 12.5.7.5 Aerospace & Defense Technologies
- 12.5.7.6 Telecommunications
- 12.5.7.7 Smart Devices
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Embedded Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Embedded Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Embedded Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Embedded Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Renesas Electronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 STMicroelectronics N.V.
- 18.4 Infineon Technologies
- 18.5 Texas Instruments Inc.
- 18.6 Qualcomm Incorporated
- 18.7 NXP Semiconductors
- 18.8 Microchip Technology Inc.
- 18.9 Analog Devices Inc.
- 18.10 Intel Corporation
- 18.11 Advanced Micro Devices, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

