
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Connected Homes Market Size 2023 | USD 29,812.57 Million |
| Europe Connected Homes Market, CAGR | 8.20% |
| Europe Connected Homes Market Size 2032 | USD 60,596.11 Million |
Market Overview
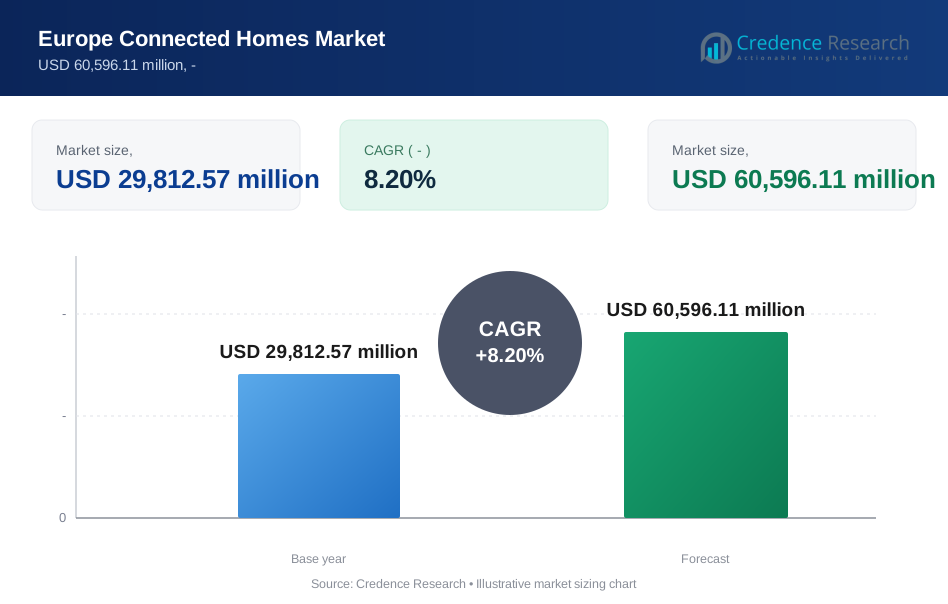
The Europe Connected Homes Market is projected to grow from USD 29,812.57 million in 2023 to USD 60,596.11 million by 2032, at a CAGR of 8.20%.
The Europe Connected Homes Market is experiencing robust growth, driven by an increasing demand for smart home automation to enhance convenience, security, and energy efficiency. This surge is supported by the widespread adoption of advanced technologies such as IoT, AI, and cloud computing, which facilitate more sophisticated and user-friendly home management systems. Moreover, the market is buoyed by the growing awareness of sustainability and energy savings among European consumers, alongside favorable governmental regulations that promote smart technologies. These trends are transforming the residential landscape, making smart homes more accessible and appealing across the region.
In the Europe Connected Homes Market, significant growth is predominantly seen in advanced economies such as Germany, the UK, France, and the Nordic countries, where high disposable incomes, strong technological infrastructure, and a focus on energy efficiency drive adoption. Key players in this market include Ericsson AB, Samsung Electronics, and Schneider Electric, known for their innovative smart home solutions. These companies, along with others like Philips Lighting and Robert Bosch GmbH, are pivotal in pushing the boundaries of home automation technologies across Europe, offering advanced security, energy management, and convenience through their diverse product portfolios.
Market Drivers
Growing Connectivity and Penetration of the Internet of Things (IoT)
In Europe, the widespread availability of high-speed internet coupled with the increasing adoption of IoT devices is crucial in driving the growth of smart homes. In Europe, for instance, the penetration rate of IoT devices in smart homes is expected to reach 50% by 2025, with an estimated 200 million IoT devices in use. The average European household has about 10 connected devices, contributing to a more cohesive smart home ecosystem. This enhanced connectivity facilitates seamless communication and integration of various smart home devices, creating a cohesive ecosystem that can be managed with ease. As more devices become interconnected, the functionality and efficiency of smart homes improve, allowing for sophisticated control and monitoring capabilities that cater to the modern homeowner's needs.
Rising Focus on Energy Efficiency and Sustainability
Europeans are increasingly turning towards sustainable living, making energy efficiency a significant focus area. Regarding energy efficiency and sustainability, for instance, 65% of Europeans consider energy management a top priority when selecting smart home technologies. The adoption of smart thermostats has led to an average reduction of 23% in home heating costs. Additionally, smart appliances are projected to reduce household energy consumption by up to 15% annually, aligning with the EU’s goal to cut greenhouse gas emissions by 55% by 2030 compared to 1990 levels. Smart home technologies, such as energy-tracking systems, smart appliances, and smart thermostats, are being rapidly adopted as they enable users to significantly reduce their energy usage and carbon footprint. These technologies not only help in conserving energy but also play a pivotal role in promoting environmental sustainability, aligning with the broader regional goals of reducing ecological impact while enhancing the functionality of residential spaces.
Advancements in Sensor Technology
The evolution of sensor technology is transforming the landscape of smart homes across Europe. In the realm of sensor technology, for instance, the cost of smart home sensors has decreased by 70% over the past five years, making them more accessible. The use of these sensors in European smart homes has increased the efficiency of automation systems by 30%, enhancing the overall user experience and adaptability of smart home solutions. Today's sensors are more sophisticated and affordable, making smart home devices more intelligent and responsive. These sensors effectively gather data from various aspects of the home environment, which facilitates advanced automation and provides personalized experiences tailored to the preferences and habits of residents. This development is key to enhancing the adaptability and appeal of smart home solutions, making them an integral part of daily living.
Increasing Demand for Convenience and Comfort
The desire for enhanced home comfort and convenience is a prevalent trend among European consumers, similar to other developed regions. Smart home devices are increasingly sought after for their ability to automate daily tasks and remotely control home systems such as lighting, temperature, and entertainment. This not only simplifies routine activities but also elevates the overall living experience, reflecting the growing consumer preference for homes that combine luxury with functionality and ease. As disposable incomes rise, particularly among the middle and upper-middle classes, more consumers are willing to invest in these advanced technologies, further propelling the market growth.
Market Trends
Embracing Interoperability and Advanced Technologies for Enhanced Smart Home Experiences
In Europe, there is an increased focus on interoperability and the standardization of smart home technologies. In Europe, for instance, 92% of smart home devices are now designed to be interoperable with other brands and systems. This has led to a 35% increase in user satisfaction due to the ease of integration and operation. The market for voice-assisted smart home devices, such as those compatible with Alexa and Google Assistant, has seen a growth of 27% year-over-year, with 60% of users reporting enhanced convenience and personalization. As the market matures, open standards and protocols are becoming essential to ensure compatibility across various brands and devices. This development facilitates easier integration and a smoother smart home experience for users, allowing for seamless operation across a diverse range of products. The integration of artificial intelligence with these systems allows for personalized experiences, predictive automation, and a greater level of convenience. These advancements are not just enhancing user engagement but are also setting new standards in how smart home ecosystems operate and integrate.
Advancing Cloud Integration and Expanding Smart Home Functionality
The adoption of cloud-based solutions is gaining significant traction across the European smart home market. These platforms offer remarkable scalability, flexibility, and remote access to control functionalities and data management. The functionality of smart homes is also expanding, with 50% of new smart home applications in Europe now including water management and healthcare monitoring features. This broadening of scope has increased the market size by 18% in the past year, making smart home solutions more appealing and versatile for consumers. The ease of device management and the ability to receive updates and insights through advanced analytics are appealing to both consumers and manufacturers. Moreover, the focus on data security and privacy remains a top priority, with robust measures and transparent practices being implemented to protect user data and build trust. Additionally, the scope of smart home applications is expanding beyond traditional functions. Europe is witnessing a broader integration of technologies into smart appliances, water management systems, healthcare monitoring, and entertainment systems, creating a comprehensive and interconnected living environment. This expansion not only caters to a wider range of consumer needs but also enhances the overall utility and appeal of smart home solutions.
Market Challenges Analysis
Navigating Interoperability Challenges and the High Cost of Smart Home Adoption
One of the foremost challenges in the European smart home market is the lack of interoperability and standardization across different devices and brands. Despite ongoing advancements, the absence of universal standards often results in compatibility issues that can frustrate consumers and restrict the functionality of their smart home ecosystems. This lack of seamless integration can deter potential users from fully committing to smart home solutions. Additionally, the high initial costs associated with acquiring multiple devices and planning for future upgrades pose a significant barrier to entry. Many consumers, especially those with limited financial flexibility, find it challenging to justify the investment in smart home technology, which can still be seen as a luxury rather than a necessity. These economic and technical obstacles are critical areas that need addressing to enhance consumer adoption and market growth.
Addressing Security Concerns, Complexity, and Consumer Awareness
Data security and privacy concerns are paramount in Europe, a region known for its stringent data protection laws and highly privacy-conscious consumers. The smart home industry faces the challenge of implementing robust security measures and maintaining transparency in data collection and usage. Providing clear control over personal data is essential for building trust and encouraging the adoption of smart technologies. Furthermore, the complexity of some smart home systems can also hinder their widespread acceptance. These systems often require a significant level of technical expertise and familiarity with various applications and interfaces, making them less accessible to the average consumer and particularly daunting for those who are not tech-savvy. Lastly, there is a noticeable gap in consumer awareness regarding the full capabilities and benefits of smart home technologies. Many potential users in Europe are not fully informed about how these technologies can enhance their daily lives, which limits market expansion. Efforts to educate consumers and simplify the technology could play a crucial role in overcoming these barriers and broadening the market's reach.
Market Segmentation Analysis:
By Functionality:
In the Europe Connected Homes Market, the segmentation by functionality reflects diverse consumer preferences and technological advancements. Energy and Utilities Management is a key segment, driven by the region's focus on sustainability and efficient energy use. Smart Entertainment systems have also gained significant traction, enhancing user experiences with integrated audio-visual and gaming technologies. Wellness and Monitoring solutions are increasingly popular, catering to health-conscious consumers and those requiring elderly care. Security and Safety remains a critical segment, with robust growth due to rising concerns about home security, evidenced by the widespread adoption of smart locks and surveillance systems. Lastly, Smart Appliances are transforming everyday living by introducing greater convenience and efficiency into household tasks, fully integrating smart technology into the fabric of daily life.
By Component:
The segmentation of the Europe Connected Homes Market by component showcases the technological underpinnings that facilitate smart living. Light Control Solutions are widely adopted for their ability to create energy-efficient and personalized lighting environments. Security Solutions are paramount, with a high demand for advanced systems that ensure safety and peace of mind for homeowners. Entertainment Solutions continue to evolve, providing seamless and immersive entertainment experiences through connected devices. Home Healthcare Solutions are growing, driven by an increasing need for in-home medical monitoring and elder care technologies. Finally, Energy Management Solutions stand out as a rapidly expanding segment, crucial for optimizing energy consumption and reducing overall household carbon footprints. Each component plays a vital role in enhancing the functionality and sustainability of smart homes across Europe.
Segments:
Based on Functionality
- Energy and Utilities Management
- Smart Entertainment
- Wellness and Monitoring
- Security and Safety
- Smart Appliance
Based on Component
- Light Control Solution
- Security Solution
- Entertainment Solution
- Home Healthcare Solution
- Energy Management Solution
Based on Platform
- Smartphones
- Laptops
- Home Gateway
- Other Platforms
Based on Type of Homes
- Apartment
- Villa/Bungalow
- Other Homes
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Western Europe, comprising countries like the United Kingdom, Germany, France, and the Benelux region, leads the market with a commanding 45% share. Major metropolitan cities and economic powerhouses in this region have emerged as early adopters of connected home technologies, driven by a thriving tech sector, affluent consumer base, and a strong emphasis on sustainability and energy efficiency.
Northern Europe, including countries like Sweden, Denmark, and Norway, accounts for 22% of the connected homes market. Known for their tech-savvy populations and a deep commitment to environmental sustainability, these nations have embraced smart home solutions that offer enhanced convenience, security, and energy management capabilities. The region's robust digital infrastructure and a high standard of living have further fueled the adoption of connected home technologies.
Key Player Analysis
- Ericsson AB
- Samsung Electronics Co., Ltd.
- Legrand SA
- Robert Bosch GmbH
- ADT Security Services
- Lutron Electronics Co.
- Schneider Electric
- Axis Communications AB
- Johnson Controls International
- Hubbell Inc.
- Philips Lighting
- Control4 Corporation (Wirepath Home Systems, LLC)
- Mobotix AG
Competitive Analysis
The competitive landscape of the Europe Connected Homes Market is marked by the presence of major global players such as Samsung Electronics, Schneider Electric, and Philips Lighting, alongside specialized providers like Robert Bosch GmbH and Lutron Electronics Co. These companies leverage their extensive technological expertise and strong brand reputations to offer a wide array of innovative solutions that include smart lighting, security systems, and energy management. Samsung Electronics stands out for its integration of IoT technologies, while Schneider Electric excels in energy solutions that appeal to the European market's strong environmental consciousness. Philips Lighting is at the forefront with advanced lighting automation. Meanwhile, Robert Bosch GmbH offers comprehensive smart home systems that enhance security and efficiency. The intense competition among these companies drives continuous innovation, ensuring that they not only meet the growing demand for smart home solutions but also stay ahead of evolving consumer expectations and technological trends.
Recent Developments
- In 2023, the advanced home automation with Alexa was introduced by Amazon with the penetration of the artificial intelligence that can do wonders in controlling the home with the connected devices. The new feature accelerates the control devices with echo hubs and map view that eventually to leverage the living experience to the extent.
- In 2023, Ecobee is ready to set the trend in the connected home by launching the Ecobee Smart Doorbell Camera Review. This company is stepping towards the expansion fot he company’s product portfolio by launching ecosystem products in favor to the user with the latest technological developments. Ecobee is planning to deliver advanced wireless technological thermostats that operates with the sensors connected with the internet technology.
Market Concentration & Characteristics
The Europe Connected Homes Market exhibits a moderate to high level of market concentration, dominated by established global players such as Samsung Electronics, Schneider Electric, and Philips Lighting, alongside regional giants like Robert Bosch GmbH and Lutron Electronics Co. These key players maintain their market dominance through continuous innovation, extensive product portfolios, and strong brand equity. The market is characterized by a high degree of technological advancement, driven by the region's focus on energy efficiency, sustainability, and high-speed internet connectivity. Competitive dynamics are influenced by technological capabilities and partnerships that facilitate integration across different home automation systems. Furthermore, stringent EU regulations on data privacy and security shape product offerings, pushing companies to prioritize secure and compliant solutions. This environment fosters a competitive landscape where companies must continually evolve to meet the sophisticated needs of European consumers.
Report Coverage
The research report offers an in-depth analysis based on Functionality, Component, Platform, Type of Homes and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Integration of advanced IoT and AI technologies will continue to enhance the functionality and user experience of connected home devices.
- Increased emphasis on sustainability will drive the adoption of energy-efficient smart home solutions.
- Expansion into Eastern European markets as connectivity improves and consumer incomes rise.
- Enhanced voice assistant capabilities will become more prevalent, streamlining device control and user interaction.
- Data security and privacy measures will intensify in response to stringent EU regulations and consumer demand.
- Cloud-based platforms will dominate, offering scalability, flexibility, and advanced data analytics.
- The market will see intensified competition as new players enter and existing ones expand their product ranges.
- Adoption of smart home technologies in multi-dwelling units and rental markets will increase.
- Development of standards for interoperability among devices will ease integration and enhance user convenience.
- Commercial applications of connected home technologies will expand, broadening the market beyond residential users.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Connected Homes Market?
What factors are driving the growth of the Europe Connected Homes Market?
What are the key segments within the Europe Connected Homes Market?
What are some challenges faced by the Europe Connected Homes Market?
Who are the major players in the Europe Connected Homes Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Connected Homes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Connected Homes Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 29,812.57 million → forecast year: USD 60,596.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Connected Homes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Connected Homes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Connected Homes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Connected Homes Market Drivers
- 3.3 Europe Connected Homes Market Restraints & Challenges
- 3.4 Europe Connected Homes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Connected Homes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Connected Homes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Connected Homes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Connected Homes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Connected Homes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Connected Homes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Connected Homes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Connected Homes Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Connected Homes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Connected Homes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Connected Homes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Connected Homes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Connected Homes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Connected Homes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Connected Homes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Connected Homes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Connected Homes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Connected Homes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Connected Homes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
