
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
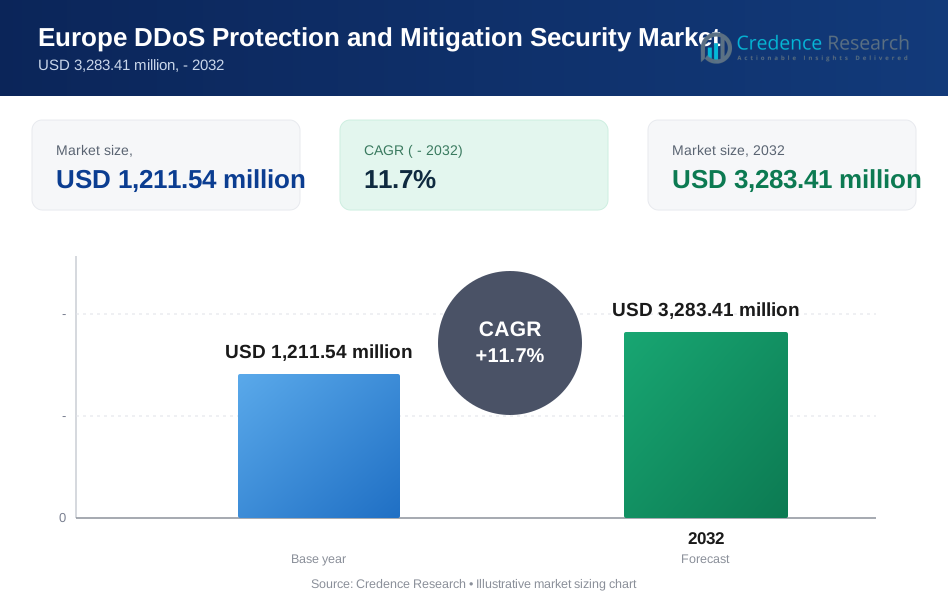
| Europe DDoS Protection & Mitigation Security Market Size 2023 | USD 1,211.54 Million |
| Europe DDoS Protection & Mitigation Security Market, CAGR | 11.7% |
| Europe DDoS Protection & Mitigation Security Market Size 2032 | USD 3,283.41 Million |
Market Overview
The Europe DDoS Protection & Mitigation Security Market is projected to grow from USD 1,211.54 million in 2023 to an estimated USD 3,283.41 million by 2032, with a compound annual growth rate (CAGR) of 11.7% from 2024 to 2032. The rising frequency and sophistication of Distributed Denial-of-Service (DDoS) attacks, along with the increasing adoption of cloud-based services, are key factors driving market growth.
Market drivers include the rapid increase in cyberattacks targeting critical infrastructure and businesses, pushing organizations to invest in mitigation solutions. The integration of AI and machine learning in DDoS protection services is also becoming a significant trend, as it allows for faster detection and response. The growing reliance on cloud computing and IoT devices, along with stringent regulatory requirements, fuels the need for scalable and efficient DDoS mitigation strategies across industries.
Geographically, Europe is witnessing a significant demand for DDoS protection, driven by increasing awareness of cyber threats and high adoption rates of cybersecurity solutions across key industries like finance, healthcare, and government. Major players in the Europe DDoS Protection & Mitigation Security Market include Akamai Technologies, Cloudflare, Inc., Imperva, and F5 Networks, among others, who continue to innovate and provide advanced solutions to safeguard against evolving cyber threats.
Market Insights
- The Europe DDoS Protection & Mitigation Security Market is projected to grow from USD 1,211.54 million in 2023 to USD 3,283.41 million by 2032, with a CAGR of 11.7%.
- Increasing frequency and sophistication of DDoS attacks targeting businesses and critical infrastructure are driving the demand for advanced mitigation solutions.
- The rapid adoption of cloud-based services and IoT devices is significantly contributing to the demand for scalable and efficient DDoS protection technologies.
- The integration of AI and machine learning in DDoS protection services is a key trend, enhancing the speed and accuracy of threat detection and response.
- Stricter data privacy and cybersecurity regulations, such as GDPR, are pushing businesses to invest in comprehensive DDoS protection solutions to ensure compliance.
- Western Europe leads the market, with countries like the UK, Germany, and France driving demand due to high digitalization and cybersecurity awareness.
- High costs of advanced DDoS mitigation solutions and the complexity of integrating them into existing infrastructure can be a barrier for smaller enterprises and SMEs.
Segments
Based on Component
- Hardware
- Software
- Services
Based on Deployment Type
- On-premise
- Cloud-based
Based on Software Type
- Network Traffic Analyzers
- Threat Mitigation Systems
- Botnet Detection & Management software
- Others
Based on End-User
- BFSI (Banking, Financial Services, and Insurance)
- Government & Defense entities
- IT & Telecom sectors
- Manufacturing
- Others
Based on Enterprise Size
- Large Enterprises
- SMEs
Key players
- Akamai Technologies
- BT Group
- Corero
- DDoS-Guard
- Huawei
- Link11 GmbH
- Radware Inc.
- NetScout Systems, Inc.
- Fortinet
- Nexusguard
- Imperva
- Cloudflare, Inc.
- Fastly Inc.
- F5
Competitive Analysis
The Europe DDoS Protection & Mitigation Security Market is highly competitive, with several key players offering advanced solutions to address the growing threat of DDoS attacks. Companies like Akamai Technologies, Cloudflare, and Radware lead the market due to their comprehensive, scalable, and cloud-based DDoS protection solutions that offer real-time traffic analysis, mitigation, and monitoring. These players have a strong presence across multiple industries, including finance, telecommunications, and government. In contrast, companies like BT Group and Fortinet focus on integrated security solutions that combine DDoS protection with broader network security services. Smaller players, such as Corero and Link11 GmbH, differentiate themselves with specialized solutions for specific market segments. Huawei and Nexusguard are expanding their market share through robust global network infrastructures and tailored mitigation services. Competitive strategies include offering managed services, incorporating AI and machine learning, and maintaining compliance with regulatory standards.
Recent Developments
- In October 2024, Akamai successfully mitigated one of the largest DDoS attacks targeting a financial services institution in EMEA. The attack peaked at 1.48 Tbps and 125 million packets per second, with over 60% of the malicious traffic neutralized by Akamai's Prolexic cloud scrubbing centers located in major European cities. This demonstrated Akamai's ability to protect critical infrastructure using advanced machine intelligence and localized mitigation strategies.
- In Q4 2024, Corero secured a major equipment upgrade commitment from a long-term European government client and expanded its partnerships with organizations in cloud services, telecommunications, and aerospace sectors. These developments highlight Corero's growing presence in Europe, supported by its SmartWall ONE DDoS protection solutions that deliver automated detection and mitigation capabilities.
- In October 2024, Link11 mitigated Europe's largest recorded DDoS attack, which peaked at 1.4 Tbps. The attack was neutralized using Link11's fully automated DDoS protection platform, ensuring zero impact on customer services and demonstrating the platform's advanced capabilities in handling high-volume attacks.
- In January 2025, Radware deployed its AI-powered DefensePro X system at TelemaxX Telekommunikation’s German data centers to address a 265% surge in web-based DDoS attacks. The system leverages AI algorithms to combat sophisticated threats such as IoT-based attacks and ransom campaigns, aligning with Europe's growing demand for AI-driven cybersecurity solutions.
- In December 2024, NETSCOUT enhanced its Adaptive DDoS Protection solution with AI/ML-driven updates to its Arbor Edge Defense (AED) and Arbor Enterprise Manager (AEM) products. These updates provide real-time protection against evolving threats across hybrid IT environments, including on-premise and cloud platforms.
- During Q1 2024, Cloudflare mitigated over 4.5 million DDoS attacks globally, with Europe seeing a significant share of these incidents. The company’s automated defenses handled more than 59 petabytes of malicious traffic on the network layer, showcasing its robust capability to protect against high-frequency attacks.
Market Concentration and Characteristics
The Europe DDoS Protection & Mitigation Security Market is moderately concentrated, with a few dominant players leading the market, such as Akamai Technologies, Cloudflare, Radware, and Imperva. These companies hold a significant share due to their comprehensive, scalable solutions and strong reputations in the cybersecurity space. However, the market also features a range of smaller players, such as Corero and Link11 GmbH, that cater to specific niches or regions, providing specialized services. The competitive landscape is characterized by innovation, with many players integrating advanced technologies like AI, machine learning, and real-time traffic analysis to enhance their offerings. There is also a clear trend towards cloud-based solutions, as businesses seek flexibility, scalability, and cost-efficiency. Regulatory compliance and the increasing frequency of cyberattacks continue to drive market growth, prompting both large and smaller companies to innovate and adapt to changing security needs.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Type, Software Type, End-User, Enterprise Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As businesses continue migrating to cloud environments, the demand for scalable, cloud-based DDoS protection solutions is expected to rise. Cloud providers will likely expand their DDoS mitigation services to cater to this growing need.
- AI and ML technologies will play a critical role in enhancing the speed and accuracy of DDoS attack detection and mitigation. These technologies will allow for automated, adaptive responses to emerging threats in real-time.
- As attackers evolve their methods, the complexity and scale of DDoS attacks will increase, creating a constant need for more advanced and effective mitigation solutions. Protection systems will need to stay ahead of increasingly sophisticated attack vectors.
- The demand for managed security services (MSSPs) will continue to grow as businesses, especially SMEs, prefer outsourcing DDoS protection. MSSPs provide cost-effective, 24/7 monitoring and incident response for DDoS threats.
- Regulatory frameworks like GDPR will continue to push businesses toward adopting comprehensive DDoS protection solutions to comply with data privacy and cybersecurity requirements. Non-compliance could lead to penalties, prompting increased investments in security.
- The proliferation of IoT devices will expand the attack surface for DDoS threats. Organizations will focus on enhancing DDoS protection for connected devices and networks to mitigate vulnerabilities posed by these technologies.
- Hybrid DDoS protection solutions, combining both on-premise and cloud-based defense, will gain traction. These solutions offer more flexibility, customization, and efficiency in mitigating large-scale attacks across various digital environments.
- Real-time traffic analysis and monitoring will be a critical component of future DDoS protection systems. By identifying and responding to threats immediately, businesses can reduce the impact and downtime caused by attacks.
- As the frequency and severity of DDoS attacks rise, businesses will allocate more resources toward cybersecurity budgets. This will drive growth in the DDoS protection market as organizations invest in both prevention and mitigation technologies.
- Increased collaboration between private companies, government agencies, and cybersecurity firms will foster innovation and collective defense strategies. Industry alliances will enhance the sharing of threat intelligence to combat the growing DDoS threat landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe DDoS Protection & Mitigation Security Market in 2023 and 2032?
What factors are driving the growth of the DDoS Protection & Mitigation Security Market in Europe?
How does AI and machine learning influence DDoS protection services?
Which industries are most affected by DDoS attacks in Europe?
Who are the major players in the Europe DDoS Protection & Mitigation Security Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe DDoS Protection and Mitigation Security Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe DDoS Protection and Mitigation Security Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 1,211.54 million → 2032: USD 3,283.41 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe DDoS Protection and Mitigation Security Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe DDoS Protection and Mitigation Security Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe DDoS Protection and Mitigation Security Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe DDoS Protection and Mitigation Security Market Drivers
- 3.3 Europe DDoS Protection and Mitigation Security Market Restraints & Challenges
- 3.4 Europe DDoS Protection and Mitigation Security Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe DDoS Protection and Mitigation Security Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe DDoS Protection and Mitigation Security Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe DDoS Protection and Mitigation Security category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe DDoS Protection and Mitigation Security Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe DDoS Protection and Mitigation Security Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe DDoS Protection and Mitigation Security market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe DDoS Protection and Mitigation Security Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe DDoS Protection and Mitigation Security Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe DDoS Protection and Mitigation Security Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe DDoS Protection and Mitigation Security (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe DDoS Protection and Mitigation Security Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe DDoS Protection and Mitigation Security Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe DDoS Protection and Mitigation Security Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe DDoS Protection and Mitigation Security Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe DDoS Protection and Mitigation Security Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe DDoS Protection and Mitigation Security Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe DDoS Protection and Mitigation Security Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe DDoS Protection and Mitigation Security Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe DDoS Protection and Mitigation Security Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
