
Market Overview
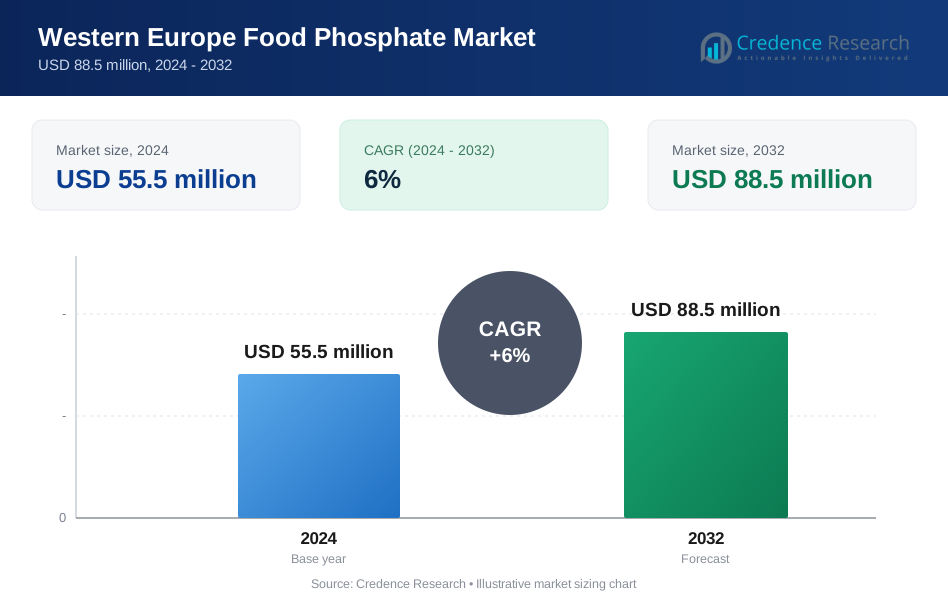
Western Europe Food Phosphate Market size was valued at USD 55.5 million in 2024 and is anticipated to reach USD 88.5 million by 2032, at a CAGR of 6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Western Europe Food Phosphate Market Size 2024 | USD 55.5 million |
| Western Europe Food Phosphate Market, CAGR | 6% |
| Western Europe Food Phosphate Market Size 2032 | USD 88.5 million |
The Western Europe Food Phosphate Market grows on rising demand for processed, ready-to-eat, and frozen meat, poultry, and seafood products. It is driven by the need to enhance product texture, water retention, and shelf life while maintaining food safety standards. Manufacturers adopt advanced phosphate formulations and customized blends to meet evolving consumer preferences for high-quality, convenient foods. Trends include increased use of blended phosphates, focus on regulatory compliance, and integration of sustainable and cost-efficient production methods. Growing export demand and technological innovation in phosphate applications further support market expansion and long-term growth prospects.
The Western Europe Food Phosphate Market is concentrated in Germany, France, Italy, Spain, and the Benelux region, where demand is driven by advanced meat, poultry, and seafood processing industries. Northern Europe and export-oriented markets also contribute significantly. Key players focus on high-purity phosphate formulations, technical support, and supply chain efficiency to strengthen regional presence. Companies emphasize regulatory compliance, product reliability, and customized solutions to capture market share and meet the evolving needs of both domestic and international food processors.

Market Insights
- The Western Europe Food Phosphate Market size was valued at USD 55.5 million in 2024 and is anticipated to reach USD 88.5 million by 2032, growing at a CAGR of 6% during the forecast period.
- Rising demand for processed, ready-to-eat, and frozen meat, poultry, and seafood products drives market growth.
- Manufacturers focus on enhancing product texture, water retention, and shelf life while meeting food safety standards.
- Increased use of blended phosphates and adoption of advanced, customized formulations reflect current market trends.
- The market is moderately concentrated, with companies competing through high-purity products, technical support, and supply chain efficiency.
- Regulatory compliance, production costs, and strict quality standards act as restraints, influencing adoption and pricing.
- Germany, France, Italy, Spain, and the Benelux region dominate the market, supported by export-oriented operations and advanced food processing industries.
Market Drivers
Rising Demand for Processed and Packaged Foods Driving Phosphate Utilization
The Western Europe Food Phosphate Market grows steadily on the back of consumer preference for processed, ready-to-eat, and packaged foods. Phosphates serve critical functions as emulsifiers, stabilizers, and leavening agents, improving texture and extending shelf life. Food producers rely on these additives to maintain consistent quality across large-scale production. It supports bakery products, dairy, and meat processing where uniformity is vital. The demand for convenience and fast meal solutions strengthens phosphate integration into product formulations. This dynamic secures a strong base for continued market relevance.
- For instance, ICL Group, a major player in the region's industrial phosphate sector, delivered approximately 0.063 million tonnes. This highlights their significant role in the industry and the scale of their operations.
Expanding Meat and Seafood Processing Industry Enhancing Phosphate Applications
Rising meat and seafood consumption across Western Europe encourages broader phosphate usage in preservation and moisture retention. Phosphates improve water-holding capacity and maintain tenderness in processed meats. Seafood processors employ them to preserve freshness during storage and distribution. It helps reduce product waste by extending usability and improving overall product appeal. The preference for value-added products such as marinated and processed cuts sustains this application. Strong consumer trust in product safety further accelerates phosphate adoption in protein-based industries.
- For instance, ICL Group Ltd. recently reported delivering 40,000 tonnes of food-grade phosphoric acid to meat and poultry processors in Western Europe.
Technological Advancements in Food Formulation Boosting Adoption
Innovations in food technology strengthen phosphate applications in diverse product categories. Modern formulations enhance solubility and reduce sodium levels to meet health standards. It allows producers to balance functionality with nutritional requirements. Enhanced performance in low-fat dairy, fortified beverages, and plant-based alternatives widens phosphate utilization. Producers benefit from solutions that deliver consistent quality under stringent EU regulations. The emphasis on advanced formulations aligns with consumer health awareness and industry standards.
Stringent Food Safety Regulations Supporting Consistent Market Demand
Regulatory compliance remains a strong driver in the Western Europe Food Phosphate Market, where food safety standards shape product development. Phosphates approved by European Food Safety Authority (EFSA) hold a critical role in ensuring consumer protection. It provides manufacturers with reliable functional ingredients backed by regulatory acceptance. Clear guidelines and regular reviews strengthen confidence in phosphate applications. Compliance with sustainability and clean-label demands further integrates phosphates into evolving food systems. The assurance of safety, stability, and regulatory backing ensures their continued importance in Western European food production.
Market Trends
Growing Preference for Clean-Label and Low-Sodium Food Products
The Western Europe Food Phosphate Market adapts to evolving consumer preferences for healthier and cleaner food labels. Manufacturers reduce sodium-based phosphates and develop alternatives that align with dietary recommendations. It encourages greater focus on transparency in ingredient labeling. Clean-label reformulation trends push companies to create phosphate blends with natural positioning. Consumers demand functional ingredients that improve food quality without compromising health. This shift reshapes industry strategies and product innovation.
- For instance, ICL Group Ltd., a global leader in food additives, reported delivering 63,000 tonnes of food-grade multi‑blend phosphate salts in its most recent period.
Expansion of Plant-Based and Dairy Alternative Applications
Rising demand for plant-based foods drives new applications for phosphates in dairy and meat substitutes. Phosphates enhance texture, stability, and nutrient fortification in plant-based formulations. It helps producers deliver consistent taste and performance in rapidly growing vegan and flexitarian segments. Plant-based cheese and beverages particularly benefit from improved meltability and mineral balance. The expansion of this category reflects consumer interest in sustainable and healthier food options. Strong growth in this sector widens phosphate usage in non-traditional areas.
- For instance, ICL Group Ltd., active in the alternative‑protein arena, opened a 10,000 square‑foot alternative‑protein production facility.
Increased Focus on Sustainable Production and Circular Economy Practices
Sustainability emerges as a core trend influencing phosphate production and sourcing. Producers adopt energy-efficient processes and explore recovery methods to minimize environmental impact. It aligns with regional policies that promote circular economy models. Companies strengthen supply chains by integrating waste reduction and eco-friendly packaging initiatives. The focus on sustainability appeals to environmentally conscious consumers and regulators. This trend creates long-term opportunities for competitive differentiation in the market.
Advancements in Functional Food and Nutraceutical Integration
The Western Europe Food Phosphate Market gains momentum from the expansion of functional foods and nutraceuticals. Phosphates support mineral fortification and enhance nutritional profiles in specialized products. It enables manufacturers to cater to growing demand for bone health, energy metabolism, and performance-related benefits. Functional beverages, fortified snacks, and dietary supplements rely on phosphate-based solutions. Rising health awareness among European consumers strengthens this integration. The convergence of nutrition and functionality positions phosphates as vital ingredients in next-generation food systems.
Market Challenges Analysis
Regulatory Pressure and Health Concerns Limiting Phosphate Usage
The Western Europe Food Phosphate Market faces challenges from strict regulations and rising health concerns regarding phosphate intake. The European Food Safety Authority (EFSA) continues to review acceptable daily intake levels, raising pressure on manufacturers to reduce phosphate content in processed foods. It restricts flexibility in product formulation and compels companies to invest in reformulation strategies. Consumers associate excessive phosphate consumption with cardiovascular and kidney health risks, fueling negative perceptions. Growing demand for natural alternatives adds further complexity to market positioning. Regulatory constraints, coupled with consumer awareness, place direct limits on the widespread use of phosphates in food processing.
Intense Competition and Supply Chain Vulnerabilities Affecting Stability
The market also struggles with supply chain disruptions and competition from alternative ingredients. Phosphate production depends heavily on raw material availability, and geopolitical factors often impact sourcing costs. It increases volatility in pricing and challenges long-term supplier agreements. Manufacturers encounter rising competition from natural stabilizers and clean-label solutions that appeal strongly to health-conscious consumers. Pressure to maintain cost efficiency while meeting strict standards intensifies the operational burden. Fluctuating supply conditions and competition from substitutes create ongoing uncertainty, hindering growth and profitability in the sector.
Market Opportunities
Rising Demand for Convenience Foods and Value-Added Products Creating Growth Opportunities
The Western Europe Food Phosphate Market benefits from increasing consumer demand for convenience and ready-to-eat products. Phosphates enhance texture, stability, and shelf life in processed meats, dairy, and bakery items. It allows manufacturers to maintain consistent quality across large-scale production. Growing urbanization and busier lifestyles strengthen the adoption of pre-packaged meals and meal kits. Companies can leverage phosphate functionality to innovate new product lines and meet evolving taste and convenience expectations. Expansion in frozen and chilled food segments further drives potential market uptake.
Expansion in Plant-Based and Functional Food Segments Offering Strategic Potential
The shift toward plant-based diets and functional foods creates significant opportunities for phosphate applications. Phosphates support mineral fortification, improve texture, and enhance nutrient retention in vegan and fortified products. It enables producers to deliver high-quality alternatives that meet health-conscious consumer demands. Rising awareness of bone health, protein supplementation, and fortified beverages strengthens adoption in nutraceutical-oriented foods. Innovation in plant-based cheese, meat substitutes, and dairy alternatives opens new revenue streams. Companies investing in R&D to optimize phosphate formulations for these applications can gain a competitive advantage.
Market Segmentation Analysis:
By Product:
The Western Europe Food Phosphate Market segments by product into sodium phosphate, potassium phosphate, calcium phosphate, phosphoric acid, ammonium phosphate, and blended phosphates. Sodium phosphate dominates due to its extensive use in meat processing, bakery, and dairy applications. It improves water retention, texture, and shelf stability, ensuring consistent quality in large-scale production. Potassium phosphate gains traction in low-sodium formulations, providing functionality while meeting health-conscious consumer demand. Calcium phosphate acts as both a stabilizer and a fortifying agent, especially in dairy and plant-based products. Phosphoric acid regulates pH and enhances mineral content in beverages and processed foods. Blended phosphates allow manufacturers to optimize texture, emulsification, and preservation across complex formulations, while ammonium phosphate serves niche uses in specialty processes requiring controlled leavening or stabilization. Each product type addresses specific functional needs, offering food producers flexibility in quality maintenance.
- For instance, Yara Phosphates Holland (YPH) (part of Yara International), has been operating an additional food‑grade phosphoric acid plant since 2021, with a production capacity of 70,000 tonnes of qualified commercial food‑grade phosphoric acid annually.
By Application:
The market also segments by application, focusing on meat and poultry products and seafood products. Meat and poultry segments consume a major share due to high phosphate use for moisture retention, texture enhancement, and extended shelf life. It enables consistent production of processed cuts, marinated items, and ready-to-cook meals. Seafood products benefit from phosphate addition to preserve freshness, maintain water-holding capacity, and retain structural integrity during storage and transport. It supports high-quality output in chilled, frozen, and processed seafood segments. Phosphates reduce product loss and preserve organoleptic properties, which are critical for consumer acceptance. Rising demand for convenience protein products, ready-to-eat meals, and processed seafood further drives phosphate adoption across the region, emphasizing its strategic role in operational efficiency and product quality.
- For instance, Prayon S.A., headquartered in Belgium, reported an annual production capacity of 0.25 million tonnes of phosphate salts, of which a significant portion is dedicated to food-grade sodium and potassium phosphates widely used in Western European meat and poultry processing
Segments:
Based on Product Type:
- Sodium Phosphate
- Potassium Phosphate
- Calcium Phosphate
- Phosphoric Acid
- Ammonium Phosphate
- Blended Phosphates
Based on Application:
- Meat and Poultry Products
- Seafood Products
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounts for approximately 5% of the Western Europe Food Phosphate Market through imports of European-processed foods and collaborative ventures. The region’s food industry, including meat, poultry, and seafood processing, increasingly sources high-purity phosphates from Europe to ensure product consistency and regulatory compliance. For instance, Tyson Foods imports sodium phosphate from Germany to enhance water retention and texture in processed meats, resulting in improved cooking yields by 10–12%. Strong cold chain infrastructure and adherence to strict food additive regulations support sustained demand for European food phosphates in North American processing facilities.
Europe
Europe dominates the Western Europe Food Phosphate Market, contributing around 60% of the share, with Germany, France, Italy, Spain, and Benelux as major contributors. Germany leads the regional market due to its advanced meat and poultry processing industry. For instance, Südzucker AG employs calcium and sodium phosphate blends in emulsified meat products, increasing moisture retention by over 12%. France represents a significant share with Groupe Bigard utilizing potassium phosphate in processed meats to enhance juiciness and yield. Italy’s Ferrarini S.p.A. integrates blended phosphates in cured meats to improve sliceability and texture. Spain focuses on seafood processing, with Grupo Calvo applying phosphates in canned seafood, reducing drip loss by 8% and improving overall product quality. The Benelux region maintains steady phosphate demand in processed meats and ready-to-eat foods through companies like Vion Food Group, which enhances tenderness and water-holding capacity using phosphate blends.
Asia-Pacific
Asia-Pacific contributes roughly 15% of the market, primarily through import of Western-style processed foods and collaboration with European manufacturers. Rising consumption of convenience foods and processed meats in countries such as China, Japan, and Australia drives phosphate usage. For instance, Nippon Meat Packers in Japan incorporates calcium phosphate imported from Europe to improve water-holding capacity in meat products, enhancing texture and cooking stability. Strategic partnerships with European food producers facilitate technology transfer and adoption of high-quality phosphate applications, ensuring product consistency for local and export markets.
Latin America
Latin America holds about 12% of the market, supported by meat and poultry exports and domestic processed food production. JBS S.A. in Brazil applies sodium phosphate in processed meats to improve water retention and reduce weight loss during storage and transport. European quality standards influence regional adoption, ensuring exported products meet Western Europe’s food safety and performance benchmarks. Growing demand for packaged and ready-to-eat meals also sustains phosphate consumption.
Middle East & Africa
The Middle East and Africa collectively account for 8% of the Western Europe Food Phosphate Market. The region relies on European food phosphate imports for processed meat, poultry, and seafood products, particularly for the hospitality and export segments. Al Kabeer Group in the UAE utilizes phosphates in frozen seafood processing to maintain texture and shelf life, ensuring product stability for both regional and European distribution. Investment in cold chain logistics and growing consumer preference for high-quality processed foods supports consistent market growth.
Key Player Analysis
- Hawkins Inc.
- Sulux Phosphates Ltd.
- Arkema Group
- Prayon
- Aditya Birla Chemicals
- ICL Specialty Products Inc
- Sichuan ZhituoBiochem Technology
- Univar, Inc.
- Merck KGaA
- Fosfa A.S
Competitive Analysis
The Western Europe Food Phosphate Market key players including ICL Specialty Products Inc, Fosfa A.S, Prayon, Arkema Group, Merck KGaA, Univar, Inc., Sulux Phosphates Ltd., Aditya Birla Chemicals, Hawkins Inc., and Sichuan ZhituoBiochem Technology. The Western Europe Food Phosphate Market remains highly competitive, driven by continuous innovation, stringent regulatory compliance, and growing demand for high-quality processed foods. Market participants focus on developing advanced phosphate formulations, including sodium, calcium, potassium, and blended variants, to enhance water retention, texture, and shelf life in meat, poultry, and seafood products. Companies invest heavily in research and development to create solutions that meet evolving consumer expectations, such as improved product tenderness, juiciness, and stability during storage and transport. Distribution efficiency and technical support play a crucial role, with manufacturers providing guidance to ensure optimal application in diverse food matrices. Market competition also intensifies through strategic partnerships, mergers, and regional expansions, allowing producers to strengthen their presence across key Western European markets. Sustainability and cost-effectiveness increasingly influence competitive strategies, with manufacturers exploring eco-friendly production methods and optimized phosphate blends to reduce operational costs while maintaining quality. The dynamic landscape is characterized by a focus on premium product quality, regulatory adherence, and technological advancements, enabling companies to differentiate their offerings, capture new market segments, and maintain long-term growth in the region’s evolving processed food sector.
Recent Developments
- In October 2024, NutriScience Innovations, LLC, a leading North American supplier and developer of science-backed ingredient solutions, announced its acquisition of XSTO Solutions, LLC.
- In September 2024, Prayon, a global leader in phosphorus chemistry, announced the successful acquisition of Natural Enrichment Industries (NEI), a U.S.-based producer of tricalcium phosphate (TCP).
- In March 2024, EuroChem launched a phosphate fertilizer production facility in Serra do Salitre, Minas Gerais, Brazil. The new facility, which includes a phosphate mine and processing plant, has an annual production capacity of 1 million tons of advanced phosphate fertilizers.
- In January 2023, the specialty minerals firm ICL Group Ltd. entered partnership as the exclusive supplier of specialty phosphate solutions for General Mills, Inc. As per the collaboration.
Market Concentration & Characteristics
The Western Europe Food Phosphate Market exhibits a moderately concentrated structure, dominated by a mix of multinational manufacturers and regional suppliers. It is characterized by high product standardization and stringent regulatory compliance, with participants focusing on quality, purity, and performance of sodium, calcium, and blended phosphates for meat, poultry, and seafood applications. Market players differentiate through technical support, customized formulations, and reliable supply chains to meet diverse processing requirements. Demand stability is influenced by the mature food processing industry and consistent consumption of processed and convenience foods. Supply chain efficiency and adherence to European food safety regulations define competitive positioning. It demonstrates steady growth in premium and export-oriented segments, with processors prioritizing additives that enhance product texture, water retention, and shelf life. Barriers to entry include regulatory certification, production expertise, and distribution networks. The market responds quickly to shifts in consumer preferences, innovation in processed food products, and advancements in phosphate applications. Strategic partnerships, research-driven formulation improvements, and regional distribution capabilities reinforce market presence, allowing companies to maintain operational efficiency and meet stringent quality standards. The market environment emphasizes technological competence, product reliability, and regulatory alignment, creating a landscape where consistent performance and compliance dictate competitiveness and long-term sustainability.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for phosphates in meat, poultry, and seafood products will grow steadily.
- Manufacturers will focus on high-purity and customized phosphate formulations.
- Adoption of processed and ready-to-eat foods will drive consistent phosphate consumption.
- Regulatory compliance and food safety standards will remain key market drivers.
- Producers will invest in research to enhance water retention and product texture.
- Export-oriented segments will expand, increasing demand for standardized phosphate solutions.
- Companies will strengthen supply chain efficiency to ensure timely delivery.
- Sustainability and cost-effective production methods will influence product development.
- Technological advancements in phosphate applications will support product innovation.
- Strategic partnerships and regional collaborations will reinforce market presence and competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Western Europe Food Phosphate Market, and what is itsprojected size in 2032?
At what Compound Annual Growth Rate is the Western Europe Food Phosphate Market projected to grow between 2025 and 2032?
Which Western Europe Food Phosphate Market segment held the largest share in 2024?
Who are the leading companies in the Western Europe Food Phosphate Market
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Western Europe Food Phosphate Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Western Europe Food Phosphate Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 55.5 million → 2032: USD 88.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Western Europe Food Phosphate Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Western Europe Food Phosphate Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Western Europe Food Phosphate Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Western Europe Food Phosphate Market Drivers
- 3.3 Western Europe Food Phosphate Market Restraints & Challenges
- 3.4 Western Europe Food Phosphate Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Western Europe Food Phosphate Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Western Europe Food Phosphate Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Western Europe Food Phosphate category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Western Europe Food Phosphate Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Western Europe Food Phosphate Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Western Europe Food Phosphate market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Western Europe Food Phosphate Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Western Europe Food Phosphate Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Western Europe Food Phosphate Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Western Europe Food Phosphate (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Western Europe Food Phosphate Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Western Europe Food Phosphate Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Western Europe Food Phosphate Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Western Europe Food Phosphate Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Western Europe Food Phosphate Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Western Europe Food Phosphate Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Western Europe Food Phosphate Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Western Europe Food Phosphate Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Western Europe Food Phosphate Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
