
Market Overview:
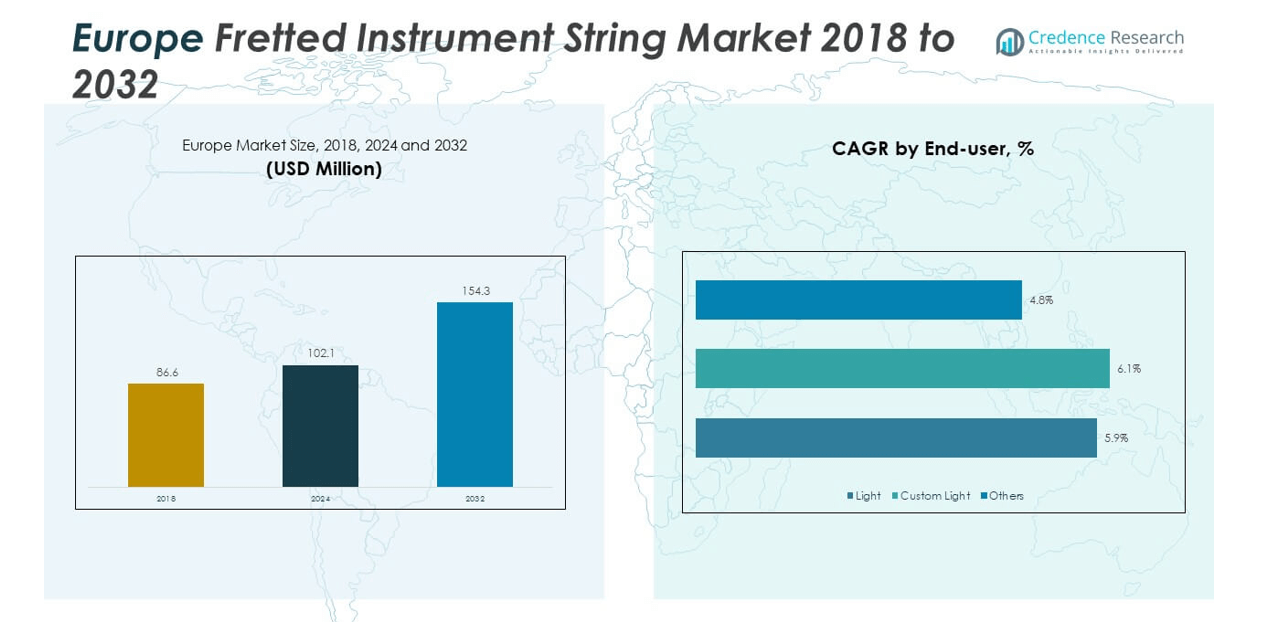
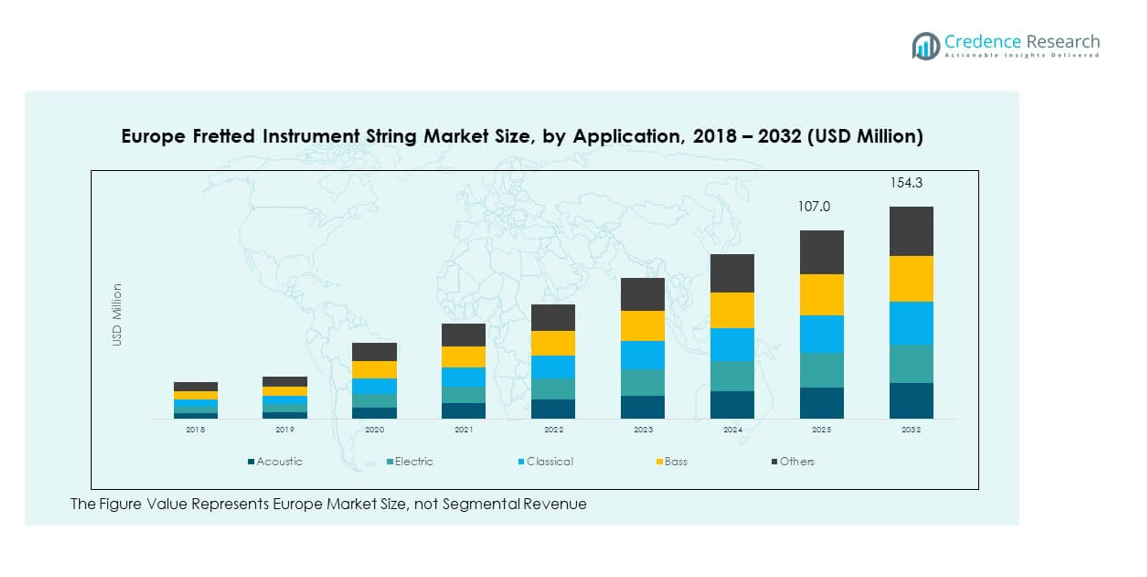
The Europe Fretted Instrument String Market size was valued at USD 86.6 million in 2018 to USD 102.1 million in 2024 and is anticipated to reach USD 154.3 million by 2032, at a CAGR of 5.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Fretted Instrument String Market Size 2024 | USD 102.1 million |
| Europe Fretted Instrument String Market, CAGR | 5.40% |
| Europe Fretted Instrument String Market Size 2032 | USD 154.3 million |
The market growth is driven by rising consumer interest in music education, expanding live music and festival culture, and the growing influence of online platforms promoting both traditional and modern string instruments. Increasing demand for premium and coated strings, favored for their durability and tonal consistency, further accelerates adoption. Additionally, manufacturers are focusing on innovative materials and customization to meet the preferences of both professional musicians and hobbyists. The e-commerce boom has also boosted accessibility, making strings more widely available across diverse consumer segments.
Geographically, Western Europe remains the dominant market, with countries such as Germany, France, and the United Kingdom leading due to strong cultural traditions in classical and contemporary music. Southern European countries like Spain and Italy also contribute significantly, supported by their deep-rooted guitar and mandolin culture. Meanwhile, Eastern Europe is emerging as a growth market, fueled by increasing disposable incomes and expanding music education programs. This regional diversity highlights both mature and expanding opportunities within the European fretted instrument string landscape.
Market Insights:
- The Europe Fretted Instrument String Market was valued at USD 102.1 million in 2024 and is projected to reach USD 154.3 million by 2032, growing at a CAGR of 5.40% during the forecast period.
- The Global Fretted Instrument String Market size was valued at USD 342.1 million in 2018 to USD 420.0 million in 2024 and is anticipated to reach USD 674.1 million by 2032, at a CAGR of 6.1% during the forecast period.
- Strong demand from music education programs and conservatories supports consistent adoption, especially for acoustic and classical string categories.
- Rising popularity of live music events and festivals fuels frequent string replacement, boosting demand among professionals and hobbyists.
- Price sensitivity among casual players and the influx of low-cost imports challenge the growth of premium and innovative string products.
- Supply chain disruptions and uneven distribution networks across emerging European countries create hurdles for consistent market penetration.
- Western Europe leads the market with 42% share, driven by Germany, the United Kingdom, and France, while Southern Europe accounts for 28% due to strong guitar traditions.
- Eastern and Northern Europe together hold 30% market share, with growing contributions from Russia, Poland, and Nordic countries supported by rising disposable incomes and expanding music education programs.
Market Drivers:
Expanding Influence of Music Education and Cultural Institutions
Music education continues to play a significant role in shaping the Europe Fretted Instrument String Market. Schools, conservatories, and cultural institutions actively promote learning across guitars, violins, and other fretted instruments, creating steady demand for strings. It benefits from structured programs that encourage students to upgrade equipment regularly. Professional musicians emphasize the importance of quality strings, reinforcing demand for premium products. Online tutorials and digital learning platforms further widen the reach of fretted instruments to younger demographics. Government-supported initiatives to promote cultural heritage strengthen the appeal of string-based instruments. Festivals and competitions across Europe provide visibility and recognition, indirectly boosting sales. The long-term role of education ensures recurring consumption and stable market expansion.
Rising Popularity of Live Performances and Growing Event Culture
Live performances and music festivals contribute strongly to the Europe Fretted Instrument String Market. It gains traction from increased attendance at concerts, small-scale gigs, and major festivals that encourage frequent string replacement. Musicians demand strings capable of enduring intense use, leading to higher sales volumes across multiple categories. Event-driven exposure inspires amateurs and hobbyists to invest in instruments, strengthening retail sales. Manufacturers target festival sponsorships and partnerships to highlight their products to diverse audiences. The growth of independent artists creates further reliance on quality strings for both studio recordings and live shows. Acoustic and electric string demand rises in tandem with audience preference for varied genres. Regional festivals across Europe establish reliable distribution points for leading brands.
- For example, D’Addario’s NYXL electric guitar strings offer up to 131% greater tuning stability and 40% enhanced break resistance, making them a go-to choice for touring musicians seeking reliable performance under demanding stage conditions.
Strong Penetration of Online Platforms and Digital Retail Channels
Digital retail channels significantly influence the Europe Fretted Instrument String Market by improving accessibility and purchase convenience. It benefits from the ability to reach professional musicians and casual learners with equal ease. E-commerce platforms provide a wide assortment of strings, enabling comparisons of tone, durability, and cost. Direct-to-consumer strategies allow brands to retain control over distribution and pricing. Marketing campaigns leverage online music communities to enhance visibility among niche groups. Subscription services for string replacements encourage recurring purchases and long-term loyalty. Digital retail growth supports regional accessibility in areas where traditional stores remain limited. The integration of fast delivery and easy returns builds consumer confidence and supports market adoption.
Innovation in Materials and Premium String Development
Innovation in string design remains a key growth factor for the Europe Fretted Instrument String Market. It thrives on advanced materials that enhance tonal clarity, durability, and performance. Coated strings with extended lifespan find acceptance among both professionals and casual players. Premium product lines offer customization, targeting specific tonal preferences across genres. Brands invest in R&D to create eco-friendly strings aligned with sustainability trends. Endorsements from well-known artists amplify demand for innovative string sets. Retailers focus on highlighting premium offerings through trial packs and bundled promotions. The adoption of innovative coatings and hybrid materials consolidates the role of premium strings as a primary driver of revenue growth.
- For example, Elixir Strings introduced their NANOWEB-coated electric strings featuring a micro-thin protective layer that guards against corrosion and debris buildup. Independent testing and player feedback confirm that these strings deliver significantly longer tone life and smoother feel compared to standard uncoated options.
Market Trends:
Growing Consumer Preference Toward Sustainable and Eco-Friendly Strings
Sustainability emerges as a prominent trend influencing the Europe Fretted Instrument String Market. It benefits from growing awareness among environmentally conscious consumers seeking alternatives with lower ecological impact. Manufacturers introduce bio-based coatings and recyclable packaging to align with green preferences. Brands adopting environmentally certified production processes establish a stronger competitive edge. Consumers show increasing interest in strings that balance performance with reduced carbon footprint. Market adoption of eco-friendly options strengthens brand image and fosters consumer loyalty. Retailers promote sustainable products across online and offline platforms to meet this demand. Industry-wide emphasis on sustainability highlights a transition toward more responsible product development.
- For example, D’Addario’s Playback recycling program, created in partnership with TerraCycle, has successfully diverted nearly 5 million used strings from landfills, underscoring its commitment to sustainable practices. Rotosound supports similar eco-conscious efforts through lightweight sealed foil pouches that use less material than conventional packaging, reducing waste and lowering environmental impact.
Increasing Role of Customization and Personalized String Solutions
Customization defines a growing trend within the Europe Fretted Instrument String Market. It enables musicians to choose string types tailored to their playing style and tonal requirements. Brands offer adjustable gauges, materials, and finishes to meet diverse demands. Direct engagement with customers through digital tools enhances personalization. It allows users to create bespoke sets suited to specific instruments or genres. Custom offerings capture loyalty among serious musicians seeking a distinct sound. Retailers and online stores adopt flexible packaging formats for personalized orders. Growth in customized solutions signals a shift toward user-centric product development strategies.
Expansion of Hybrid Strings and Cross-Genre Adoption
Hybrid strings gain popularity as musicians explore new styles within the Europe Fretted Instrument String Market. It benefits from cross-genre influences that require versatile tonal qualities. Manufacturers develop strings blending different materials to balance durability with clarity. Hybrid sets appeal to artists experimenting across classical, rock, jazz, and folk genres. Professional musicians endorse hybrid strings for their adaptability in studio and stage settings. Retailers position hybrid strings as versatile solutions for broad audiences. Growth of independent and fusion music accelerates acceptance of multi-genre instruments and accessories. Hybrid innovations reinforce the role of product diversity as a long-term trend.
Rising Integration of Digital Technology with String Performance Monitoring
The integration of digital tools influences the future of the Europe Fretted Instrument String Market. It benefits from devices that track string wear, tuning stability, and tonal output in real time. Smart accessories paired with mobile apps extend the functional life of strings. Musicians adopt digital solutions for precision and consistent performance during live shows. Retailers collaborate with technology providers to enhance consumer engagement. This integration provides opportunities for premium product differentiation and service-based models. Amateur musicians gain confidence through guided monitoring solutions. Adoption of digital integration represents a new dimension of product innovation and consumer value.
- For example, Roadie’s smart tuning devices now in their fourth iteration pair vibration detection with Bluetooth-enabled apps to deliver ultra-precise tuning, metronome features, and string-winding capability to musicians worldwide.
Market Challenges Analysis:
High Price Sensitivity and Consumer Preference for Low-Cost Alternatives
Price sensitivity poses a considerable challenge for the Europe Fretted Instrument String Market. It faces pressure from consumers who prioritize affordability over premium features. Low-cost alternatives attract hobbyists and casual players, reducing the appeal of advanced string sets. Discounted imports further intensify competition across key regions. Retailers catering to price-driven buyers limit shelf space for premium brands. Online platforms amplify access to budget options, strengthening the challenge for established players. The presence of counterfeit products in the marketplace worsens pricing issues. Overcoming these pressures requires brands to create distinct value propositions that justify higher costs.
Supply Chain Disruptions and Uneven Regional Distribution Networks
Supply chain disruptions create operational difficulties for the Europe Fretted Instrument String Market. It struggles with logistical delays, raw material price volatility, and uneven distribution networks across countries. Smaller retailers face difficulties maintaining inventory, especially during peak demand. Dependence on global suppliers makes manufacturers vulnerable to geopolitical and economic uncertainties. Gaps in regional distribution channels restrict product availability in emerging markets. Brands encounter challenges in aligning demand forecasts with actual consumption patterns. Regulatory differences across Europe complicate cross-border product movement. Streamlining supply networks remains critical to sustaining growth in the face of these disruptions.
Market Opportunities:
Rising Demand for Premium and Artist-Endorsed Strings
Premium and artist-endorsed strings create new opportunities in the Europe Fretted Instrument String Market. It benefits from musicians seeking superior tonal quality and reliability for professional use. Endorsements from recognized artists enhance credibility and drive aspirational purchases. Rising consumer preference for high-performance products strengthens brand positioning. Retailers highlight premium offerings through promotional campaigns and bundled kits. Innovative coatings and hybrid materials create avenues for differentiation. The willingness of musicians to invest in quality ensures recurring demand in this segment.
Expansion of E-Commerce and Subscription-Based Models
E-commerce platforms and subscription services offer strong opportunities in the Europe Fretted Instrument String Market. It gains traction from efficient delivery systems and recurring sales models. Subscription-based services provide convenience to musicians who replace strings frequently. Direct-to-consumer channels improve margins and brand loyalty. Online tutorials and digital promotions complement e-commerce expansion by driving awareness. Subscription packages strengthen predictability in demand while enhancing consumer engagement. Growing online penetration across Europe broadens access to both budget and premium string sets.
Market Segmentation Analysis:
By application, the Europe Fretted Instrument String Market demonstrates diverse growth across its application segments. Acoustic strings hold a strong position, supported by their deep cultural association with folk and traditional music. Electric strings continue to expand with the rising demand from rock, pop, and contemporary genres, while classical strings maintain relevance through structured learning in conservatories and music schools. Bass strings cater to both professional performers and recording artists, reinforcing their consistent demand. The "Others" category, including niche and specialty strings, gains traction among experimental musicians seeking unique tonal outputs.
- For instance, Rotosound’s Swing Bass 66 stainless-steel bass strings remain a favorite among professional players across genres. Renowned for durability and bright tone, the model continues to hold a reputation for consistency and longevity based on both historical use and expert reviews.
By end-user segmentation, the market reflects distinct purchasing patterns. Light strings dominate due to their ease of playability, making them highly preferred by beginners and casual players. Custom light strings attract intermediate and professional musicians who value tonal balance and durability, strengthening their market adoption. The "Others" category captures specialized string types that appeal to niche users and advanced artists with specific performance requirements. The Europe Fretted Instrument String Market benefits from this segmentation framework, as it enables manufacturers to tailor product innovations and distribution strategies for both mass and specialized demand across regions.
- For example, Savarez provides classical guitarists with flexible tension options Normal, High, and Mixed in its Alliance and Cantiga series, allowing for tailored string setups suited to diverse playing preferences.
Segmentation:
By Application Segment
- Acoustic
- Electric
- Classical
- Bass
- Others
By End-User Segment
- Light
- Custom Light
- Others
Regional Analysis:
Western Europe dominates the Europe Fretted Instrument String Market with a market share of 42%. The region benefits from strong cultural traditions in classical and modern music, supported by extensive music education systems and well-established distribution networks. Germany, the United Kingdom, and France lead demand due to their vibrant music industries, active concert culture, and wide consumer base of both professional and amateur musicians. It maintains strong sales of acoustic and electric strings, reflecting the diversity of music preferences across these countries. Retailers and online platforms in this region also highlight premium and artist-endorsed strings, reinforcing steady growth.
Southern Europe accounts for 28% of the market share, with Italy and Spain emerging as key contributors. The deep-rooted guitar and mandolin heritage in these countries continues to drive demand for acoustic and classical strings. It gains strength from tourism-driven cultural events and traditional music festivals that encourage instrument adoption. Regional manufacturers emphasize affordability and accessibility, making strings more attractive to younger players and hobbyists. The growth of small music schools and independent artists adds further momentum to sales. This segment of the market is expected to maintain resilience through continued cultural relevance.
Eastern and Northern Europe together capture 30% of the market share. Russia, Poland, and Nordic countries represent growing demand centers due to rising disposable incomes and expanding music education initiatives. It shows increasing adoption of electric and bass strings as younger audiences embrace global music genres. Online platforms play a vital role in reaching consumers in less urbanized areas where retail networks are limited. Manufacturers target these regions with budget-friendly and hybrid strings to cater to mixed demand. The expanding role of regional festivals and independent artists underlines the long-term potential for growth in these geographies.
Key Player Analysis:
- D’Addario
- Fender Musical Instruments Corporation
- Gibson Brands
- Ernie Ball Inc.
- GHS Strings
- F. Martin & Company Inc.
- Dunlop Manufacturing Inc.
- DR Handmade Strings
- Elixir Strings
Competitive Analysis:
The Europe Fretted Instrument String Market features a mix of global leaders and specialized regional brands competing across product quality, innovation, and distribution reach. D’Addario, Fender, and Ernie Ball maintain strong visibility through premium product lines and artist endorsements, while Gibson and Martin emphasize heritage-driven offerings with wide appeal among professionals. It demonstrates competitive strength from Elixir Strings, which focuses on coated technologies that extend durability, and GHS Strings and DR Handmade Strings, which cater to niche segments seeking tonal precision. Dunlop Manufacturing leverages its established presence in accessories to reinforce cross-selling opportunities. Regional distributors and smaller firms compete by offering affordable alternatives that attract hobbyists and casual players. Competitive strategies involve partnerships with online platforms, product customization, and sustainability-driven innovations. The market reflects an ongoing balance between premium differentiation and value-driven options, giving consumers broad access to both high-end and budget-friendly strings.
Recent Developments:
- In May 2025, Thalia Capos expanded its collaboration with Fender to deliver officially licensed accessories capos and pick pucks for guitarists across Europe. This partnership blends Thalia’s precision-engineered designs with Fender’s iconic brand identity, enhancing accessory options within the fretted instrument ecosystem.
- In January 2025, C. F. Martin & Co. unveiled a refreshed Standard Series acoustic guitar lineup at the NAMM Show, including new D-17, 000-17, and OM-45 models. They added Sitka spruce Golden Era bracing, a refined low-oval neck profile, beveled fingerboards, GE modern belly bridges, bone or ebony bridge pins, and vintage finishes with angled nuts and sleeker heels-blending classic tone with modern playability.
- In Sep 2024, D’Addario is celebrating its 50th anniversary with a special series of releases and events for musicians worldwide. To mark the milestone, the company has launched a curated collection of vintage-inspired merchandise such as T-shirts and hats that pay homage to its enduring legacy.
Market Concentration & Characteristics:
The Europe Fretted Instrument String Market shows moderate concentration, with a handful of global companies holding significant revenue shares while regional players compete in niche categories. It reflects characteristics of a fragmented industry where innovation, artist endorsements, and distribution strength define competitive advantage. Premium brands dominate urban and professional segments, whereas smaller firms capture value-conscious buyers in regional markets. Strong brand loyalty influences repeat purchases, particularly in acoustic and electric segments. The market remains highly responsive to technological improvements, material innovations, and shifts in consumer preference. Competitive intensity continues to rise with growing online penetration, enabling newer entrants to challenge established players through direct-to-consumer models.
Report Coverage:
The research report offers an in-depth analysis based on Application and End-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Fretted Instrument String Market will continue to benefit from the rising integration of music education in schools and cultural programs across the region.
- Demand for premium coated strings will expand, driven by professional musicians seeking longer durability and consistent tonal performance.
- Online sales channels will strengthen their role, with e-commerce platforms and subscription services enhancing consumer convenience.
- Sustainable product innovations, including eco-friendly materials and recyclable packaging, will shape purchasing decisions among environmentally aware consumers.
- Hybrid and customizable string sets will gain traction as musicians explore diverse genres and seek personalized tonal qualities.
- Regional festivals and live events will boost demand, with artists replacing strings more frequently due to performance intensity.
- Emerging markets in Eastern Europe will contribute to overall growth, supported by rising disposable incomes and music education initiatives.
- Partnerships between leading brands and independent artists will increase visibility, creating aspirational value for younger audiences.
- Smart accessories and digital monitoring tools linked to string performance will open new avenues for premium differentiation.
- Competitive intensity will rise as smaller regional brands leverage online platforms to challenge established players in targeted segments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Influence of Music Education and Cultural Institutions
Structured music education programs, conservatories, and government-supported cultural initiatives across Europe drive recurring demand for fretted instrument strings, especially in acoustic and classical categories. These programs encourage regular equipment upgrades and foster a culture of music learning among youth.
Rising Popularity of Live Performances and Event Culture
The growth of live music events, festivals, and independent artist performances across Europe leads to frequent string replacement and higher demand for durable, high-performance strings among both professionals and hobbyists.
Strong Penetration of Online Platforms and Digital Retail Channels
E-commerce and digital retail channels have made strings more accessible to a wider audience, enabling easy comparison, direct-to-consumer sales, and subscription models that encourage recurring purchases and brand loyalty.
Innovation in Materials and Premium String Development
Manufacturers are investing in advanced materials, coated technologies, and customizable string solutions to meet the evolving preferences of musicians, driving adoption of premium and innovative products that offer enhanced durability and tonal consistency.
Growing Consumer Preference Toward Sustainable and Eco-Friendly Strings
Increasing environmental awareness among European consumers is pushing brands to develop eco-friendly strings and recyclable packaging, which not only aligns with sustainability trends but also strengthens brand loyalty and market differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Fretted Instrument String Market, and what is its projected size in 2032?
Which Europe Fretted Instrument String Market segment held the largest share in 2024?
Who are the leading companies in the Europe Fretted Instrument String Market?
Which region commanded the largest share of the Europe Fretted Instrument String Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Light
- 1.2.2 Custom Light
- 1.2.3 Others
- 1.3 By Material
- 1.3.1 Nickel-Plated Steel
- 1.3.2 Stainless Steel
- 1.3.3 Phosphor Bronze
- 1.3.4 Coated/Polymer
- 1.3.5 Nylon
- 1.3.6 Others
- 1.4 By Application
- 1.4.1 Acoustic
- 1.4.2 Electric
- 1.4.3 Classical
- 1.4.4 Bass
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 102.1 million → 2032: USD 154.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Fretted Instrument String Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Fretted Instrument String Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Fretted Instrument String Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Fretted Instrument String Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Fretted Instrument String Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Fretted Instrument String Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Fretted Instrument String Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Fretted Instrument String Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 102.1 million → 2032: USD 154.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Fretted Instrument String Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Light
- 12.3.7.2 Custom Light
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Nickel-Plated Steel
- 12.4.7.2 Stainless Steel
- 12.4.7.3 Phosphor Bronze
- 12.4.7.4 Coated/Polymer
- 12.4.7.5 Nylon
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Acoustic
- 12.5.7.2 Electric
- 12.5.7.3 Classical
- 12.5.7.4 Bass
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Fretted Instrument String End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Fretted Instrument String Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Fretted Instrument String Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Fretted Instrument String Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 D’Addario
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Fender Musical Instruments Corporation
- 18.4 Gibson Brands
- 18.5 Ernie Ball Inc.
- 18.6 GHS Strings
- 18.7 F. Martin & Company Inc.
- 18.8 Dunlop Manufacturing Inc.
- 18.9 DR Handmade Strings
- 18.10 Elixir Strings
- 18.11 Rotosound
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

