
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Last Mile Delivery Market Size 2024 | USD 30,231.58 million |
| Europe Last Mile Delivery Market, CAGR | 7.12% |
| Europe Last Mile Delivery Market Size 2032 | USD 54,874.12 million |
Market Overview
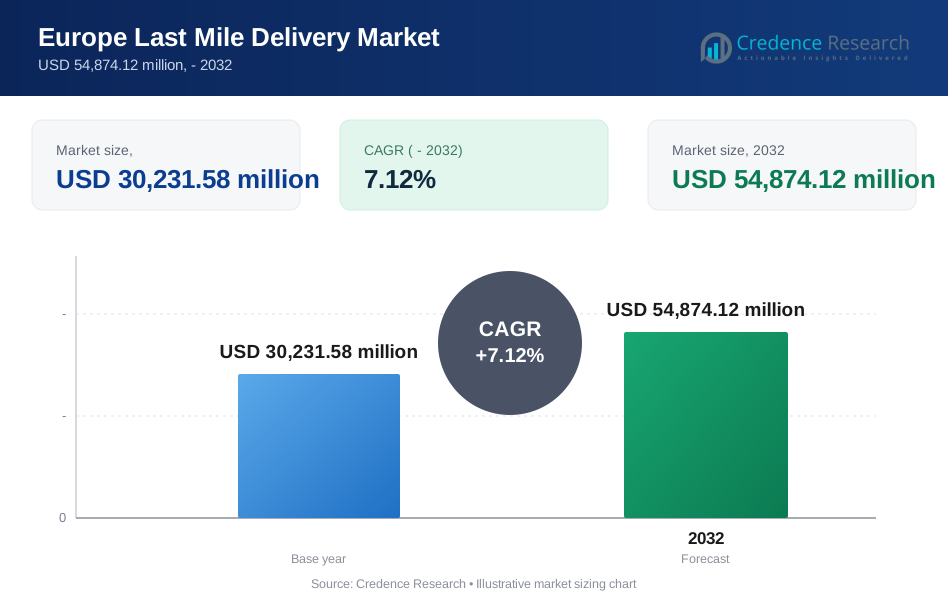
The Europe Last Mile Delivery Market is projected to grow from USD 30,231.58 million in 2023 to an estimated USD 54,874.12 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12% from 2024 to 2032. This growth is driven by the increasing demand for efficient and rapid delivery services, fueled by the expansion of e-commerce and online retail platforms.
Key drivers in this market include the growing adoption of automation and advanced technologies, such as drones and autonomous vehicles, to enhance delivery efficiency. Additionally, the rise of urbanization and the push for sustainable delivery methods, such as electric vehicles, are shaping trends in the last mile delivery sector. Companies are focusing on reducing delivery costs and improving the overall customer experience, while regulatory support for greener logistics is further driving market expansion.
Geographically, Western Europe dominates the market due to its developed infrastructure and high demand for same-day delivery services, with countries like Germany, the UK, and France leading the charge. Eastern Europe, though growing at a slower pace, presents opportunities for future growth as e-commerce penetration increases. Key players in the market include DHL, DPD Group, UPS, and FedEx, all of which are investing in innovative technologies and expanding their networks to meet rising demand.
Market Drivers
The E-Commerce Boom and Consumer Expectations
The surge in e-commerce has fundamentally transformed the last mile delivery market across Europe. Over the past decade, online shopping has become deeply ingrained in consumer behavior, accelerated further by the COVID-19 pandemic. For instance, in the UK, online retail sales increased by £76.1 billion between 2011 and 2021, highlighting the significant growth in e-commerce over the past decade. The convenience of online shopping has created a growing demand for faster and more efficient delivery services, putting pressure on logistics providers to meet these expectations. Consumers now expect shorter delivery times, often within 24 hours, and seamless tracking of their orders. This shift has made last mile delivery, the final stage in the logistics chain, more crucial than ever. Companies that can provide a smooth and fast delivery experience stand to gain a competitive advantage. For instance, a survey conducted by PwC in 2021 found that 41% of consumers in Europe are willing to pay extra for same-day delivery, emphasizing the growing demand for faster delivery services. Furthermore, the rise of mobile commerce (m-commerce) has compounded the need for speed and efficiency, as consumers make purchases on the go and expect their orders to be fulfilled promptly. In this environment, businesses are increasingly focused on improving their last mile capabilities, whether through investment in technology or innovative delivery models, such as crowd-sourced delivery.
Advancements in Technology and Automation
Technological advancements are playing a pivotal role in enhancing the efficiency and effectiveness of last mile delivery operations. The adoption of automation, artificial intelligence (AI), and data analytics has revolutionized how deliveries are managed, enabling companies to optimize routes, reduce delivery times, and improve customer satisfaction. One of the most significant developments is the use of autonomous delivery vehicles, drones, and robots, which promise to streamline delivery processes and reduce reliance on human labor. AI and machine learning algorithms are also being deployed to predict delivery patterns, optimize routes, and allocate resources more effectively. This not only reduces operational costs but also ensures timely deliveries, even during peak seasons. Furthermore, real-time data tracking and visibility systems provide customers with precise updates on the status of their deliveries, thereby enhancing transparency and improving the overall customer experience. In addition to automation, innovations such as smart lockers and parcel collection points are being introduced to cater to the growing need for flexible delivery options. These technologies offer consumers greater convenience and reduce the burden on delivery drivers by providing centralized locations for drop-offs, thus alleviating congestion in urban areas.
Sustainability and Green Logistics Initiatives
Sustainability has become a critical focus for both consumers and businesses in Europe, and the last mile delivery market is no exception. With increasing awareness of environmental issues, there is growing pressure on companies to adopt eco-friendly delivery practices. Governments across Europe have also implemented stricter regulations aimed at reducing carbon emissions, particularly in urban areas. These regulations are pushing logistics providers to invest in electric vehicles (EVs), cargo bikes, and other low-emission delivery solutions. The adoption of electric delivery vehicles is a key trend in this regard, as companies look to minimize their carbon footprint while complying with new environmental standards. For instance, DPD, a leading parcel delivery company in Europe, has deployed over 7,000 electric vehicles as part of its commitment to reducing its carbon footprint. Major cities like London, Paris, and Berlin are enforcing low-emission zones, which further incentivize the use of sustainable transportation. Additionally, alternative fuel vehicles and the integration of renewable energy sources in logistics operations are gaining traction as part of broader green logistics initiatives. In response to these regulatory and consumer-driven demands, many last mile delivery companies are also exploring ways to reduce packaging waste, use more sustainable materials, and promote circular economy principles. For instance, in 2020, the city of Amsterdam set a target to have 100% emission-free deliveries by 2025, encouraging the adoption of electric vehicles and cargo bikes in last mile delivery operations. These initiatives not only enhance brand reputation but also align with broader corporate social responsibility (CSR) goals, helping companies differentiate themselves in a highly competitive market.
Urbanization and Infrastructure Development
Europe’s increasing urbanization is another critical driver for the growth of the last mile delivery market. As more people move to cities, the demand for convenient, fast, and reliable delivery services continues to rise. Urban areas present unique challenges for logistics providers, including traffic congestion, limited parking, and higher delivery densities. However, they also offer opportunities for innovative solutions to meet the growing demand. To address these challenges, many cities are investing in infrastructure improvements, such as smart city initiatives that integrate logistics into urban planning. These developments include the creation of dedicated delivery zones, micro-distribution centers, and urban consolidation hubs, which help optimize delivery routes and reduce congestion. Additionally, the rise of multi-modal delivery systems, combining bikes, electric vans, and public transportation, is helping companies navigate urban environments more efficiently. Companies are also experimenting with new delivery models tailored to densely populated areas. For instance, on-demand delivery services, supported by real-time data and mobile apps, are becoming increasingly popular in cities. These services allow consumers to choose specific delivery windows, ensuring that packages arrive at the most convenient time and place.
Market Trends
Shift Toward Sustainable Delivery Solutions
One of the most significant trends in the Europe Last Mile Delivery Market is the increasing shift toward sustainable delivery solutions. Environmental consciousness is growing across Europe, both from regulatory authorities and consumers. Governments in major cities are imposing stricter environmental regulations, including low-emission zones and carbon reduction targets, which are directly impacting how companies manage their logistics operations. In response, many last mile delivery companies are adopting electric vehicles (EVs), cargo bikes, and other eco-friendly modes of transportation. Major logistics companies like DHL, UPS, and DPD Group are investing heavily in expanding their fleets of electric vehicles to comply with sustainability goals. For instance, major logistics companies like DHL have committed to deploying 80,000 electric vehicles for last-mile deliveries and investing €7 billion in clean operations by 2030. Cities such as London, Paris, and Amsterdam are becoming key areas where green delivery practices are being tested and implemented on a large scale. In addition to EVs, innovative solutions like cargo e-bikes and electric scooters are being deployed to navigate urban areas more efficiently, reducing both emissions and congestion. This growing focus on sustainability is not only in response to regulations but also due to increasing consumer demand for environmentally responsible services.
Increased Adoption of Technology and Automation
Technological innovation continues to be a major trend shaping the last mile delivery market in Europe. Companies are increasingly integrating advanced technologies such as artificial intelligence (AI), machine learning, and data analytics into their operations to optimize delivery efficiency. AI-driven systems are enabling more accurate route optimization, predicting delivery patterns, and improving overall delivery speed while reducing costs. The use of autonomous delivery vehicles and drones is gaining traction as companies seek to overcome challenges related to labor shortages, traffic congestion, and increasing delivery volumes. These innovations are particularly useful in last-mile logistics, where traditional delivery methods often face inefficiencies. Robotics is also making an impact with automated parcel lockers and smart drop-off points, offering consumers more flexible and convenient delivery options. In addition, real-time tracking technologies and enhanced communication systems between consumers and delivery companies are becoming standard. Customers now expect real-time visibility of their parcels and seamless communication throughout the delivery process. For instance, a recent study found that 64% of European consumers expect real-time tracking to be available with every parcel they receive, highlighting the growing demand for enhanced visibility and communication in last-mile delivery. These technologies not only improve customer satisfaction but also help companies reduce failed delivery attempts and operational costs.
Market Restraints and Challenges
High Costs of Last Mile Delivery Operations
One of the most significant challenges faced by the Europe Last Mile Delivery Market is the high operational costs associated with the final leg of delivery. Last mile delivery is the most expensive segment of the supply chain, often accounting for up to 50% of total delivery costs. This is due to several factors, including the complexity of delivering to multiple, often dispersed, individual destinations, and the requirement for fast, sometimes same-day, delivery services. The increasing demand for free delivery and returns from e-commerce customers further strains profitability, as logistics providers must balance customer expectations with cost-efficiency. Additionally, the operational costs are heightened by issues such as failed deliveries due to customers not being available, traffic congestion in urban areas, and inefficient delivery routes in less dense rural regions. These challenges necessitate ongoing investments in technology and infrastructure, which further drive up costs. Companies are also under pressure to invest in electric vehicles (EVs) and other sustainable solutions to meet environmental regulations, adding another layer of financial burden.
Logistical and Infrastructure Challenges in Urban Areas
Urbanization poses another significant restraint on the last mile delivery market in Europe. As populations in cities grow, logistical complexities also increase. Traffic congestion, limited parking spaces, and strict city regulations create substantial challenges for logistics providers. Many European cities are implementing low-emission zones and congestion charges, which, while beneficial for the environment, complicate delivery operations and add costs for companies that must adapt to these restrictions. Moreover, dense urban areas create difficulties in accessing specific delivery locations, especially in older cities with narrow streets and complex infrastructure. This leads to inefficient delivery routes, higher fuel consumption, and increased delivery times, all of which reduce operational efficiency. At the same time, rising customer expectations for fast and flexible delivery options in urban environments add pressure on companies to optimize their delivery processes despite these infrastructural constraints. These logistical and infrastructure challenges remain significant barriers to cost-effective and efficient last mile delivery.
Market Segmentation Analysis
By Service Type
The Europe Last Mile Delivery Market is segmented into three key service types: Business-to-Consumer (B2C), Business-to-Business (B2B), and Consumer-to-Consumer (C2C). The B2C segment is the largest and fastest-growing, propelled by the rapid expansion of e-commerce and consumers' increasing demand for quicker and more efficient delivery services. As a result, companies are focusing on reducing delivery times and enhancing customer experiences to maintain competitiveness. While the B2B segment is not growing as rapidly as B2C, it remains vital for sectors such as manufacturing, wholesale, and industrial deliveries, emphasizing timely and cost-effective services for larger, more predictable shipments. Lastly, the C2C segment caters to peer-to-peer deliveries facilitated by online marketplaces and social commerce, supported by the rise of second-hand goods and sharing economies; though smaller than the B2B and B2C segments, it is expected to grow as digital sales platforms gain traction.
By Application
The Europe Last Mile Delivery Market is significantly influenced by various application segments, including food and beverages, retail and e-commerce, healthcare, and others. The food and beverage sector has seen a surge in demand for quick deliveries, driven by online food platforms and meal-kit services, necessitating specialized logistics to ensure timely service and maintain food quality. Retail and e-commerce represent the largest application segment, as the rapid growth of online shopping-particularly in fashion, electronics, and household goods-has prompted retailers to offer fast, reliable delivery options, including same-day or next-day services. The healthcare sector is also expanding, requiring secure and timely delivery of medical supplies and pharmaceuticals, often under stringent temperature control. Additionally, other industries such as automotive and consumer electronics contribute to market diversity, each with distinct last mile delivery requirements that logistics providers must address.
Segments
Based on Service Type
- Business-to-Consumer (B2C)
- Business-to-Business (B2B)
- Consumer-to-Consumer (C2C)
Based on Application
- Food & Beverages
- Retail & E-commerce
- Healthcare
- Others
Based on Region
- Western Europe
- Eastern Europe
- Southern and Northern Europe
Regional Analysis
Western Europe (45%)
Western Europe holds the largest share of the Europe Last Mile Delivery Market, accounting for approximately 45% of the market. This dominance is driven by the region’s advanced logistics infrastructure, high urbanization levels, and a mature e-commerce sector. Countries like Germany, the UK, and France lead in this region, benefiting from well-established networks of logistics providers and a strong consumer base with high disposable incomes.Germany, as Europe’s largest economy, plays a pivotal role in driving growth, especially in sectors like retail and e-commerce. The UK has also emerged as a leader, particularly in urban last mile delivery innovations, with companies adopting electric vehicles (EVs) and drones to enhance delivery efficiency. Western European countries are early adopters of green logistics solutions, with a strong focus on sustainability, reducing carbon emissions, and meeting stringent environmental regulations. As such, the region is also leading in the integration of electric fleets and smart delivery systems.
Eastern Europe (18%)
Eastern Europe contributes to around 18% of the Europe Last Mile Delivery Market. Although this region has a smaller share compared to Western Europe, it is experiencing steady growth due to rising e-commerce adoption and improving logistics infrastructure. Countries like Poland, Hungary, and the Czech Republic are seeing significant investment from e-commerce giants, as internet penetration and online shopping become more widespread.However, infrastructure gaps and varying regulations between countries in the region pose challenges for logistics providers. Despite these hurdles, the demand for last mile delivery solutions is increasing, particularly in urban centers. The region’s relatively lower labor costs also offer competitive advantages for logistics companies, making Eastern Europe an attractive area for future growth.
Key players
- DHL Group
- United Parcel Service Inc (UPS)
- FedEx Corp
- com Inc
- Kerry Logistics Network Ltd
- Drone Delivery Canada Corp
- XPO Logistics
- A2Z Drone Delivery
- Power Link Expedite
Competitive Analysis
The Europe Last Mile Delivery Market is characterized by intense competition among key players, each striving to enhance service efficiency and customer satisfaction. DHL Group leads with a robust global network and a focus on sustainability, leveraging advanced technology for operational efficiency. United Parcel Service Inc and FedEx Corp follow closely, known for their extensive logistics solutions and innovation in delivery speed. Amazon.com Inc has disrupted the market with its aggressive delivery initiatives, including same-day services, supported by its vast infrastructure. Meanwhile, Kerry Logistics Network Ltd and XPO Logistics emphasize tailored solutions and regional expertise to cater to diverse market needs. The emergence of drone delivery services, represented by Drone Delivery Canada Corp and A2Z Drone Delivery, reflects the industry's shift toward innovative solutions that enhance delivery speed and efficiency. Overall, these players are continuously evolving their strategies to maintain competitive advantages in a rapidly changing market landscape.
Recent Developments
- In September 2024, UPS announced plans to acquire Frigo-Trans and its sister company BPL, German-based cold chain logistics providers. This acquisition aims to expand UPS's healthcare logistics capabilities throughout Europe, particularly in time-sensitive and temperature-controlled deliveries.
- In October 2024, FedEx introduced the FedEx Surround Monitoring and Intervention Solution in Europe. This innovative portfolio enhances logistics and supply chain management by providing customers with greater visibility and control over their shipments. The solution will be rolled out in phases, starting with the healthcare sector in several European countries.
- In June 2024, Amazon announced plans to invest €8.8 billion in expanding its Frankfurt cloud computing subsidiary, Amazon Web Services (AWS). Additionally, the company revealed plans to invest €7.8 billion in the AWS European Sovereign Cloud, with the first AWS Region set to launch in Brandenburg, Germany, by the end of 2025.
- In March 2024, Kerry Logistics Network launched a new air-sea solution between Europe and Oceania. This innovative service is 50% cheaper than airfreight and three times faster than sea freight on the same routes, connecting eight European countries with destinations in Australia and New Zealand.
- In 2024, XPO Logistics launched "Connect Europe" a unique solution that simplifies the management of shipments to 25 European countries. This service consolidates international shipping needs using a single point of contact, aiming to make cross-border logistics more accessible to companies of all sizes
Market Concentration and Characteristics
The Europe Last Mile Delivery Market exhibits a moderate level of concentration, characterized by a mix of established logistics giants and emerging innovative companies. Major players like DHL Group, United Parcel Service Inc (UPS), and FedEx Corp dominate the market with their extensive networks, advanced technologies, and comprehensive service offerings. These companies leverage economies of scale and operational efficiencies to maintain competitive pricing and service reliability. However, the market also features a growing number of niche players, such as Drone Delivery Canada Corp and A2Z Drone Delivery, which are capitalizing on advancements in technology and changing consumer preferences for faster and more sustainable delivery options. This blend of large-scale operators and agile startups creates a dynamic competitive landscape, where innovation, customer experience, and adaptability to local market needs are key determinants of success. Overall, the market is evolving rapidly, driven by increasing e-commerce penetration, changing consumer expectations, and a strong focus on sustainability.
Report Coverage
The research report offers an in-depth analysis based on Deployment Service Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The surge in e-commerce is expected to persist, driving demand for efficient last mile delivery solutions. Retailers will increasingly focus on enhancing delivery speed and flexibility to meet customer expectations.
- Innovations in technology, such as AI, automation, and real-time tracking, will revolutionize last mile logistics. Companies will adopt these technologies to optimize routes, reduce delivery times, and improve overall efficiency.
- Growing environmental awareness will prompt logistics providers to adopt sustainable practices. The use of electric vehicles, cargo bikes, and alternative delivery methods will become standard as companies strive to reduce their carbon footprints.
- Rapid urbanization in Europe will create new challenges for last mile delivery, including increased congestion and limited parking. Providers will need to develop adaptive strategies to navigate these complexities effectively.
- The establishment of micro-fulfillment centers in urban areas will enhance delivery efficiency. These centers will facilitate faster order processing and improve the accessibility of goods for last mile deliveries.
- The demand for same-day delivery will continue to grow as consumers seek immediate gratification. Logistics providers will invest in infrastructure and technology to fulfill this demand efficiently.
- Collaborations between logistics providers and tech companies will become more common. Strategic partnerships will enable companies to leverage expertise and innovate solutions that enhance last mile delivery capabilities.
- Ongoing regulatory changes in urban areas will shape last mile delivery strategies. Companies must stay informed about local regulations regarding emissions, congestion charges, and delivery time restrictions.
- As competition intensifies, companies will prioritize customer experience. Personalized delivery options, improved communication, and flexible delivery windows will become essential for retaining customer loyalty.
- Increased investment in research and development will drive innovation in last mile delivery. Companies will explore new technologies and methods to streamline operations and meet evolving consumer needs effectively.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
E-Commerce Boom and Consumer Expectations
The rapid growth of e-commerce and mobile commerce in Europe has significantly increased demand for fast, reliable last mile delivery, with consumers expecting same-day or next-day service and seamless tracking. This shift is compelling logistics providers to invest in speed, flexibility, and customer experience to remain competitive.
Advancements in Technology and Automation
The adoption of automation, AI, and real-time data analytics is enabling companies to optimize delivery routes, reduce operational costs, and improve delivery accuracy. Innovations such as autonomous vehicles, drones, and smart lockers are streamlining last mile operations and enhancing customer satisfaction.
Sustainability and Green Logistics Initiatives
Growing environmental awareness and stricter European regulations are driving logistics providers to adopt electric vehicles, cargo bikes, and other low-emission solutions. These sustainable practices are not only regulatory requirements but also align with consumer preferences for eco-friendly delivery options.
Urbanization and Infrastructure Development
Increasing urbanization across Europe is raising demand for efficient last mile delivery in densely populated cities, prompting investments in smart city logistics, micro-distribution centers, and multi-modal delivery systems to overcome congestion and access challenges.
Rising Demand for Flexible and Personalized Delivery
Consumers are seeking more flexible delivery windows, real-time tracking, and personalized options, pushing companies to innovate with on-demand and crowd-sourced delivery models. This trend is reshaping service offerings and driving differentiation in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe Last Mile Delivery Market in 2023 and 2032?
What is the expected compound annual growth rate (CAGR) for the market?
What are the primary drivers of growth in the Europe Last Mile Delivery Market?
Which regions are leading in the last mile delivery market in Europe?
Who are the major players in the Europe Last Mile Delivery Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Food & Beverages
- 1.2.2 Retail & E-commerce
- 1.2.3 Healthcare
- 1.2.4 Others
- 1.3 By Service Type
- 1.3.1 Business-to-Consumer (B2C)
- 1.3.2 Business-to-Business (B2B)
- 1.3.3 Consumer-to-Consumer (C2C)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 30,231.58 million → 2032: USD 54,874.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Last Mile Delivery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Last Mile Delivery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Last Mile Delivery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Last Mile Delivery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Last Mile Delivery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Last Mile Delivery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Last Mile Delivery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Last Mile Delivery Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 30,231.58 million → 2032: USD 54,874.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Last Mile Delivery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverages
- 12.3.7.2 Retail & E-commerce
- 12.3.7.3 Healthcare
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Business-to-Consumer (B2C)
- 12.4.7.2 Business-to-Business (B2B)
- 12.4.7.3 Consumer-to-Consumer (C2C)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Last Mile Delivery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Last Mile Delivery Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Last Mile Delivery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Last Mile Delivery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DHL Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 United Parcel Service Inc (UPS)
- 18.4 FedEx Corp
- 18.5 Amazon.com Inc
- 18.6 Kerry Logistics Network Ltd
- 18.7 Drone Delivery Canada Corp
- 18.8 XPO Logistics
- 18.9 A2Z Drone Delivery
- 18.10 DPD Group
- 18.11 Power Link Expedite
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

