
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Military Vehicle Sustainment Market Size 2024 | USD 4,513.84 Million |
| Europe Military Vehicle Sustainment Market, CAGR | 7.19% |
| Europe Military Vehicle Sustainment Market Size 2032 | USD 7,868.25 Million |
Market Overview
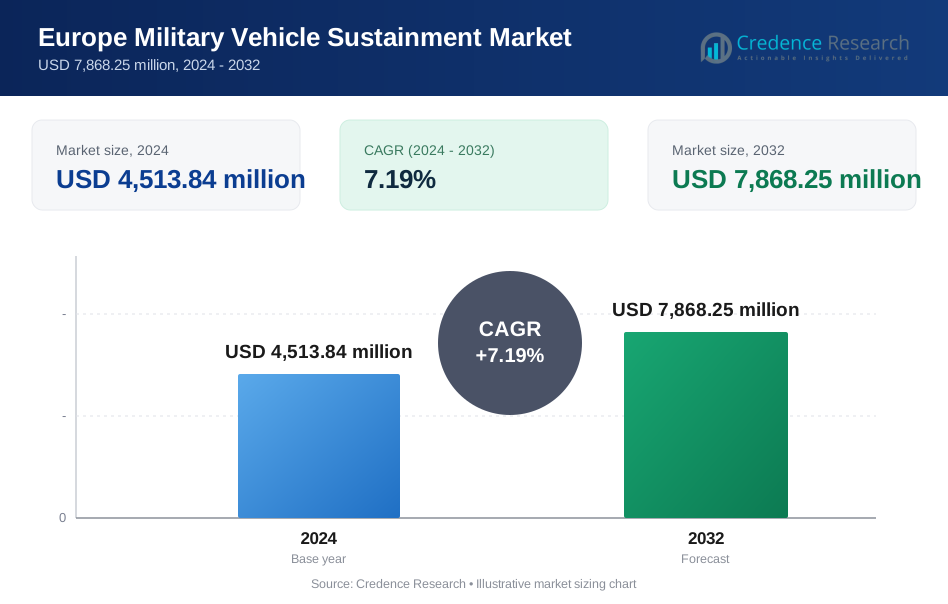
Europe Military Vehicle Sustainment Market size was valued at USD 4,513.84 million in 2024 and is anticipated to reach USD 7,868.25 million by 2032, at a CAGR of 7.19% during the forecast period (2024-2032).
The Europe Military Vehicle Sustainment Market is expanding due to rising defense budgets, fleet modernization initiatives, and increasing geopolitical tensions. Governments are prioritizing the maintenance, repair, and overhaul (MRO) of aging military vehicles to enhance operational readiness and extend service life. The adoption of advanced technologies such as predictive maintenance, artificial intelligence (AI)-based diagnostics, and automation is improving efficiency and reducing downtime. Additionally, the integration of hybrid and electric propulsion systems is driving the need for specialized sustainment services. Strong collaborations between defense contractors and military organizations are fostering innovation in sustainment strategies. Moreover, the European Union’s focus on strengthening regional defense capabilities and interoperability among NATO allies is further accelerating investments in vehicle sustainment programs. The market also benefits from an increasing shift toward outsourcing MRO services to private firms, ensuring cost-effective and rapid maintenance solutions. These factors collectively support market growth over the forecast period.
The Europe Military Vehicle Sustainment market is driven by increasing defense modernization programs, rising geopolitical tensions, and advancements in maintenance technologies across key countries such as Germany, the UK, France, Italy, and Poland. These nations are heavily investing in predictive maintenance solutions, AI-driven diagnostics, and fleet upgrades to enhance operational efficiency and combat readiness. The demand for sustainment services is also growing in Sweden, Spain, and the Netherlands, where military forces are focusing on interoperability and long-term fleet sustainability. Leading defense contractors such as Rheinmetall AG, Leonardo S.p.A., BAE Systems, Thales Group, Nexter Systems, Saab AB, and Krauss-Maffei Wegmann (KMW) play a crucial role in providing advanced sustainment solutions, including overhaul, refurbishment, and modernization services. Companies like GDELS, Patria Group, and MBDA Systems are expanding their regional presence through strategic collaborations and technology-driven maintenance programs, ensuring fleet readiness and long-term operational effectiveness for European defense forces.
Market Insights
- The Europe Military Vehicle Sustainment market was valued at USD 4,513.84 million in 2024 and is projected to reach USD 7,868.25 million by 2032, growing at a CAGR of 7.19% during the forecast period.
- Increasing defense budgets and modernization programs across European nations are driving demand for advanced sustainment solutions.
- The adoption of predictive maintenance, AI-driven diagnostics, and digital twin technology is transforming military vehicle sustainment strategies.
- Leading defense contractors such as Rheinmetall AG, BAE Systems, Leonardo S.p.A., and Nexter Systems are strengthening their market position through technological innovations and partnerships.
- Budget constraints and high maintenance costs of aging military fleets pose challenges for defense forces and sustainment providers.
- Germany, the UK, France, and Poland are key markets, with increasing investments in fleet readiness and interoperability initiatives.
- Strategic collaborations between military forces and private defense contractors are enhancing sustainment capabilities and ensuring long-term operational efficiency.
Market Drivers
Advancements in Predictive Maintenance and AI-Based Diagnostics
The integration of artificial intelligence (AI) and predictive maintenance technologies is transforming military vehicle sustainment in Europe. Defense organizations are leveraging AI-driven analytics, Internet of Things (IoT) sensors, and real-time data monitoring to detect mechanical failures before they occur. For instance, the use of IoT sensors in military vehicles provides continuous feedback on critical components, allowing for optimized maintenance schedules and reduced downtime. Additionally, AI-powered diagnostics enhance decision-making by providing accurate failure predictions and automated maintenance recommendations. The adoption of these advanced technologies is improving sustainment efficiency, ensuring fleet readiness, and reducing reliance on traditional time-based maintenance practices. As a result, defense forces are increasingly investing in digital sustainment solutions to enhance mission effectiveness and reduce lifecycle costs.
Increasing Adoption of Hybrid and Electric Military Vehicles
The shift toward hybrid and electric propulsion systems in military vehicles is driving the need for specialized sustainment services. European defense forces are focusing on energy-efficient and environmentally sustainable solutions, leading to the deployment of hybrid-electric and fully electric armored vehicles. For instance, countries like Germany and France are leading in the development and fielding of electrified military solutions, driven by their superior technological capacity and high defense budgets. These new platforms require advanced maintenance capabilities, including battery management, software upgrades, and high-voltage component servicing. As military fleets transition to cleaner energy sources, sustainment providers are adapting to support emerging propulsion technologies. Furthermore, the integration of electric powertrains enhances fuel efficiency and reduces logistical challenges associated with traditional fuel supply chains, making them an attractive option for military operations. This transition is creating new opportunities for innovation in military vehicle sustainment.
Growing Defense Budgets and Modernization Initiatives
European nations are significantly increasing their defense expenditures to enhance military readiness and address evolving security threats. Rising geopolitical tensions, territorial disputes, and commitments to NATO’s defense spending targets are driving investments in military vehicle sustainment programs. Governments are prioritizing the maintenance, repair, and overhaul (MRO) of aging fleets to ensure operational efficiency and extend service life. Additionally, modernization programs focusing on next-generation armored vehicles, unmanned ground systems, and hybrid-electric propulsion technologies are fueling demand for advanced sustainment solutions. These initiatives are not only improving fleet longevity but also enhancing mobility, protection, and combat effectiveness, further contributing to market expansion.
Growing Outsourcing of MRO Services to Private Contractors
European defense forces are increasingly outsourcing MRO services to private firms to enhance efficiency and reduce operational costs. Strategic partnerships between military organizations and defense contractors enable rapid maintenance turnaround times, access to specialized expertise, and streamlined logistics support. Outsourcing allows military units to focus on core operational activities while leveraging the technical capabilities of industry leaders. Additionally, private-sector involvement fosters innovation by incorporating commercial best practices, automation, and digital maintenance solutions into sustainment operations. As European nations continue to modernize their defense infrastructure, outsourcing sustainment services is expected to become a key strategy for optimizing fleet availability and reducing long-term maintenance expenses.
Market Trends
Integration of Advanced Digital Technologies
The Europe Military Vehicle Sustainment market is witnessing a significant shift toward digitalization, with the adoption of advanced technologies such as artificial intelligence (AI), Internet of Things (IoT), and predictive maintenance solutions. AI-driven diagnostics and machine learning algorithms are enabling real-time monitoring of vehicle components, improving fault detection, and reducing unplanned downtime. For instance, the integration of IoT sensors in military vehicles provides continuous feedback on critical components, allowing for optimized maintenance schedules and reduced downtime. This shift from reactive to proactive maintenance is improving operational efficiency and extending vehicle lifespan. Additionally, the use of digital twin technology is gaining traction, enabling military forces to simulate wear and tear, optimize maintenance schedules, and reduce overall sustainment costs.
Expansion of Private Sector Involvement in MRO Services
The trend of outsourcing military vehicle maintenance, repair, and overhaul (MRO) services to private contractors is gaining momentum across Europe. Governments and defense forces are increasingly collaborating with industry leaders to enhance sustainment efficiency, reduce costs, and improve fleet readiness. For instance, partnerships between military organizations and private contractors enable rapid maintenance turnaround times, access to specialized expertise, and streamlined logistics support. Private firms are bringing in commercial best practices, automation, and advanced logistics management to optimize sustainment operations. Additionally, long-term performance-based contracts are becoming a preferred model, ensuring that service providers focus on improving vehicle availability and minimizing maintenance downtime. This shift toward privatization is streamlining sustainment processes and driving innovation within the military MRO sector.
Rising Demand for Hybrid and Electric Military Vehicles
Sustainability and fuel efficiency are becoming critical priorities for European defense forces, leading to the increased deployment of hybrid and electric military vehicles. As governments focus on reducing carbon footprints and minimizing reliance on fossil fuels, hybrid-electric propulsion systems are being integrated into military fleets. These advanced vehicles require specialized sustainment services, including battery management, software updates, and high-voltage component maintenance. Consequently, military vehicle sustainment providers are adapting their capabilities to support emerging technologies and ensure seamless fleet operations. The growing emphasis on green military initiatives is expected to reshape sustainment strategies, driving investments in infrastructure, training, and specialized maintenance solutions.
Growing Focus on Interoperability and NATO-Standardized Maintenance
European defense forces are emphasizing interoperability in sustainment practices to strengthen military cooperation among NATO allies. Standardized maintenance protocols, common spare parts supply chains, and unified repair procedures are being developed to ensure seamless coordination during joint military operations. This trend is particularly crucial in multinational deployments, where allied forces operate diverse fleets requiring consistent sustainment support. As a result, defense organizations are investing in shared logistics networks, digital sustainment platforms, and collaborative MRO programs. The push for interoperability is enhancing operational readiness, reducing maintenance redundancies, and improving overall fleet management across Europe’s military landscape.
Market Challenges Analysis
High Maintenance Costs and Budget Constraints
The Europe Military Vehicle Sustainment market faces significant challenges due to high maintenance costs and budget constraints. Military vehicle sustainment involves complex and resource-intensive processes, including spare parts procurement, skilled labor, and advanced diagnostic technologies. As defense budgets are allocated across multiple priorities such as procurement of new weaponry, cybersecurity, and personnel training, sustainment programs often experience financial limitations. Additionally, aging military fleets require extensive overhauls, further straining maintenance budgets. The rising costs of advanced materials, supply chain disruptions, and inflationary pressures exacerbate these financial challenges, making it difficult for military forces to maintain optimal fleet readiness. Governments must strike a balance between investing in sustainment programs and addressing other defense priorities, which can hinder the timely execution of maintenance operations.
Supply Chain Disruptions and Spare Parts Shortages
Supply chain disruptions and shortages of critical spare parts pose a major challenge to military vehicle sustainment in Europe. The dependence on global supply networks for specialized components, including electronics, sensors, and high-tech vehicle parts, makes sustainment operations vulnerable to geopolitical tensions, trade restrictions, and manufacturing delays. For instance, companies like Rheinmetall AG have introduced innovative solutions such as mobile production facilities to mitigate supply chain risks by enabling rapid on-site production of critical spare parts using 3D printing. However, overcoming these challenges requires significant investment and strategic planning to ensure the uninterrupted availability of critical vehicle components. Additionally, the increasing complexity of modern military vehicles requires highly specialized replacement parts that are often produced by a limited number of suppliers. Any delays in procurement can lead to extended vehicle downtime, reducing operational readiness.
Market Opportunities
The Europe Military Vehicle Sustainment market presents significant opportunities driven by advancements in digitalization and predictive maintenance solutions. The integration of artificial intelligence (AI), Internet of Things (IoT), and real-time data analytics is transforming sustainment operations by enhancing fault detection, optimizing maintenance schedules, and reducing downtime. Defense forces are increasingly investing in predictive maintenance technologies that enable proactive identification of potential failures, improving fleet efficiency and longevity. Additionally, the adoption of digital twin technology allows military organizations to simulate wear and tear, optimize repair processes, and reduce sustainment costs. These technological advancements create opportunities for defense contractors and service providers to offer innovative, data-driven solutions that enhance the effectiveness of military vehicle sustainment programs. As digital transformation accelerates, companies that specialize in AI-driven diagnostics, remote monitoring, and automated maintenance solutions are well-positioned to capitalize on this growing market demand.
Another key opportunity lies in the increasing shift toward hybrid and electric military vehicles, which require specialized sustainment capabilities. As European nations focus on sustainability and fuel efficiency, the demand for maintenance services tailored to hybrid and electric propulsion systems is expected to rise. The transition to electrification introduces new challenges related to battery management, software upgrades, and high-voltage component maintenance, creating a market for specialized service providers. Additionally, the push for interoperability among NATO allies is driving investments in standardized sustainment frameworks and collaborative MRO programs, fostering partnerships between defense forces and private sector players. Companies that develop expertise in electric military vehicle maintenance, supply chain resilience, and NATO-compliant sustainment solutions will find lucrative opportunities in this evolving market. With increasing government focus on fleet modernization and long-term operational readiness, military vehicle sustainment is set to remain a strategic priority, offering growth potential for industry stakeholders.
Market Segmentation Analysis:
By Vehicle Type:
The Europe Military Vehicle Sustainment market is segmented into armored vehicles, combat vehicles, utility vehicles, and others. Armored vehicles account for a significant share of the market, as they form the backbone of military operations and require extensive maintenance to ensure battlefield readiness. The sustainment of armored vehicles involves structural reinforcements, weapons system upgrades, and advanced mobility solutions. Combat vehicles, including main battle tanks and infantry fighting vehicles, require frequent refurbishment due to their high exposure to combat conditions. These vehicles undergo modernization programs focusing on enhanced firepower, automation, and protection systems. Utility vehicles, such as transport trucks, logistics carriers, and tactical support vehicles, play a crucial role in military mobility and require routine maintenance to maintain operational efficiency. The growing adoption of hybrid-electric propulsion in military utility vehicles is driving the demand for specialized sustainment services. The others category includes specialized military vehicles such as engineering and reconnaissance vehicles, which require niche maintenance solutions tailored to their unique operational requirements.
By Service Type:
Based on service type, the market is segmented into maintenance and repair, overhaul and refurbishment, and upgrade and modernization. Maintenance and repair services dominate the segment as regular servicing is essential to prevent mechanical failures and extend vehicle lifespan. Predictive maintenance solutions leveraging AI and IoT are gaining traction, enabling real-time monitoring and efficient fault detection. Overhaul and refurbishment services are critical for aging fleets, ensuring that older vehicles remain operationally effective through component replacements and structural reinforcements. These services are essential for European defense forces aiming to sustain legacy fleets while managing budget constraints. Upgrade and modernization services are witnessing increasing demand due to advancements in military technologies. European defense organizations are investing in next-generation armor, advanced communication systems, and hybrid-electric propulsion upgrades to enhance vehicle performance. The growing focus on digitization and automation in military vehicles is further driving demand for modernization services, presenting opportunities for defense contractors specializing in cutting-edge military sustainment solutions.
Segments:
Based on Vehicle Type:
- Armored Vehicles
- Combat Vehicles
- Utility Vehicles
- Others
Based on Service Type:
- Maintenance and Repair
- Overhaul and Refurbishment
- Upgrade and Modernization
Based on End- User:
- Army
- Navy
- Air Force
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Germany and the UK
Germany and the UK hold a substantial share of the market, collectively accounting for approximately 38% of the total regional revenue in 2024. Germany leads with its strong defense industry, significant military vehicle modernization programs, and investments in AI-driven maintenance solutions. The UK follows closely, driven by its commitment to enhancing fleet readiness, collaborative defense initiatives with NATO, and strategic partnerships with private defense contractors for MRO services. Both nations continue to invest in digitized sustainment programs, leveraging AI and IoT for predictive maintenance, thereby improving operational efficiency and reducing long-term costs.
France
France represents a significant market for military vehicle sustainment, contributing around 18% of the total European market. The French government has prioritized the modernization and sustainment of its armored and combat vehicle fleets through its Scorpion Program, which focuses on integrating next-generation technologies, AI-based diagnostics, and hybrid-electric propulsion systems. Additionally, the nation collaborates with other European defense forces under multinational defense programs, enhancing interoperability and streamlining maintenance operations. France's strong domestic defense manufacturing sector, including key players such as Nexter and Arquus, plays a crucial role in sustainment services, ensuring consistent supply chains and advanced refurbishment capabilities. The increasing reliance on AI-driven sustainment solutions and digital twin technology further strengthens France’s market position in military vehicle maintenance and repair services.
Italy and Spain
Italy and Spain together account for approximately 16% of the Europe Military Vehicle Sustainment market, with Italy contributing the larger share. Italy has been investing heavily in upgrading its land-based military fleet, particularly armored and utility vehicles, to align with NATO's defense modernization strategies. The Italian defense industry, led by firms like Leonardo S.p.A., is focusing on next-generation sustainment technologies, including automated maintenance and advanced diagnostics. Spain is also expanding its sustainment capabilities, driven by defense collaborations with European allies and increased procurement of armored vehicles for national security. Both countries are leveraging strategic defense partnerships and outsourcing maintenance services to private contractors to enhance efficiency and reduce operational costs.
Poland and Sweden
Poland and Sweden are emerging as key players in the military vehicle sustainment market, contributing 12% of the total market share. Poland has been aggressively modernizing its military fleet in response to regional security threats, particularly following the Russia-Ukraine conflict. The country is focusing on overhauling legacy armored vehicles and integrating advanced battlefield management systems. Sweden, on the other hand, is strengthening its defense infrastructure through increased investments in AI-driven predictive maintenance, digitized logistics support, and hybrid-electric combat vehicles. Both nations are prioritizing fleet readiness, interoperability, and sustainability, creating new opportunities for defense contractors specializing in advanced sustainment solutions.
Key Player Analysis
- Rheinmetall AG
- Leonardo S.p.A.
- BAE Systems
- Thales Group
- Nexter Systems
- Saab AB
- GDELS (General Dynamics European Land Systems)
- Krauss-Maffei Wegmann (KMW)
- Patria Group
- MBDA Systems
Competitive Analysis
The Europe Military Vehicle Sustainment market is highly competitive, with leading players focusing on innovation, strategic partnerships, and technological advancements to strengthen their market position. Rheinmetall AG, BAE Systems, Leonardo S.p.A., Thales Group, Nexter Systems, Saab AB, Krauss-Maffei Wegmann (KMW), GDELS (General Dynamics European Land Systems), Patria Group, and MBDA Systems dominate the industry, offering a wide range of sustainment solutions, including maintenance, overhaul, and modernization services. For instance, companies like Rheinmetall AG are leveraging advanced technologies such as AI-driven predictive maintenance and digital twin technology to enhance fleet efficiency and reduce downtime. Key players are also securing long-term contracts with European defense ministries and NATO allies, ensuring a steady revenue stream. The growing demand for hybrid and electric military vehicles is further driving competition, with firms investing in specialized sustainment services for next-generation fleets. Additionally, collaborations with local MRO service providers and technology firms are helping industry leaders expand their regional presence and improve supply chain resilience.
Recent Developments
- In March 2024, BAE Systems secured a $318 million services contract to support the U.S. Army's fleet of M109A6 and A7 self-propelled howitzers along with their companion vehicles. This contract includes delivering lifecycle sustainment and technical services.
- In June 2023, General Dynamics Land Systems attained a $712.3 million order from the U.S. Army for 300 Stryker DVHA1 vehicles. This contract enhances the capabilities of Stryker brigades by providing advanced technological features such as a powerful engine, robust suspension, and digital network integration.
- In June 2023, Rheinmetall AG presented a new solution for the mobile production of spare parts for military vehicles. The Mobile Smart Factory (MSF) offers metal 3D printing and postprocessing capabilities and is fully integrated into Rheinmetall’s IRIS (Integrated Rheinmetall Information System) digital ecosystem.
- In June 2022, General Dynamics Corporation demonstrated Autonomous Vehicle System (AVS) at CANSEC 2022. The AVS solution will optimize equipment performance and increase operational readiness to reduce the military's cost of ownership of vehicle fleets.
Market Concentration & Characteristics
The Europe Military Vehicle Sustainment market exhibits a moderate to high market concentration, with a few dominant players controlling a significant share of the industry. Leading defense contractors, including Rheinmetall AG, BAE Systems, Leonardo S.p.A., and Thales Group, drive market growth through long-term defense contracts, advanced sustainment solutions, and continuous technological innovation. The market is characterized by high barriers to entry, as extensive regulatory compliance, specialized expertise, and significant capital investment are required to establish a foothold. Additionally, technological advancements in predictive maintenance, AI-driven diagnostics, and hybrid-electric propulsion systems are reshaping sustainment strategies, leading to increased competition among established players. The industry also relies on strong government partnerships and international collaborations to enhance fleet readiness and efficiency. With rising geopolitical tensions and the increasing need for fleet modernization, market players are focusing on strategic acquisitions, digital transformation, and localized sustainment services to maintain a competitive edge and expand their regional presence.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Service Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Military Vehicle Sustainment market will witness steady growth driven by increasing defense modernization initiatives and fleet upgrades.
- Predictive maintenance and AI-driven diagnostics will play a crucial role in enhancing operational efficiency and reducing downtime.
- Defense budgets across major European nations will continue to prioritize sustainment services for armored and combat vehicles.
- Hybrid and electric military vehicle sustainment will gain traction as nations focus on sustainability and fuel efficiency.
- Strategic partnerships between defense contractors and technology firms will drive innovation in maintenance and repair solutions.
- Digital twin technology will become more prevalent, allowing real-time monitoring and predictive analysis of vehicle performance.
- NATO and EU-led defense collaborations will enhance interoperability and streamline sustainment strategies across multiple countries.
- The demand for third-party MRO service providers will rise as governments seek cost-effective maintenance solutions.
- Cybersecurity in sustainment operations will become a priority to protect digital infrastructure and vehicle communication networks.
- Automation and robotics will revolutionize repair and overhaul processes, improving efficiency and reducing human intervention.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Military Vehicle Sustainment market?
What factors are driving the growth of the Europe Military Vehicle Sustainment market?
What are the key segments within the Europe Military Vehicle Sustainment market?
What are some challenges faced by the Europe Military Vehicle Sustainment market?
Who are the major players in the Europe Military Vehicle Sustainment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Military Vehicle Sustainment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Military Vehicle Sustainment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,513.84 million → 2032: USD 7,868.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Military Vehicle Sustainment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Military Vehicle Sustainment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Military Vehicle Sustainment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Military Vehicle Sustainment Market Drivers
- 3.3 Europe Military Vehicle Sustainment Market Restraints & Challenges
- 3.4 Europe Military Vehicle Sustainment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Military Vehicle Sustainment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Military Vehicle Sustainment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Military Vehicle Sustainment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Military Vehicle Sustainment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Military Vehicle Sustainment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Military Vehicle Sustainment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Military Vehicle Sustainment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Military Vehicle Sustainment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Military Vehicle Sustainment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Military Vehicle Sustainment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Military Vehicle Sustainment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Military Vehicle Sustainment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Military Vehicle Sustainment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Military Vehicle Sustainment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Military Vehicle Sustainment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Military Vehicle Sustainment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Military Vehicle Sustainment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Military Vehicle Sustainment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Military Vehicle Sustainment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
