
Market Overview:
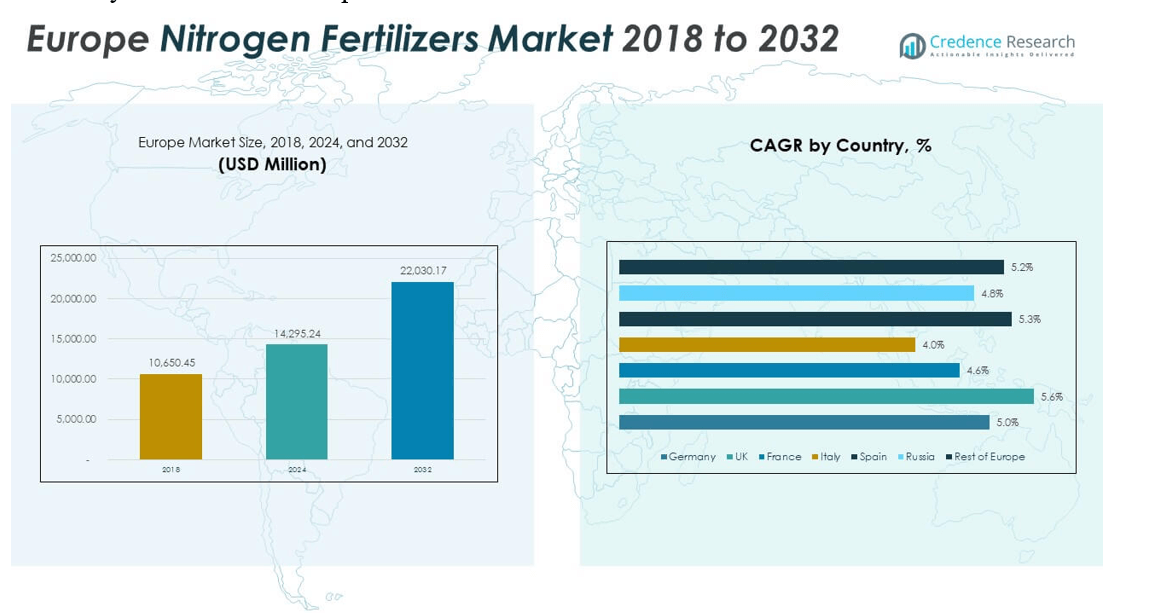
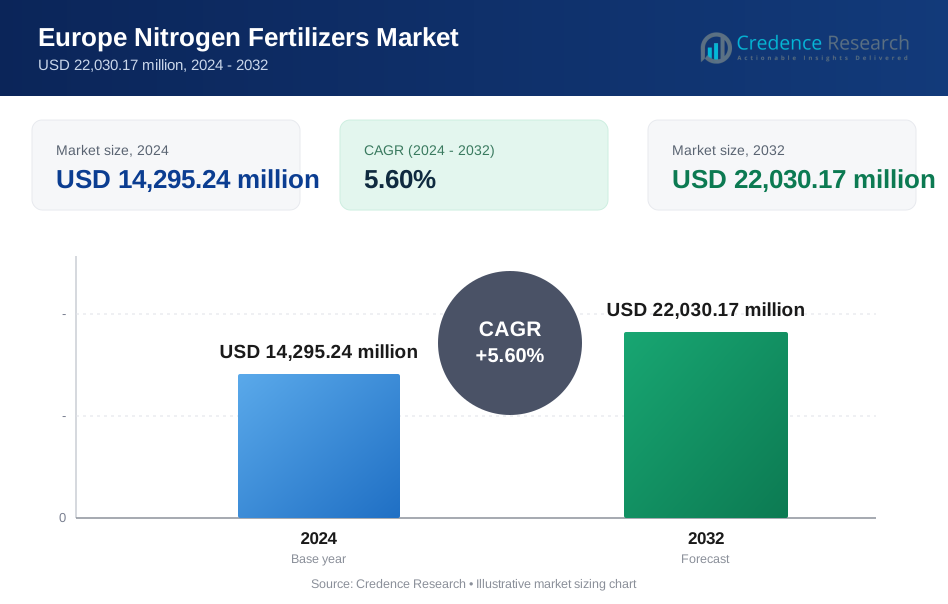
The Europe Nitrogen Fertilizers Market size was valued at USD 10,650.45 million in 2018 to USD 14,295.24 million in 2024 and is anticipated to reach USD 22,030.17 million by 2032, at a CAGR of 5.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Nitrogen Fertilizers Market Size 2024 | USD 14,295.24 million |
| Europe Nitrogen Fertilizers Market, CAGR | 5.60% |
| Europe Nitrogen Fertilizers Market Size 2032 | USD 22,030.17 million |
The Europe nitrogen fertilizers market is driven by rising food demand, expanding agricultural productivity, and increasing adoption of precision farming methods. Farmers rely on nitrogen-based fertilizers to enhance soil fertility and maximize yields of cereals, oilseeds, and horticultural crops. Government initiatives promoting sustainable farming and balanced nutrient management strengthen adoption. Shifts in dietary patterns toward protein-rich foods create added pressure on food production, which elevates fertilizer demand. Advanced technologies and training programs further support the growth trajectory of the market.
Western Europe leads the market with strong infrastructure, advanced farming practices, and significant fertilizer adoption across countries such as Germany, France, and the UK. Eastern Europe is emerging as a high-growth region, supported by modernization of agriculture and expansion of grain exports from countries like Poland and Romania. Southern Europe contributes notably with demand for liquid fertilizers in fruit, vegetable, and vineyard cultivation across Italy and Spain. Regional variations in crop production and farming systems shape overall market dynamics across Europe.
Market Insights
- The Europe Nitrogen Fertilizers Market was valued at USD 10,650.45 million in 2018, grew to USD 14,295.24 million in 2024, and is projected to reach USD 22,030.17 million by 2032 at a CAGR of 5.60%.
- Western Europe accounted for 42% share, driven by advanced farming practices, while Eastern Europe held 31% and Southern Europe 27%, reflecting strong agricultural diversification.
- Eastern Europe represents the fastest-growing region with 31% share, supported by modernization efforts and rising grain exports.
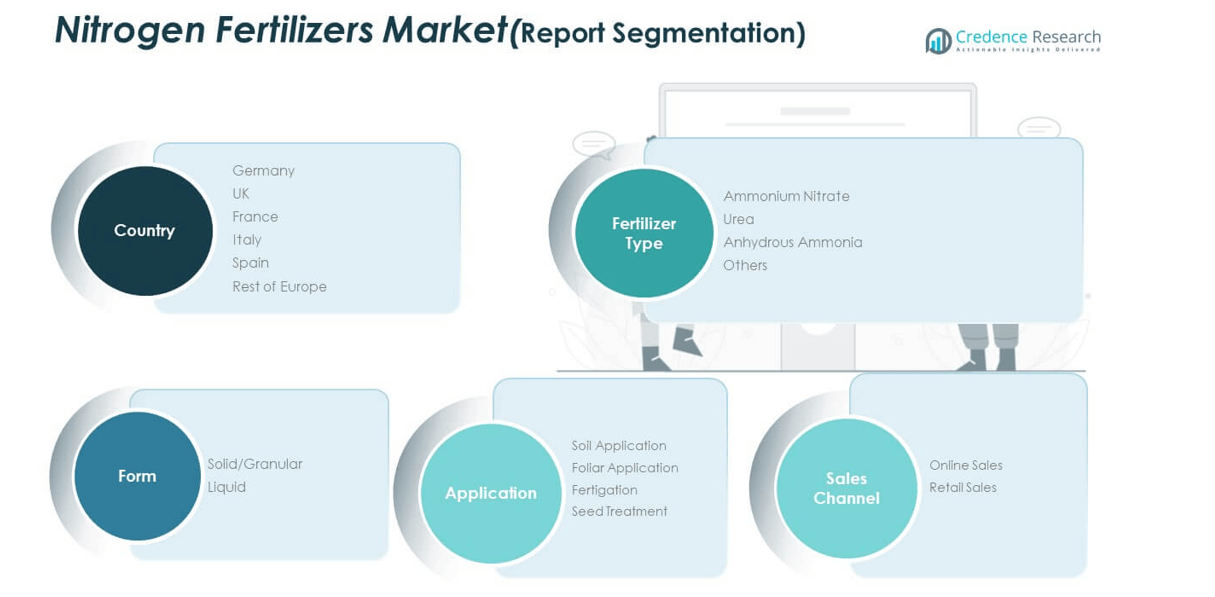
- Retail sales represented 65% of the Europe Nitrogen Fertilizers Market share, supported by strong accessibility and established distributor networks.
- Online sales accounted for 35% share, reflecting growing digital adoption and demand for faster, transparent product access.
Market Drivers
Rising Food Demand and Expanding Agricultural Productivity Across Europe
The rising population in Europe has pushed food demand to higher levels. Farmers must increase productivity to meet the region’s dietary needs. The Europe Nitrogen Fertilizers Market supports this demand by enhancing soil fertility and boosting yields. It helps sustain production of key crops including cereals, oilseeds, and fruits. Consumers prefer protein-rich diets, creating pressure on farmers to expand supply. Efficient fertilizers help maintain consistent output. Government policies favoring higher production targets add momentum. This driver keeps the market central to Europe’s food supply chain.
- For example, EuroChem supplied more than 16.5 million metric tons of fertilizers to global markets in 2022, despite losing over 1.5 million metric tons of potential output due to supply chain constraints, as reported in its official Annual Review.
Growing Focus on Soil Fertility Management and Balanced Nutrient Application
The need for sustainable agriculture has made soil fertility management a priority. Farmers apply nitrogen fertilizers to restore soil health and improve nutrient levels. The Europe Nitrogen Fertilizers Market benefits from increasing adoption of balanced nutrient strategies. It ensures optimum crop growth without exhausting natural resources. Fertilizer efficiency becomes vital for long-term soil productivity. Awareness programs help farmers understand nutrient requirements better. Agricultural agencies encourage balanced application methods. This driver strengthens the link between fertilizer use and sustainable soil health.
Government Support Through Subsidies and Favorable Agricultural Policies
Governments across Europe continue to offer subsidies to farmers for fertilizer adoption. These measures help reduce financial pressure on growers. The Europe Nitrogen Fertilizers Market gains strength from such institutional support. It ensures small and medium farmers access fertilizers at lower costs. Favorable agricultural policies prioritize stable food output. Policymakers promote precision farming practices for efficiency. Training initiatives encourage farmers to adapt innovative methods. This driver integrates government support with market expansion strategies.
- For instance, EuroChem highlighted in its 2022 Annual Review that its sales network spans 21 countries and serves over 10,000 customers worldwide, supporting small and medium farmers with timely fertilizer access and reinforcing stable production aligned with regional agricultural goals.
Technological Advancements and Precision Farming Practices in European Agriculture
Advanced technologies have changed farming methods across Europe. Farmers use precision farming tools to apply nitrogen fertilizers more effectively. The Europe Nitrogen Fertilizers Market expands through these innovations. It allows accurate measurement of soil conditions and nutrient requirements. Farmers reduce waste and maximize productivity with advanced solutions. Precision farming ensures fertilizers reach targeted areas directly. Technology-driven practices lower environmental risks. This driver creates long-term advantages for both producers and consumers.
Market Trends
Rising Adoption of Controlled-Release and Enhanced-Efficiency Fertilizers in Europe
Controlled-release products are gaining popularity among European farmers. They provide steady nutrient supply to crops over longer cycles. The Europe Nitrogen Fertilizers Market benefits from this rising demand. It reduces environmental risks linked to excessive application. Enhanced-efficiency fertilizers help improve nitrogen use rates. Farmers adopt these solutions to cut input costs. Agrochemical firms expand production of such innovative products. This trend reflects a shift toward precision and sustainability in farming practices.
- For example, in December 2024, Grupa Azoty launched eNpluS, a granular nitrogen fertilizer with sulfur and calcium produced at its Puławy and Kędzierzyn-Koźle facilities.
Integration of Digital Platforms and Smart Agriculture Tools in Fertilizer Use
Digital platforms are transforming the way fertilizers are applied. Farmers use sensors and software to track soil health and crop growth. The Europe Nitrogen Fertilizers Market adapts to this digital integration. It improves decision-making for nutrient application strategies. Data-driven tools reduce risks of overuse. Precision agriculture aligns with smart farming models across the region. Agritech startups bring new platforms into farming networks. This trend accelerates digital adoption across European agriculture.
- For example, in July 2024, Yara and PepsiCo Europe formed a partnership involving around 1,000 farms across the EU and UK, covering nearly 128,000 hectares, where farmers will use Yara’s AtFarm platform and MegaLab soil analysis alongside low-carbon fertilizers under the Yara Climate Choice range.
Growing Preference for Organic and Bio-Based Fertilizer Blends Alongside Nitrogen Fertilizers
Farmers show greater interest in bio-based alternatives to strengthen soil health. Organic fertilizers are often combined with nitrogen-based products for efficiency. The Europe Nitrogen Fertilizers Market adapts to this blended use. It reflects consumer demand for sustainable crop production. Bio-based solutions reduce environmental footprints. Retailers promote organic food, creating demand for eco-friendly inputs. Producers diversify portfolios to include hybrid fertilizer lines. This trend highlights the balance between sustainability and productivity.
Regional Expansion of Distribution Channels and Cross-Border Fertilizer Trade
Distribution networks play a growing role in fertilizer availability. European suppliers strengthen regional supply chains across borders. The Europe Nitrogen Fertilizers Market gains from wider access to rural farming zones. It improves timely delivery of fertilizers during peak seasons. Online platforms now support direct fertilizer sales. Distributors establish storage hubs for quicker delivery. Cross-border trade agreements enhance product flow within Europe. This trend reflects broader integration of the regional market system.
Market Challenges Analysis
Environmental Regulations and Rising Concerns Over Fertilizer Overuse in Europe
Strict regulations in Europe restrict excessive fertilizer use. Authorities aim to reduce nitrogen leaching into water bodies. The Europe Nitrogen Fertilizers Market faces pressure from compliance standards. It must adapt to environmental targets while sustaining growth. Farmers balance crop needs with policy limits. High penalties discourage overuse of nitrogen fertilizers. Public concerns about soil degradation amplify the challenge. This issue influences long-term market strategies across the region.
Volatile Raw Material Costs and Supply Chain Disruptions Impacting Fertilizer Prices
Rising energy costs influence nitrogen fertilizer production expenses. Supply chain disruptions affect timely product availability. The Europe Nitrogen Fertilizers Market struggles with fluctuating raw material prices. It creates uncertainty for farmers planning seasonal purchases. Import dependency in some regions worsens the challenge. Currency fluctuations impact trade dynamics further. Producers face difficulty in maintaining stable margins. This challenge creates long-term risks for consistent supply security.
Market Opportunities
Expansion of Sustainable Fertilizer Solutions and Growing Role of Green Ammonia in Europe
Sustainability goals push demand for green fertilizer solutions. Producers explore green ammonia as a nitrogen source. The Europe Nitrogen Fertilizers Market finds scope in this development. It aligns with Europe’s decarbonization targets. Farmers prefer sustainable inputs that maintain crop performance. Green solutions gain momentum in both Western and Eastern Europe. Companies invest in eco-friendly production plants. This opportunity strengthens the market’s long-term outlook.
Rising Demand for Customized Fertilizer Blends Tailored to Specific Crop Requirements
Farmers demand crop-specific fertilizer blends for better efficiency. Producers develop tailored nitrogen products for cereals, vegetables, and horticulture. The Europe Nitrogen Fertilizers Market grows by addressing this shift. It supports higher yields through precision nutrient supply. Customized blends minimize waste and increase soil health. Regional suppliers create products adapted to local soil conditions. This opportunity highlights innovation in product design. It drives future market competitiveness across Europe.
Market Segmentation Analysis
By fertilizer type, urea dominates the Europe Nitrogen Fertilizers Market due to its widespread use in cereals and horticulture. It is preferred for its high nitrogen content and cost efficiency. Ammonium nitrate maintains strong demand in regions with established grain farming. Anhydrous ammonia caters to large-scale producers focusing on efficiency. Other specialized fertilizers serve niche applications across diverse crops.
By form, solid or granular fertilizers lead the market because of easier handling and broader distribution networks. It remains the most common choice for both small and large farms. Liquid fertilizers are expanding in use, particularly in horticulture and vineyards. Farmers prefer liquid options for uniform application through irrigation systems. The balance between solid and liquid reflects diverse agricultural practices across the region.
- For instance, EuroChem Group’s Urea 46.2 Granulated formulation is widely produced in Europe, consistently delivering a guaranteed 46.2% nitrogen content per application, and is used in both broadacre cereal and specialty crop farming throughout the European Union.
By application, soil application holds the largest share due to its efficiency in delivering nutrients to crops. It supports major grain and oilseed production across Europe. Foliar application grows in demand for horticultural and high-value crops. Fertigation gains traction with modern irrigation systems, particularly in Southern Europe. Seed treatment remains a smaller segment but contributes to early crop protection.
- For instance, Poland reported the use of 1.0 million tonnes of nitrogen-based fertilizers in 2023, primarily for direct soil application on maize and wheat, according to Eurostat data. This made Poland one of the top three European countries by applied nitrogen fertilizer volumes in agriculture.
By sales channel, retail sales dominate through agricultural suppliers and distributors. It ensures accessibility for farmers in rural areas. Online sales gain momentum as digital platforms expand, offering faster delivery and product transparency. It provides farmers with broader choices and enhances competition among suppliers. This mix reflects the evolving distribution structure of the fertilizer industry.
Segmentation
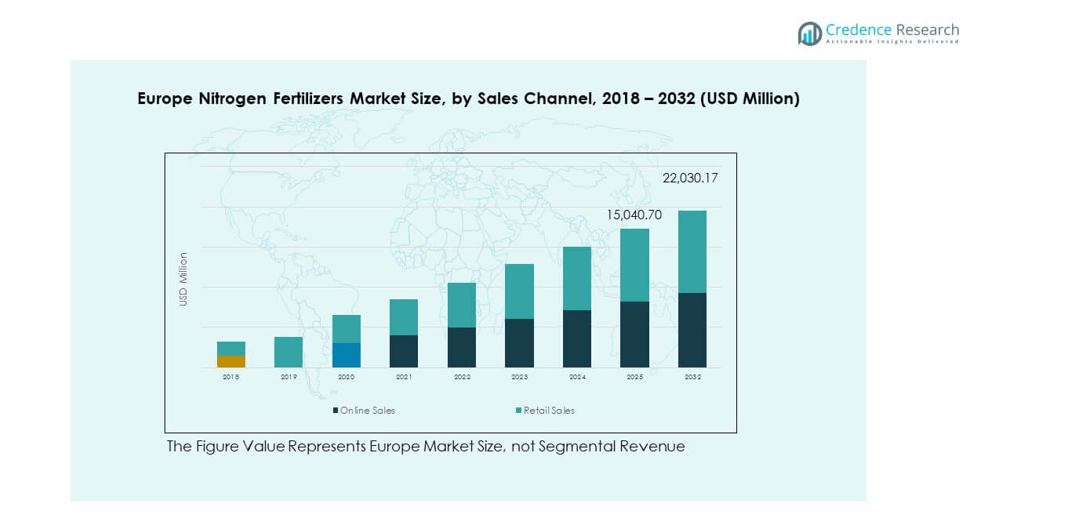
By Fertilizer Type
- Ammonium Nitrate
- Urea
- Anhydrous Ammonia
- Others
By Form
- Solid/Granular
- Liquid
By Application
- Soil Application
- Foliar Application
- Fertigation
- Seed Treatment
By Sales Channel
- Online Sales
- Retail Sales
By Country
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Regional Analysis
Western Europe holds the largest share of the Europe Nitrogen Fertilizers Market with 42%. Countries such as Germany, France, and the UK dominate due to advanced agricultural practices and strong infrastructure. It benefits from government support for sustainable farming and precision technologies. The region shows high demand for ammonium nitrate and urea, particularly in cereals and horticulture. Strong distribution networks ensure timely supply to large-scale farms. Western Europe continues to set benchmarks for innovation and environmental compliance.
Eastern Europe accounts for 31% of the Europe Nitrogen Fertilizers Market. Countries including Poland, Romania, and Ukraine focus on expanding production capacity to strengthen exports. It experiences rising adoption of modern farming inputs driven by crop diversification. Fertilizer demand is high for grains and oilseeds, reflecting the region’s role as a major supplier to global markets. Modernization of agriculture and supportive policies enhance market growth. Eastern Europe provides significant opportunities for suppliers aiming to capture emerging demand.
Southern Europe holds 27% share of the Europe Nitrogen Fertilizers Market. Italy, Spain, and Greece drive this growth due to strong cultivation of fruits, vegetables, and vineyards. It relies heavily on urea and liquid fertilizers to support intensive horticulture. High-value crops and irrigation systems increase demand for efficient nitrogen solutions. Farmers seek tailored fertilizer blends for diverse soil conditions. Southern Europe positions itself as a specialized hub for horticultural and niche crop fertilizer use.
Key Player Analysis
- Yara International ASA
- EuroChem Group
- OCI N.V.
- Grupa Azoty
- K+S AG
- Lovochemie
- Fertiberia
- Agrofert
- Achema
- Other Key Players
Competitive Analysis
The Europe Nitrogen Fertilizers Market is highly competitive with the presence of multinational producers and regional firms. Leading companies include Yara International ASA, EuroChem Group, OCI N.V., Grupa Azoty, K+S AG, Lovochemie, Fertiberia, Agrofert, and Achema. It is marked by strong competition on pricing, product innovation, and distribution strength. Yara International ASA leads with advanced product portfolios and significant regional presence. EuroChem Group and OCI N.V. focus on capacity expansion and trade efficiency. Grupa Azoty and Fertiberia concentrate on serving domestic and neighboring markets with tailored solutions. K+S AG and Agrofert enhance competitiveness through diversified fertilizer offerings. Emerging players such as Lovochemie and Achema strengthen regional supply, contributing to overall market resilience. The competitive environment encourages investment in sustainable technologies and efficiency improvements, shaping long-term market positioning.
Recent Developments
- In September 2025, Yara International ASA signed a definitive offtake agreement with ATOME PLC, confirming the purchase of renewable fertilizer volumes targeted at key European markets. Yara also continues to strengthen its portfolio of low-carbon ammonia and crop nutrition solutions, seeking to enhance sustainable agriculture through new partnerships and commercial agreements across Europe.
- In October 2024, OCI N.V. sold its entire equity stake (50% plus one share) in Fertiglobe PLC to ADNOC (Abu Dhabi National Oil Company). The deal raised OCI’s strategic liquidity and allowed ADNOC to increase its holding in Fertiglobe to over 86%, giving ADNOC more control over the nitrogen fertilizer platform.
Report Coverage
The research report offers an in-depth analysis based on Fertilizer Type, Form, Application and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Nitrogen Fertilizers Market will experience steady expansion with growing food demand across the region.
- Rising protein-based diets will push fertilizer demand for cereals, grains, and horticultural crops.
- Precision farming adoption will enhance efficiency, reducing wastage and improving soil nutrient balance.
- Controlled-release and enhanced-efficiency fertilizers will see higher uptake in advanced agricultural systems.
- Government initiatives will support sustainable fertilizer practices through subsidies and training programs.
- Green ammonia and eco-friendly fertilizer solutions will gain traction in meeting climate goals.
- Eastern Europe will emerge as a stronger contributor, driven by modernization and export growth.
- Southern Europe will strengthen demand for liquid fertilizers due to horticulture and vineyard expansion.
- Digital tools and agritech platforms will accelerate smart fertilizer management across farming practices.
- Competitive pressures will push companies to expand portfolios with sustainable and customized blends.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Food Demand and Expanding Agricultural Productivity
Europe's growing population and shifting dietary preferences toward protein-rich foods are increasing the need for higher crop yields, driving demand for nitrogen fertilizers to boost soil fertility and maximize output of cereals, oilseeds, and horticultural crops.
Government Support and Favorable Agricultural Policies
Subsidies and supportive policies across Europe reduce financial barriers for farmers, encouraging the adoption of nitrogen fertilizers and precision farming practices, which in turn sustains stable food production and market growth.
Technological Advancements and Precision Farming
The integration of advanced technologies and precision agriculture tools enables more efficient and targeted application of nitrogen fertilizers, reducing waste, improving yields, and supporting sustainable farming practices.
Focus on Soil Fertility Management and Balanced Nutrient Application
Increasing awareness of sustainable agriculture and soil health is driving the adoption of balanced nutrient management strategies, with nitrogen fertilizers playing a key role in restoring soil fertility and supporting long-term productivity.
Expansion of Sustainable and Green Fertilizer Solutions
The push for decarbonization and environmental compliance in Europe is accelerating the development and adoption of green ammonia and eco-friendly nitrogen fertilizers, aligning with climate goals and opening new market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Nitrogen Fertilizers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Nitrogen Fertilizers Market projected to grow between 2024 and 2032?
Which Europe Nitrogen Fertilizers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Nitrogen Fertilizers Market?
Who are the leading companies in the Europe Nitrogen Fertilizers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Solid/Granular
- 1.2.2 Liquid
- 1.3 By Application
- 1.3.1 Soil Application
- 1.3.2 Foliar Application
- 1.3.3 Fertigation
- 1.3.4 Seed Treatment
- 1.4 By Sales Channel
- 1.4.1 Retail Sales
- 1.4.2 Online Sales
- 1.5 By Fertilizer Type
- 1.5.1 Ammonium Nitrate
- 1.5.2 Urea
- 1.5.3 Anhydrous Ammonia
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,295.24 million → 2032: USD 22,030.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Nitrogen Fertilizers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Nitrogen Fertilizers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Nitrogen Fertilizers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Nitrogen Fertilizers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Nitrogen Fertilizers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Nitrogen Fertilizers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Nitrogen Fertilizers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Nitrogen Fertilizers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,295.24 million → 2032: USD 22,030.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Nitrogen Fertilizers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solid/Granular
- 12.3.7.2 Liquid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soil Application
- 12.4.7.2 Foliar Application
- 12.4.7.3 Fertigation
- 12.4.7.4 Seed Treatment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Retail Sales
- 12.5.7.2 Online Sales
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Fertilizer Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Ammonium Nitrate
- 12.6.7.2 Urea
- 12.6.7.3 Anhydrous Ammonia
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Nitrogen Fertilizers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Nitrogen Fertilizers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Nitrogen Fertilizers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Nitrogen Fertilizers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yara International ASA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 EuroChem Group
- 18.4 OCI N.V.
- 18.5 Grupa Azoty
- 18.6 K+S AG
- 18.7 Lovochemie
- 18.8 Fertiberia
- 18.9 Agrofert
- 18.10 Achema
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

