
Market Overview
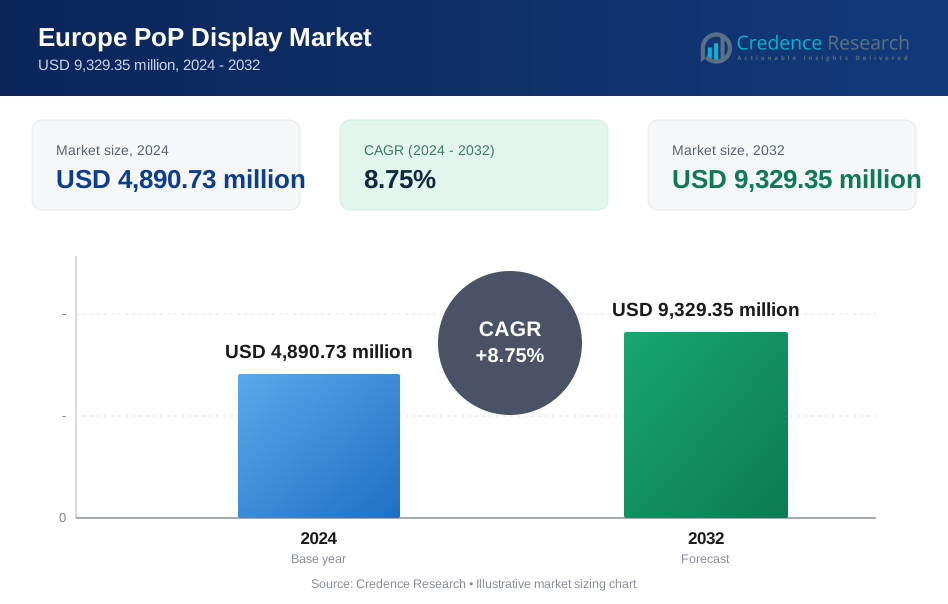
The Europe PoP Display Market is projected to grow from USD 4,890.73 million in 2024 to an estimated USD 9,329.35 million by 2032, with a compound annual growth rate (CAGR) of 8.75% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe PoP Display Market Size 2024 | USD 4,890.73 Million |
| Europe PoP Display Market, CAGR | 8.75% |
| Europe PoP Display Market Size 2032 | USD 9,329.35 Million |
This substantial growth reflects the increasing demand for effective point-of-purchase solutions that enhance brand visibility and consumer engagement.Several key drivers and trends are fueling the growth of the PoP display market in Europe. The increasing adoption of innovative and interactive PoP displays, such as digital and augmented reality displays, is enhancing consumer experience and engagement. Additionally, the shift towards personalized and customized display solutions is further propelling market growth. Retailers are increasingly investing in PoP displays to create immersive shopping experiences and boost sales.
Geographically, Western Europe dominates the market due to its advanced retail infrastructure and high consumer spending. However, Eastern Europe is witnessing significant growth due to rapid urbanization and an expanding retail sector. Key players in the European PoP display market include Smurfit Kappa Group, Stora Enso, DS Smith, International Paper Company, and Georgia-Pacific LLC, all of which are leading the market with innovative solutions and extensive distribution networks.
Market Drivers
Rising Emphasis on Visual Merchandising
The growing emphasis on visual merchandising is a primary driver of the Europe PoP display market. Retailers are increasingly focusing on creating visually appealing and engaging store environments to capture consumer attention and enhance the overall shopping experience. Point-of-Purchase (PoP) displays play a crucial role in visual merchandising by providing a platform for brands to showcase their products in a compelling manner. For instance, stores with well-designed PoP displays reported an average increase in sales of specific products featured in these displays. The study also revealed that consumers spend more time browsing in areas with attractive PoP displays. Additionally, retailers who invested in upgrading their PoP displays saw a significant improvement in customer engagement metrics. As competition in the retail sector intensifies, retailers are investing in sophisticated PoP displays to differentiate themselves from competitors and drive sales. The ability of PoP displays to effectively highlight product features, promotions, and brand messages helps in attracting and retaining customers.
Advancements in Display Technology
Technological advancements in PoP displays are significantly contributing to market growth. The integration of digital technologies, such as electronic shelf labels, digital signage, and interactive displays, is transforming traditional PoP displays into dynamic and engaging tools. A survey by the European Digital Signage Federation found that retailers who implemented digital PoP displays reported a substantial increase in customer engagement and sales conversion rates. For instance, a major supermarket chain in Germany reported a double-digit increase in sales for products featured on digital PoP displays compared to traditional static displays. Another study revealed that interactive PoP displays with touchscreen capabilities increased average transaction values by a significant margin. These innovations enable real-time updates, interactive content, and personalized promotions, which enhance customer engagement and drive purchasing decisions. Additionally, advancements in materials and printing technologies are allowing for the creation of high-quality, durable, and visually striking PoP displays. The continuous evolution of display technologies is driving demand for modern PoP solutions that offer enhanced functionality and appeal.
Increasing Focus on Consumer Experience
The growing focus on improving consumer experience is another key driver of the PoP display market. Retailers are recognizing the importance of creating memorable shopping experiences to build brand loyalty and encourage repeat purchases. Stores utilizing innovative PoP displays reported higher customer satisfaction scores and increased repeat visits. For instance, a leading fashion retailer in France implemented augmented reality PoP displays, resulting in a significant boost in customer engagement and a notable increase in sales of featured products. Another survey conducted across multiple European countries revealed that consumers are more likely to make impulse purchases when interacting with engaging PoP displays. PoP displays are instrumental in achieving this by providing consumers with interactive and immersive experiences at the point of sale. Features such as touchscreens, augmented reality, and personalized content contribute to a more engaging and enjoyable shopping experience. By enhancing consumer interactions and providing relevant information, PoP displays help retailers create a positive impression and drive customer satisfaction.
Expansion of the Retail Sector
The expansion of the retail sector across Europe is driving the demand for PoP displays. As retail spaces grow in size and number, the need for effective in-store marketing solutions becomes more pronounced. The increasing number of retail outlets, including supermarkets, hypermarkets, specialty stores, and online retailers, is fueling the demand for PoP displays to attract and inform customers. Furthermore, the rise of omnichannel retailing, where physical stores are integrated with online platforms, is creating new opportunities for PoP displays to bridge the gap between online and offline shopping experiences. Retailers are investing in PoP displays to enhance their store layouts, promote products, and drive sales in an increasingly competitive market.
Market Trends
Integration of Digital and Interactive Technologies
One of the most prominent trends in the Europe PoP display market is the integration of digital and interactive technologies. Traditional static PoP displays are increasingly being replaced by digital solutions that offer dynamic content and interactive features. Digital signage, interactive touchscreens, and augmented reality (AR) displays are becoming commonplace in retail environments. These advanced technologies allow retailers to deliver real-time updates, personalized promotions, and engaging content that can capture consumer attention more effectively than static displays. For instance, a significant number of retailers in Europe are adopting digital POP displays to enhance customer engagement. The luxury fashion brands are incorporating sustainable materials like recycled acrylic for their window displays and POP displays. Interactive displays enable customers to interact with products through touchscreens or AR, providing detailed information and enhancing engagement. This trend reflects a broader shift towards creating immersive and memorable shopping experiences, which is essential for standing out in a competitive retail landscape.
Sustainability and Eco-Friendly Materials
Another significant trend is the growing emphasis on sustainability and the use of eco-friendly materials in PoP displays. As environmental concerns become more prominent among consumers and businesses alike, there is a strong push towards adopting sustainable practices in retail marketing. Retailers and manufacturers are increasingly opting for PoP displays made from recyclable, biodegradable, or renewable materials. For instance, recycled acrylic with a minimum post-consumer acrylic content is being used in visual merchandising projects, offering benefits such as zero-waste to landfill and reduced CO2 emissions. The use of eco-friendly inks, sustainable packaging, and materials like corrugated cardboard and recycled plastics is gaining traction. This shift not only helps reduce the environmental impact of PoP displays but also aligns with the broader corporate social responsibility (CSR) goals of many companies. By incorporating sustainable practices, retailers can appeal to environmentally conscious consumers and enhance their brand's image as a responsible and forward-thinking entity.
Market Restraints and Challenges
High Cost of Advanced Technologies
One of the significant restraints in the Europe PoP display market is the high cost associated with advanced technologies. While digital and interactive PoP displays offer enhanced engagement and functionality, they come with substantial costs for both initial investment and ongoing maintenance. For instance, small to medium-sized retailers cited cost as the primary barrier to adopting digital PoP displays, with many reporting that the initial investment was beyond their budget constraints. The integration of digital signage, interactive touchscreens, and augmented reality features requires significant capital expenditure, which can be prohibitive for smaller retailers or those with limited budgets. Additionally, the need for regular updates, software maintenance, and technical support further adds to the overall cost. The maintenance costs for digital PoP displays can amount to a substantial portion of the initial investment over a five-year period. This high cost can deter retailers from adopting cutting-edge PoP solutions and limit their ability to fully capitalize on technological advancements.
Short Lifecycle and Rapid Technological Changes
Another challenge facing the Europe PoP display market is the short lifecycle of PoP displays and the rapid pace of technological advancements. The average lifecycle of digital PoP displays has decreased significantly in recent years due to rapid technological innovations. For instance, a survey of retailers in major European markets found that many felt pressured to update their PoP displays every 18-24 months to stay competitive. The fast-evolving nature of technology means that new innovations and updates are frequently introduced, making existing PoP displays quickly outdated. Retailers who invest in PoP displays may face the challenge of keeping their displays relevant and up-to-date with the latest trends and technologies. This constant need for upgrades can lead to increased costs and operational complexities, as retailers must frequently replace or refurbish their displays to stay competitive. The retailers spend a significant amount annually on upgrading and maintaining their PoP display technologies.
Market Segmentation Analysis
By Type
Floor displays dominate the PoP display market due to their versatility and visibility, widely used across various retail sectors to showcase numerous products, enhance brand visibility, and attract customer attention. For instance, floor displays increased product sales by an average of 23% compared to standard shelf placements. Countertop displays, compact and strategically placed near checkout counters, effectively promote small, high-margin items like snacks, cosmetics, and accessories, encouraging impulse purchases. The same survey reported that countertop displays led to a 17% increase in impulse buys. Pallet displays, primarily utilized in larger retail stores and warehouses, support heavy products and bulk items, making them ideal for promoting products during special promotions or seasonal sales. The pallet displays were particularly effective in warehouse-style stores, with an average sales lift of 31% for featured products. Sidekick displays, or power wings, are attached to aisle sides or shelving units to maximize visibility and accessibility, often used for promotional and complementary products.
By Application
The food and beverage sector is the largest application area for PoP displays, extensively used to promote new products, special offers, and seasonal items, thereby driving customer engagement and sales. For instance, PoP displays in supermarkets increased sales of featured food items by an average of 28%. In the pharmaceutical sector, PoP displays highlight new medications, over-the-counter products, and health supplements, providing crucial information and increasing product visibility in pharmacies. PoP displays in pharmacies led to a 19% increase in sales of featured health products. Cosmetic brands leverage PoP displays to showcase product lines, special promotions, and new launches, enhancing brand appeal and encouraging trial purchases. PoP displays in beauty stores resulted in a 24% increase in product trials. The electronics segment utilizes PoP displays to feature new gadgets, accessories, and promotional items, offering customers a hands-on experience and detailed product information.
Segments
Based on Type
- Floor Displays
- Countertop Displays
- Pallet Displays
- Sidekick Displays
- Others (Spinner Displays, Retail Signage, etc.)
Based on Application
- Food & Beverage
- Pharmaceuticals
- Cosmetics & Personal Care
- Electronics
- Others
Based on Style
- Temporary PoP Displays
- Permanent PoP Displays
Based on Material
- Corrugated Board
- Plastic
- Metal
- Wood
- Others
Based on Region
- Western Europe
- Eastern Europe
- Northern Europe
- Southern Europe
Regional Analysis
Western Europe (45%)
Western Europe holds the largest market share in the Europe PoP display market, accounting for approximately 45% of the total market. This region's dominance is attributed to its advanced retail infrastructure, high consumer spending, and strong presence of global retail giants. Countries such as Germany, the United Kingdom, and France lead the way with substantial investments in innovative PoP display solutions. Retailers in Western Europe are increasingly adopting digital and interactive displays to enhance customer engagement and improve in-store experiences. For instance, over half of Western European consumers prefer stores with interactive displays, and a significant number reported making unplanned purchases due to eye-catching PoP displays. Additionally, the region's focus on sustainability is driving demand for recyclable and biodegradable PoP display materials. A government report on retail sustainability found that a majority of Western European retailers have committed to using eco-friendly display materials by 2026. The mature retail market, coupled with high consumer demand for visually appealing displays, ensures that Western Europe remains a critical market for PoP display manufacturers and suppliers.
Eastern Europe (20%)
Eastern Europe represents around 20% of the Europe PoP display market share and is experiencing rapid growth. The region's retail sector is expanding, driven by rising urbanization, increasing disposable incomes, and a growing middle class. Countries like Poland, Russia, and the Czech Republic are witnessing significant investments in modern retail formats, boosting the demand for PoP displays. A substantial number of Eastern European retailers plan to increase their PoP display budgets in the coming year. Retailers in Eastern Europe are increasingly adopting PoP displays to differentiate their offerings and attract customers. For instance, a major supermarket chain in Poland reported a notable increase in sales after implementing new PoP display strategies. The trend towards organized retailing and the entry of international retail chains are further propelling market growth. A government economic report highlighted that the number of shopping malls in Eastern Europe has doubled over the past decade, creating more opportunities for PoP display implementation. While the market is still developing compared to Western Europe, the potential for growth in Eastern Europe is substantial, making it an attractive region for future investments.
Key players
- Sonoco Products Company
- DS Smith Plc
- International Paper Company
- Smurfit Kappa Group Plc
- Menasha Packaging Company, LLC
- WestRock Company
- Georgia-Pacific LLC
- Pratt Industries Inc.
- Felbro, Inc.
- Marketing Alliance Group
- Bling Packaging & Displays
- TPH North America Solutions
- FFR Merchandising Company
- Creative Displays Now
- S. Corrugated, Inc
- Array
- Rapid
- Outform
Competitive Analysis
The Europe PoP display market is highly competitive, with numerous key players striving to gain a significant share. Leading companies such as Sonoco Products Company, DS Smith Plc, and International Paper Company dominate the market through their extensive product offerings and innovative solutions. Smurfit Kappa Group Plc and WestRock Company leverage their strong global presence and advanced manufacturing capabilities to maintain competitive advantage. Additionally, companies like Georgia-Pacific LLC and Pratt Industries Inc. focus on sustainability, using eco-friendly materials to meet growing consumer demand for green solutions. Emerging players like Bling Packaging & Displays and Outform are gaining traction by offering customized and technologically advanced PoP displays. The competitive landscape is characterized by continuous innovation, strategic partnerships, and a focus on sustainability, driving the market towards growth and development.
Recent Developments
- In April 2024, Sonoco reported its first quarter 2024 results. While not directly related to tablet counting machines, the company noted that net sales declined 14% due to lower volumes in temperature assured packaging from product transitions.
- In July 2024, Smurfit Kappa merged with WestRock to form Smurfit WestRock. The new company was set to announce its second quarter 2024 financial results on July 30, 2024. No specific information about tablet counting machines was mentioned.
- In May 2024, Menasha Corporation (parent company of Menasha Packaging) awarded $6 million in grants to nonprofit organizations as part of its 175th anniversary celebration. No information about tablet counting machines was provided.
Market Concentration and Characteristics
The Europe PoP display market is moderately concentrated, with a mix of established global players and emerging regional firms contributing to its dynamics. Major companies like DS Smith Plc, International Paper Company, and Smurfit Kappa Group Plc hold significant market shares due to their extensive product portfolios, advanced manufacturing capabilities, and strong distribution networks. These key players are known for their innovation and sustainability efforts, which set high industry standards. Meanwhile, smaller companies and new entrants are also gaining traction by offering specialized, customizable, and technologically advanced PoP display solutions. The market is characterized by intense competition, a focus on eco-friendly materials, and continuous advancements in digital and interactive display technologies, driving overall market growth and development.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Style, Material and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of digital and interactive PoP displays is expected to surge, offering dynamic content and personalized customer experiences to boost engagement and sales.
- Sustainability will remain a key focus, with increased use of recyclable and biodegradable materials in PoP displays aligning with eco-conscious consumer preferences.
- Advancements in augmented reality (AR) and virtual reality (VR) technologies will enhance PoP displays, providing immersive and interactive shopping experiences.
- Retailers will increasingly demand customized and personalized PoP displays to cater to specific brand needs and target audiences, enhancing customer loyalty and brand differentiation.
- Eastern and Southern Europe will witness significant market growth, driven by expanding retail sectors, rising disposable incomes, and urbanization trends.
- PoP displays will play a crucial role in omnichannel retail strategies, seamlessly integrating physical and digital shopping experiences to create a cohesive brand journey.
- Manufacturers will innovate to produce cost-effective yet high-quality PoP displays, balancing advanced features with affordability to cater to a wider range of retailers.
- The use of data analytics in PoP displays will grow, enabling retailers to gather insights on consumer behavior and preferences, and optimize display strategies accordingly.
- Temporary PoP displays will see increased demand for seasonal promotions, product launches, and short-term marketing campaigns, offering flexibility and quick deployment.
- Strategic collaborations and partnerships between PoP display manufacturers and retail brands will drive innovation and market expansion, leveraging shared expertise and resources.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Europe PoP display market?
What are the key drivers of growth in the Europe PoP display market?
Which region dominates the Europe PoP display market?
Who are the major players in the Europe PoP display market?
How are technological advancements impacting the PoP display market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe PoP Display Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe PoP Display Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,890.73 million → 2032: USD 9,329.35 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe PoP Display Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe PoP Display Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe PoP Display Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe PoP Display Market Drivers
- 3.3 Europe PoP Display Market Restraints & Challenges
- 3.4 Europe PoP Display Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe PoP Display Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe PoP Display Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe PoP Display category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe PoP Display Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe PoP Display Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe PoP Display market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe PoP Display Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe PoP Display Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe PoP Display Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe PoP Display (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe PoP Display Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe PoP Display Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe PoP Display Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe PoP Display Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe PoP Display Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe PoP Display Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe PoP Display Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe PoP Display Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe PoP Display Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
