
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Explosion Proof Equipment Market Size 2024 | USD 7,390.97 million |
| Explosion Proof Equipment Market, CAGR | 6.44% |
| Explosion Proof Equipment MarketSize 2032 | USD 12,108.03 million |
Market Overview
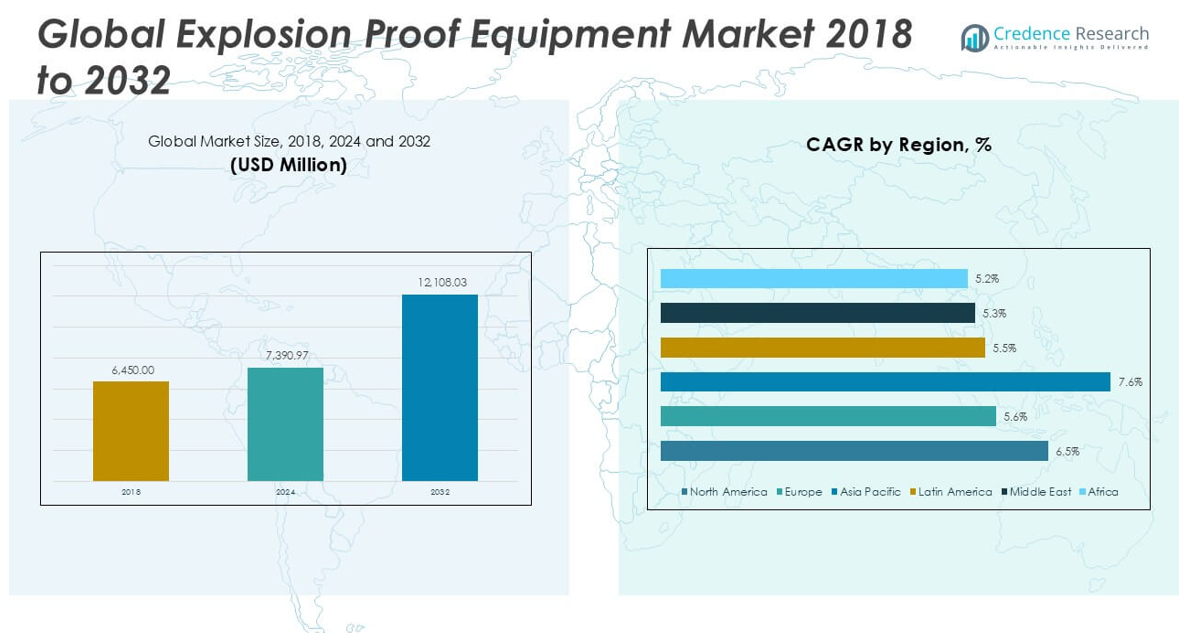
The Explosion Proof Equipment market size was valued at USD 6,450.00 million in 2018, reached USD 7,390.97 million in 2024, and is anticipated to reach USD 12,108.03 million by 2032, at a CAGR of 6.44% during the forecast period.
The Explosion Proof Equipment market is highly competitive, with key players such as Adalet, Siemens, Honeywell International Plc., Rockwell Automation Inc., ABB, Eaton Corporation, Emerson Electric Co., Warom Technology Inc., WorkSite Lighting, Extronics Ltd., Alloy Industry Co. Ltd, Tomar Electronics Inc., Potter Electric Signal Co. LLC, Federal Signal Corporation, and Pepperl+Fuchs SE leading the industry. These companies focus on expanding their product portfolios, strategic partnerships, and technological advancements to strengthen their market presence. North America dominates the market, holding a 34.4% share in 2024, driven by stringent safety regulations and advanced industrial infrastructure. Asia Pacific follows closely, propelled by rapid industrialization and rising safety awareness.
Market Insights
- The Explosion Proof Equipment market was valued at USD 7,390.97 million in 2024 and is expected to reach USD 12,108.03 million by 2032, growing at a CAGR of 6.44% during the forecast period.
- Increasing demand for explosion-proof solutions is driven by strict safety regulations, rising industrial activities, and the expansion of oil & gas, chemical, and mining sectors worldwide.
- Key market trends include the integration of smart monitoring systems, IoT-enabled explosion-proof devices, and growing adoption in emerging economies like Asia Pacific.
- The market is highly competitive with major players such as Siemens, Honeywell International Plc., ABB, Eaton Corporation, and Emerson Electric Co. focusing on product innovation, strategic partnerships, and global expansion.
- North America leads with a 34.4% market share, followed by Europe and Asia Pacific, while high equipment costs and complex certification processes remain significant market restraints, especially for small and medium enterprises.
Market Segmentation Analysis:
By Protection Method
In the Explosion Proof Equipment market, Explosion Prevention holds the largest market share among the protection methods. This dominance is driven by the increasing adoption of preventive technologies aimed at minimizing the risk of explosion through controlled environments and intrinsically safe equipment. Industries prioritize explosion prevention due to its cost-effectiveness and regulatory compliance advantages. Explosion Containment and Explosion Segregation are also gaining attention, particularly in high-risk environments, but remain secondary to prevention strategies as companies increasingly focus on proactive safety measures to protect assets and workforce.
- For instance, Siemens offers its intrinsically safe SIMATIC ET 200SP system with over 500 certified safety modules designed specifically to prevent ignition in hazardous environments.
By Industry Segment
The Oil & Gas industry is the leading segment in the Explosion Proof Equipment market, accounting for the highest revenue share due to the inherently hazardous nature of oil exploration, drilling, and refining processes. Strict safety regulations and the need to prevent catastrophic failures drive the demand in this sector. The Chemical & Petrochemical and Mining industries also significantly contribute to the market, while sectors such as Energy & Power, Manufacturing, Food Processing, and Pharmaceuticals are steadily increasing adoption to enhance workplace safety and operational reliability in potentially explosive environments.
- For instance, Honeywell International Plc. provides over 60,000 installed units of its X-series fixed gas detectors across oil and gas facilities globally, supporting critical explosionprevention in high-risk environments.
By System Segment
Within the system segment, Junction Boxes & Enclosures dominate the market, driven by their essential role in safely housing electrical components and preventing ignition sources from contacting explosive atmospheres. These systems are widely used across various industries due to their versatility and critical function in explosion prevention. Communication & Networking Systems and Monitoring Systems, including Explosion-Proof Cameras and Sensors, are rapidly growing due to the rising need for real-time data acquisition and remote monitoring in hazardous zones. Additionally, the increasing deployment of Automation Systems and advanced Signaling Devices further propels market growth in this segment.
Market Overview
Stringent Safety Regulations and Standards
The Explosion Proof Equipment market is significantly driven by the increasing enforcement of stringent safety regulations across industries such as oil & gas, chemicals, and mining. Regulatory bodies mandate the use of certified explosion-proof systems to safeguard personnel and infrastructure in hazardous environments. Compliance with standards like ATEX and IECEx is essential, pushing companies to invest in high-quality explosion-proof equipment. This regulatory pressure not only ensures workplace safety but also creates consistent demand for reliable, certified solutions, thereby accelerating market growth across key industrial sectors.
- For instance, Pepperl+Fuchs SE has developed more than 1,500 explosion-proof components certified to both ATEX and IECEx standards, widely deployed across European and Middle Eastern chemical plants.
Expansion of Hazardous Industrial Operations
The rapid expansion of hazardous industrial operations, particularly in oil & gas exploration, chemical processing, and mining activities, is a major growth driver for the Explosion Proof Equipment market. Increasing global energy demand and the need to access challenging reserves have led to more operations in potentially explosive environments. These activities necessitate robust explosion-proof systems to mitigate risks, fueling the demand for advanced protection methods and systems. As industries continue to venture into complex and high-risk zones, the reliance on explosion-proof equipment is expected to grow steadily.
- For instance, ABB has delivered over 10,000 explosion-proof motor starters to offshore oil rigs in the Gulf of Mexico to support safe drilling and production activities.
Rising Demand for Automation and Smart Monitoring
Growing emphasis on industrial automation and smart monitoring solutions is enhancing the demand for advanced explosion-proof equipment. Integration of real-time monitoring systems, explosion-proof sensors, and smart communication devices in hazardous locations improves operational efficiency and safety. Companies seek automated solutions to remotely control and monitor critical assets, reducing human exposure to dangerous areas. The convergence of explosion-proof technology with IoT and Industry 4.0 trends is opening new growth avenues, enabling safer and more efficient operations in high-risk industrial settings.
Key Trends & Opportunities
Integration of Wireless and IoT-Based Systems
A key trend in the Explosion Proof Equipment market is the increasing integration of wireless communication and IoT-enabled devices. Companies are adopting explosion-proof access points, routers, and smart sensors that offer real-time monitoring and data transmission in hazardous areas. This trend enhances remote operation capabilities and predictive maintenance, reducing downtime and improving safety. The shift towards smart, connected equipment presents significant opportunities for manufacturers to develop advanced solutions that align with Industry 4.0 and digital transformation initiatives in hazardous industries.
- For instance, Emerson Electric Co. has deployed over 8,000 wireless, explosion-proof vibration monitoring sensors in refineries and chemical plants worldwide to enable predictive maintenance.
Growing Adoption in Emerging Economies
The growing industrialization in emerging economies presents a substantial opportunity for the Explosion Proof Equipment market. Rapid infrastructure development and increased oil & gas exploration in regions such as Asia Pacific, the Middle East, and Latin America are driving demand for explosion-proof systems. Local regulatory frameworks are gradually aligning with international safety standards, prompting industries to invest in certified equipment. This creates favorable conditions for market expansion as companies look to tap into these high-growth regions with tailored, cost-effective solutions.
- For instance, Warom Technology Inc. has supplied more than 12,000 explosion-proof lighting units to petrochemical facilities in China and Southeast Asia, supporting regional safety upgrades.
Key Challenges
High Initial Investment and Maintenance Costs
One of the primary challenges in the Explosion Proof Equipment market is the high initial investment and ongoing maintenance costs associated with these systems. Explosion-proof equipment requires specialized materials and complex engineering, leading to higher pricing compared to conventional systems. Additionally, regular maintenance and stringent inspection protocols increase operational expenses. These cost factors can deter small and medium enterprises from adopting explosion-proof solutions, especially in price-sensitive markets, thereby restraining broader market penetration.
Complex Certification Processes
The certification and approval processes for explosion-proof equipment are highly complex and time-consuming. Meeting the stringent requirements of global standards such as ATEX, IECEx, and UL involves extensive product testing and documentation. This can delay product launches and increase costs for manufacturers, particularly when targeting multiple international markets with varying certification criteria. The complexity of obtaining and maintaining these certifications often poses a barrier for new entrants and can limit the pace of innovation and market expansion.
Limited Awareness in Developing Regions
Limited awareness regarding the importance and availability of explosion-proof equipment in developing regions poses a significant market challenge. Many industries in these areas continue to operate without fully understanding the risks associated with explosive environments or the benefits of explosion-proof systems. This lack of awareness results in slower adoption rates, despite increasing regulatory efforts. Addressing this gap through educational initiatives, partnerships, and targeted marketing is essential to unlocking growth potential in these emerging markets.
Regional Analysis
North America
North America holds a significant share of the Explosion Proof Equipment market, accounting for approximately 34.4% of the global market in 2024, with a market size of USD 2,521.98 million, up from USD 2,225.25 million in 2018. The region is projected to reach USD 4,153.72 million by 2032, growing at a CAGR of 6.5%. This growth is primarily driven by strict regulatory frameworks, advanced industrial infrastructure, and the presence of major oil, gas, and chemical manufacturing facilities. Continuous investments in safety upgrades and the rapid adoption of advanced monitoring systems further contribute to market expansion in this region.
Europe
Europe represents 27.5% of the global Explosion Proof Equipment market in 2024, with a market size of USD 2,030.84 million, rising from USD 1,838.25 million in 2018. The market is expected to grow to USD 3,133.23 million by 2032 at a CAGR of 5.6%. Growth in Europe is supported by robust industrial safety regulations, especially in countries like Germany, the UK, and France. The well-established chemical, oil, and energy sectors prioritize explosion-proof solutions to comply with strict safety standards, while advancements in automation and industrial IoT also support continued demand across the region.
Asia Pacific
Asia Pacific is the fastest-growing region in the Explosion Proof Equipment market, holding around 26.5% market share in 2024 with a market size of USD 1,957.47 million, up from USD 1,638.30 million in 2018. The market is projected to reach USD 3,498.24 million by 2032, growing at a CAGR of 7.6%. Rapid industrialization, expanding oil & gas exploration, and increasing investments in chemical and manufacturing sectors drive the region's growth. Countries like China, India, and Japan are major contributors, with growing awareness and stricter safety regulations boosting the adoption of explosion-proof equipment across various industries.
Latin America
Latin America accounts for approximately 5.4% of the global Explosion Proof Equipment market in 2024, with a market size of USD 398.30 million, rising from USD 351.53 million in 2018. The market is anticipated to reach USD 603.83 million by 2032, growing at a CAGR of 5.5%. Growth is primarily supported by ongoing development in oil & gas extraction, mining operations, and energy infrastructure, particularly in countries like Brazil and Mexico. Increasing regulatory focus on workplace safety and gradual industrial modernization are contributing to the steady rise in demand for explosion-proof solutions in the region.
Middle East
The Middle East holds a 4.2% market share in 2024 in the Explosion Proof Equipment market, with a market size of USD 255.68 million, up from USD 238.65 million in 2018. The market is expected to reach USD 382.53 million by 2032, growing at a CAGR of 5.3%. The dominance of oil & gas operations in this region is a key growth driver, as these industries consistently require explosion-proof systems to ensure safety. Ongoing investments in petrochemical and energy projects, alongside growing industrialization, are expected to further support the steady demand for explosion-proof equipment across the Middle East.
Africa
Africa represents 3.1% of the global Explosion Proof Equipment market in 2024, with a market size of USD 226.70 million, increasing from USD 158.03 million in 2018. The market is projected to reach USD 336.48 million by 2032, expanding at a CAGR of 5.2%. Africa’s market growth is driven by the gradual expansion of mining, oil & gas, and chemical processing industries, particularly in countries like Nigeria and South Africa. Although the region currently has a smaller share, increasing safety awareness and growing infrastructure investments are expected to support consistent growth in explosion-proof equipment adoption.
Market Segmentations:
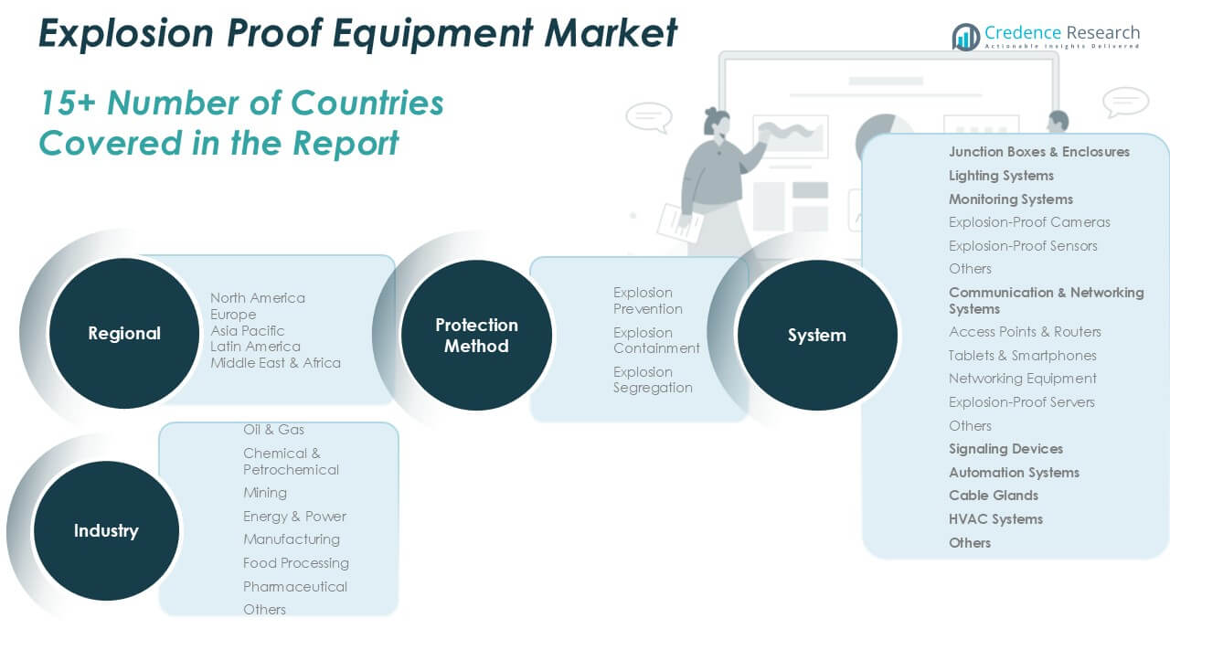
By Protection Method
- Explosion Prevention
- Explosion Containment
- Explosion Segregation
By Industry
- Oil & Gas
- Chemical & Petrochemical
- Mining
- Energy & Power
- Manufacturing
- Food Processing
- Pharmaceutical
- Others
By System
- Junction Boxes & Enclosures
- Lighting Systems
- Monitoring Systems
- Explosion-Proof Cameras
- Explosion-Proof Sensors
- Others
- Communication & Networking Systems
- Access Points & Routers
- Tablets & Smartphones
- Networking Equipment
- Explosion-Proof Servers
- Others
- Signaling Devices
- Automation Systems
- Cable Glands
- HVAC Systems
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Explosion Proof Equipment market is characterized by the presence of several global and regional players actively competing through product innovation, strategic collaborations, and geographic expansion. Leading companies such as Siemens, Honeywell International Plc., ABB, Eaton Corporation, Emerson Electric Co., and Adalet consistently invest in developing advanced, certified explosion-proof solutions to meet evolving industry safety standards. These players focus on integrating smart technologies like IoT-enabled monitoring systems and wireless communication devices to strengthen their market positions. Additionally, companies such as Warom Technology Inc., Extronics Ltd., and Pepperl+Fuchs SE are expanding their portfolios to address the rising demand across emerging markets. Mergers, acquisitions, and partnerships remain key strategies to enhance global reach and technological capabilities. Intense competition drives continuous product development and pricing strategies to capture market share, particularly in high-growth regions like Asia Pacific and North America. However, the market also presents barriers for new entrants due to stringent certification requirements and high investment costs.
Key Player Analysis
- Adalet
- Siemens
- Honeywell International Plc.
- Rockwell Automation Inc.
- ABB
- Eaton Corporation
- Emerson Electric Co.
- Warom Technology Inc.
- WorkSite Lighting
- Extronics Ltd.
- Alloy Industry Co. Ltd
- Tomar Electronics Inc.
- Potter Electric Signal Co. LLC
- Federal Signal Corporation
- Pepperl+Fuchs SE
Recent Developments
- In June 2024, Honeywell International Plc. acquired the Enraf Holding B.V. agreement valued at approximately USD 260 million. The company consists of six groups, including a division called Enraf Fluid Technology, which is a custom-engineered explosion-proof precision blending and additive metering equipment manufacturer.
- In March 2024, Emerson Electric Co. launched a new Acoustic Particle Monitor, Rosemount SAM42, for measuring entrained sand in the oil & gas wells output. The new products feature explosion proof protection along with onboard data processing.
- In November 2024, Konecranes expanded its explosion-proof equipment portfolio with the launch of the EX C-series electric chain hoist, engineered for use in Zone 1/2/21 hazardous environments. Introduced across the EMEA and APAC regions, the hoist incorporates advanced safety and efficiency features, making it ideal for operations in explosive atmospheres such as oil refineries, chemical plants, and gas facilities.
- In August 2022, ARCHON Industries, Inc. launched the EX20100 explosion-proof light, specifically engineered to provide continuous illumination for various industrial equipment in hazardous and non-hazardous areas. Designed for use in Class I Division I Group C&D and Class I Division II Group C&D locations, the luminaire enhances safety and visibility in challenging environments
- In April 2022, Mitsubishi Heavy Industries, Ltd., in partnership with ENEOS Corporation, introduced the second-generation 'EX ROVR' plant inspection robot with explosion-proof capabilities. Utilizing remote maintenance technology, it enhances worker safety, increases work efficiency, and ensures continuous facility inspections in potentially explosive atmospheres, catering to the demands of the explosion-proof equipment market.
Market Concentration & Characteristics
The Explosion Proof Equipment Market demonstrates a moderately concentrated structure, dominated by several established multinational companies with strong technological capabilities and extensive product portfolios. It features a competitive environment where leading players continuously introduce certified and innovative explosion-proof solutions to meet stringent safety standards across industries. The market focuses on serving high-risk sectors, including oil and gas, chemicals, mining, and energy, which demand reliable, high-performance equipment. It emphasizes safety, regulatory compliance, and durability, which drive manufacturers to prioritize product quality and certification. The market shows steady demand from developed regions, particularly North America and Europe, while Asia Pacific presents significant growth potential due to rapid industrialization and increasing safety awareness. Barriers to entry remain high due to complex certification processes, significant initial investments, and the need for advanced engineering capabilities. It rewards companies that offer technologically advanced, cost-efficient, and easily integrated solutions. Competitive pricing, product reliability, and strong distribution networks are key factors that influence market positioning.
Report Coverage
The research report offers an in-depth analysis based on Protection Method, Industry, System and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for explosion-proof equipment will increase with stricter global safety regulations across hazardous industries.
- Rapid industrialization in Asia Pacific will create strong growth opportunities for explosion-proof equipment manufacturers.
- Companies will continue to integrate IoT and smart monitoring technologies into explosion-proof systems.
- The oil and gas sector will remain the largest end-user, sustaining steady demand for explosion-proof solutions.
- Wireless communication and remote monitoring capabilities will become essential features in future product designs.
- Manufacturers will invest in product innovation to offer lighter, more cost-effective, and durable explosion-proof equipment.
- High equipment costs and complex certification processes will continue to challenge small and medium enterprises.
- Mergers and acquisitions will shape market dynamics as companies seek to expand their global reach and technology base.
- The food processing and pharmaceutical industries will gradually increase their adoption of explosion-proof systems.
- North America and Europe will maintain strong market shares, while Asia Pacific will emerge as the fastest-growing region.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Safety Regulations and Standards
Global enforcement of safety standards such as ATEX and IECEx compels industries to adopt certified explosion-proof equipment, ensuring workplace safety and regulatory compliance, which drives consistent market demand.
Expansion of Hazardous Industrial Operations
Growth in oil & gas exploration, chemical processing, and mining activities increases the need for robust explosion-proof systems to mitigate risks in potentially explosive environments, fueling market expansion.
Integration of IoT and Smart Monitoring
The adoption of IoT-enabled explosion-proof devices and real-time monitoring systems enhances operational safety and efficiency, prompting industries to upgrade to advanced, connected equipment.
Rapid Industrialization in Emerging Economies
Accelerated industrial growth in Asia Pacific, the Middle East, and Latin America, coupled with rising safety awareness and regulatory alignment, is boosting demand for explosion-proof solutions in these high-growth regions.
Technological Advancements and Product Innovation
Continuous innovation in explosion-proof equipment, such as lighter materials, wireless communication, and predictive maintenance features, is expanding application possibilities and attracting new industry segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Explosion Proof Equipment Market?
What are the key segments within the Explosion Proof Equipment Market?
What are some challenges faced by the Explosion Proof Equipment Market?
Who are the major players in the Explosion Proof Equipment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By System
- 1.2.1 Junction Boxes & Enclosures
- 1.2.2 Lighting Systems
- 1.2.3 Monitoring Systems
- 1.2.4 Communication & Networking Systems
- 1.2.5 Signaling Devices
- 1.2.6 Automation Systems
- 1.2.7 Cable Glands
- 1.2.8 HVAC Systems
- 1.2.9 Others
- 1.3 By Industry
- 1.3.1 Oil & Gas
- 1.3.2 Chemical & Petrochemical
- 1.3.3 Mining
- 1.3.4 Energy & Power
- 1.3.5 Manufacturing
- 1.3.6 Food Processing
- 1.3.7 Pharmaceutical
- 1.3.8 Others
- 1.4 By Protection Method
- 1.4.1 Explosion Prevention
- 1.4.2 Explosion Containment
- 1.4.3 Explosion Segregation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,390.97 million → 2032: USD 12,108.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Explosion Proof Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Explosion Proof Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Explosion Proof Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Explosion Proof Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Explosion Proof Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Explosion Proof Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Explosion Proof Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Explosion Proof Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,390.97 million → 2032: USD 12,108.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Explosion Proof Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By System - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Junction Boxes & Enclosures
- 12.3.7.2 Lighting Systems
- 12.3.7.3 Monitoring Systems
- 12.3.7.4 Communication & Networking Systems
- 12.3.7.5 Signaling Devices
- 12.3.7.6 Automation Systems
- 12.3.7.7 Cable Glands
- 12.3.7.8 HVAC Systems
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil & Gas
- 12.4.7.2 Chemical & Petrochemical
- 12.4.7.3 Mining
- 12.4.7.4 Energy & Power
- 12.4.7.5 Manufacturing
- 12.4.7.6 Food Processing
- 12.4.7.7 Pharmaceutical
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Protection Method - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Explosion Prevention
- 12.5.7.2 Explosion Containment
- 12.5.7.3 Explosion Segregation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Explosion Proof Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Explosion Proof Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Explosion Proof Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Explosion Proof Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Plc.
- 18.4 ABB
- 18.5 Eaton Corporation
- 18.6 Emerson Electric Co.
- 18.7 Adalet
- 18.8 Warom Technology Inc.
- 18.9 Extronics Ltd.
- 18.10 Pepperl+Fuchs SE
- 18.11 Rockwell Automation Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

