
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Artificial Intelligence in Hardware Market Size 2023 | USD 56,175 million |
| Artificial Intelligence in Hardware Market, CAGR | 15.6% |
| Artificial Intelligence in Hardware Market Size 2032 | USD 179,145.4 million |
Market Overview
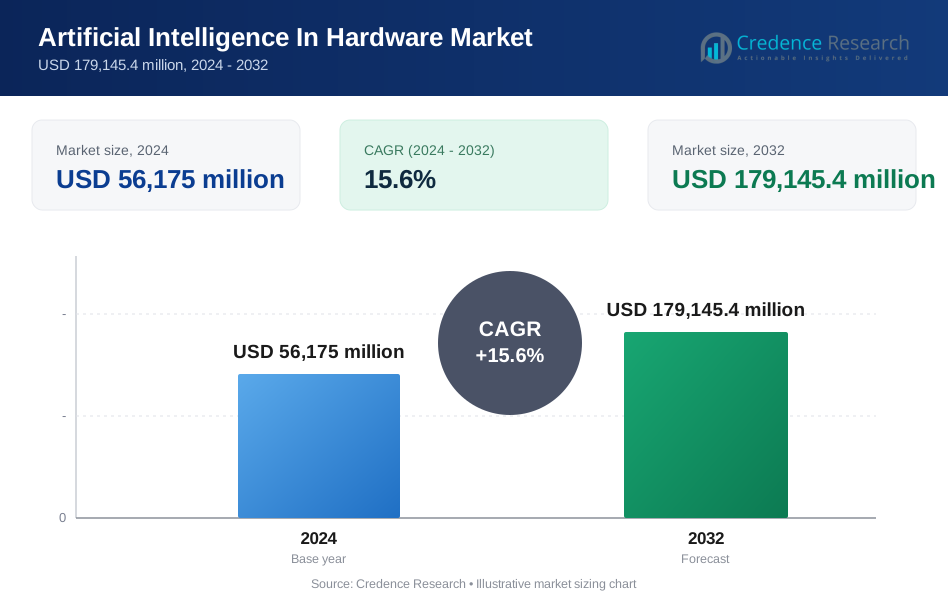
The Artificial Intelligence in Hardware market is projected to grow from USD 56,175 million in 2024 to USD 179,145.4 million by 2032, reflecting a compound annual growth rate (CAGR) of 15.6%.
The Artificial Intelligence in Hardware market is driven by advancements in AI technology, increasing demand for AI-powered devices, and significant investments in research and development. Rapid innovations in semiconductor technologies and growing adoption of AI in sectors like automotive, healthcare, and consumer electronics further propel market growth. Additionally, the integration of AI with edge computing and the rise of smart devices contribute to a robust demand for AI-enhanced hardware solutions. These factors collectively drive the expansion of the market, as industries seek to leverage AI for enhanced performance and efficiency.
The Artificial Intelligence in Hardware market is geographically diverse, with significant contributions from North America, Asia Pacific, and Europe. North America, led by key players such as Apple, Intel, NVIDIA, and Google, dominates the market due to advanced technological infrastructure and substantial R&D investments. In Asia Pacific, companies like Huawei Technologies and Samsung Electronics drive growth with their robust technological advancements and expanding consumer base. Europe also plays a vital role, with a growing emphasis on AI hardware innovations. These key players across regions are crucial in shaping the market dynamics and driving global advancements in AI hardware.
Market Drivers
Advancements in AI Algorithms
Significant progress in AI algorithms is fueling market expansion. Deep learning has seen remarkable advancements, particularly in image recognition, natural language processing, and speech synthesis. For example, advancements in deep learning have improved image recognition capabilities, enabling more accurate medical diagnoses. Machine learning algorithms are evolving, becoming more adept at handling complex datasets and providing more accurate insights. For instance, reinforcement learning has enhanced autonomous systems, allowing for better decision-making in dynamic environments. These developments enhance the capabilities of AI hardware, driving demand for more sophisticated and powerful processing units that can manage advanced computational tasks.
Data Explosion
The explosion of data is a critical factor driving the AI hardware market. The growing volume, variety, and velocity of big data necessitate powerful hardware for effective processing and analysis. For instance, the demand for AI chips in data centers is increasing to handle the vast amounts of data generated by AI applications. Cloud computing platforms support this need by offering scalable infrastructure and storage solutions for large datasets. As data continues to expand, the requirement for robust AI hardware capable of managing and analyzing substantial data loads becomes increasingly essential, fostering market growth and innovation.
Growing Demand for Real-Time Processing
The need for real-time processing is accelerating demand for AI hardware. Edge computing applications, which require low latency and instantaneous decision-making, are pivotal in areas such as autonomous vehicles and IoT devices. The proliferation of Internet of Things (IoT) devices generates vast amounts of data that must be processed and analyzed in real-time, further propelling the demand for efficient AI hardware solutions capable of handling such high-speed data requirements.
Increased Adoption of AI Across Industries
The rising adoption of AI across various sectors is a primary driver for the Artificial Intelligence in Hardware market. In healthcare, AI technologies enhance medical image analysis, facilitate drug discovery, and support personalized medicine. The automotive industry benefits from AI through autonomous vehicles and advanced driver assistance systems, which rely on sophisticated AI hardware. Financial services use AI for fraud detection, algorithmic trading, and customer service optimization. Retailers leverage AI-powered recommendation systems and inventory management solutions to boost customer experience and operational efficiency. Additionally, the manufacturing sector employs AI for predictive maintenance, quality control, and process automation, showcasing its broad industrial impact.
Market Trends
Rise of Specialized and Cloud-Based AI Hardware
The advancement and adoption of specialized AI hardware are reshaping the market landscape. Application-Specific Integrated Circuits (ASICs) are engineered for specific AI tasks, offering exceptional performance and energy efficiency tailored to particular applications. For instance, companies are developing ASICs that significantly enhance the speed and efficiency of AI computations. Field-Programmable Gate Arrays (FPGAs), with their flexibility, can be reconfigured for various AI tasks, making them suitable for diverse applications. For instance, government surveys indicate that FPGAs are being increasingly used in real-time data processing applications. Tensor Processing Units (TPUs), developed by Google, are optimized for machine learning workloads, particularly deep learning, enhancing computational efficiency. Similarly, Neural Processing Units (NPUs) are specifically designed for neural networks, providing high performance with low power consumption. For instance, companies are integrating NPUs into edge devices to improve performance while reducing energy consumption. These specialized hardware solutions cater to the growing demand for advanced AI processing capabilities, optimizing performance for various applications.
Focus on Energy Efficiency and Integration with Emerging Technologies
Energy efficiency is becoming increasingly crucial in the AI hardware sector, driven by the need to reduce power consumption in both edge devices and data centers. Manufacturers are responding by developing innovative hardware architectures and cooling solutions that minimize energy use while maintaining performance. These advancements not only contribute to operational cost savings but also align with broader sustainability goals, addressing environmental concerns associated with energy-intensive AI operations. Moreover, the integration of AI hardware with emerging technologies is enhancing its functionality and impact. The rollout of 5G networks promises to support AI applications requiring real-time processing by enabling faster data transfer and reduced latency. The growing Internet of Things (IoT) ecosystem also highlights the critical role of AI hardware in processing and analyzing data from a vast array of connected devices. Additionally, AI’s application in blockchain technology is improving security and efficiency, further extending the utility of AI hardware. These integrations underscore the dynamic interplay between AI hardware and other technological advancements, shaping the future of AI-driven solutions.
Market Challenges Analysis
High Costs and Power Consumption
The high costs associated with AI hardware pose significant challenges. Developing and manufacturing specialized AI hardware, such as Tensor Processing Units (TPUs) and Neural Processing Units (NPUs), involves substantial financial investment due to the complexity of design and production. For instance, the International Energy Agency (IEA) forecasts that energy consumption for AI is likely to double from 460 terawatt-hours (TWh) in 2022 to 1,000 TWh in 2026. Additionally, ongoing research and development efforts aimed at enhancing AI hardware performance and efficiency further contribute to these high costs. These expenses can be a barrier to entry for smaller companies or new entrants in the market. Power consumption is another critical issue impacting the AI hardware market. AI hardware, particularly for edge devices and data centers, often requires significant amounts of energy to operate effectively. This high power consumption not only raises operational costs but also poses environmental concerns. The need for robust cooling solutions to manage the heat generated by intensive computational processes further exacerbates these challenges. Increased cooling requirements lead to additional costs and can contribute to environmental impacts, highlighting the need for more energy-efficient and sustainable hardware solutions.
Complexity and Limited Availability
The complexity of designing and developing AI hardware presents considerable challenges. Creating advanced AI systems necessitates specialized expertise and sophisticated tools, making the design process intricate and resource-intensive. Integrating AI hardware with existing systems and components adds another layer of complexity, requiring careful coordination and technical knowledge. Limited availability of AI hardware, driven by supply chain constraints and market competition, also poses significant challenges. The production of specialized components can be hampered by supply chain issues, which impact availability and drive up prices. Furthermore, intense competition among hardware manufacturers can limit the supply of critical components, making it difficult for some companies to secure the necessary hardware for their needs. These factors collectively contribute to the challenges faced in the AI hardware market, affecting both costs and accessibility.
Market Segmentation Analysis:
By Type:
The Artificial Intelligence in Hardware market is segmented into four key types: processor, memory, network, and storage. Processors are critical for executing AI algorithms and include GPUs, TPUs, and NPUs, designed to handle complex computations and enhance performance. Memory components, such as RAM and high-speed storage, are essential for managing large data sets and ensuring efficient data processing. Network hardware supports the connectivity and communication required for distributed AI systems, including switches, routers, and network interface cards. Storage solutions cater to the vast amounts of data generated and processed by AI systems, utilizing high-capacity and high-speed storage devices. Each segment plays a vital role in the AI hardware ecosystem, contributing to the overall performance and efficiency of AI applications.
By End-User:
The end-user segment of the Artificial Intelligence in Hardware market includes a diverse range of industries. The telecommunication and IT industry leverages AI hardware for network management, data processing, and service optimization. In the banking and finance sectors, AI is used for fraud detection, algorithmic trading, and customer service. Education institutions use AI hardware for advanced learning tools and research applications. The ecommerce sector benefits from AI-powered recommendation systems and inventory management. Navigation and robotics industries rely on AI hardware for autonomous systems and advanced automation. Agriculture utilizes AI for precision farming and data analysis. The healthcare sector employs AI hardware for medical imaging, diagnostics, and personalized treatment. Other industries also contribute to the market, showcasing the broad applicability of AI hardware across various sectors.
Segments:
Based on Type
- Processor
- Memory
- Network
- Storage
Based on End User
- Telecommunication and IT industry
- banking and finance sectors
- Education
- Ecommerce
- Navigation
- Robotics
- Agriculture
- Health care
- Others
Based on Product Type
- CPU
- GPU
- ASIC
- FPGA
- Memory
- Storage
- Modules
Based on Application
- Training & Simulation
- Driver Monitoring Systems
- Surveillance & Security
- Imaging & Diagnosis
- Robotic Surgery
- Disaster Management
- Visual Inspection
- Others
Based on Technology
- Machine Learning
- Supervised Learning
- Un-supervised Learning
- Deep Learning
- Others
- Computer Vision
- Others
Based on Material
- Silicon
- GaN
- Glass
- Metal
- Others
Based on Devices
- Smartphones & Tablets
- Personal Computing Devices
- Autonomous Robots
- UAVs/UGVs
- HUD
- Others
Based on Deployment
- Cloud
- Cloud Platforms
- Private Cloud
- Public Cloud
- Hybrid Cloud
- Community Cloud
- Cloud Services
- SaaS
- IaaS
- PaaS
- Others
- Cloud Platforms
- On-premise
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Artificial Intelligence in Hardware market, accounting for approximately 40% of the global market. The region's leadership is attributed to its advanced technological infrastructure, high investment in AI research and development, and robust presence of major tech companies. The United States, in particular, is a hub for innovation, with substantial funding directed toward AI hardware advancements. The demand for AI hardware in North America is driven by its extensive application across sectors such as finance, healthcare, and telecommunications. The region's focus on developing cutting-edge technologies, coupled with favorable government policies and substantial investments in AI startups, continues to propel its dominance in the market.
Asia-Pacific
Asia Pacific is experiencing rapid growth in the Artificial Intelligence in Hardware market, currently holding a market share of around 30%. This growth is fueled by the region's increasing adoption of AI technologies and significant advancements in its technology infrastructure. Countries like China and India are major contributors, with extensive investments in AI research, development, and manufacturing. The expanding tech industry, coupled with a large and growing consumer base, drives demand for AI hardware in various applications, including smart devices, robotics, and healthcare. Additionally, government initiatives and strategic partnerships in the region are enhancing the development and deployment of AI hardware, positioning Asia Pacific as a critical player in the global AI hardware market.
Key Player Analysis
- Apple (US)
- Intel (US)
- NVIDIA (US)
- Qualcomm Technologies (US)
- IBM (US)
- Micron Technology (US)
- Xilinx (US)
- Google (US)
- Microsoft (US)
- AMD (US)
- Huawei Technologies (China)
- Samsung Electronics (South Korea)
Competitive Analysis
The competitive landscape of the Artificial Intelligence in Hardware market is shaped by several leading players, including NVIDIA Corporation, Intel Corporation, Xilinx, Inc., Qualcomm Technologies, Inc., IBM Corporation, Apple and Microsoft Corporation. These companies are focused on advancing AI hardware solutions, ranging from GPUs, FPGAs, and custom ASICs to AI accelerators. The market is driven by the need for efficient processing capabilities, higher power efficiency, and optimized hardware for AI model integration. With increased investment in research and development, the competition centers around enhancing hardware performance, minimizing latency, and offering scalable AI solutions tailored to diverse industry needs.
Recent Developments
- In June 2024, Apple introduced Apple Intelligence, a personal intelligence system for iPhone, iPad, and Mac, combining generative models with personal context to deliver useful and relevant intelligence.
- In January 2024, NVIDIA announced GeForce RTX SUPER desktop GPUs for generative AI performance and new AI laptops from top manufacturers.
- In April 2024, IBM partnered with Canada and Quebec to secure the future of chipmaking in North America.
- December 2023, Google introduced Gemini, its most capable AI model yet, optimized for various sizes and tasks.
- In December 2023, Intel launched the Intel Core Ultra mobile processor family and the 5th Gen Intel Xeon processors, both featuring AI acceleration.
Market Concentration & Characteristics
The Artificial Intelligence in Hardware market exhibits a high degree of concentration, with a few dominant players significantly influencing market dynamics. Major firms like NVIDIA, Intel, AMD, IBM, and Google lead the market by continually advancing their AI hardware solutions, which include GPUs, TPUs, and specialized processors. These players leverage substantial R&D investments and technological expertise to maintain competitive advantages and drive innovation. The market is characterized by rapid technological advancements and intense competition, as companies strive to develop hardware that meets the growing demands of AI applications, from data centers to edge computing. High barriers to entry, including significant capital requirements and specialized knowledge, further contribute to market concentration. Additionally, the market is marked by strategic partnerships and collaborations among leading firms to enhance their product offerings and expand their market reach, reinforcing the competitive landscape and shaping future trends.
Report Coverage
The research report offers an in-depth analysis based on Type, End-User, Product Type, Application, Technology, Material, Devices, Deployment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing adoption of AI across various sectors will drive robust growth in the AI hardware market.
- Advances in semiconductor technology will enhance the performance and efficiency of AI hardware.
- The demand for edge AI solutions will rise, leading to innovations in compact and high-performance hardware.
- Integration of AI hardware with 5G technology will enable faster data processing and real-time applications.
- Expansion of AI in data centers will push for more powerful and scalable AI processors.
- Development of specialized AI chips will cater to specific applications such as autonomous vehicles and healthcare.
- Growth in AI research and development will lead to new hardware innovations and product offerings.
- Increased focus on energy efficiency will drive advancements in low-power AI hardware solutions.
- Strategic partnerships and collaborations among tech giants will accelerate the development and deployment of AI hardware.
- The rise of AI-driven edge computing will necessitate advancements in hardware designed for localized, real-time processing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Artificial Intelligence in Hardware Market?
What factors are driving the growth of the Artificial Intelligence in Hardware Market?
What are the key segments within the Artificial Intelligence in Hardware Market?
Who are the major players in the Artificial Intelligence in Hardware Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Artificial Intelligence In Hardware Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Artificial Intelligence In Hardware Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 56,175 million → 2032: USD 179,145.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Artificial Intelligence In Hardware Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Artificial Intelligence In Hardware Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Artificial Intelligence In Hardware Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Artificial Intelligence In Hardware Market Drivers
- 3.3 Artificial Intelligence In Hardware Market Restraints & Challenges
- 3.4 Artificial Intelligence In Hardware Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Artificial Intelligence In Hardware Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Artificial Intelligence In Hardware Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Artificial Intelligence In Hardware category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Artificial Intelligence In Hardware Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Artificial Intelligence In Hardware Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Artificial Intelligence In Hardware market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Artificial Intelligence In Hardware Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Artificial Intelligence In Hardware Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Artificial Intelligence In Hardware Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Artificial Intelligence In Hardware (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Artificial Intelligence In Hardware Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Artificial Intelligence In Hardware Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Artificial Intelligence In Hardware Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Artificial Intelligence In Hardware Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Artificial Intelligence In Hardware Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Artificial Intelligence In Hardware Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Artificial Intelligence In Hardware Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Artificial Intelligence In Hardware Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Artificial Intelligence In Hardware Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
