
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Food Fortification market Size 2024 | USD 106,695 million |
| Food Fortification market, CAGR | 10.30% |
| Food Fortification market Size 2032 | USD 233,748.14 million |
Market Overview
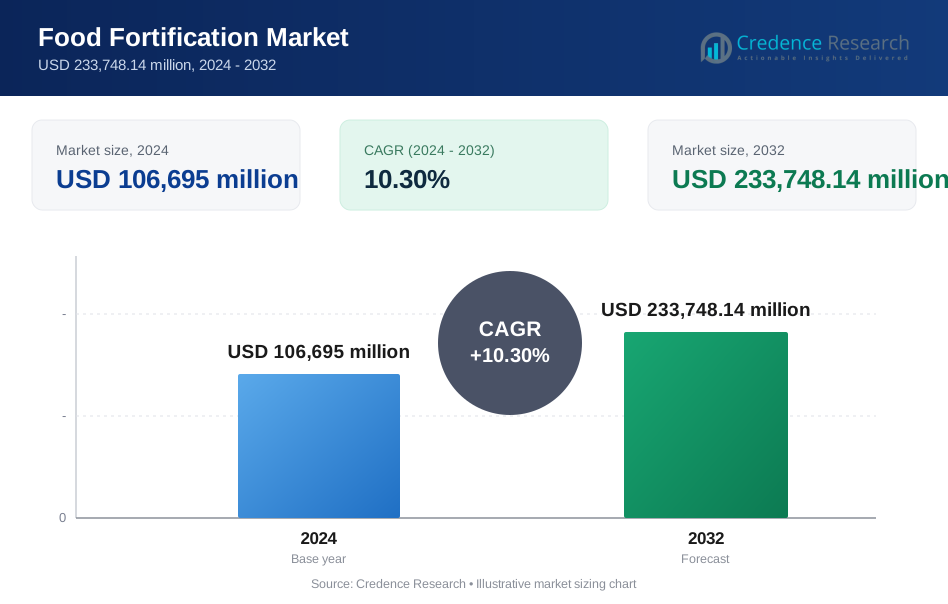
The Food Fortification market is projected to grow from USD 106,695 million in 2024 to USD 233,748.14 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.30%.
The Food Fortification market is driven by growing consumer awareness of nutritional deficiencies and an increasing demand for fortified foods to enhance health and wellness. The rising prevalence of chronic diseases linked to poor nutrition further propels the adoption of fortified products. Technological advancements in food processing techniques enable effective incorporation of essential nutrients, such as vitamins and minerals, into everyday food items. Additionally, government initiatives promoting public health and mandating food fortification in staple foods are significant trends that support market growth, ensuring wider access to nutritionally enhanced food options.
The Food Fortification market exhibits robust growth globally, with significant contributions from regions such as North America, Europe, and Asia-Pacific. North America leads in market share due to heightened consumer awareness and stringent regulatory standards, while Asia-Pacific shows rapid growth driven by increasing health awareness and rising disposable incomes. Key players like Nestlé S.A., BASF SE, and General Mills are pivotal in driving regional market dynamics through innovation and expansion into emerging markets. These companies, along with others such as Cargill Incorporated and Tata Chemicals Limited, play crucial roles in developing and distributing fortified foods, catering to diverse nutritional needs across global populations.
Market Drivers
Rising Prevalence of Micronutrient Deficiencies
Global malnutrition, particularly micronutrient deficiencies, remains a significant public health challenge, affecting diverse populations across the world. This phenomenon, often referred to as "hidden hunger," occurs when individuals consume enough calories but lack essential vitamins and minerals in their diets. For instance, it’s estimated that over half of children under five years old are micronutrient deficient (in at least one of iron, zinc, and vitamin A). The widespread nature of this issue underscores the critical need for fortified foods that can deliver these vital nutrients efficiently, addressing nutritional gaps and improving overall health outcomes.
Growing Awareness and Consumer Demand
There is a growing consumer awareness regarding the importance of balanced nutrition, spurred by increased education on health and wellness. For instance, in 2021, approximately 27 percent of participants in a survey conducted in the United States stated that they think that fortified food or beverages can be beneficial to their health. This knowledge is driving demand for fortified foods as part of a health-conscious lifestyle. More consumers are now seeking out food products that not only satisfy hunger but also provide essential nutrients to meet their dietary needs. This shift towards nutrient-rich diets is reshaping the food industry, prompting manufacturers to innovate and expand their fortified food offerings.
Government Initiatives and Technological Advances
Governments worldwide are implementing mandatory fortification programs to combat nutrient deficiencies, targeting key nutrients like iodine and iron. Alongside, regulatory bodies are setting stringent standards for fortified foods to ensure their safety and quality. Concurrently, advances in fortification technology are enhancing the effectiveness of nutrient delivery systems, making it easier and more cost-effective to enrich foods with essential vitamins and minerals. These technological improvements are crucial in making fortified foods accessible and beneficial for a broader audience.
Broadening Applications and Addressing Supply Chain Challenges
Fortification is expanding beyond staple foods to include a wider array of products such as beverages, snacks, and processed foods, tailored to meet specific dietary requirements of diverse demographic groups, including infants, children, and the elderly. Additionally, in regions experiencing food security issues or supply chain disruptions, fortified foods offer a reliable nutrient source, ensuring that populations have access to the essential nutrients required for healthy living. This strategic application of fortification technology helps mitigate nutritional deficiencies and supports overall food security globally.
Market Trends
Integration of Personalized and Functional Nutrition Trends
The Food Fortification market is increasingly influenced by the trend of personalized nutrition, where fortified foods are tailored to meet the specific dietary needs of individuals with allergies, intolerances, or particular health conditions. For instance, companies like Apple and Google are making significant strides in personalized nutrition, partnering with healthcare providers and offering personalized recommendations based on user data. Advanced nutrient profiling technologies enable the precise determination of individual nutrient requirements, facilitating more personalized fortification strategies that cater to unique health needs. Simultaneously, the concept of functional fortification is gaining traction. Foods are not only being fortified for basic nutritional enhancement but also to offer specific health benefits such as improved cognitive function, immune support, and cardiovascular health. This is achieved through the incorporation of functional ingredients like probiotics, prebiotics, and antioxidants, aligning fortified food products with the broader health and wellness trends influencing consumer preferences.
Sustainability, Technology, and Expansion in Emerging Markets
Sustainability and ethical considerations are becoming increasingly important in the Food Fortification market. Efforts to align fortification processes with sustainable practices include the ethical sourcing of ingredients and minimizing environmental impact. This approach is complemented by enhanced traceability, with consumers demanding greater transparency in the supply chain, often achieved through technologies like blockchain to track the origin and authenticity of ingredients. Moreover, the regulatory landscape for fortified foods is evolving to better accommodate these emerging trends and ensure product safety and efficacy across different regions. Additionally, the market is witnessing significant growth in developing economies and rural areas, driven by rising incomes and a growing recognition of nutritional needs. This expansion is supported by digital tools and data analytics, which optimize fortification strategies and improve product development, ensuring that fortified foods meet the specific nutritional deficiencies prevalent in these emerging markets.
Market Challenges Analysis
Economic and Regulatory Challenges in Food Fortification
The process of fortifying foods inherently involves increased production costs, which can render these products less affordable, particularly in low-income regions. This economic barrier is compounded by consumer reluctance to pay a premium for fortified foods, which may be perceived as less necessary than non-fortified alternatives. Concurrently, food manufacturers face significant regulatory hurdles. Navigating complex and often inconsistent regulatory frameworks across different regions not only proves costly but also time-consuming. These regulatory challenges demand a high level of diligence to ensure compliance and can hinder the speed to market and geographical expansion of fortified food products.
Consumer Perception and Supply Chain Complexities
Consumer acceptance of fortified foods is influenced by several factors, including misconceptions about the addition of artificial additives or concerns over excessive nutrient intake, which may deter some customers. Additionally, fortification can alter the taste or texture of food products, potentially impacting consumer satisfaction and acceptance negatively. For instance, an online survey of consumer perception within the knowledge community confirmed the case for additional mandatory food vehicles, particularly Bouillon cubes which have a wide reach in Nigeria. Beyond consumer perception, the supply chain for fortified foods presents its own set of challenges. Sourcing high-quality ingredients consistently, especially from developing regions, remains a complex issue. Moreover, ensuring that fortified foods are stored and transported under conditions that preserve nutrient integrity requires robust logistics solutions. These challenges are critical to address to maintain the efficacy and appeal of fortified foods in the market.
Market Segmentation Analysis:
By Raw Material:
The Food Fortification market is segmented based on various raw materials which include flours (rice, wheat, and corn), rice, salt, milk, oil, and sugar. Each raw material serves as a carrier for fortifying nutrients tailored to combat specific micronutrient deficiencies prevalent in different populations. For instance, flours are commonly fortified with iron and folic acid to prevent anemia, especially in developing countries where staple foods predominantly include bread and other flour-based products. Similarly, iodized salt has been a significant public health success in preventing iodine deficiency globally. Fortified milk and oils are increasingly popular, enriched with vitamins D and A, crucial for bone health and vision respectively. This segmentation reflects a targeted approach to improve public health outcomes through everyday food items.
By Micronutrients:
The market is segmented into vitamins and minerals, which are crucial for addressing various health issues. Vitamins such as A, B, C, D, and others are added to foods to support immune function, energy levels, and overall health. Minerals like calcium, iron, zinc, and iodine play essential roles in bone health, cognitive function, and thyroid function. The segment also includes other fortifying nutrients that cater to specific health needs, such as omega-3 fatty acids and fibers. This strategic incorporation of micronutrients into common foods aims to reduce the incidence of nutrient deficiencies across diverse populations, making fortified foods an integral part of a balanced diet.
Segments:
Based on Raw Material:
- Flours
- Rice Flour
- Wheat Flour
- Corn Flour
- Rice
- Salt
- Milk
- Oil
- Sugar
Based on Micronutrients:
- Vitamins
- Vitamin A
- Vitamin B
- Vitamin C
- Vitamin D
- Other Vitamins
- Minerals
- Calcium
- Iron
- Zinc
- Iodine
- Other Minerals
- Ther Fortifying Nutrients
Based on Application:
- Basic Food
- Cheese
- Butter
- Yoghurt
- Others
- Processed Food
- Extruded Products
- Powdered Products
- Value added Food
- Condiments
- Juice
Based on Technology:
- Drying
- Oven Drying
- Drum Drying
- Spray Drying
- Extrusion
- Coating & Encapsulation
- Others
Based on Sales Channel:
- Modern Trade
- Online Sales
- Neighborhood Stores
- Other Retail Format
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America commands a substantial 35% market share, driven by a combination of health-conscious consumers, stringent regulations, and a well-established food processing industry. The region's dominance is further reinforced by the prevalence of nutrient deficiencies and the growing demand for functional foods. Major food manufacturers in North America have embraced fortification as a strategy to differentiate their products and meet consumer demand for healthier options. The United States, in particular, leads the market with its advanced fortification technologies and widespread adoption of fortified staples such as bread, cereals, and dairy products.
Asia-Pacific
Asia-Pacific follows closely with a 30% market share and is poised to become the fastest-growing region in the food fortification market. For example, FFI has championed rice fortification in the Solomon Islands since 2015, working closely with the government to support evidence-based decision-making, provide compliance workshops and technical guidance for importers, and assist in drafting legislation. This growth is propelled by rising awareness of nutritional deficiencies, increasing disposable incomes, and government initiatives to combat malnutrition. Countries like India and China are at the forefront of this trend, implementing large-scale fortification programs for staple foods such as rice, wheat flour, and cooking oil. The region's rapid urbanization and changing dietary patterns have also created a fertile ground for fortified processed foods. Additionally, the growing middle class in Asia-Pacific countries is increasingly seeking out fortified products as part of a healthier lifestyle, driving market expansion. As food manufacturers in the region invest in research and development to create innovative fortified products tailored to local tastes and nutritional needs, the Asia-Pacific food fortification market is expected to witness substantial growth in the coming years.
Key Player Analysis
- BASF SE
- General Mills
- Bühler AG
- Tata Chemicals Limited
- Mondelez International
- Cargill Incorporated
- Danone
- Nestlé S.A.
- Bunge Limited
- Unilever PLC
- Koninklijke DSM NV
- Stern-Wywiol GmbH & Co.KG
- Aria Foods
- Nutritional Holdings (Pty) Limited
- Paul Lohmann GmbH KG Chemische Fabrik
- Wright Enrichment Inc.
- Gastaldi Hermanos
- Sinokrot Global
- Ufuk Kimya llac Sanayi Ve Ticaret Limited Sirketi
- Corbion NV
Competitive Analysis
In the competitive landscape of the Food Fortification market, leading players such as Nestlé S.A., BASF SE, General Mills, Tata Chemicals Limited, and Mondelez International engage in strategic initiatives to expand their market presence. These companies invest heavily in research and development to introduce innovative fortification techniques that ensure nutrient stability and effectiveness. Through strategic acquisitions, partnerships, and expansions, they leverage local market insights and distribution networks. Compliance with global and regional regulatory standards is crucial for market acceptance. Their marketing strategies emphasize the health benefits of fortified foods, educating consumers and driving product adoption, enhancing their portfolios and improving the bioavailability of fortifying nutrients.
Recent Developments
- In July 2023, General Mills doubled the amount of Vitamin D in its BIG G Cereals.
- In November 2022, Mondelez India partnered with Sikkim FDA and FSSAI to organize a Food Fortification Drive in Gangtok.
- In March 2023, BASF and Cargill expanded their partnership to offer high-performance enzyme solutions to animal protein producers in South Korea.
Market Concentration & Characteristics
The Food Fortification market is characterized by a moderate level of market concentration, with a mix of large multinational corporations and specialized nutrition companies driving innovation and growth. Key players like Nestlé S.A., BASF SE, and General Mills hold significant market shares, leveraging their extensive distribution networks and strong brand recognition to influence market dynamics. These industry leaders are complemented by a range of smaller companies that introduce niche products and target specific consumer needs, adding diversity to the market. Strategic collaborations and technological advancements play crucial roles in sustaining growth and expanding market reach. Additionally, the market is shaped by rigorous regulatory standards that ensure product safety and efficacy, compelling companies to maintain high quality and compliance. This structured market environment fosters competition, innovation, and continuous improvement in the fortification of foods to meet global nutritional needs.
Report Coverage
The research report offers an in-depth analysis based on Raw Material, Micronutrients, Application, Technology, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued expansion in global regions, particularly in developing economies where nutritional deficiencies are prevalent.
- Increased consumer demand for fortified foods as awareness of health and wellness grows.
- Enhanced focus on fortifying plant-based and alternative food products to cater to changing dietary preferences.
- Integration of advanced technologies to improve the bioavailability and effectiveness of fortified nutrients.
- Greater emphasis on sustainability and ethical sourcing in the production of fortified foods.
- Rising governmental support for mandatory food fortification programs to combat public health issues.
- Expansion of the product range to include snacks, beverages, and infant foods in fortification efforts.
- Strategic partnerships between leading players and local firms to facilitate market penetration and distribution.
- Adoption of digital tools and data analytics to optimize fortification processes and track consumer trends.
- Ongoing research and development to introduce new fortifying compounds and methods, ensuring consumer safety and satisfaction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Micronutrient Deficiencies
Global malnutrition and widespread micronutrient deficiencies, especially among children and vulnerable populations, are driving the need for fortified foods to address health gaps and improve public health outcomes.
Growing Awareness and Consumer Demand
Increasing consumer education on health and wellness is leading to higher demand for foods that provide essential nutrients, prompting manufacturers to expand their fortified product offerings.
Government Initiatives and Mandatory Fortification Programs
Governments worldwide are implementing regulations and programs mandating the fortification of staple foods, ensuring broader access to essential nutrients and supporting market growth.
Technological Advancements in Food Processing
Innovations in food processing and fortification technologies are making it easier and more cost-effective to incorporate vitamins and minerals into a wide range of food products, enhancing nutrient stability and bioavailability.
Expansion in Emerging Markets
Rising disposable incomes, urbanization, and increased health awareness in developing regions are fueling rapid adoption of fortified foods, supported by local government initiatives and international partnerships.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Fortification Market?
What factors are driving the growth of the Southeast Asia Crash Barrier Systems Market?
What are the key segments within the Food Fortification Market?
Who are the major players in the Food Fortification Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Drying (Oven, Drum, Spray)
- 1.2.2 Extrusion
- 1.2.3 Coating & Encapsulation
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Basic Food (Cheese, Butter, Yoghurt, Others)
- 1.3.2 Processed Food (Extruded Products, Powdered Products)
- 1.3.3 Value Added Food (Condiments, Juice)
- 1.4 By Raw Material
- 1.4.1 Flours (Rice, Wheat, Corn)
- 1.4.2 Rice
- 1.4.3 Salt
- 1.4.4 Milk
- 1.4.5 Oil
- 1.4.6 Sugar
- 1.5 By Micronutrient
- 1.5.1 Vitamins (A, B, C, D, Others)
- 1.5.2 Minerals (Calcium, Iron, Zinc, Iodine, Others)
- 1.5.3 Other Fortifying Nutrients
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 106,695 million → 2032: USD 233,748.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Fortification Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Fortification Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Fortification Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Fortification Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Fortification Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Fortification Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Fortification Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Fortification Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 106,695 million → 2032: USD 233,748.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Fortification Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drying (Oven, Drum, Spray)
- 12.3.7.2 Extrusion
- 12.3.7.3 Coating & Encapsulation
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Basic Food (Cheese, Butter, Yoghurt, Others)
- 12.4.7.2 Processed Food (Extruded Products, Powdered Products)
- 12.4.7.3 Value Added Food (Condiments, Juice)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Raw Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flours (Rice, Wheat, Corn)
- 12.5.7.2 Rice
- 12.5.7.3 Salt
- 12.5.7.4 Milk
- 12.5.7.5 Oil
- 12.5.7.6 Sugar
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Micronutrient - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Vitamins (A, B, C, D, Others)
- 12.6.7.2 Minerals (Calcium, Iron, Zinc, Iodine, Others)
- 12.6.7.3 Other Fortifying Nutrients
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Fortification End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Fortification Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Fortification Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Fortification Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nestlé S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 General Mills
- 18.5 Tata Chemicals Limited
- 18.6 Mondelez International
- 18.7 Cargill Incorporated
- 18.8 Danone
- 18.9 Bühler AG
- 18.10 Unilever PLC
- 18.11 Koninklijke DSM NV
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

