
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
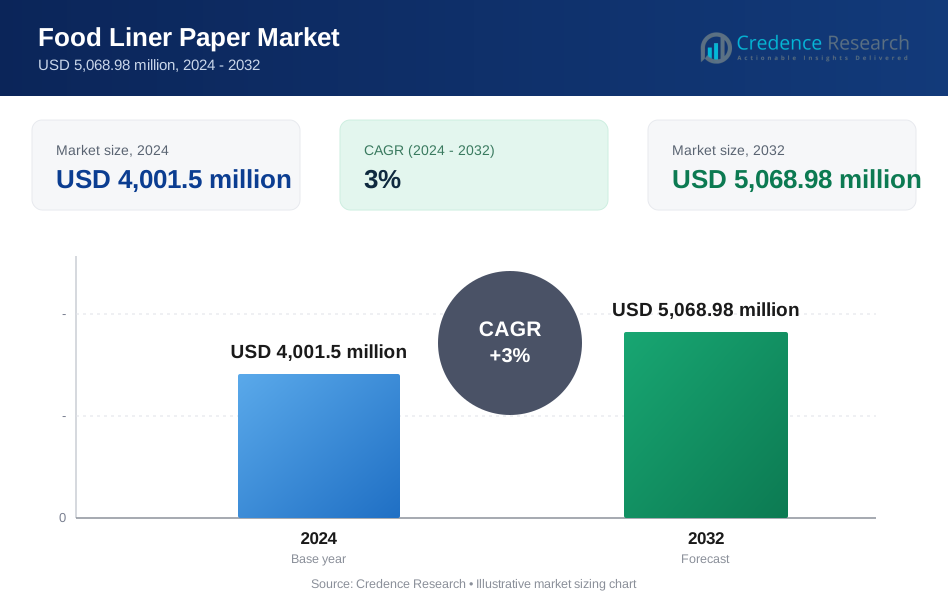
| Food Liner Paper Market Size 2024 | USD 4,001.5 Million |
| Food Liner Paper Market, CAGR | 3% |
| Food Liner Paper Market Size 2032 | USD 5,068.98 Million |
Market Overview
The global Food Liner Paper Market is projected to grow from USD 4,001.5 million in 2024 to USD 5,068.98 million by 2032, registering a compound annual growth rate (CAGR) of 3%.
The food liner paper market is driven by the increasing demand for sustainable and eco-friendly packaging solutions. Consumers and businesses are shifting towards biodegradable and recyclable materials to reduce environmental impact, fueling the growth of food liner paper. Additionally, the rise in food delivery services and takeout options contributes to the market's expansion, as food liner paper provides effective protection and insulation for various food items. Advancements in paper production technologies and the growing preference for lightweight, high-strength materials further support the adoption of food liner paper across the foodservice industry.
The food liner paper market is experiencing substantial growth across multiple regions, with North America and Europe leading the charge due to increasing demand for sustainable packaging solutions and food safety regulations. Meanwhile, the Asia-Pacific region is emerging as a key growth driver, spurred by rapid urbanization and rising disposable incomes. Major players in the market include Pratt Industries, Sonoco Products Company, Smurfit Kappa Group, Oji Fibre Solutions, Zhejiang Jingxing, Mondi Group, DS Smith, Georgia-Pacific, and WestRock, all of which are innovating to meet the growing demand for eco-friendly and food-safe packaging materials.
Market Drivers
Rising Demand for Packaged Food
As modern lifestyles become increasingly hectic, the demand for convenient, ready-to-eat food options continues to rise. Consumers seek quick meal solutions without compromising on quality, and food liner paper plays a vital role in maintaining the integrity of these packaged products. For instance, a report by the Food Packaging Forum highlights that the use of food liner paper can significantly extend the shelf life of packaged foods, making them more convenient for busy consumers. By preserving freshness and extending shelf life, food liner paper has become an essential element in the food packaging industry, ensuring that packaged food products remain safe and appealing for consumption over time.
Growing Population and Urbanization
The global population is steadily increasing, coupled with rapid urbanization, particularly in developing countries. With more people living in urban areas, where time constraints limit home cooking, there is a greater reliance on prepackaged food. For instance, according to a study by the United Nations, by 2050, two-thirds of the world's population is expected to live in urban areas, significantly increasing the demand for packaged food. Food liner paper is essential in meeting this demand, as it helps ensure the quality and safety of packaged food products, which are frequently consumed by urban dwellers looking for convenient meal options.
Increasing Focus on Food Safety
As consumers become more health-conscious and aware of food safety issues, the role of packaging in protecting food has never been more critical. Food liner paper helps maintain hygiene by providing an effective barrier against contamination, which is particularly important in the handling and storage of packaged food. For instance, a study by the World Health Organization (WHO) emphasizes the importance of safe packaging in preventing foodborne illnesses. The growing focus on food safety standards worldwide is driving the adoption of reliable packaging materials, further bolstering the demand for food liner paper.
Shift Towards Sustainable Packaging
In response to global environmental concerns, there is an increasing shift toward sustainable and eco-friendly packaging solutions. Food liner paper offers a biodegradable and recyclable alternative to conventional packaging materials. Its ability to be made from recycled materials appeals to environmentally conscious consumers and businesses, who are prioritizing sustainability in their operations. This trend towards green packaging is expected to continue driving the demand for food liner paper.
Market Trends
Sustainability and Eco-friendliness
There is a significant shift toward sustainability in the food packaging industry, with a growing demand for biodegradable and compostable food liner paper made from renewable resources. As businesses and consumers prioritize eco-friendly practices, the use of recycled paper in food liner products has increased, reducing the environmental impact of packaging. For instance, a report by the Bureau of International Recycling highlights that over 50 million tons of paper were recovered for recycling in 2021. Additionally, food liner paper is emerging as a sustainable alternative to plastic-based packaging, offering a more environmentally responsible option for food storage and transportation. This trend is driven by heightened awareness of the need to reduce plastic waste and the environmental footprint of packaging materials, especially in foodservice and retail sectors.
Functional Innovations and Health Trends
The food liner paper market is witnessing several functional innovations designed to meet evolving consumer needs. Antimicrobial coatings are being integrated into food liner paper to enhance food safety and extend shelf life, a crucial factor for maintaining food quality during storage and transit. Additionally, advances in moisture and grease resistance have improved the protective properties of food liner paper, helping preserve the integrity of food items. Customizable printing capabilities are also becoming more prominent, allowing brands to enhance product appeal and convey important information to consumers. Alongside these innovations, there is a growing demand for clean label packaging as consumers seek materials free from harmful additives and chemicals. Furthermore, food liner paper made from natural and organic materials is gaining popularity as part of the broader health and wellness trend, where consumers are increasingly focused on healthier, more sustainable food packaging options.
Market Challenges Analysis
Raw Material Fluctuations and Supply Chain Disruptions
The food liner paper market faces challenges due to fluctuations in raw material prices, particularly pulp, which is a primary component in its production. The price of pulp can vary significantly due to global demand, climate conditions, and geopolitical events, impacting overall production costs for manufacturers. Additionally, disruptions in the supply chain, such as transportation bottlenecks or shortages of key raw materials, can cause delays in production and lead to increased costs. For instance, according to the European Central Bank, global supply chain disruptions have significantly impacted the availability and cost of goods, including paper products. These supply chain vulnerabilities can affect the availability of food liner paper and hinder manufacturers’ ability to meet demand, especially during periods of instability in global trade. Managing these challenges requires manufacturers to be agile and adapt their supply chain strategies to ensure consistent production and delivery.
Regulatory Compliance and Competitive Pressure
Manufacturers in the food liner paper market must navigate a complex landscape of regulatory challenges, particularly regarding food safety and environmental standards. Strict regulations, such as those imposed by the FDA and EU, require adherence to rigorous food safety guidelines, which can be both costly and time-consuming. Failure to comply can lead to product recalls, financial penalties, and reputational damage. Furthermore, increasing environmental regulations, especially those related to waste disposal and carbon emissions, add operational costs to food liner paper production. Compounding these challenges is the intense competition in the market. Numerous players compete for market share, leading to price pressures and a constant need for innovation to maintain a competitive edge. Additionally, alternative packaging materials like plastic films and aluminum foil pose a threat to food liner paper, particularly if they offer lower costs or superior performance. Manufacturers must continuously innovate to meet evolving consumer preferences for sustainable, health-conscious, and convenient packaging options, while managing economic fluctuations and shifting trends.
Market Segmentation Analysis:
By Material:
Food liner paper is primarily categorized based on its material type, with three major segments: Kraft paper, specialty paper, and recycled paper. Kraft paper dominates the market due to its strength, durability, and cost-effectiveness, making it suitable for various food packaging applications. It is commonly used for wrapping and protecting food items, offering a balance between functionality and price. Specialty paper, on the other hand, is tailored for specific applications that require enhanced features such as moisture resistance, grease resistance, or antimicrobial properties. This type of paper is commonly used in premium packaging and high-end food products. Recycled paper is gaining traction as consumers and manufacturers increasingly focus on sustainability. Made from post-consumer recycled materials, it offers an eco-friendly alternative to traditional papers while still providing sufficient strength and durability for food packaging.
By Thickness: Food liner paper is also segmented based on thickness, with three primary categories: up to 30 GSM, 30 to 50 GSM, and above 50 GSM. Paper with a thickness of up to 30 GSM is typically used for lighter food packaging needs, such as wrapping sandwiches or bakery products. It is lightweight yet durable, providing protection without adding unnecessary weight to the product. The 30 to 50 GSM segment is more commonly used for food items requiring moderate strength and durability, such as fast food or takeout packaging. Finally, papers above 50 GSM are used for more robust applications where higher strength and resistance to moisture or grease are required, such as for heavy-duty food packaging like frozen foods or takeaway meals. The choice of thickness directly impacts the paper's performance in protecting food and extending its shelf life.
Segments:
Based on Material:
- Kraft Paper
- Specialty Paper
- Recycled Paper
Based on Thickness:
- Up to 30 GSM
- 30 to 50 GSM
- Above 50 GSM
Based on End Use:
- Hotels & Restaurants
- Bakery & Cafes
- Fast Food Outlets
- Cinemas
- Airline & Railway Catering
- Other End Use
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the food liner paper market, accounting for approximately 30% of global revenue. This region is driven by the increasing demand for packaged food products, coupled with a strong focus on sustainability. Both the U.S. and Canada have seen a marked shift towards eco-friendly packaging, with consumers and food manufacturers prioritizing biodegradable, recyclable, and compostable food packaging solutions. This trend is supported by stringent environmental regulations and the growing demand for clean-label packaging. In addition, North American consumers are increasingly concerned with food safety, making food liner paper an essential component of packaging solutions for fast food, takeout, and ready-to-eat meals. Major food service chains and e-commerce platforms contribute significantly to the region's demand, with the adoption of more sustainable materials pushing market growth.
Asia-Pacific
The Asia-Pacific region is the largest and fastest-growing market for food liner paper, contributing nearly 40% of the global market share. The rapid urbanization, population growth, and evolving lifestyles in countries like China and India have driven a surge in demand for convenient, packaged food options. As a result, the need for food liner paper in this region is expected to rise sharply over the forecast period. Furthermore, the expanding middle class in emerging economies is leading to greater disposable income, which fuels demand for packaged food products. In Asia-Pacific, there is also a growing emphasis on sustainability, with consumers and governments pushing for eco-friendly solutions. As countries in this region adopt stricter environmental regulations, food packaging companies are focusing on using recycled and biodegradable materials to meet both consumer preferences and regulatory requirements. The growth of online food delivery services is also a key driver in this market.
Key Player Analysis
- WestRock Company
- Sonoco Products Company
- Smurfit Kappa Group
- Oji Fibre Solutions (NZ) Ltd
- Georgia-Pacific LLC
- Mondi Group Plc
- Zhejiang Jingxing
- DS Smith Plc
- Pratt Industries
Competitive Analysis
The food liner paper market is highly competitive, with key players such as Pratt Industries, Sonoco Products Company, Smurfit Kappa Group, Oji Fibre Solutions, Zhejiang Jingxing, Mondi Group, DS Smith, Georgia-Pacific, and WestRock driving innovation and market growth. These companies are focusing on offering sustainable, eco-friendly products that meet rising consumer demand for environmentally conscious packaging solutions. They are investing in advanced technologies to produce biodegradable, antimicrobial, and moisture-resistant food liner papers. As the market continues to evolve, these players are differentiating themselves through the use of recycled materials, customization options, and superior performance features, while adhering to stringent food safety standards. With sustainability being a major driver, these companies are working to enhance the recyclability and environmental impact of their products, ensuring they remain competitive in a rapidly changing marketplace. Price competition, alongside innovation, remains a key factor for success in the industry.
Recent Developments
- In June 2023, Mondi and Syntegon launched a new paper packaging solution made using recycled fibers. The product is made using Mondi’s EcoVantage kraft paper, which is spot coated to create dust-tight, heat-sealable packaging. This paper packaging can be used for packing dry foods such as sugar, pasta, and flour.
- In October 2022, Mondi Plc invested funds in a new paper machine at its flagship Štětí mill in the Czech Republic. Such investment helps the company to capture the growing demand for paper-based flexible packaging. This development will contribute to increasing companies’ range of innovative, sustainable packaging, and paper solutions.
- In July 2022, Nordic Paper developed new natural greaseproof papers for the food industry without the addition of fluorochemicals. The company has achieved natural barrier properties in its new developed product (paper) without the addition of fluorochemicals. Such product developments are helpful for the company to gain more customer base by offering more sustainable alternatives to packaging manufacturers.
- In June 2022, Mondi launched Grow&Go, a range of consumer-friendly trays and carry-packs to produce pallet-ready bulk shipping boxes. The Grow&Go solutions are made using readily recyclable paper. The company claims that this product solution can reduce vegetable and fruits damage while maintaining hygienic packaging.
Market Concentration & Characteristics
The food liner paper market exhibits moderate concentration, with several large players dominating the industry while numerous smaller regional manufacturers contribute to market dynamics. The market is characterized by strong competition among companies offering sustainable, high-performance packaging solutions to meet the growing demand for eco-friendly products. These manufacturers focus on incorporating recycled materials, biodegradability, and moisture resistance to cater to the increasing consumer preference for environmentally conscious packaging. The shift toward regulatory compliance for food safety, coupled with consumer demand for clean-label products, further drives innovation in the market. While large multinational companies like Smurfit Kappa Group and Sonoco Products maintain significant market share, regional players also offer niche products to meet local needs. The market is evolving with trends in customization, providing tailored solutions for branding and performance. As sustainability remains a core driver, players are investing in more sustainable production processes and products to capture market share in this rapidly growing sector.
Report Coverage
The research report offers an in-depth analysis based on Material, Thickness, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing demand for sustainable and biodegradable food packaging will drive innovation in food liner paper products.
- The growing emphasis on reducing plastic usage will boost the adoption of paper-based packaging solutions.
- Consumer preference for eco-friendly materials will encourage manufacturers to focus on recycled and compostable food liner papers.
- Advancements in food safety features, such as antimicrobial coatings, will enhance the functionality of food liner paper.
- The rise of e-commerce and online food delivery will drive the need for robust and protective food packaging materials.
- Rising regulatory pressure for clean-label packaging will accelerate the development of non-toxic, chemical-free food liner paper.
- Economic growth in emerging markets will increase the demand for packaged food, thereby expanding the food liner paper market.
- Continuous advancements in printing technologies will allow for more customization and branding on food liner paper.
- Increased investment in automation and sustainable manufacturing processes will reduce production costs and improve product quality.
- The shift toward minimalist packaging will prompt innovations in thinner, yet durable, food liner paper options.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Liner Paper market?
What factors are driving the growth of the Food Liner Paper market?
What are the key segments within the Food Liner Paper market?
What are some challenges faced by the Food Liner Paper market?
Who are the major players in the Food Liner Paper market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Liner Paper Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Liner Paper Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,001.5 million → 2032: USD 5,068.98 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Liner Paper Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Liner Paper Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Liner Paper Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Liner Paper Market Drivers
- 3.3 Food Liner Paper Market Restraints & Challenges
- 3.4 Food Liner Paper Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Liner Paper Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Liner Paper Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Liner Paper category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Liner Paper Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Liner Paper Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Liner Paper market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Liner Paper Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Liner Paper Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Liner Paper Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Liner Paper (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Liner Paper Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Liner Paper Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Liner Paper Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Liner Paper Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Liner Paper Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Liner Paper Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Liner Paper Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Liner Paper Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Liner Paper Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
