
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Garage and Service Station Market Size 2024 | USD 4045 Million |
| Garage and Service Station Market, CAGR | 11.6% |
| Garage and Service Station Market Size 2032 | USD 9732.67 Million |
Market Overview:
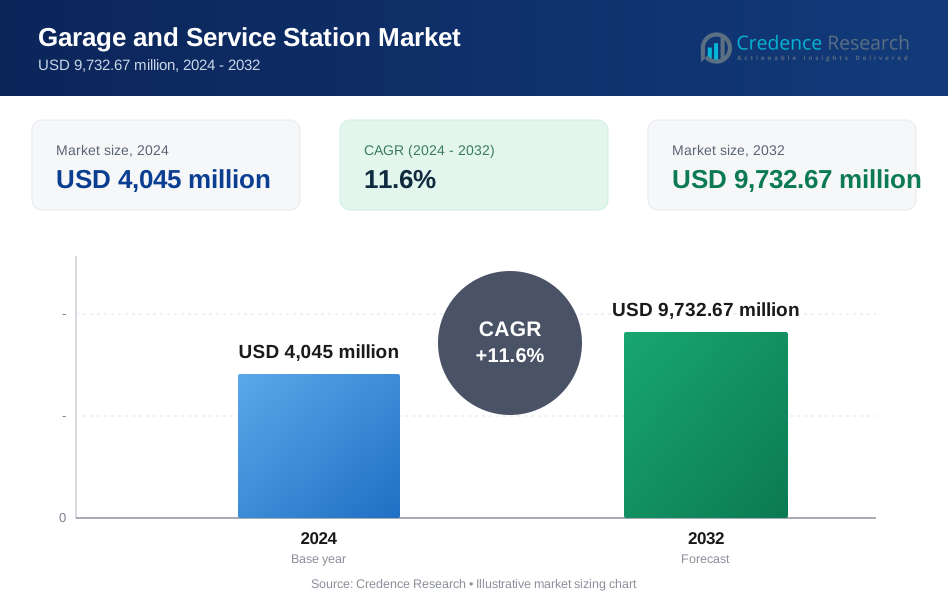
Garage and Service Station Market size was valued at USD 4045 million in 2024 and is anticipated to reach USD 9732.67 million by 2032, at a CAGR of 11.6% during the forecast period (2024-2032).
Several factors are contributing to the market's growth. The increasing disposable income of consumers in emerging economies is driving the demand for personal vehicles, leading to higher demand for maintenance and repair services. This rise in vehicle ownership is directly correlated with an uptick in service station visits. Furthermore, the trend towards longer vehicle lifespans, advancements in automotive technology, and the rising importance of preventive vehicle maintenance all play pivotal roles. As vehicles become more complex, there is an increasing need for specialized services. Additionally, innovations such as electric vehicles (EVs) and hybrid vehicles are generating new service requirements and opportunities for service stations to diversify their offerings. The growing need for environmentally friendly service solutions, like green garages, is also emerging as a critical driver in the market, aligning with global sustainability trends.
Regionally, North America and Europe dominate the Garage and Service Station market, primarily due to their well-established automotive sectors and higher per capita vehicle ownership. These regions are also leading the way in the adoption of advanced technologies within service stations, setting global benchmarks. Asia-Pacific, however, is expected to experience the highest growth during the forecast period, driven by the booming automotive industry in countries such as China and India. These regions have seen rapid urbanization and an increase in vehicle sales, leading to increased demand for service stations. Furthermore, the shift towards electric vehicles in these regions is presenting both challenges and growth opportunities for service stations. Additionally, the increasing focus on infrastructure development in emerging markets further bolsters the market's growth potential.
Market Insights:
- Garage and Service Station market valued at USD 4045 million in 2024, projected to reach USD 9732.67 million by 2032.
- Increasing vehicle ownership in emerging economies is driving demand for maintenance and repair services.
- Technological advancements such as electric vehicles (EVs) and hybrid models are generating new service opportunities.
- Preventive maintenance is gaining importance as consumers prioritize vehicle longevity and efficiency.
- The rise of eco-friendly services, such as green garages, is a growing trend in response to sustainability concerns.
- North America and Europe dominate the market, with high vehicle ownership and advanced technology adoption.
- Asia-Pacific is the fastest-growing region, with rapid urbanization, increased vehicle sales, and a rise in EV adoption.
Market Drivers:
Rising Vehicle Ownership and Demand for Maintenance
The increasing number of vehicles on the road, particularly in emerging economies, is a significant driver of the Garage and Service Station market. For instance, in India, the recent Household Consumption Expenditure Survey (HCES) finds that more than half of households own a motorcycle or a scooter, while fewer than one in ten households own a car or a jeep. As more consumers purchase personal vehicles, there is a corresponding rise in the demand for maintenance and repair services. This growth is further accelerated by rising disposable income, enabling a larger portion of the population to afford vehicles and vehicle upkeep.
Technological Advancements in the Automotive Industry
Advancements in automotive technology, such as the development of electric vehicles (EVs) and hybrid vehicles, are also playing a critical role in shaping the market. Service stations must adapt to these technological innovations, leading to the creation of new services and specialized expertise in EV maintenance. For example, companies like Tesla are pioneering electric vehicles, incorporating renewable energy into the automotive industry through investments in solar panels, battery storage, and energy-efficient manufacturing processes. As the complexity of vehicles increases, the need for more sophisticated and specialized repair services continues to drive the demand for high-quality service stations.
Focus on Preventive Vehicle Maintenance
The growing importance of preventive maintenance is another key driver in the market. Consumers are increasingly aware of the long-term benefits of regular vehicle maintenance in preventing costly repairs and improving vehicle longevity. For instance, a case study from Windmill Garage highlighted how regular servicing prevented MOT disasters, ensuring vehicle safety and efficiency. This shift in consumer behavior is contributing to the expansion of service stations that offer scheduled maintenance and repairs to meet customer demand.
Sustainability and Green Solutions
The shift towards sustainability has led to the rise of environmentally friendly service solutions, such as green garages. Consumers are more inclined to choose service stations that prioritize eco-friendly practices, such as using energy-efficient equipment and offering environmentally conscious vehicle maintenance options. For example, Repsol has achieved a significant milestone by reaching 600 service stations supplying 100% renewable fuel across the Iberian Peninsula, including 550 in Spain and 50 in Portugal. As environmental concerns continue to grow, this trend is expected to drive market growth, especially in regions with strong regulatory support for sustainability.
Market Trends:
Rise of Electric Vehicles (EVs) and Hybrid Vehicles
The shift toward electric and hybrid vehicles is a prominent trend reshaping the Garage and Service Station market. As the global automotive industry moves towards more sustainable solutions, service stations are increasingly adapting to meet the unique maintenance needs of electric and hybrid vehicles. For instance, PDI Technologies' 2024 Sustainability, EV, and Convenience Retail Survey Report indicates that 80% of consumers are very or somewhat concerned about the environmental impact of the products they buy, up from 68% in 2023. This includes offering specialized services such as battery maintenance and charging station installation, driving innovation within the service industry.
Adoption of Digital Technologies
Service stations are increasingly integrating digital technologies to enhance customer experience and operational efficiency. Many are adopting advanced diagnostic tools, online booking systems, and customer management platforms to streamline operations. For example, a survey by Pega in 2020 found that 49% of vehicle owners expect high-quality service and base their choice of service provider and automaker on the quality of the services provided. Additionally, the use of data analytics to predict vehicle issues before they arise is becoming more prevalent, helping service stations offer proactive solutions and attract more customers.
Eco-Friendly and Sustainable Practices
In response to rising environmental concerns, service stations are embracing eco-friendly practices. The demand for green garages is growing, where energy-efficient equipment, water conservation, and the use of non-toxic cleaning products are becoming standard. For instance, a survey by the OECD in 2023 showed that many households are willing to shift to greener lifestyles, with 83% using reusable shopping bags and 37% buying second-hand items. This trend aligns with both consumer preferences and government regulations encouraging sustainability, making eco-conscious service stations a key differentiator in the market.
Mobile and On-Demand Services
Convenience is becoming a key driver in the market, with the rise of mobile and on-demand vehicle maintenance services. Customers are increasingly opting for services such as at-home oil changes and tire replacements, as well as remote diagnostics. For example, a report by Auto Monkey highlighted that the mobile mechanic segment grew by 15% in 2024, compared to an 8% growth in traditional repair shops. This shift reflects a growing desire for convenience and flexibility, challenging traditional service station models and pushing for more innovation in service delivery.
Market Challenges Analysis:
Technological Adaptation and Expertise
One of the significant challenges facing the Garage and Service Station market is the need for continuous technological adaptation. As vehicles become more advanced, especially with the rise of electric and hybrid models, service stations must continually upgrade their knowledge, tools, and infrastructure. Service providers are required to invest in specialized training for technicians and advanced diagnostic equipment to keep pace with emerging automotive technologies. This can result in high capital expenditures and operational complexities, especially for smaller or independent service stations. Ensuring that staff are trained and equipped to handle evolving vehicle technologies remains a major challenge. The Garage and Service Station market is highly competitive, with numerous players, from large chains to independent service providers. This competition often leads to price wars and lower margins, making it difficult for smaller businesses to stay profitable. Additionally, market saturation in developed regions creates challenges for growth, as there are fewer new customers to capture. Differentiation becomes key in such a competitive environment, but many service stations struggle to offer unique services that set them apart from competitors, further intensifying the competitive pressure.
Regulatory Compliance and Environmental Concerns
The growing emphasis on sustainability and environmental regulations presents another challenge for service stations. The adoption of environmentally friendly practices such as waste disposal, water conservation, and energy-efficient equipment requires substantial investment. Additionally, service stations must comply with increasingly stringent regulations related to emissions, disposal of hazardous materials, and overall environmental impact. The costs associated with maintaining compliance can be burdensome, particularly for smaller service stations operating with limited resources. Consumers are demanding higher levels of convenience and faster service. With the rise of digital platforms and mobile services, customers expect quicker turnaround times and more flexible service options, such as mobile mechanics or on-demand services. Service stations that are unable to meet these high expectations risk losing market share to more agile competitors. The pressure to maintain customer satisfaction while managing operational efficiency and costs remains a significant challenge in the market.
Market Opportunities:
The rising demand for electric vehicles (EVs) presents a significant opportunity for garage and service stations to diversify their offerings and cater to a growing customer base. As the shift towards sustainable transportation accelerates, service stations that invest in EV charging infrastructure and specialized battery maintenance services are poised for growth. This trend not only allows service stations to capture a new market segment but also positions them as leaders in the evolving automotive landscape. Service providers that embrace this technological shift will be able to secure long-term profitability by addressing the unique needs of electric vehicle owners.
Another promising opportunity lies in the growing emphasis on preventive vehicle maintenance. With consumers becoming more proactive about maintaining their vehicles, service stations can capitalize on offering scheduled maintenance packages and extended warranties. By providing value-added services such as vehicle health monitoring systems and remote diagnostics, service stations can increase customer loyalty and generate recurring revenue streams. Moreover, the rise of on-demand and mobile services opens up new avenues for growth, enabling service providers to offer maintenance and repairs directly at customers' locations. This shift in consumer behavior, driven by convenience, creates a competitive advantage for service stations that are quick to adapt to evolving market needs.
Market Segmentation Analysis:
By Product Type
The Garage and Service Station market can be segmented by product type, which includes services such as vehicle maintenance, repair services, fueling, and car washing. Vehicle maintenance services are the largest segment, driven by increasing consumer awareness of preventive care for vehicles. Repair services follow closely, with high demand for specialized services for both conventional and electric vehicles. The rise of eco-friendly car wash solutions has also gained popularity, providing opportunities for service stations to attract environmentally conscious customers.
By Ownership Type
The market is also segmented by ownership type, which includes independent service stations and chain service stations. Chain service stations dominate the market due to their established networks, brand recognition, and the ability to provide standardized services. However, independent service stations are expected to grow, particularly in emerging markets, due to their personalized service offerings, local presence, and cost-effectiveness. Independent stations are also increasingly adopting digital tools to compete with large chains.
By Sector
The market is categorized into automotive, commercial, and residential sectors. The automotive sector leads the market, driven by the rising number of personal vehicles and increasing demand for maintenance and repair services. Commercial vehicles, including fleets and transport vehicles, also contribute significantly to service demand, requiring specialized services for larger vehicles. The residential sector involves more specialized, localized service requirements but is growing due to the convenience of home-based services.
Segmentations:
By Product Type
- Fueling
- Vehicle Maintenance
- Repair Services
- Car Washing
By Ownership Type
- Independent Service Stations
- Chain Service Stations
By Sector
- Automotive
- Commercial
- Residential
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the Garage and Service Station market, accounting for 30% of the global market. The region's well-established automotive sector, combined with high vehicle ownership rates, contributes significantly to this dominance. The demand for both vehicle maintenance and repair services is driven by a growing focus on safety, the longevity of vehicles, and regulatory compliance. The adoption of advanced technologies, such as electric vehicles (EVs) and autonomous vehicles, is also fostering the growth of specialized service stations. The United States and Canada are key players in this region, with service stations adapting to meet the increasing demand for EV charging infrastructure and environmentally friendly services.
Europe
Europe holds a market share of 28% in the Garage and Service Station market, driven by high vehicle density and significant investments in sustainable automotive solutions. The shift towards electric vehicles is a key driver of growth, with countries like Germany, France, and the United Kingdom leading the transition. These nations have been investing heavily in green garages, promoting eco-friendly maintenance practices. Additionally, the automotive aftersales sector is thriving, as consumers prioritize preventive maintenance to ensure optimal vehicle performance and minimize downtime. The growing trend toward digital services, such as online booking and remote diagnostics, further enhances the market dynamics in the region.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the Garage and Service Station market, with a market share of 25%. This growth is fueled by rapid urbanization, increasing disposable incomes, and a boom in vehicle sales, particularly in countries such as China, India, and Japan. The demand for vehicle maintenance and repair services is rapidly expanding, with a rising number of consumers seeking high-quality services. The region is also experiencing a surge in EV adoption, prompting service stations to upgrade their infrastructure and offer specialized services. Government incentives and infrastructure development are further bolstering the growth of the garage and service station market in this region.
Latin America
Latin America holds a market share of 10% in the Garage and Service Station market, driven by the increasing vehicle fleet and demand for maintenance services. Countries such as Brazil and Mexico are seeing growth in the automotive sector, which fuels demand for aftersales services. The trend towards preventive maintenance and the growing number of commercial vehicles in the region present ample opportunities for service stations to expand their offerings and customer base.
Middle East & Africa
The Middle East & Africa holds a market share of 7%, driven by increasing demand for vehicle services in nations like Saudi Arabia and the United Arab Emirates. The region's affluent consumer base and growing vehicle fleet, particularly in the luxury and commercial sectors, create opportunities for service stations to expand their operations. Additionally, government initiatives promoting sustainable transportation and automotive services are expected to contribute to market growth in the coming years.
Key Player Analysis:
- Firestone
- Pep Boys
- Autoliv
- Midas
- Safelite Group
- Monro Muffler Brake
- Lithia Motors
- Advance Auto Parts
- Napa Auto Parts
- Hendrick Automotive Group
Competitive Analysis:
The Garage and Service Station market is highly competitive, with leading players such as Firestone, Pep Boys, Midas, and Autoliv shaping the landscape. Firestone and Midas are well-established brands, offering a comprehensive range of vehicle maintenance and repair services, including tire services and diagnostics. Firestone, for instance, has been recognized for its commitment to customer satisfaction, with surveys indicating that 92% of customers are satisfied with their service experience. Pep Boys competes with an extensive network of service stations, focusing on customer convenience with services like mobile tire fitting and online booking options. Autoliv, while not directly providing maintenance services, contributes to the market by supplying safety components, which influence vehicle service requirements. These larger players dominate through scale, technological investments, and brand recognition, while independent service stations often compete with personalized services and more flexible pricing. As the market evolves, technological integration and eco-friendly services are key areas where these companies differentiate themselves.
Recent Developments:
- In July 2024, Autoliv announced that their second quarter sales increased organically by 0.7%, outperforming the global light vehicle production (LVP) decline of 0.7%.
- In February 2024, Safelite Group acquired Tri State Auto Glass, expanding its presence in the Carolinas and adding locations in South Carolina and North Carolina.
- In July 2024, Safelite Group announced the acquisition of City Auto Glass, based in St. Paul, Minnesota, with 39 mobile operations and shop locations in the Greater Minnesota area, Western Wisconsin, Northern Iowa, and Central and South Florida.
Market Concentration & Characteristics:
The Garage and Service Station market is moderately concentrated, with a mix of global players and independent operators. Major companies like Firestone, Pep Boys, and Midas hold significant market share, leveraging their large networks, established brands, and comprehensive service offerings. These players benefit from economies of scale, allowing for investment in advanced technology and the development of innovative services such as mobile maintenance and electric vehicle (EV) charging stations. Autoliv, though not a direct service provider, plays a critical role in the industry by supplying essential safety components, impacting service station operations. While larger players dominate with their resources and brand recognition, independent service stations are also prevalent, offering personalized services at competitive prices. The market is evolving, with a growing focus on sustainability and digital solutions, driving both large chains and independent stations to adapt and innovate.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Ownership Type, Sector and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Garage and Service Station market is expected to continue growing due to the increasing global vehicle fleet and demand for maintenance services.
- The rise in electric vehicle (EV) adoption will drive significant changes, creating new service requirements for charging infrastructure and specialized maintenance.
- Technological advancements in vehicles, such as autonomous cars and connected systems, will necessitate ongoing innovation in diagnostic tools and repair services.
- Sustainability initiatives will play a pivotal role, with service stations focusing on eco-friendly practices like waste reduction, energy-efficient equipment, and green garages.
- Consumer preferences for on-demand services and mobile maintenance will shape the service delivery model, prompting stations to adopt digital solutions and remote diagnostics.
- Regulatory pressures related to emissions and environmental impact will influence the development of cleaner service solutions.
- The growing preference for preventive maintenance will fuel demand for scheduled service packages, helping service stations generate recurring revenue.
- Increased urbanization in emerging markets will create new opportunities for service stations, especially in regions like Asia-Pacific and Latin America.
- Collaborations and partnerships between service stations and automotive manufacturers will help improve service offerings and enhance customer experiences.
- As the market becomes more fragmented, both large chains and independent stations will need to differentiate themselves through customer-centric innovations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Vehicle Ownership in Emerging Economies
Increasing disposable incomes and urbanization in countries like China and India are leading to higher personal vehicle ownership, directly boosting demand for garage and service station maintenance and repair services.
Technological Advancements in Automotive Industry
The proliferation of electric and hybrid vehicles is creating new service requirements, prompting service stations to invest in specialized equipment and training, thereby expanding their service offerings and market reach.
Emphasis on Preventive Maintenance
Consumers are increasingly prioritizing regular vehicle maintenance to extend vehicle lifespan and avoid costly repairs, driving demand for scheduled service packages and routine check-ups at service stations.
Shift Toward Eco-Friendly and Sustainable Services
Growing environmental awareness and regulatory pressures are encouraging service stations to adopt green practices, such as energy-efficient equipment and renewable fuels, attracting environmentally conscious customers and opening new market segments.
Adoption of Digital and On-Demand Service Models
The integration of digital technologies, such as online booking, remote diagnostics, and mobile maintenance services, is enhancing customer convenience and operational efficiency, making service stations more competitive and accessible.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size and expected growth rate of the Garage and Service Station sector?
What factors are driving the growth of the Garage and Service Station market?
Which regions are leading in the Garage and Service Station market?
How are environmental trends influencing the Garage and Service Station market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Sector
- 1.2.1 Automotive
- 1.2.2 Commercial
- 1.2.3 Residential
- 1.3 By Product Type
- 1.3.1 Fueling
- 1.3.2 Vehicle Maintenance
- 1.3.3 Repair Services
- 1.3.4 Car Washing
- 1.4 By Ownership Type
- 1.4.1 Independent Service Stations
- 1.4.2 Chain Service Stations
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,045 million → 2032: USD 9,732.67 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Garage and Service Station Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Garage and Service Station Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Garage and Service Station Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Garage and Service Station Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Garage and Service Station Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Garage and Service Station Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Garage and Service Station Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Garage and Service Station Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,045 million → 2032: USD 9,732.67 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Garage and Service Station Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Sector - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Commercial
- 12.3.7.3 Residential
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fueling
- 12.4.7.2 Vehicle Maintenance
- 12.4.7.3 Repair Services
- 12.4.7.4 Car Washing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Ownership Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Independent Service Stations
- 12.5.7.2 Chain Service Stations
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Garage and Service Station Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Garage and Service Station Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Garage and Service Station Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Firestone
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pep Boys
- 17.4 Autoliv
- 17.5 Midas
- 17.6 Safelite Group
- 17.7 Monro Muffler Brake
- 17.8 Lithia Motors
- 17.9 Advance Auto Parts
- 17.10 Napa Auto Parts
- 17.11 Hendrick Automotive Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

