
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
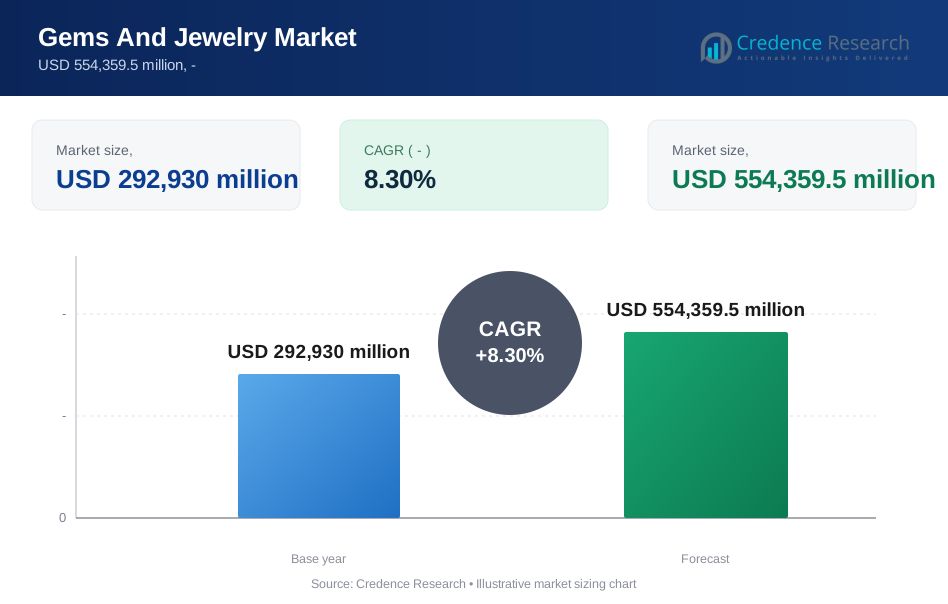
| Gems and Jewelry Market Size 2024 | USD 292,930 million |
| Gems and Jewelry Market, CAGR | 8.3% |
| Gems and Jewelry Market Size 2032 | USD 554,359.5 million |
Market Overview:
The Gems and Jewelry Market is projected to grow significantly, reaching an estimated market size of USD 292,930 million in 2024 and expanding to approximately USD 554,359.5 million by 2032, with a compound annual growth rate (CAGR) of 8.3% during the forecast period. This robust growth is fueled by rising consumer demand for luxury and high-end jewelry products, driven by increasing disposable income, shifting lifestyle trends, and a heightened focus on fashion and personal adornment. The expansion of e-commerce channels and digital transformation within the sector has also contributed to market growth, providing greater accessibility and a wider reach to customers globally.
Key factors driving the growth of the gems and jewelry market include increasing consumer spending on luxury goods, a rising middle-class population in emerging economies, and a strong preference for branded and customized jewelry. The growing significance of gems and jewelry as a form of investment has further fueled demand, especially for gold, diamonds, and other precious stones. The influence of social media, celebrity endorsements, and changing consumer preferences for contemporary and personalized designs have also positively impacted the market. Additionally, technological advancements in jewelry design and production, such as 3D printing and blockchain for authentication and traceability, continue to drive innovation and growth.
The gems and jewelry market exhibits strong regional dynamics, with Asia-Pacific emerging as a dominant player, holding a significant market share. Countries such as India and China are key contributors due to their long-standing cultural association with jewelry, increasing disposable incomes, and growing demand for luxury and wedding-related items. North America is also a prominent market, driven by strong demand for diamond and fashion jewelry, along with increasing online retail channels. Europe remains a significant player, fueled by luxury brands and established design houses. Meanwhile, the Middle East's demand is bolstered by a strong preference for gold jewelry and high-value gemstones, reflecting regional cultural and religious practices.
Market Drivers:
Rising Disposable Incomes and Middle-Class Expansion:
Increasing disposable incomes and the expansion of the middle-class population, particularly in emerging markets, have been major drivers of the gems and jewelry market. Governments in countries like India and China have reported consistent growth in per capita income over the past decade, creating a larger consumer base willing to spend on luxury items. For example, the Indian Ministry of Finance highlighted a 7% increase in household income in 2022, which has translated into higher spending on high-value and luxury items, including gems and jewelry. This trend has fueled demand for both traditional and contemporary jewelry items.
Growing Demand for Customization and Personalization:
Consumer preferences have shifted towards customized and personalized jewelry pieces, as customers seek unique and meaningful designs that reflect their identity. Companies have responded by introducing advanced customization options, leveraging technologies such as 3D printing and design software. For instance, a major global jewelry brand reported that 30% of its 2023 sales were attributed to bespoke and made-to-order items. This trend aligns with consumer desires for exclusivity, further driving market growth by offering tailored solutions that cater to individual tastes.
Influence of Digital and Social Media Platforms:
The influence of social media and digital platforms has significantly shaped consumer behavior in the gems and jewelry market. According to a survey, more than 50% of jewelry purchases in 2022 were influenced by social media channels. Leading brands and designers have harnessed platforms like Instagram and TikTok to showcase collections, engage directly with consumers, and build brand loyalty. The proliferation of digital marketing campaigns, influencer collaborations, and virtual try-on technologies have created an immersive and engaging buying experience, boosting consumer interest and market growth.
Technological Advancements and Innovations:
Technological advancements have transformed the gems and jewelry market, enhancing design, production, and authentication processes. Blockchain technology has gained prominence for ensuring transparency and traceability in the supply chain, helping companies combat counterfeit products. For example, De Beers introduced a blockchain-based diamond traceability system that tracks stones from mining to retail. Innovations like 3D printing have also enabled faster prototyping and production of intricate designs, leading to greater efficiency and cost reduction, thus attracting both consumers and manufacturers.
Market Trends:
Sustainable and Ethical Sourcing:
Sustainability and ethical sourcing have become key trends in the gems and jewelry market, as consumers increasingly demand transparency regarding the origins and production methods of their purchases. Companies are responding by adopting fair trade practices, conflict-free sourcing, and eco-friendly manufacturing processes. For example, a 2023 global consumer survey revealed that 70% of buyers consider sustainability important when purchasing jewelry. Major players, such as Tiffany & Co., have committed to using 100% responsibly sourced metals, and the company’s initiatives in this area have set a benchmark for ethical sourcing within the industry.
Rise of Lab-Grown Diamonds:
Lab-grown diamonds have gained significant traction in recent years, driven by their affordability, lower environmental impact, and ethical appeal compared to traditionally mined stones. According to a 2022 report by the U.S. Federal Trade Commission (FTC), consumer interest in lab-grown diamonds surged by 50% over the past three years. Leading brands, including Pandora, have embraced this trend, shifting entirely to lab-created diamonds for their collections to cater to environmentally conscious and cost-sensitive customers. This trend is reshaping the diamond market, creating new growth avenues and fostering innovation in diamond manufacturing technology.
E-Commerce and Omnichannel Retailing:
The growth of e-commerce and omnichannel retailing has revolutionized the way consumers shop for gems and jewelry. Online platforms offer a convenient, accessible, and engaging shopping experience, often augmented with virtual try-on features and detailed product visualizations. According to a 2023 industry report, over 30% of jewelry sales occurred through online channels, reflecting the growing preference for digital buying. Retailers have integrated online and in-store experiences, enabling customers to browse and purchase seamlessly across channels, enhancing customer satisfaction and loyalty.
Cultural and Regional Influences:
Cultural preferences and regional influences continue to shape consumer demand in the gems and jewelry market. For instance, traditional gold jewelry remains highly popular in regions like the Middle East and India, often used in weddings and cultural ceremonies. Government data from India shows that gold jewelry accounted for approximately 60% of total jewelry demand in 2022, reflecting its deep-rooted cultural significance. Conversely, Western markets are experiencing increased demand for minimalist and contemporary designs, driven by evolving fashion trends and lifestyle choices.
Market Challenges Analysis:
Volatility in Raw Material Prices:
One of the key restraints facing the gems and jewelry market is the volatility in the prices of raw materials such as gold, silver, diamonds, and other precious stones. Frequent fluctuations in commodity prices can significantly impact the cost structures of manufacturers and retailers, creating pricing challenges for end consumers. For instance, gold prices have shown considerable volatility due to global economic uncertainties and changes in interest rates, often influenced by policy actions from government bodies like the U.S. Federal Reserve. This unpredictability can deter consumer spending on high-value jewelry items, limiting market growth.
Stringent Regulatory Compliance:
The gems and jewelry industry are subject to stringent regulatory requirements imposed by various government authorities to ensure transparency, ethical sourcing, and environmental sustainability. For example, the European Union enforces strict conflict mineral regulations, compelling companies to trace and disclose the origins of their precious metals and stones. Similarly, the U.S. Securities and Exchange Commission (SEC) mandates compliance with conflict minerals reporting under the Dodd-Frank Act. Adhering to these regulations can be both complex and costly, particularly for small and medium-sized enterprises, adding compliance burdens and operational challenges.
Increasing Competition from Alternatives:
The rise of lab-grown diamonds and alternative jewelry materials presents a challenge to traditional gemstone and precious metal markets. Lab-grown diamonds, which offer a more affordable and ethically appealing alternative, have gained significant consumer traction, shifting demand away from mined diamonds. Government bodies like the U.S. Federal Trade Commission (FTC) have recognized and regulated lab-grown diamonds, influencing market dynamics. This shift poses a challenge for traditional players to maintain their competitive edge and differentiate themselves amid changing consumer preferences.
Impact of Economic Uncertainty:
Economic slowdowns and global crises can affect consumer spending on discretionary items such as luxury gems and jewelry. Events like recessions or financial crises often lead to reduced spending power, limiting demand for high-value items. This poses challenges for industry players, particularly during periods of economic downturn.
Market Segmentation Analysis:
By Type The gems and jewelry market is segmented into various types, including gold, diamond, platinum, gemstones, and others such as silver and pearl. Gold jewelry holds a significant share, driven by its cultural, religious, and investment appeal in regions such as Asia-Pacific and the Middle East. Diamonds also maintain a strong market position, favored for engagement rings, wedding bands, and luxury items. The demand for platinum jewelry is growing steadily, primarily among high-end consumers seeking exclusivity and durability, while colored gemstones are gaining popularity due to their vibrant appeal and customization potential.
By Technology The market segmentation by technology includes traditional handcrafting methods, casting, 3D printing, and advanced laser cutting. Traditional methods continue to dominate due to the cultural value and craftsmanship associated with bespoke jewelry pieces. However, 3D printing and laser cutting technologies are rapidly gaining traction, enabling precision, cost-effective production, and intricate designs. This adoption is revolutionizing the industry, offering faster prototyping and customization capabilities for consumers and manufacturers alike.
By End User The end-user segmentation comprises individual consumers, retailers, and institutional buyers. Individual consumers drive a substantial portion of the market, with demand varying from everyday fashion jewelry to luxury pieces. Retailers, including brick-and-mortar stores and e-commerce platforms, play a key role in distribution, while institutional buyers, such as collectors and investment firms, often focus on high-value and rare gemstones and metals, reflecting the market's diverse customer base.
Segmentations:
By Type
- Diamond in Gold
- Gold
- Platinum
- Silver
- Gemstones
- Diamond
- Others
By Product
- Rings
- Necklaces
- Earrings
- Bracelets
- Chains and Pendants
- Others
By Distribution Channel
- Online
- Offline
- Jewelry Stores
- Multi Branded Stores
- Standalone
By Application
- Collections
- Weddings
- Festive Blessing
- Fashions
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the gems and jewelry market, accounting for approximately 40% of global demand. The region’s dominance stems from strong cultural ties to jewelry, particularly in countries such as India and China, where it plays a central role in weddings, festivals, and other significant life events. India remains one of the largest consumers of gold jewelry globally, driven by traditions and a robust market for diamonds and precious gemstones. China is a key contributor, with growing demand for both traditional and contemporary designs, reflecting increased disposable incomes and changing consumer preferences. Economic growth, rising middle-class populations, and the rapid expansion of retail channels further drive market growth in the region.
North America
North America accounts for approximately 25% of the global gems and jewelry market. This region’s strong market position is driven by high demand for diamond engagement rings, luxury jewelry, and fashion-forward pieces. The United States leads, supported by a well-established retail network, significant online sales channels, and a strong affinity for premium and branded jewelry. Consumer preferences for lab-grown diamonds have also surged in recent years due to their affordability and ethical appeal. Canada contributes to market growth with a strong focus on premium gold and diamond jewelry, fueled by a stable economy and robust consumer spending on luxury products.
Europe
Europe holds around 20% of the market share, characterized by a rich tradition of fine craftsmanship, luxury brands, and heritage design houses. Countries such as Italy, France, and the United Kingdom are major players, catering to both domestic demand and international exports of high-end jewelry. The European market is distinguished by its emphasis on quality, unique designs, and ethically sourced materials, driven by strict regulatory standards and a focus on sustainability. Germany, in particular, stands out with its strong engineering expertise in precision jewelry-making, while the U.K. is known for combining traditional craftsmanship with modern styles.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively represent about 15% of the market. In Latin America, Brazil and Mexico are leading contributors, with a blend of traditional gold jewelry and contemporary designs. The Middle East and Africa region, known for its high demand for intricate gold jewelry and gemstones, is driven by cultural traditions and substantial spending on luxury items. Despite facing economic and regulatory challenges, these regions are experiencing steady market growth due to increasing disposable incomes and demand for luxury and bespoke jewelry.
Key Player Analysis:
- Tiffany & Co.
- Cartier
- Harry Winston
- Bvlgari
- Van Cleef & Arpels
- Graff
- Chopard
- Mikimoto
- Buccellati
- Piaget
Competitive Analysis:
The gems and jewelry market are highly competitive, characterized by the presence of established luxury brands, regional jewellers, and emerging players. Leading brands such as Tiffany & Co., Cartier, and Harry Winston dominate the high-end segment with strong brand equity, exquisite craftsmanship, and exclusive collections that appeal to affluent consumers. These major players emphasize innovation, ethical sourcing, and sustainability initiatives to maintain market leadership and align with evolving consumer values. Meanwhile, regional players and independent jewellers focus on customization, cultural designs, and unique offerings to differentiate themselves. The increasing demand for lab-grown diamonds and alternative materials has also intensified competition, encouraging both established and emerging companies to innovate and adapt. Digital transformation, e-commerce expansion, and strategic partnerships further shape the competitive landscape, as companies seek to enhance consumer engagement and streamline operations in a dynamic global market.
Recent Developments:
- In 2023, Tiffany & Co. unveiled its "Blue Book" high jewelry collection, showcasing innovative designs and rare gemstones, reinforcing its position in the luxury segment.
- In 2024, Cartier expanded its "Clash de Cartier" collection, introducing bold, contemporary pieces that blend traditional craftsmanship with modern aesthetics, appealing to a younger demographic.
- In 2022, Harry Winston launched the "Winston with Love" collection, featuring heart-shaped motifs and vibrant colored gemstones, celebrating romantic themes and attracting a diverse clientele.
- In 2023, Bvlgari introduced the "Magnifica" high jewelry collection, emphasizing Italian heritage and artistry through intricate designs and exceptional gemstones, solidifying its reputation for opulence.
Market Concentration & Characteristics:
The gems and jewelry market are characterized by moderate to high market concentration, with several well-established luxury brands dominating the global landscape alongside regional and independent players. Major brands such as Tiffany & Co., Cartier, and Bvlgari leverage their strong brand heritage, craftsmanship, and premium positioning to capture a significant share of the luxury segment. These leaders emphasize innovation, ethical sourcing, and high-end customization, appealing to affluent consumers worldwide. Regional jewellers and smaller independent players, on the other hand, cater to local tastes, traditions, and personalized preferences, offering diverse product ranges at varying price points. The market is further defined by trends such as sustainability, digital transformation, and the increasing popularity of lab-grown diamonds. The competitive dynamics encourage constant product innovation, strategic collaborations, and efforts to adapt to evolving consumer expectations, shaping a market that blends tradition, luxury, and modernity.
Report Coverage:
The research report offers an in-depth analysis based on Type, Product, Distribution Channel, and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The gems and jewelry market are expected to witness robust demand driven by rising disposable incomes and increasing consumer interest in luxury and personalized items.
- Digital transformation and the expansion of e-commerce channels will continue to reshape consumer buying behavior, offering enhanced accessibility and personalized online experiences.
- Growing consumer awareness around sustainability and ethical sourcing will prompt manufacturers to adopt eco-friendly practices and transparent supply chains.
- Lab-grown diamonds are projected to gain greater market share, appealing to environmentally conscious and cost-sensitive consumers due to their affordability and ethical considerations.
- Demand for customization and bespoke jewelry is likely to grow as consumers seek unique designs that reflect their personal identities and special occasions.
- Technological advancements such as 3D printing and blockchain for traceability will drive innovation and efficiency in jewelry production and authentication.
- Emerging markets, particularly in Asia-Pacific and the Middle East, are poised to contribute significantly to market growth due to cultural traditions and rising wealth.
- High demand for lightweight, contemporary designs will influence product development, particularly among younger demographics seeking fashion-forward and versatile jewelry.
- Partnerships between luxury brands and high-profile influencers or celebrities will continue to shape consumer preferences and enhance brand visibility.
- Regulatory pressures around conflict-free and ethically sourced materials will encourage the adoption of responsible business practices, driving industry transformation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Incomes and Middle-Class Expansion
Increasing disposable incomes and the growth of the middle-class population, especially in emerging markets like India and China, are expanding the consumer base for luxury and high-value jewelry, driving overall market growth.
Growing Demand for Customization and Personalization
Consumers are increasingly seeking unique, bespoke jewelry pieces that reflect their personal style and identity, prompting brands to offer advanced customization options and driving higher-value sales.
Influence of Digital and Social Media Platforms
Social media and digital marketing have transformed consumer engagement, with platforms like Instagram and TikTok influencing over half of jewelry purchases and enabling brands to reach wider, younger audiences.
Technological Advancements and Innovations
Innovations such as 3D printing and blockchain for authentication are streamlining production, enabling intricate designs, and ensuring traceability, which enhances consumer trust and operational efficiency.
Sustainable and Ethical Sourcing
Rising consumer awareness around sustainability and ethical sourcing is pushing brands to adopt responsible practices, such as conflict-free sourcing and eco-friendly manufacturing, which is increasingly a key purchase criterion for buyers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Gems and Jewelry Market?
What factors are driving the growth of the Gems and Jewelry Market?
What are some challenges faced by the Gems and Jewelry Market?
Who are the major players in the Gems and Jewelry Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Diamond in Gold
- 1.2.2 Gold
- 1.2.3 Platinum
- 1.2.4 Silver
- 1.2.5 Gemstones
- 1.2.6 Diamond
- 1.2.7 Others
- 1.3 By Product
- 1.3.1 Rings
- 1.3.2 Necklaces
- 1.3.3 Earrings
- 1.3.4 Bracelets
- 1.3.5 Chains and Pendants
- 1.3.6 Others
- 1.4 By Application
- 1.4.1 Collections
- 1.4.2 Weddings
- 1.4.3 Festive Blessing
- 1.4.4 Fashions
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 292,930 million → 2032: USD 554,359.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gems And Jewelry Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gems And Jewelry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gems And Jewelry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gems And Jewelry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gems And Jewelry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gems And Jewelry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gems And Jewelry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gems And Jewelry Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 292,930 million → 2032: USD 554,359.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gems And Jewelry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diamond in Gold
- 12.3.7.2 Gold
- 12.3.7.3 Platinum
- 12.3.7.4 Silver
- 12.3.7.5 Gemstones
- 12.3.7.6 Diamond
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rings
- 12.4.7.2 Necklaces
- 12.4.7.3 Earrings
- 12.4.7.4 Bracelets
- 12.4.7.5 Chains and Pendants
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Collections
- 12.5.7.2 Weddings
- 12.5.7.3 Festive Blessing
- 12.5.7.4 Fashions
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gems And Jewelry End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gems And Jewelry Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gems And Jewelry Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gems And Jewelry Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tiffany & Co.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cartier
- 18.4 Harry Winston
- 18.5 Bvlgari
- 18.6 Van Cleef & Arpels
- 18.7 Graff
- 18.8 Chopard
- 18.9 Mikimoto
- 18.10 Buccellati
- 18.11 Piaget
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

