
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Bamboos Market Size 2023 | USD 75,102.79 Million |
| Bamboos Market, CAGR | 5.65% |
| Bamboos Market Size 2032 | USD 123,163.38 Million |
Market Overview
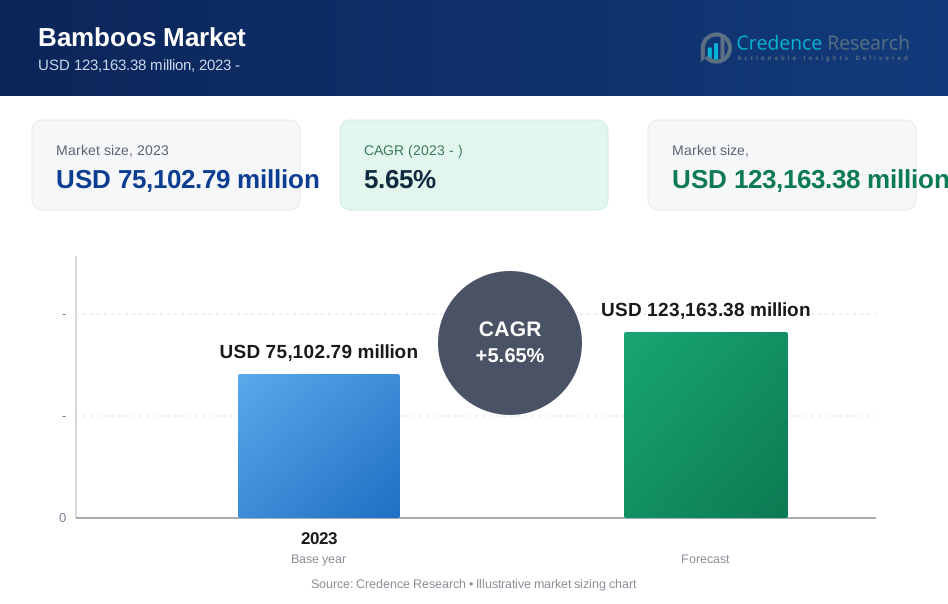
The global bamboo market is projected to grow from USD 75,102.79 million in 2023 to USD 123,163.38 million by 2032, at a CAGR of 5.65%.
The bamboo market is driven by increasing environmental concerns and the growing adoption of sustainable materials. Bamboo is a highly renewable resource with significant carbon sequestration capabilities, it is becoming a favored material in various sectors, including construction, textiles, and furniture. Additionally, advancements in processing technologies are enhancing bamboo's versatility and durability, further boosting its appeal. The market is also benefiting from governmental support for eco-friendly initiatives and the rising consumer preference for green products. These factors collectively propel the global demand for bamboo, setting a robust trajectory for market growth.
Geographically, the bamboo market is dominated by Asia-Pacific, primarily due to the abundant bamboo forests and established bamboo industries in countries like China and India. These nations lead in bamboo production and its innovative applications across various sectors. North America and Europe are experiencing growth due to rising environmental awareness and the adoption of sustainable materials. Key players in the market include Bamboo Village Company Limited, Shanghai Tenbro Bamboo Textile Co., Bamboo Australia Pty Ltd, and Smith & Fong Co., which focus on expanding their global reach and improving bamboo product offerings to capitalize on the growing market demand.
Market Drivers
Sustainability and Eco-Friendliness
The shift towards more sustainable resources like bamboo is a testament to the growing environmental consciousness among consumers. For instance, bamboo plantations can absorb up to 12 tons of carbon dioxide per hectare yearly and produce 35% more oxygen than an equivalent area of trees. This makes bamboo a valuable resource for mitigating climate change. However, the rate of deforestation has decreased over the past three decades. The world has lost one-third of its forest-an area twice the size of the United States. Bamboo, as a strategic resource, can alleviate poverty, develop economies, address climate change through sustainable management and utilization, and hence, can contribute significantly to the accomplishment of the UN 2030 Agenda for Sustainable Development Goals (SDGs), the UN Strategic Plan for Forests 2017–2030, the Paris Agreement adopted under the United Nations Framework Convention on Climate Change (UNFCCC), green growth of the Organisation for Economic Co-operation and Development (OECD), and the Reducing Emissions from Deforestation and Forest Degradation (REDD+) targets of the UNFCCC.
Growing Demand for Eco-Friendly Products
Amid rising environmental consciousness, there is an escalating demand for eco-friendly products. A study revealed that there’s a clear and substantive correlation between consumer spending and sustainability-related claims on product packaging. Another report indicates that sustainable products have an overall 17% market share and a 32% share of growth, and they grew 2.7x faster than those that were not marketed as sustainable. Bamboo, with its sustainable attributes, is increasingly appealing to both manufacturers and consumers. Bamboo’s applications cut across various sectors, including construction materials like flooring and scaffolding, consumer products such as furniture and textiles, and even innovative areas like biofuel production. This broad utility is enhancing its marketability and bolstering the market’s expansion.
Versatility and Wide Range of Applications
Bamboo is celebrated for its strength, flexibility, and aesthetic appeal, making it versatile across various applications. Bamboo’s strength, flexibility, and aesthetic appeal make it a versatile material across various applications. For instance, bamboo’s tensile strength varies in the range of 70–210 MPa, its compressive strength is 20–65 MPa, its elastic modulus is 2500–17500 MPa, and its modulus of rupture is 50–200 MPa. This makes bamboo an ideal material for construction materials like flooring and scaffolding. Bamboo shows great potential when it comes to innovative areas like biofuel production. Bamboo’s remarkable growth rate, high biomass production, and low input requirements make it a promising candidate for biofuel production. As a lignocellulosic material, bamboo contains cellulose, hemicellulose, and lignin, which can be converted into fermentable sugars for ethanol production. The charcoal yield from bamboo ranges from 24.60 to 74.27%.
Innovation in Processing Techniques and Government Support
Technological advancements in bamboo processing are pivotal in improving its durability and suitability for diverse applications, including more resilient building materials and attractive consumer products. Furthermore, supportive government initiatives and regulations promoting sustainable resources and curtailing deforestation provide a conducive environment for the growth of the bamboo market. These factors collectively facilitate the development of bamboo as a preferred material, aligning with increasing consumer preferences for sustainability and quality in emerging economies.
Market Trends
Innovative Developments in Bamboo Composites and Fabrics
The bamboo industry is indeed transforming with the development of high-tech bamboo composites and advancements in bamboo textiles. Integrating bamboo fibers with resins or polymers creates materials that are not only stronger and more durable but also have enhanced fire resistance. These properties are essential for their application in sectors that demand high material integrity, such as construction and automotive interiors. Bamboo is becoming increasingly popular in the realm of textiles due to its sustainability and the development of new processing techniques. These techniques produce bamboo fabrics that are softer and more breathable, making them ideal for clothing and bedding. Furthermore, the advancements in dyeing technologies are expanding the range of colors available, catering to the fashion industry’s needs.
Sustainable Building and Aesthetic Innovation in Bamboo Usage
Bamboo is indeed making significant strides in sustainable building practices. Its environmental benefits, such as being a renewable resource that requires minimal energy to grow and its role in preventing soil erosion and providing biomass, make it an attractive choice for eco-conscious architects and builders. Bamboo’s lightweight nature and strength allow it to be used for various structural elements, including flooring, wall panels, and even roofing. The design and aesthetics of bamboo products have evolved, with manufacturers now producing items that rival or exceed the visual appeal of traditional materials. This is particularly important in home décor and structural applications, where the demand for both functionality and beauty is high. The use of bamboo in interior design is not only sustainable but also adds elegance and a natural aesthetic to spaces. As bamboo continues to gain popularity in mainstream markets, its potential in sustainable construction and design seems boundless, offering a versatile and eco-friendly alternative that aligns with the growing trend of environmental responsibility.
Market Challenge Analysis
Challenges in Awareness, Quality Control, and Industry Infrastructure
One of the significant hurdles in the bamboo market is the limited awareness and familiarity with bamboo as a material, especially compared to well-established materials like wood or plastic. To drive wider adoption, it is essential to increase awareness among consumers, architects, builders, and manufacturers about bamboo’s beneficial properties and its diverse applications. This involves educating stakeholders about the environmental and structural benefits of bamboo, which are critical to its acceptance and use in broader markets. Moreover, the bamboo market frequently encounters challenges related to inconsistent product quality and a lack of standardization across the industry. Developing and implementing standardized grading systems and processing guidelines is vital to ensuring that bamboo products consistently meet high-quality standards. Standardization helps maintain product integrity, builds trust among users, and can spur greater adoption across various industries.
Overcoming competition and optimizing logistics
Bamboo also faces robust competition from entrenched materials that boast well-established supply chains and are often perceived as less risky, particularly in applications where durability and long-term performance are paramount. To counter this, it is crucial to highlight bamboo's sustainable advantages, such as its rapid renewability and lower environmental impact, along with competitive pricing structures tailored to specific applications where bamboo has a clear advantage.
Market segmentation analysis:
By End-Use Industry:
The bamboo market exhibits significant diversity in its applications, segmented broadly across various end-use industries. In the wood and furniture sector, bamboo is utilized as a timber substitute and in producing plywood, mat boards, flooring, furniture, and outdoor decking. This versatility underlines bamboo's appeal as a sustainable and durable material in the furniture industry. The construction sector also heavily employs bamboo, notably in scaffolding, housing, and road projects, leveraging its strength and resilience. Additionally, bamboo is gaining prominence in the food industry through bamboo shoots, recognized for their nutritional benefits. Other critical segments include pulp, paper, and textiles, where bamboo's fibrous nature is highly valued. Agriculture benefits from bamboo in terms of stakes and tools, while niche markets such as charcoal production and handicrafts further broaden its usage. Each segment showcases bamboo's adaptability and growing acceptance across diverse industries, driving the market forward.
By Type:
The global market for bamboos is also categorized based on the type of bamboo, which includes herbaceous bamboos, tropical woody bamboos, and temperate woody bamboos. Herbaceous bamboos, though less common, are used in specific niche applications due to their unique properties. Tropical woody bamboos are predominantly used in furniture and construction due to their robustness and higher growth rate, making them ideal for structural applications. Conversely, temperate woody bamboos, which thrive in cooler climates, are frequently utilized in products requiring higher durability and aesthetic appeal, such as high-quality furniture and decorative items. This segmentation by type allows for targeted development and marketing strategies, catering to the specific needs and conditions of different global regions, thus optimizing growth within the bamboo market.
Segmentations:
Based on End-Use Industry:
- Wood and furniture
-
- Timber Substitute
- Plywood
- Mat Boards
- Flooring
- Furniture
- Outdoor Decking
- Construction
- Scaffolding
- Housing
- Roads
- Food (bamboo shoots)
- Pulp and paper
- Textile
- Agriculture
- Others (charcoal and handicrafts)
Based on type:
- Herbaceous Bamboos
- Tropical Woody Bamboos
- Temperate woody bamboos
Based on the geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America captures a 10% market share, driven by the growing popularity of bamboo as a sustainable and versatile material in various applications, including flooring, furniture, and outdoor structures. The United States remains the largest contributor to the North American market, followed by Canada, where environmental consciousness and aesthetics drive the demand for bamboo products.
Asia-Pacific
Asia-Pacific currently dominates the market, capturing a substantial 60% share. This region's prominence can be attributed to the long-standing cultural and traditional use of bamboo in various applications, including construction, furniture, and handicrafts. Countries like China, India, and Southeast Asian nations are the key contributors to the Asia-Pacific market's growth, fueled by the abundance of bamboo resources and the increasing awareness of bamboo's sustainability and versatility.
Key Player Analysis
- MOSO International B.V.
- Bamboo Australia
- Bamboo Village Company Limited
- Shanghai Tenbro Bamboo Textile Co., Ltd.
- Simply Bamboo Pty Ltd.
- Xiamen HBD Industry & Trade Co., Ltd.
- Dassogroup
- Smith & Fong
- Anji Tianzhen Bamboo Flooring Co., Ltd.
- Fujian HeQiChang Bamboo Product Co., Ltd.
Competitive Analysis
In the competitive landscape of the bamboo market, MOSO International B.V. stands out for its extensive range of bamboo products, including flooring and decking, which are well-regarded globally. Bamboo Australia also plays a significant role, primarily focusing on the eco-friendly segment and promoting bamboo as a sustainable alternative in various applications. Bamboo Village Company Limited and Shanghai Tenbro Bamboo Textile Co., Ltd. are key players in the textile sector, specializing in bamboo fiber products known for their softness and environmental benefits. Simply Bamboo Pty Ltd. and Xiamen HBD Industry & Trade Co., Ltd. cater to both domestic and international markets with a diverse product lineup ranging from bamboo kitchenware to furniture. Dastogroup and Smith & Fong excel at providing innovative architectural solutions and bamboo wall panels, targeting the construction and design industries. Lastly, Anji Tianzhen Bamboo Flooring Co., Ltd. and Fujian HeQiChang Bamboo Product Co., Ltd. focus on bamboo flooring products, emphasizing durability and aesthetic appeal to meet rising consumer demands in the flooring market segment.
Recent Developments
In September 2022, Libas Consumer Products Ltd. announced a rights issue and launched the bamboo-based 'Organic Innerwear' brand 'KNG.' This launch replaces regular innerwear due to its sustainable and non-allergic aspects.
Market Concentration and Characteristics
The bamboo market is characterized by a moderate level of market concentration, with a few key players dominating the landscape while numerous smaller companies serve niche segments. Leading companies such as MOSO International B.V., Bamboo Australia, and Smith & Fong leverage their extensive research and development capabilities to innovate and expand their product offerings, thereby securing significant market shares. These major players have established strong distribution networks globally, which enhances their market reach and customer base. Additionally, the bamboo market is diverse, catering to various sectors such as construction, textiles, and consumer goods, each requiring specific types of bamboo products. This diversity allows for a wide range of specialized firms to coexist and thrive within the market. As environmental sustainability becomes a higher priority worldwide, the market is poised for further growth, with increased opportunities for both existing companies and new entrants.
Report Coverage
The research report offers an in-depth analysis based on end-use industry, type, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The bamboo market is expected to experience substantial growth driven by increasing global demand for sustainable and eco-friendly materials.
- Technological advancements in bamboo processing will enhance product quality and expand application areas.
- Growing environmental awareness will continue to push consumers towards bamboo-based products in sectors such as construction, textiles, and furniture.
- The expansion of bamboo use in non-traditional markets like biofuels and bioplastics is anticipated.
- Government policies and incentives promoting sustainable practices will further boost the bamboo industry.
- Increased investment in research and development will lead to innovative uses of bamboo, particularly in high-performance applications.
- The rise in bamboo adoption in the construction industry for green building projects is likely to continue.
- E-commerce platforms will play a crucial role in increasing the market reach of bamboo products, especially in less saturated markets.
- More stringent quality standards and certifications will be developed to ensure product consistency and foster trust among consumers.
- The global expansion of bamboo cultivation to non-traditional regions will address supply constraints and reduce transportation costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainability and Eco-Friendliness
Bamboo's rapid renewability, high carbon sequestration, and ability to produce more oxygen than trees make it a preferred material for mitigating climate change and supporting global sustainability goals. This environmental advantage is driving adoption across industries seeking greener alternatives.
Growing Demand for Eco-Friendly Products
Consumers and manufacturers are increasingly seeking sustainable materials, and bamboo's attributes - such as biodegradability and low environmental impact - make it highly attractive for use in construction, textiles, and consumer goods, fueling market expansion.
Versatility and Wide Range of Applications
Bamboo's strength, flexibility, and aesthetic appeal allow it to be used in diverse sectors, from construction and furniture to textiles and biofuels. Its adaptability to various end-uses increases its marketability and broadens its adoption.
Innovation in Processing Techniques and Government Support
Advancements in bamboo processing technologies are improving product durability and expanding application areas, while supportive government policies and incentives for sustainable materials are accelerating market growth.
Expansion in Non-Traditional Markets
Bamboo is increasingly being used in innovative applications such as biofuels, bioplastics, and high-performance composites, opening new revenue streams and driving further market penetration beyond traditional uses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the bamboo market?
What factors are driving the growth of the bamboo market?
What are the key segments within the bamboo market?
What are some challenges faced by the bamboo market?
Who are the major players in the bamboo market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Herbaceous Bamboos
- 1.2.2 Tropical Woody Bamboos
- 1.2.3 Temperate Woody Bamboos
- 1.3 By End-Use Industry
- 1.3.1 Wood and Furniture (Timber Substitute, Plywood, Mat Boards, Flooring, Furniture, Outdoor Decking)
- 1.3.2 Construction (Scaffolding, Housing, Roads)
- 1.3.3 Food (Bamboo Shoots)
- 1.3.4 Pulp and Paper
- 1.3.5 Textile
- 1.3.6 Agriculture
- 1.3.7 Others (Charcoal, Handicrafts)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 75,102.79 million → 2032: USD 123,163.38 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bamboos Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bamboos Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bamboos Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bamboos Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bamboos Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bamboos Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bamboos Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bamboos Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 75,102.79 million → 2032: USD 123,163.38 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bamboos Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Herbaceous Bamboos
- 12.3.7.2 Tropical Woody Bamboos
- 12.3.7.3 Temperate Woody Bamboos
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wood and Furniture (Timber Substitute, Plywood, Mat Boards, Flooring, Furniture, Outdoor Decking)
- 12.4.7.2 Construction (Scaffolding, Housing, Roads)
- 12.4.7.3 Food (Bamboo Shoots)
- 12.4.7.4 Pulp and Paper
- 12.4.7.5 Textile
- 12.4.7.6 Agriculture
- 12.4.7.7 Others (Charcoal, Handicrafts)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bamboos End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bamboos Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bamboos Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bamboos Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 MOSO International B.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bamboo Australia Pty Ltd
- 18.4 Bamboo Village Company Limited
- 18.5 Shanghai Tenbro Bamboo Textile Co., Ltd.
- 18.6 Simply Bamboo Pty Ltd.
- 18.7 Xiamen HBD Industry & Trade Co., Ltd.
- 18.8 Dassogroup
- 18.9 Smith & Fong Co.
- 18.10 Anji Tianzhen Bamboo Flooring Co., Ltd.
- 18.11 Fujian HeQiChang Bamboo Product Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

