
Market Overview:
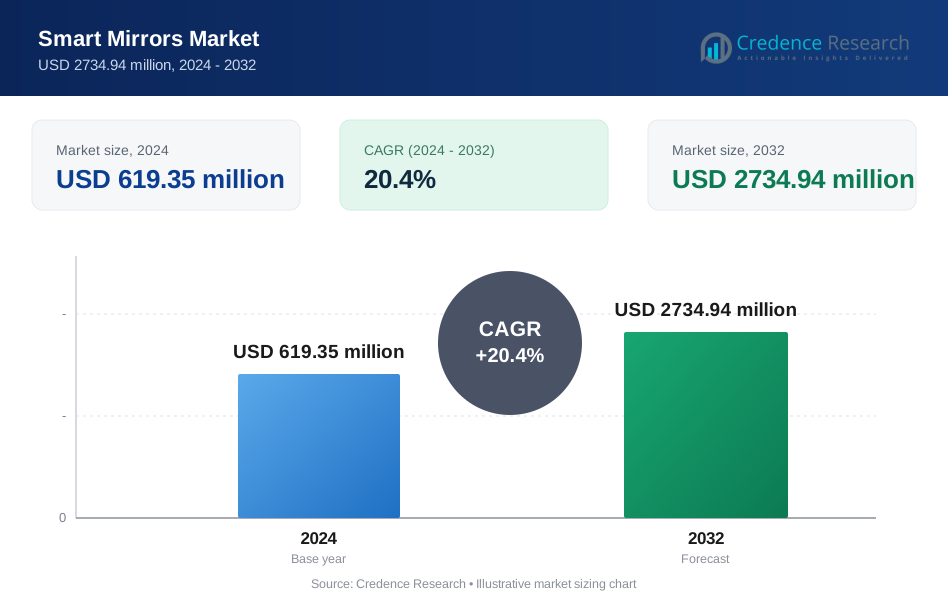
Smart Mirror Market size was valued USD 619.35 million in 2024 and is anticipated to reach USD 2734.94 million by 2032, at a CAGR of 20.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Mirror Market Size 2024 | USD 619.35 million |
| Smart Mirror Market, CAGR | 20.4% |
| Smart Mirror Market Size 2032 | USD 2734.94 million |
The Smart Mirror Market is shaped by leading players including Kohler Company, Electric Mirror, Inc, AD Natom AG, Dension Evervue, Gentex Corporation, Keonn Technologies SL, Avis Electronics Corporation, Harman International Industries, LumiDesign, and Ficoca International SA. These companies emphasize innovation, advanced integration of AI and IoT, and strategic expansion across residential, automotive, retail, and healthcare applications. Gentex Corporation drives dominance in automotive solutions, while Kohler Company and Electric Mirror, Inc lead in premium residential and hospitality segments. Regionally, North America commands the largest share at 35% in 2024, supported by strong adoption in automotive safety systems, widespread smart home penetration, and advanced retail solutions.

Market Insights
- The Smart Mirror Market was valued at USD 619.35 million in 2024 and is expected to reach USD 2734.94 million by 2032, growing at a CAGR of 20.4%.
- Market growth is driven by rising demand in automotive safety systems, expanding smart home adoption, and increasing integration in healthcare and retail applications.
- Key trends include the integration of AI, IoT, and AR technologies that enhance personalization, connectivity, and interactive shopping experiences across industries.
- The market is competitive, with players such as Kohler Company, Electric Mirror, Inc, Gentex Corporation, and Harman International Industries focusing on innovation, while high costs of advanced hardware remain a key restraint.
- Regionally, North America holds the largest share at 35% in 2024, followed by Europe at 30% and Asia Pacific at 25%, with automotive applications leading at over 40% share, supported by regulatory standards and growing consumer demand for connected vehicles.
Market Segmentation Analysis:
By Component
In the Smart Mirror Market, hardware holds the dominant share, accounting for over 60% of the segment. The strong demand is driven by integrated displays, sensors, and camera technologies that form the foundation of smart mirror functions. Hardware dominance stems from rising adoption in automotive rearview mirrors, retail fitting rooms, and healthcare diagnostic tools, where physical components are essential. Continuous improvements in display quality, sensor accuracy, and touch-enabled interfaces further strengthen hardware’s position, while software and services act as supporting elements to enhance overall functionality.
- For instance, Electric Mirror’s Savvy Smart Mirror Brilliance and Elite mirror's indicate that they are equipped with LEDs that have a Color Rendering Index (CRI) of 90 or greater.
By Application
The automotive segment leads the Smart Mirror Market with over 40% share, driven by safety and comfort features. Advanced driver-assistance systems (ADAS), blind-spot detection, and integrated navigation have made smart mirrors essential in modern vehicles. Automakers are investing heavily in digital rearview mirrors to improve driver visibility and comply with safety standards. While residential and retail applications are gaining traction through smart homes and interactive shopping experiences, automotive adoption remains strongest due to regulatory support, increasing vehicle connectivity, and consumer demand for advanced driving solutions.
- For instance, Evervue’s MirrorVue line supports TV sizes from 15.6" up to 75" and is designed with a slim profile of just 38 mm (1.5") thick, including the TV and mirror. This makes it one of the thinnest mirror TVs on the market.
By Distribution Channel
Offline channels dominate the Smart Mirror Market, holding nearly 70% share, owing to the high-value and demonstration-driven nature of these products. Customers prefer physical stores, showrooms, and specialty outlets to experience functionality before purchase, especially in automotive and retail applications. Offline dominance is reinforced by partnerships between manufacturers, retailers, and automobile dealers. However, online channels are witnessing rapid growth fueled by expanding e-commerce platforms, convenience, and rising awareness among residential buyers. The shift toward digital retailing highlights a growing balance, but offline networks remain the leading distribution route.
Market Overview
Rising Demand in Automotive Industry
The automotive sector is a key growth driver in the Smart Mirror Market, as manufacturers integrate advanced features like digital rearview mirrors, blind-spot detection, and navigation systems. Growing safety regulations and the adoption of ADAS technologies fuel higher installation rates across premium and mid-range vehicles. Consumers increasingly value enhanced visibility and connectivity, which strengthens the role of smart mirrors in modern vehicles. Automakers’ investments in technology integration further support the segment’s expansion, positioning automotive applications as a primary contributor to market growth.
- For instance, Keonn’s AdvanMirror is available in 27-inch and 43-inch interactive displays and integrates two built-in RFID antennas that detect tagged items brought within the mirror's detection zone.
Expansion of Smart Homes and Residential Adoption
The rapid growth of smart homes significantly drives the adoption of smart mirrors, especially for personal grooming, fitness tracking, and home automation. Consumers are drawn to AI-enabled mirrors that provide health insights, voice assistance, and personalized content. Rising disposable incomes and increasing awareness of connected devices further boost residential demand. Integration with platforms like Alexa and Google Home enhances user experience, making smart mirrors more appealing in households. The expanding smart home ecosystem ensures strong long-term growth for the residential application segment.
- For instance, Avis Electronics (brand AVEL) produces mirror TVs with screen diagonals from 23.8 inch to 75 inch, offering Full HD models for 23.8" and 32" units, and Ultra HD 4K for 43", 55", 65", 75".
Technological Advancements in Retail and Healthcare
Retail and healthcare sectors are increasingly embracing smart mirrors due to innovations in interactive technologies. In retail, smart mirrors enhance customer experience with virtual try-ons, personalized recommendations, and digital engagement tools. In healthcare, diagnostic-enabled smart mirrors support skin analysis, vital monitoring, and patient care improvements. Advancements in AI, augmented reality, and sensor technology drive adoption across these sectors. Retailers and healthcare providers leverage these tools to improve efficiency and customer satisfaction, strengthening demand and positioning smart mirrors as essential innovation-driven solutions.
Key Trends & Opportunities
Integration with AI and IoT Platforms
A prominent trend in the Smart Mirror Market is the integration of AI and IoT, enabling advanced personalization and connectivity. Smart mirrors now deliver health insights, fitness tracking, and interactive shopping experiences tailored to user preferences. IoT compatibility with other devices ensures seamless integration within connected ecosystems. This trend creates opportunities for developers and manufacturers to expand into multi-functional offerings. As consumers demand more intuitive experiences, AI-enabled mirrors that combine data-driven insights and personalized services open pathways for growth in residential and commercial use.
- For instance, LumiDesign’s iMira LED Vanity Mirror features an 8-inch HD mirror surface and offers a 5× magnification for close detail work, paired with a magnetic 10× spot mirror for ultra-fine inspection.
Growing E-commerce and Online Sales
The expansion of e-commerce presents a strong opportunity for the Smart Mirror Market, particularly within residential adoption. Online platforms enable greater reach, allowing manufacturers to target diverse customer bases beyond traditional retail stores. Rising consumer confidence in purchasing high-value electronics online accelerates digital distribution. Innovative marketing strategies, including virtual demonstrations and augmented reality tools, enhance consumer trust. This trend not only diversifies sales channels but also supports rapid adoption among tech-savvy users. E-commerce’s growth ensures a steady revenue stream and broader accessibility.
- For instance, Apple has been granted U.S. Patent No. 12,154,386, which describes combining facial recognition with additional body metrics (like gait, clothing, posture) to improve identification accuracy even when the face is partially obscured.
Key Challenges
High Cost of Smart Mirror Technology
One of the main challenges in the Smart Mirror Market is the high cost associated with advanced hardware and integrated features. Premium displays, sensors, and AI-enabled functions raise production expenses, making these products less affordable for mass-market adoption. Price sensitivity in emerging economies further limits penetration, as consumers prioritize cost-effective alternatives. Manufacturers face the challenge of balancing innovation with affordability. Without cost optimization, the widespread adoption of smart mirrors across residential and commercial applications could face significant delays.
Data Privacy and Security Concerns
Data privacy and security risks present another challenge in the Smart Mirror Market, particularly with AI-driven and IoT-connected mirrors. These devices often collect sensitive personal data, including health metrics and user behavior patterns. Concerns over misuse, unauthorized access, or breaches reduce consumer trust. Compliance with stringent data protection regulations further complicates product development for manufacturers. Addressing these security challenges is essential for ensuring consumer confidence and long-term adoption. Companies must invest in robust cybersecurity measures to safeguard personal data and maintain market credibility.
Regional Analysis
North America
North America holds the largest share of the Smart Mirror Market, accounting for 35% in 2024. The region benefits from strong adoption in the automotive sector, driven by advanced driver-assistance systems and rising integration of digital rearview mirrors in premium vehicles. Retail adoption is also significant, with leading brands deploying interactive mirrors to enhance customer engagement. High consumer spending on smart home devices further strengthens growth. Robust technological infrastructure and innovation-led strategies by manufacturers ensure the region’s leading position, while continued investment in automotive safety features sustains long-term market demand.
Europe
Europe represents 30% of the Smart Mirror Market share, supported by widespread adoption in both automotive and retail sectors. The region benefits from stringent road safety regulations, pushing automakers to integrate smart mirrors with ADAS features. Retailers increasingly deploy augmented reality-based smart mirrors to improve shopping experiences, particularly in fashion and luxury segments. Strong presence of leading automotive manufacturers across Germany, France, and the UK enhances regional demand. Rising awareness of connected devices in households also supports adoption, positioning Europe as a key growth hub within the global market.
Asia Pacific
Asia Pacific holds 25% share in the Smart Mirror Market and is the fastest-growing region. Rising automotive production in China, Japan, and South Korea drives demand for advanced mirror solutions integrated with safety and connectivity features. Expanding smart home ecosystems, particularly in urban centers, support residential adoption. Retailers across emerging economies like India and Southeast Asia explore interactive solutions to attract younger consumers. The region’s large consumer base, rapid digitalization, and cost-effective manufacturing capabilities position it as a major growth driver. Continuous technological investments ensure Asia Pacific’s expanding role in the market.
Latin America
Latin America accounts for 6% share of the Smart Mirror Market, with growth led by automotive and retail applications. Countries like Brazil and Mexico show increasing adoption of digital rearview mirrors as vehicle connectivity advances. Retail penetration is also growing, with fashion and cosmetic brands experimenting with virtual try-on solutions to improve customer experience. However, limited consumer purchasing power and high product costs restrict widespread adoption in residential settings. Despite these challenges, gradual digital transformation and partnerships with global manufacturers are expected to create steady opportunities in the coming years.
Middle East & Africa
The Middle East & Africa region holds 4% share of the Smart Mirror Market, driven by increasing adoption in luxury retail and premium automotive segments. Countries such as the UAE and Saudi Arabia are investing in advanced retail technologies, including AR-enabled mirrors, to strengthen customer engagement. Rising disposable incomes and growing preference for connected solutions in premium households further boost demand. However, market penetration remains limited in lower-income countries due to high product costs. Strategic partnerships and technology investments are likely to support gradual expansion, positioning the region as an emerging niche market.
Market Segmentations:
By Component:
- Hardware
- Software
By Application:
- Automotive
- Residential
By Distribution Channel:
- Online
- Offline
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The Smart Mirror Market features strong competition with key players such as Kohler Company, Electric Mirror, Inc, AD Natom AG, Dension Evervue, Gentex Corporation, Keonn Technologies SL, Avis Electronics Corporation, Harman International Industries, LumiDesign, and Ficoca International SA. The Smart Mirror Market is highly competitive, driven by continuous innovation and rapid adoption across multiple industries. Companies focus on integrating advanced features such as AI, IoT, and augmented reality to enhance product functionality and user experience. Automotive applications dominate, with growing demand for safety and connectivity features, while residential and retail sectors adopt smart mirrors for personalized services and interactive engagement. Healthcare providers also explore diagnostic-enabled solutions, expanding market opportunities. Intense competition encourages manufacturers to prioritize affordability, design innovation, and multi-functional capabilities, ensuring strong positioning in an evolving and technology-driven marketplace.
Key Player Analysis
- Kohler Company
- Electric Mirror, Inc
- AD Natom AG
- Dension Evervue
- Gentex Corporation
- Keonn Technologies SL
- Avis Electronics Corporation
- Harman International Industries
- LumiDesign
- Ficoca International SA
Recent Developments
- In May 2025, Brilliant NextGen, a leader in smart home innovation, unveiled its second-generation smart home products. It is designed to set a new benchmark in home automation. These user-friendly controls are engineered to deliver advanced functionality while integrating effortlessly with Brilliant’s existing product family, which includes smart dimmer switches, plugs, a mobile app, and a robust multifamily platform.
- In May 2025, Gopalan Enterprises proudly announced the launch of an AI-powered smart home project, catering to the growing demand from millennial buyers. The company plans to build 3,000 units by 2025, with an investment of ₹500 crore.
- In January 2025, Consumer Electronics Show (CES) was Withings’ OMNIA smart mirror. It scans a user to offer a holistic picture of their health and metrics. This highly advanced technology is raising the competition standard in the market.
- In June 2024, ABB launched ReliaHome Smart Panel, a new smart home energy management system. The product, intended for residential projects in the United States and Canada, was developed in partnership with software provider Lumin. The smart panel coordinates home energy assets, enabling energy optimization, circuit scheduling, and real-time control
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Smart Mirror Market will expand with rising adoption in automotive safety systems.
- Residential demand will grow as smart homes integrate connected mirror solutions.
- Retailers will increasingly deploy interactive mirrors to enhance customer experiences.
- Healthcare adoption will rise with diagnostic and monitoring-enabled smart mirrors.
- AI and IoT integration will drive personalization and real-time data connectivity.
- Online sales will grow as e-commerce platforms boost accessibility and reach.
- Cost optimization will support wider adoption across emerging economies.
- Luxury and premium segments will drive growth in hospitality and high-end retail.
- Partnerships between technology firms and automakers will accelerate innovation.
- Strong investments in AR and sensor technologies will shape future applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automotive Safety and Connectivity
Automotive manufacturers are rapidly integrating smart mirrors with advanced driver-assistance systems (ADAS), blind-spot detection, and digital rearview features to comply with safety regulations and meet consumer demand for connected vehicles, making automotive the leading application segment.
Smart Home Expansion
The proliferation of smart home ecosystems is driving residential adoption of smart mirrors, as consumers seek devices that offer personal health insights, voice assistance, and seamless integration with platforms like Alexa and Google Home.
Retail and Healthcare Innovation
Retailers are deploying interactive smart mirrors for virtual try-ons and personalized shopping experiences, while healthcare providers are adopting diagnostic-enabled mirrors for skin analysis and health monitoring, both of which are expanding the market’s reach.
Integration of AI, IoT, and AR Technologies
The incorporation of artificial intelligence, Internet of Things, and augmented reality into smart mirrors enables advanced personalization, real-time data connectivity, and interactive features, enhancing user experience and broadening application possibilities.
Growth of E-commerce and Digital Sales Channels
The rise of e-commerce platforms is making smart mirrors more accessible to a wider audience, especially in the residential segment, as online demonstrations and AR tools build consumer confidence and accelerate adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Smart Mirrors market?
What is the expected growth rate of the Smart Mirrors market between 2024 and 2032?
What are the primary factors fueling the growth of the Smart Mirror Market?
Which end users segment governs the demand for Smart Mirrors in the world?
Who are the major players in the global Smart Mirrors market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Residential
- 1.3.3 Retail
- 1.3.4 Healthcare
- 1.3.5 Hospitality
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 619.35 million → 2032: USD 2734.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Mirrors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Mirrors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Mirrors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Mirrors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Mirrors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Mirrors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Mirrors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Mirrors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 619.35 million → 2032: USD 2734.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Mirrors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Residential
- 12.4.7.3 Retail
- 12.4.7.4 Healthcare
- 12.4.7.5 Hospitality
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Mirrors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Mirrors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Mirrors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Mirrors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kohler Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Electric Mirror, Inc
- 18.4 Gentex Corporation
- 18.5 Harman International Industries
- 18.6 AD Natom AG
- 18.7 Dension Evervue
- 18.8 Keonn Technologies SL
- 18.9 Avis Electronics Corporation
- 18.10 LumiDesign
- 18.11 Ficoca International SA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

