
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
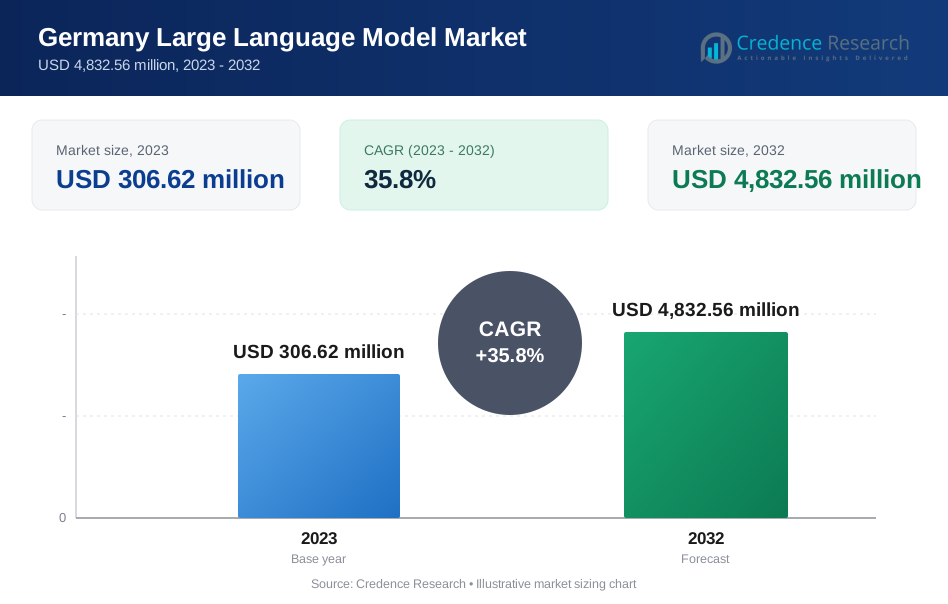
| Germany Large Language Model Market Size 2023 | USD 306.62 Million |
| Germany Large Language Model Market, CAGR | 35.8% |
| Germany Large Language Model Market Size 2032 | USD 4,832.56 Million |
Market Overview
The Germany Large Language Model Market is projected to grow from USD 306.62 million in 2023 to an estimated USD 4,832.56 million by 2032, registering a CAGR of 35.8% from 2024 to 2032. This significant growth is driven by the increasing adoption of AI-driven applications across industries, including healthcare, finance, and customer service.
Key market drivers include technological advancements in natural language processing (NLP), growing enterprise demand for AI-powered automation, and rising digital transformation initiatives. Companies are integrating LLMs into various business functions, such as chatbots, content generation, and predictive analytics, to enhance efficiency and reduce operational costs. Additionally, the surge in multilingual AI applications tailored to the German language fosters market growth. Ethical AI adoption and regulatory frameworks are also shaping the industry, ensuring responsible AI deployment while fostering innovation.
Geographically, Germany dominates the European AI landscape, benefiting from a strong technology ecosystem, government initiatives, and AI-focused research institutions. Major cities like Berlin, Munich, and Frankfurt are hubs for AI development, attracting significant investments. Key market players include OpenAI, Google DeepMind, IBM, Microsoft, Aleph Alpha, and Cohere, among others, who are actively innovating and expanding their AI capabilities. Strategic partnerships, mergers, and acquisitions further drive competition, fostering market expansion in Germany
Market Insights
- The Germany Large Language Model Market is projected to grow from USD 306.62 million in 2023 to USD 4,832.56 million by 2032, driven by a CAGR of 35.8%.
- Innovations in natural language processing (NLP) and deep learning are major drivers, improving the accuracy and capabilities of LLMs across various industries.
- Growing enterprise demand for AI-driven automation in sectors like healthcare, finance, and customer service is fueling the widespread adoption of LLMs.
- Compliance with GDPR and ethical AI frameworks is a challenge, as businesses must ensure privacy and transparency in AI deployments.
- The German market sees increased adoption of multilingual LLMs, particularly in regions with diverse linguistic requirements, such as Berlin and Munich.
- Berlin, Munich, and Frankfurt lead the German LLM market, benefiting from a strong AI research ecosystem and substantial investments in AI innovation.
- Demand for domain-specific LLMs in industries like legal, finance, and healthcare is growing, offering more targeted and efficient AI applications.
Market Drivers
Advancements in Natural Language Processing (NLP) and AI Technologies
The rapid evolution of NLP and AI algorithms is pivotal for the growth of the Germany LLM market. Deep learning, transformer models, and neural networks continuously improve, enabling LLMs to achieve higher accuracy in text comprehension, sentiment analysis, and contextual understanding. Transformer architectures, such as OpenAI’s GPT series and Google’s BERT, have significantly enhanced LLMs' ability to generate human-like text, improving performance in content generation, summarization, and translation. The multilingual capabilities of LLMs are crucial in Germany's diverse business environment, supporting German, English, and regional dialects. Self-supervised learning techniques reduce reliance on large labeled datasets, making AI training more scalable and cost-effective. For instance, Germany’s robust research ecosystem, supported by institutions such as the Max Planck Institute for Intelligent Systems and the German Research Center for Artificial Intelligence (DFKI), continually pushes the boundaries of AI innovation, accelerating the sophistication and integration of LLMs into enterprise operations.
Rising Enterprise Adoption and Demand for AI-Powered Automation
Organizations across Germany are actively deploying LLMs to enhance automation, streamline operations, and improve customer interactions, driven by a focus on digital transformation. LLMs are utilized for automated content generation, copywriting, and marketing campaigns to enhance SEO strategies, social media engagement, and personalized email marketing. Companies integrate LLMs into internal workflows for document automation, knowledge management, and data analysis, enhancing decision-making. AI-driven resume screening, interview scheduling, and employee engagement analysis are transforming HR functions. For instance, industries such as retail, finance, and healthcare are leveraging LLMs to develop AI-powered chatbots, virtual assistants, and automated customer support solutions, reducing response times, personalizing interactions, and improving overall customer satisfaction. The increasing availability of AI-as-a-Service (AIaaS) platforms further accelerates the adoption of AI-driven automation.
Strong Government Support and AI-Focused Regulations
The German government plays a vital role in the growth of the LLM market by fostering AI research, digital innovation, and regulatory frameworks. The government is integrating AI-powered solutions into public administration, healthcare, and legal systems, deploying LLMs for automated document processing, legal research, and policy analysis. Compliance with GDPR fosters trust among businesses and consumers, encouraging wider AI adoption. Public and private sector investments support AI startups and research institutions, strengthening Germany’s position as an AI innovation hub. For instance, Germany’s national AI strategy, backed by the Federal Ministry for Economic Affairs and Climate Action (BMWK), aims to position the country as a global AI leader, allocating billions of euros to AI research, startups, and industrial AI applications.
Expanding AI Infrastructure and Cloud-Based AI Solutions
The growing adoption of cloud computing and AI-driven infrastructure facilitates the large-scale deployment of LLMs, providing organizations with on-demand access to powerful computing resources. Companies benefit from local cloud infrastructure that complies with GDPR regulations, ensuring secure and privacy-compliant AI operations. The rise of edge AI enables businesses to run AI models locally on devices, reducing latency and enhancing real-time processing capabilities, particularly beneficial for manufacturing, automotive, and IoT applications. Enterprises are increasingly adopting hybrid AI models, combining cloud-based and on-premises AI solutions to optimize performance, security, and cost-effectiveness. For instance, subscription-based AI services, such as Google Cloud AI, Microsoft Azure AI, and AWS AI, provide cost-effective solutions that enhance accessibility for enterprises of all sizes, enabling them to scale AI applications according to demand.
Market Trends
Increased Enterprise Integration of LLMs for Automation and Decision-Making
Businesses across Germany are progressively weaving large language models into their operational structures to bolster automation, amplify productivity, and refine data-driven decision-making. The capacity of LLMs to process and generate text akin to human language, enriched with contextual understanding, is spearheading their widespread acceptance across varied sectors. For instance, enterprises in banking are deploying AI-powered chatbots to handle customer inquiries and provide transaction assistance in real time. Furthermore, LLMs are enabling automated content generation, streamlining the creation of marketing content and reports. In Business Intelligence, organizations are using LLMs to analyze market trends and consumer behavior, thereby informing business decisions. AI is also transforming Human Resources through resume screening and interview scheduling tools. The growing adoption of AI-as-a-Service platforms simplifies LLM implementation, allowing businesses to leverage AI without heavy infrastructure investments, promising further integration of AI-driven automation across industries.
Expansion of Industry-Specific and Multilingual AI Models
Germany’s diverse economy and multilingual workforce are fueling the demand for industry-specific and multilingual LLMs tailored to precise business requirements. Companies and AI developers are increasingly concentrating on training custom language models to augment industry relevance and overall efficiency. In the healthcare sector, AI-driven medical chatbots and documentation tools support healthcare professionals in tasks like patient diagnosis and medical transcription. Similarly, in the legal field, LLMs are being adapted for legal document analysis and contract summarization. Financial institutions are also leveraging AI for risk assessment and fraud detection, while the manufacturing sector uses AI models to optimize inventory management and logistics. Multilingual AI development is responding to Germany’s global trade partnerships by creating AI models that support German, English, French, and other European languages, enabling seamless communication in diverse linguistic environments.
Advancements in AI Regulation and Ethical AI Development
The regulatory environment in Germany is evolving to ensure the ethical and responsible application of AI. As LLM adoption increases, policymakers and industry leaders are directing their attention towards creating frameworks that promote transparency, fairness, and accountability in AI applications. LLM developers are implementing privacy-centric AI architectures to comply with GDPR's stringent data protection policies. The European Union’s AI Act aims to establish a legal framework for AI development and deployment, with Germany actively influencing these regulations to balance AI innovation and ethical compliance. To ensure unbiased and ethical content, AI researchers in Germany are developing bias mitigation strategies for LLMs. Universities and AI research institutions are also creating auditing tools to monitor AI fairness and prevent algorithmic discrimination. This proactive approach towards AI regulation and ethical development promises to foster responsible AI adoption.
Growth in AI Infrastructure and Cloud-Based LLM Deployment
Germany’s robust technological ecosystem and expanding cloud infrastructure are accelerating the scalability and accessibility of large language models. Companies are increasingly turning to cloud-based AI solutions to efficiently train, deploy, and manage LLMs. Leading cloud providers such as AWS, Microsoft Azure, and Google Cloud are augmenting their AI capabilities in Germany, offering scalable LLM deployment solutions. These businesses benefit from on-demand computing power, eliminating the need for expensive in-house AI infrastructure. Germany’s AI data centers are enhancing high-performance computing capabilities, leading to faster and more efficient LLM training. Furthermore, edge AI adoption is growing, allowing LLMs to operate on local devices and IoT systems, reducing latency and improving real-time decision-making. The expansion of cloud-based AI infrastructure is democratizing LLM adoption, making it more accessible to businesses of all sizes.
Market Challenges
Stringent Data Privacy Regulations and Ethical AI Compliance
Germany’s rigorous data protection laws, notably the General Data Protection Regulation (GDPR), present significant hurdles for organizations developing large language models (LLMs). Compliance with GDPR requires businesses to maintain transparency in user data, obtain informed consent, and implement strong data security protocols when training AI models. Additionally, limited access to high-quality data due to GDPR restrictions hampers AI developers, as they struggle to gather the vast datasets needed for LLM training. While anonymization techniques can mitigate this issue, they often come at the cost of model accuracy and performance. Ensuring AI bias and fairness also remains a major concern, with developers needing to continuously monitor and adjust models to prevent biased or discriminatory outputs. Furthermore, the upcoming European Union AI Act, which is expected to introduce new regulations, could impose additional compliance requirements, increasing operational challenges and costs. To navigate these complexities, companies must invest in privacy-preserving AI techniques, transparent AI governance, and ethical AI development.
High Computational Costs and Scalability Challenges
The development, training, and deployment of large language models require substantial high-performance computing (HPC) infrastructure, presenting significant cost management challenges, particularly for startups and SMEs. Training advanced LLMs requires enormous computational resources, often involving cloud-based GPU clusters or on-premise data centers, which results in high energy consumption and operational expenses. Scalability also presents obstacles, such as latency, response optimization, and real-time processing limitations, all of which necessitate investments in efficient model optimization and cloud-based solutions. Moreover, the environmental concerns related to the carbon footprint of AI model training are prompting companies to seek more energy-efficient AI solutions. To overcome these challenges, businesses must explore AI model optimization, leverage hybrid cloud architectures, and invest in energy-efficient computing technologies, ensuring both cost-effective scalability and sustainability in the German LLM market.
Market Opportunities
Expanding Adoption Across Industry Verticals
As AI-powered automation and data-driven decision-making gain momentum, Large Language Models (LLMs) are increasingly being adopted across diverse industries. In healthcare, LLMs are improving diagnostic accuracy, streamlining clinical documentation, and automating administrative tasks, enhancing both patient care and operational efficiency. The financial services sector benefits from AI-driven fraud detection, risk assessments, and automated trading strategies, providing financial institutions with a competitive edge. In retail and e-commerce, companies use LLMs for personalized customer engagement, dynamic pricing, and AI-powered marketing, leading to enhanced consumer experiences. Legal and compliance teams are leveraging LLMs for contract analysis, legal research automation, and compliance monitoring, reducing the burden of time-consuming manual processes. This broad industry adoption presents significant growth opportunities for AI providers to deliver specialized LLM solutions.
Advancements in AI Infrastructure and Cloud Computing
The increasing availability of high-performance cloud computing and AI-as-a-Service (AIaaS) platforms is making the deployment of LLMs more accessible to businesses. Cloud-based AI solutions allow companies to integrate LLMs without the need for expensive on-premise infrastructure, simplifying the adoption process. Moreover, edge AI and hybrid AI models offer real-time processing capabilities and greater scalability, addressing industries with strict data privacy requirements. In countries like Germany, the strong AI research ecosystem and government-supported digital initiatives are paving the way for businesses to invest in scalable AI infrastructure, driving long-term growth in the LLM market.
Market Segmentation Analysis
By Offerings
The software segment leads the market, with pre-trained large language models (LLMs), AI frameworks, and cloud-based AI platforms at the forefront. Businesses are increasingly investing in tailored AI solutions to address specific industry needs. The services segment, which includes AI consulting, integration, and maintenance, is also experiencing significant growth as companies seek expertise in the deployment and optimization of LLMs. The combination of software and services is driving the adoption of AI solutions across diverse sectors.
By Software Type
The market for software types is divided into general-purpose LLMs and specialized LLMs. General-purpose LLMs, such as OpenAI's GPT and Google’s Gemini, are designed for a wide range of applications, including chatbots and content generation. Domain-specific LLMs are tailored for industries such as healthcare, finance, and legal, offering enhanced accuracy and compliance. Additionally, multilingual LLMs cater to global trade and multilingual business environments, while task-specific LLMs, which focus on functions like coding assistance, document summarization, and legal analysis, are gaining traction in enterprise settings.
Segments
Based on Offerings
- Software
- Services
Based on Software Type
- General-Purpose LLMs
- Domain-Specific LLMs
- Multilingual LLMs
- Task-Specific LLMs
Based on Deployment Type
- On-Premise
- Cloud-Based
Based on Modality Type
- Text-Based LLMs
- Code-Based LLMs
- Image-Based LLMs
- Video-Based LLMs
Based on Application
- Information Retrieval
- Language Translation & Localization
- Content Generation & Curation
- Code Generation
- Others
Based on End-User Industry
- IT & ITES
- Healthcare
- BFSI (Banking, Financial Services, and Insurance)
- Retail & E-Commerce
- Other Industries
Based on Region
- Berlin
- Munich
- Frankfurt
- Hamburg
Regional Analysis
Berlin (28%)
Berlin is a major hub for AI research and innovation, home to several leading AI startups and multinational technology companies. The city benefits from a strong ecosystem of venture capital, research institutions, and a talent pool in data science and machine learning. The region accounts for 28% of the Germany LLM market, driven by the increasing demand for cloud-based AI services, AI research and development, and startups focused on AI applications in healthcare, finance, and e-commerce. Berlin is also a focal point for AI-focused conferences and collaborations between private companies and academic institutions.
Munich (24%)
Munich is another key region contributing significantly to the growth of the Germany LLM market, accounting for 24% of the market share. The city is a well-established center for technology, finance, and automotive industries, all of which are increasingly adopting LLM-driven solutions. Munich’s strong presence of global tech giants like Google, Microsoft, and IBM, as well as major research institutions, makes it a leader in AI adoption. The region is particularly focused on domain-specific LLMs for industries like automotive, finance, and manufacturing, with a growing focus on multilingual AI models for global operations.
Key players
- Neuralfinity Ltd
- Stability AI
- Tencent Holdings Limited
- TextVerstehen GmbH
- Meta Platforms Inc
- Microsoft Corporation
- Amazon Web Services
- NVIDIA
- IBM Corporation
- Oracle Corporation
- Hewlett Packard Enterprise (HPE)
- Google LLC
- Alibaba Group Holding Limited
Competitive Analysis
The Germany Large Language Model (LLM) Market is highly competitive, with major players including global tech giants like Google, Microsoft, Amazon Web Services, and NVIDIA dominating the landscape. These companies have established themselves as leaders in cloud-based AI services and LLM deployment, offering scalable, customizable solutions for a wide range of industries. Additionally, companies like Meta Platforms Inc, IBM, and Oracle provide enterprise-grade AI solutions and have a strong presence in sectors such as finance, healthcare, and automotive. Emerging players like Neuralfinity Ltd, Stability AI, and TextVerstehen GmbH focus on niche LLM solutions tailored to specific applications, including multilingual processing and domain-specific models. These players face stiff competition from larger, resource-rich competitors but have the potential to capture market share by offering specialized, cost-effective products. The market also sees increasing investments in AI research and data privacy compliance as companies align with Germany’s regulatory framework.
Recent Developments
- Founded in 2022 and headquartered in Hamburg, Neuralfinity focuses on building AI models and its Gravity enterprise AI platform. They launched their first-generation LLM in 2021 and ASR in 2022. Neuralfinity is developing an end-to-end platform to automate the training of custom generative AI models and has received EU grants and contracts with European and American customers.
- In January 2025, Stability AI has a market-leading open-source LLM. They introduced the Stable LM 2 series, including a 1.6 billion parameter base model. More recently, Stability AI added a 12 billion parameter base model and an instruction-tuned variant to the Stable LM 2 series.
- In June 2024, ECARX is strengthening its strategic partnership with Tencent to jointly develop a platform to train and operate automotive intelligence LLMs.
- In September 2024, Microsoft plans to invest $3.4 billion in Germany's AI infrastructure to construct new data centers and train workers (February 2024). Microsoft is also facing higher competition scrutiny in Germany, including over its use of AI.
- In June 2024, AWS plans to invest an additional €8.8 billion in its cloud infrastructure in the AWS Europe (Frankfurt) region. A surge in corporate data is driving German organizations to seek support from providers in the AWS ecosystem.
Market Concentration and Characteristics
The Germany Large Language Model (LLM) Market exhibits a moderate to high level of concentration, with a few dominant players like Google, Microsoft, Amazon Web Services, and NVIDIA leading the market due to their substantial investments in cloud computing, AI infrastructure, and research & development. These global tech giants hold significant market share, providing scalable and customizable AI solutions to various industries, including finance, healthcare, and automotive. At the same time, emerging players such as Neuralfinity Ltd, Stability AI, and TextVerstehen GmbH offer specialized LLM applications focused on domain-specific needs and multilingual capabilities, targeting niche markets. The market is characterized by rapid technological advancements, strong competition, and increasing demand for AI-powered automation and natural language processing solutions across sectors. Regulatory factors, such as GDPR compliance, also shape the competitive landscape, encouraging innovation while ensuring ethical AI development.
Report Coverage
The research report offers an in-depth analysis based on Offerings, Software Type, Deployment Type, Modality Type, Application, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for LLMs across various industries, including finance, healthcare, and e-commerce, is expected to increase as organizations seek enhanced automation and data-driven insights.
- Industry-specific LLMs tailored to sectors like legal, finance, and healthcare will gain traction, offering more accurate and efficient AI solutions for specialized tasks.
- With Germany’s diverse multilingual environment, multilingual LLMs will see higher adoption to support global business operations and facilitate seamless communication.
- The demand for cloud-based LLM solutions will grow as businesses seek scalable, cost-effective AI models without the need for large on-premise infrastructure.
- LLMs will increasingly integrate with enterprise software, driving process automation in customer service, content creation, and data analysis for improved operational efficiency.
- Stricter regulatory frameworks like the European Union’s AI Act will shape the development and deployment of LLMs, emphasizing ethics, fairness, and data privacy in AI solutions.
- Advances in model training techniques, including transfer learning and fine-tuning, will improve LLM performance, reducing costs and increasing deployment efficiency.
- The German government and private investors will continue funding AI research and development, enabling the creation of more advanced LLM technologies and driving market growth.
- Edge AI will become more prevalent, allowing LLMs to perform real-time processing on local devices, reducing latency and enhancing performance for industries like automotive and manufacturing.
- Partnerships between tech companies and academic institutions will foster innovation in LLMs, ensuring continuous improvements and cutting-edge advancements in AI research and application.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Germany Large Language Model Market in 2023 and 2032?
What factors are driving the growth of the Germany Large Language Model Market?
How does the regulatory environment impact the Germany Large Language Model Market?
Which cities in Germany are key hubs for AI development?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Large Language Model Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Large Language Model Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 306.62 million → 2032: USD 4,832.56 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Large Language Model Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Large Language Model Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Large Language Model Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Large Language Model Market Drivers
- 3.3 Germany Large Language Model Market Restraints & Challenges
- 3.4 Germany Large Language Model Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Large Language Model Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Large Language Model Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Large Language Model category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Large Language Model Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Large Language Model Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Large Language Model market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Large Language Model Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Large Language Model Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Large Language Model Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Large Language Model (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Large Language Model Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Large Language Model Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Large Language Model Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Large Language Model Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Large Language Model Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Large Language Model Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Large Language Model Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Large Language Model Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Large Language Model Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
